
 Caustic Calcined Magnesite Market | 2026-2036
Caustic Calcined Magnesite Market Size, Share, and Industry Trends Forecast 2026-2036
Caustic Calcined Magnesite Market Outlook
The split between premium high-purity grades and commodity caustic calcined magnesite is repositioning competitive boundaries in the market. RHI Magnesita leverages captive magnesite reserves in Europe to sustain refractory-grade supply chains. Haicheng Magnesite Group anchors Chinese domestic production with integrated mining-to-calcination operations. Nedmag differentiates through synthetic magnesite chemistry tailored to water treatment and agricultural applications.
Caustic calcined magnesite refers to magnesium oxide produced by calcining raw magnesite at temperatures between 700°C and 1000°C, yielding a reactive, lightly burned product with high surface area and superior chemical reactivity compared to deadburned alternatives. Its primary purpose centers on industrial applications requiring controlled reactivity, including steel slag conditioning, environmental remediation, and chemical processing feedstock. The steelmaking end-use industry commands the largest volume share, though water treatment applications are gaining traction as municipalities tighten discharge standards. Powder form dominates current shipments, while granules are capturing interest in automated agricultural spreading systems where dust control matters.
EPA effluent guidelines in the United States and China's MEE emission standards are elevating purity requirements for magnesite products used in environmental applications. REACH registration obligations in Europe restrict market access for unregistered imports, favoring established suppliers with compliance infrastructure. Stakeholders must track evolving regulatory thresholds for heavy metal content and carbon intensity metrics, as these parameters increasingly determine contract eligibility with industrial buyers.
Market Dynamics
Steelmakers in China and India are tightening specifications for slag conditioning agents, forcing caustic calcined magnesite suppliers to upgrade calcination controls and heavy metal testing protocols to retain contract eligibility with integrated mills.
Growth Catalysts
- REACH Registration:ECHA compliance requirements in Europe are filtering out unregistered imports, consolidating demand around established suppliers with dossier infrastructure.
- Steel Slag Conditioning:Electric arc furnace operators in Karnataka State and Liaoning Province are expanding high-grade magnesite consumption to meet sulfur and phosphorus removal targets.
- MEE Emission Standards:China's tightened discharge rules for heavy metals are redirecting water treatment procurement toward certified high-purity grades.
Market Restraints
- Raw Magnesite Volatility:Mining license restrictions in Liaoning Province are constraining feedstock availability and amplifying input cost swings for calciners without captive reserves.
- Substitution Pressure:Synthetic magnesium oxide from seawater and brine sources is capturing share in desulfurization applications where reactivity specifications permit.
- Energy Cost Exposure:Natural gas and coal price spikes are compressing margins for rotary kiln operators in Europe and China.
Strategic Opportunities
- Automated Agricultural Spreading:Granule-form magnesite is penetrating precision farming systems in Brazil and Australia where dust suppression and flowability command premiums.
- EPA Effluent Guidelines:Updated US discharge standards for municipal wastewater are expanding addressable demand for heavy metal precipitation applications.
- Synthetic-Mineral Blends:Hybrid formulations combining caustic calcined magnesite with dolomitic lime are opening specification windows in flue gas treatment.
Industry Challenges
- Calcination Expertise Gap:Shortage of process engineers capable of optimizing 700-1000°C temperature profiles is constraining capacity expansion at mid-tier producers.
- REACH Dossier Maintenance:Extended substance evaluation timelines and data cost obligations are draining compliance resources for smaller EU-registered suppliers.
- Legacy Equipment Retrofit:Aging shaft kiln installations face prohibitive capital requirements to meet MEE particulate emission limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caustic Calcined Magnesite Market |
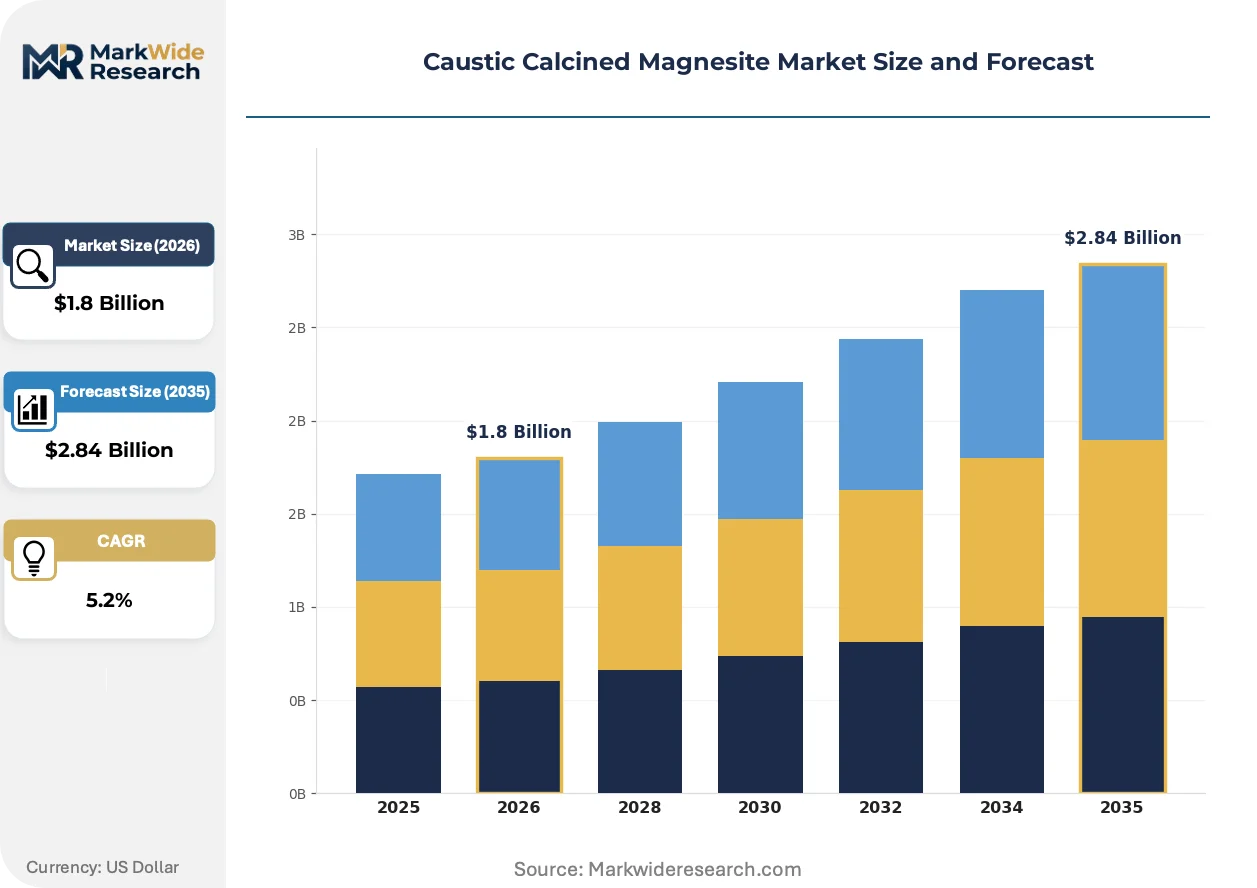
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadburned Magnesite, Lightburned Magnesite, Caustic Calcined Magnesite, Other End Use Industry: Steelmaking, Agriculture, Construction, Refractories Form: Powder, Granules, Anhydrous, Slurry Application: Textiles, Ceramics, Glass, Water Treatment |
| Companies Covered | RHI Magnesita, Nedmag, Haicheng Magnesite Group Co., Ltd., Erzkontor Group, Sibelco, Magnezit Group, Martin Marietta Magnesia Specialties, TERNA MAG, Grecian Magnesite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caustic Calcined Magnesite Market Strategic Shifts
Calcination technology and regulatory chemistry are converging to redefine product differentiation, with reactivity control and carbon intensity emerging as the primary axes of supplier competition.
Flash calcination systems with precise temperature zoning are absorbing market share from conventional rotary kilns in premium-grade production. Specialty refractory manufacturers in Germany and Japan are adopting these units to achieve tighter surface area specifications. The technology is absorbing capital allocation that previously targeted capacity expansion, compressing effective supply growth for standard grades.
REACH authorization requirements for nickel and chromium content are tightening specification windows for environmental applications. ECHA substance evaluation is forcing reformulation of legacy magnesite sources with elevated heavy metal backgrounds. Water treatment procurement in the Netherlands and Belgium is responding by mandating third-party certified purity documentation.
Integrated steel mills are consolidating supplier panels and extending quality audits to upstream mining operations. Procurement teams at Baosteel and Tata Steel are replacing spot purchasing with multi-year framework agreements tied to consistent reactivity metrics. This concentration is most visible in East Asian refractory clusters, where three-supplier policies are displacing fragmented sourcing.
Caustic Calcined Magnesite Market Segmentation
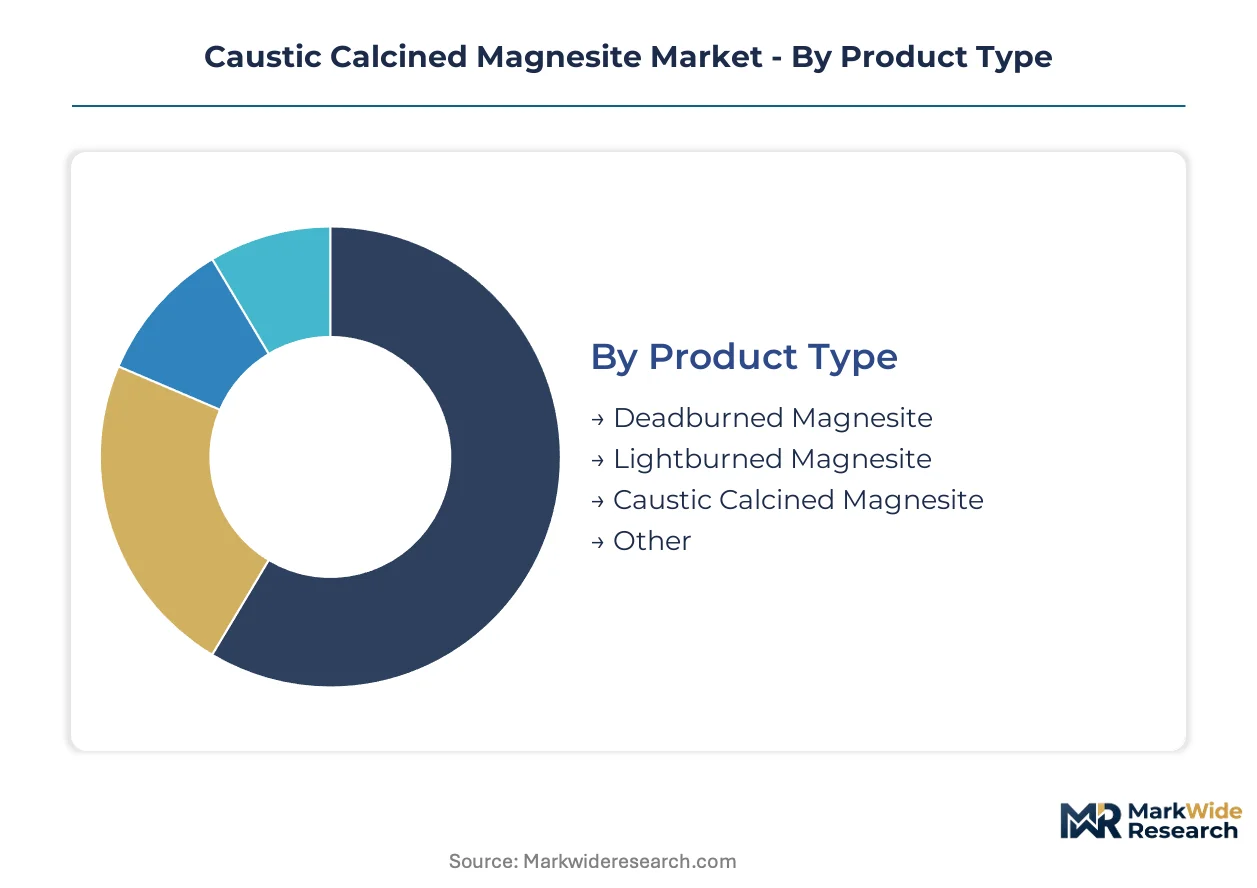
Caustic calcined magnesite suppliers configure production lines around thermal profile control and particle morphology, with each segment demanding distinct calcination temperatures and downstream processing investments. Specification divergence between steelmaking slag conditioners and agricultural soil amendments forces parallel equipment trains at integrated operations.
Product Type:
Customization intensity varies sharply across thermal processing tiers, with captive mining operations favoring integrated multi-product kilns while merchant calciners specialize in single-grade output.
- Deadburned Magnesite:Sintered at temperatures exceeding 1500°C to achieve crystalline periclase structures with minimal reactivity. Liaoning Province shaft kilns supply refractory brick manufacturers in Hebei and Shanxi provinces facing GB standard purity mandates.
- Lightburned Magnesite:Calcined at 700-1000°C yielding high surface area and superior chemical reactivity for slag conditioning and environmental applications. Karnataka State EAF operators specify this grade for sulfur removal protocols.
- Caustic Calcined Magnesite:The core analytical focus of this study, positioned between lightburned and deadburned variants for controlled reactivity applications.
- Other:Fused magnesia and electrofused variants serving specialty electrical insulation and high-temperature ceramic applications.
Most installed capacity flows through Deadburned Magnesite. Expansion is steepest in Lightburned Magnesite.
End Use Industry:
Volume concentration tracks regional industrial specialization, with steelmaking clusters in East Asia absorbing the majority of high-grade output while agricultural demand fragments across dispersed farming regions.
- Steelmaking:Slag conditioning in electric arc and basic oxygen furnaces requires consistent reactivity metrics for sulfur and phosphorus control. Baosteel and Tata Steel procurement teams audit upstream mining operations for heavy metal compliance.
- Agriculture:Magnesium deficiency correction in oil palm plantations and soybean fields drives granule-form demand. Brazil's Mato Grosso precision spreading systems specify dust-suppressed formulations.
- Construction:Magnesium oxychloride cement and flooring applications consume standard-grade powder in urban building clusters.
- Refractories:Monolithic lining materials for steel ladles and cement kilns require deadburned variants with controlled grain sizing.
Steelmaking commands the dominant volume position. Agriculture is climbing the fastest as automated spreading technology penetrates South American and Australian farming systems.
Form:
Physical morphology determines handling economics and application precision, with powder maintaining cost advantage in industrial settings while granules capture premiums in mechanized agriculture.
- Powder:Dominates current shipments for steel slag conditioning and chemical processing feedstock. Rotary kiln operators in Liaoning Province optimize for surface area specifications in the 20-40 m²/g range.
- Granules:Engineered for flowability and dust suppression in precision farming equipment. Australian broadacre operations specify 2-4mm granules for aerial and ground-based spreading systems.
- Anhydrous:Low-moisture variants for moisture-sensitive chemical synthesis and specialty refractory binders.
- Slurry:Pre-dispersed aqueous suspensions for continuous water treatment dosing systems.
Powder form retains the largest installed processing capacity. Granules are gaining share fastest in agricultural channels.
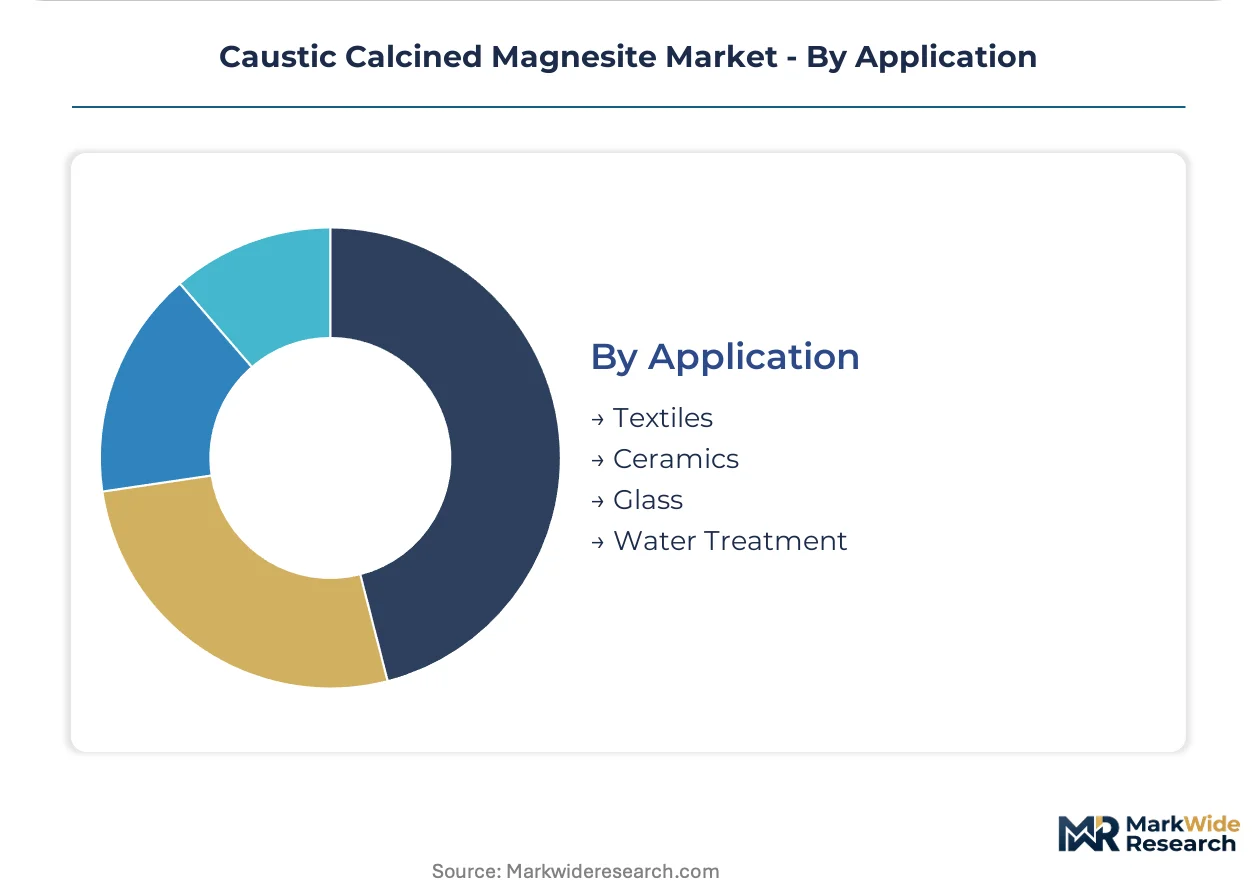
Application:
Purity thresholds and certification requirements fragment demand across industrial sectors, with environmental applications tightening heavy metal specifications fastest.
- Textiles:Magnesium hydroxide formation for flame-retardant fiber treatments. Synthetic fiber producers in Zhejiang Province specify low-iron grades.
- Ceramics:Body and glaze formulations requiring controlled thermal expansion. Japanese sanitaryware manufacturers source from ECHA-registered suppliers.
- Glass:Fining agent and refractory lining applications in container and flat glass production.
- Water Treatment:Heavy metal precipitation and pH adjustment in municipal and industrial effluent systems. EPA effluent guidelines and China's MEE standards are elevating purity requirements fastest.
Water Treatment is expanding most quickly as discharge standards tighten across multiple jurisdictions. Textiles retains substantial volume through established supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled calcination engineers cluster around legacy mining districts in China, Austria, and Greece, anchoring technical expertise to ore body geography rather than downstream demand centers.
China
Steelmakers in Liaoning Province consume high-grade caustic calcined magnesite for electric arc furnace slag conditioning, with procurement teams at Baosteel mandating consistent reactivity metrics. MEE emission standards for heavy metal discharge redirect water treatment procurement toward certified high-purity grades. Haicheng city hosts integrated mining-to-calcination operations supplying domestic refractory clusters.
India
Karnataka State electric arc furnace operators expand magnesite consumption to meet sulfur and phosphorus removal targets in specialty steel production. BIS certification requirements for industrial minerals filter unregistered imports, consolidating demand around established suppliers with testing infrastructure. Bellary-Hospet steel corridor procurement teams audit upstream mining operations for heavy metal compliance.
Germany
Specialty refractory manufacturers in the Rhineland adopt flash calcination systems with precise temperature zoning to achieve tighter surface area specifications. REACH authorization requirements for nickel and chromium content tighten specification windows for environmental applications. ECHA-registered suppliers in North Rhine-Westphalia reformulate legacy magnesite sources with elevated heavy metal backgrounds.
United States
Municipal water treatment facilities respond to EPA effluent guidelines by expanding heavy metal precipitation applications using certified high-purity grades. Updated discharge standards for municipal wastewater elevate purity requirements fastest in the Great Lakes region. Michigan and Ohio industrial clusters redirect procurement toward third-party certified documentation.
Greece
European water treatment procurement in the Netherlands and Belgium mandates third-party certified purity documentation, favoring ECHA-registered Mediterranean suppliers. REACH dossier maintenance obligations drain compliance resources, filtering market access for smaller registered operations. Kozani region mining concessions anchor production for environmental remediation feedstock.
Caustic Calcined Magnesite Market Competitive Environment
Capital-heavy producers with captive magnesite reserves compete with merchant calciners dependent on spot feedstock markets, creating divergent margin structures across the supply base. The vendor base stratifies around thermal processing sophistication, with integrated mining operations favoring multi-product kilns while specialized calciners concentrate on single-grade output. Three archetypes dominate: integrated miners with backward control over ore supply, synthetic magnesite chemists leveraging brine chemistry, and regional merchant calciners serving spot industrial demand. Competitive moves center on calcination technology licensing for reactivity control and multi-year framework agreements replacing fragmented spot purchasing.
Among integrated mining specialists, RHI Magnesita and Haicheng Magnesite Group occupy positions exemplifying the captive reserve archetype, while Nedmag represents the synthetic chemistry vector with seawater-derived production systems. These three anchors illustrate the strategic divergence between mineral extraction and chemical synthesis pathways.
| Leading Market Players |
|---|
| RHI Magnesita |
| Nedmag |
| Haicheng Magnesite Group Co., Ltd. |
| Erzkontor Group |
| Sibelco |
| Magnezit Group |
| Martin Marietta Magnesia Specialties |
| TERNA MAG |
| Grecian Magnesite |
| Others |
Value Chain & Pricing Dynamics
Liaoning Province magnesite ore spot indices cascade through calcination tolling contracts into three distinct pricing tiers: REACH-registered premium grades for European environmental applications, certified industrial grades for East Asian steelmakers, and unregistered commodity grades facing margin compression from synthetic magnesium oxide substitutes.
Pricing Analysis
Unbundled calcination services separate from captive mining operations command 15-25% premiums over integrated producer pricing, with quality grade and REACH certification level driving the steepest differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies around heavy metal testing protocols and reactivity surface area specifications. Cost compression in commodity-grade powder runs through energy-intensive rotary kiln operators exposed to natural gas price spikes. Spot buyers at merchant calciners exhibit highest price sensitivity, while framework agreement holders at integrated steel mills absorb modest increases for supply security.
Supply Chain Analysis
REACH dossier completion and MEE emission compliance certification gate market access for environmental-grade shipments, filtering unregistered imports from smaller calciners. Supply concentrates in China, Greece, and Austria, with raw magnesite feedstock, natural gas for kiln fuel, and skilled process engineers anchoring production economics. Single-source vulnerability concentrates in Liaoning Province mining concessions facing license renewal uncertainty. Distribution runs through refractory cluster distributors in Hebei and Shanxi provinces, direct mill contracts for steelmaking grades, and agricultural input dealers for granule-form products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between European REACH compliance costs and Chinese production scale, with carbon intensity differentials widening effective cost spreads for low-carbon synthetic magnesite alternatives.
For Market Incumbents: Extend framework agreement coverage to upstream mining audits, locking in heavy metal traceability before BIS and MEE tighten certification windows. Deepen backward integration into captive magnesite reserves in Liaoning and Kozani regions to offset feedstock volatility from license restrictions. Prioritize flash calcination technology licensing for premium-grade reactivity control as synthetic magnesium oxide encroaches on desulfurization applications. For New Entrants and Emerging Players: Launch via tolling partnerships with underutilized rotary kiln capacity in Karnataka State, avoiding capital-heavy greenfield construction. Target automated agricultural spreading systems in Brazil's Mato Grosso and Australian broadacre operations where dust-suppressed granules command 20-30% premiums over powder. Penetrate water treatment procurement in US Great Lakes municipalities responding to EPA effluent guideline updates with certified high-purity grades. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic magnesite chemists leveraging brine chemistry for carbon-negative production pathways, particularly those with seawater extraction assets in coastal Europe. Five-to-ten-year viability favors integrated miners with captive reserves and REACH dossier infrastructure over merchant calciners exposed to spot feedstock markets. Watch for MEE emission standard enforcement consistency as inflection indicator for Chinese supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Secures feedstock traceability for Baosteel and Tata Steel procurement audits. |
| Flash Calcination Technology Licensing | Enables German and Japanese specialty refractory manufacturers to achieve tighter surface area specifications. |
| REACH Dossier Maintenance Investment | Preserves ECHA-registered supplier status as substance evaluation timelines extend. |
| Long-term Supply Agreement with Steel Mills | Replaces fragmented spot purchasing with multi-year frameworks tied to reactivity metrics. |
| Joint Venture for Synthetic-Mineral Blends | Opens specification windows in flue gas treatment combining caustic calcined magnesite with dolomitic lime. |
Study Parameters
Multiple input streams — primary interviews with plant managers at Liaoning and Karnataka calcination facilities, procurement leads at integrated steel mills, distribution channel partners in refractory clusters, and technical R&D directors at specialty refractory manufacturers — were reconciled against secondary validation from customs and trade data, SEC 10-K filings of listed refractory producers, ECHA registration dossiers, and MEE emission standard disclosures. Bottom-up capacity and utilization estimates triangulated with top-down demand modeling across steelmaking, agriculture, and water treatment end-uses.
Historical production and trade flows cross-referenced against panel input from industry participants informed analytical framework development across the analysis window. Segmentation dimensions modeled include thermal processing tier, end-use industry concentration, physical form morphology, and regional regulatory cluster stringency. CAGRs derived from regression analysis of installed capacity expansion, demand elasticity to steel production cycles, and substitution dynamics from synthetic magnesium oxide alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement intensity variations and Liaoning mining license renewal disruptions. Model outputs reflect assumptions on reactivity specification stability, energy cost pass-through mechanisms, and REACH authorization timeline consistency. A model refresh is warranted upon material change in Chinese environmental regulator enforcement posture or breakthroughs in seawater-derived synthetic magnesite cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Snowflake Salt Market