
 Luxury Yacht Market | 2026-2036
Luxury Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Yacht Market Intelligence
The luxury yacht end-use vertical is broadening as charter companies expand fleet commitments alongside traditional private ownership. Ferretti Group leverages its Italian manufacturing heritage to anchor premium motor yacht production across European and Middle Eastern markets. Azimut Benetti competes through integrated design-to-delivery capabilities that span multiple size categories. Sunseeker International specializes in performance-oriented craft that dominate the British and Caribbean charter circuits.
A luxury yacht denotes a privately owned, professionally crewed vessel exceeding 24 meters in length, constructed from advanced composites or steel-aluminum alloys with custom naval architecture, and designed for extended ocean cruising with residential-grade interiors and stabilized platform systems. Motor yachts occupy the dominant revenue position due to higher customization margins and shorter build cycles, while superyachts concentrate the deepest profit pools despite elongated delivery timelines. Sailing yachts retain niche demand among purist owners seeking reduced environmental footprints through wind-assisted propulsion.
The International Maritime Organization enforces MARPOL Annex VI emission standards that constrain engine specifications and fuel sulfur content for vessels operating in controlled zones. The EU Green Deal extends these pressures through the F-Gas Regulation and forthcoming carbon border adjustments affecting hull fabrication and outfitting supply chains. Stakeholders must monitor regulatory divergence between European environmental mandates and Middle Eastern operational flexibility as order books stretch across jurisdictions with divergent compliance timelines.
Market Dynamics
The International Maritime Organization's MARPOL Annex VI emission standards are compressing engine specifications and fuel sulfur limits, forcing shipyards toward hybrid-electric architectures and alternative propulsion systems across all size categories.
Growth Catalysts
- EU Green Deal decarbonization mandates:The F-Gas Regulation and impending carbon border adjustments accelerate demand for hydrogen fuel cells and battery-electric propulsion in Mediterranean and Middle Eastern order books.
- Experiential maritime tourism expansion:Ultra-high-net-worth individuals are prioritizing extended charter durations over outright ownership, expanding fleet utilization rates for multi-week itineraries.
- Advanced composite fabrication:Carbon fiber infusion and resin transfer molding reduce hull weight by substantial margins, extending range and improving fuel efficiency for transoceanic cruising.
Market Restraints
- Specialized marine-grade steel and aluminum supply:Hull fabrication depends on European and Japanese metallurgical suppliers with extended lead times and quota-based allocation systems.
- IMO Tier III compliance costs:Selective catalytic reduction systems and exhaust gas recirculation add seven-figure outfitting premiums for vessels above 500 gross tons.
- Superyacht delivery timeline elongation:Custom naval architecture and interior fit-out cycles now span 36-48 months, freezing capital and compressing shipyard cash conversion.
Strategic Opportunities
- Saudi Arabia's Red Sea tourism corridor:The Kingdom's giga-project developments are creating dedicated marina infrastructure with preferential berthing for charter operators establishing regional hubs.
- Wind-assisted propulsion hybridization:Rigid sail systems and kite propulsion are converging with diesel-electric architectures to reduce fuel consumption on transatlantic routes.
- Fractional ownership platforms:Digital marketplaces for yacht syndication are opening vessel access to sub-ultra-high-net-worth segments previously excluded from the category.
Industry Challenges
- Naval architect and marine engineer scarcity:Specialized talent for computational fluid dynamics and stabilization system design commands premium compensation and extended recruitment cycles.
- Classification society certification bottlenecks:Lloyd's Register and Bureau Veritas inspection backlogs delay commercial registration and charter licensing by 4-6 months.
- Legacy engine retrofit complexity:Existing diesel propulsion installations face technical incompatibility with hydrogen or ammonia conversion pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Yacht Market |
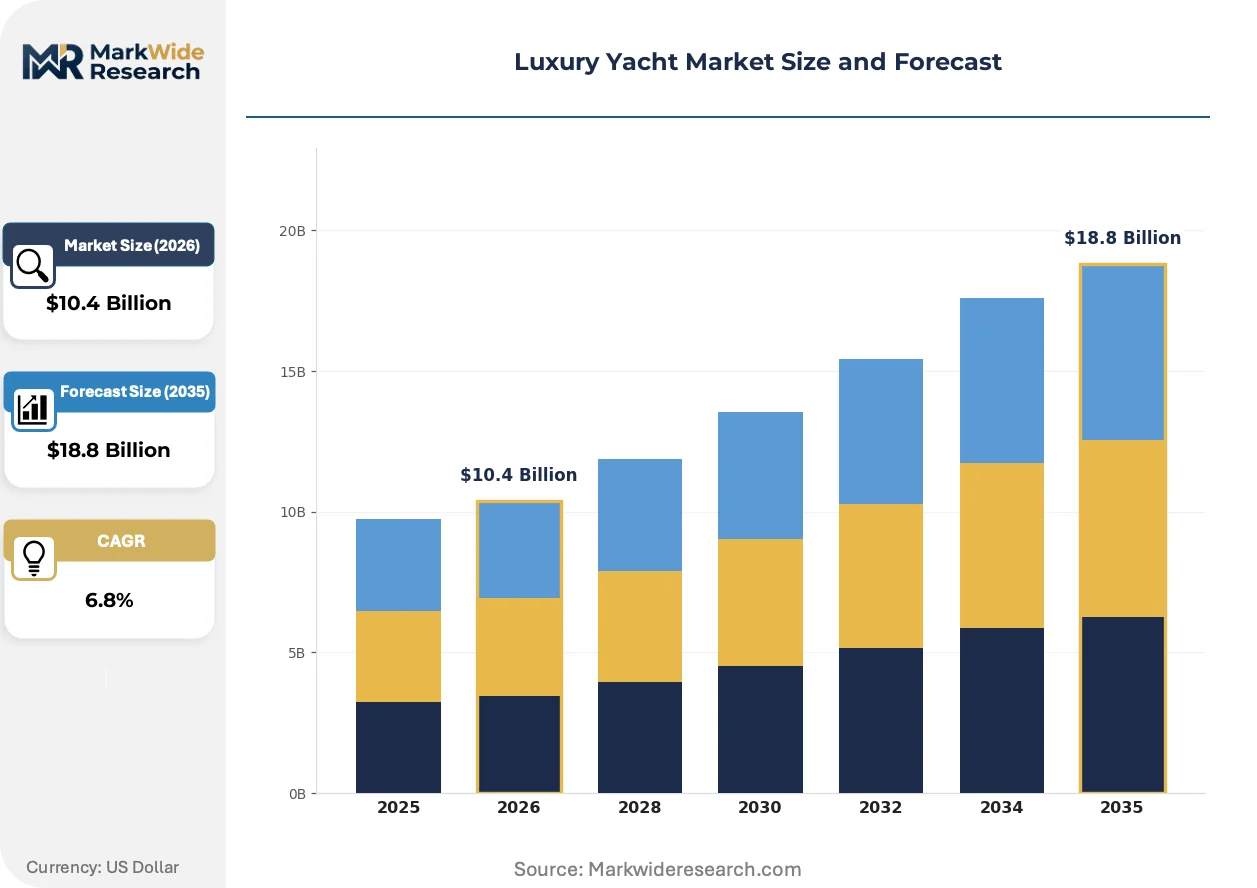
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Yachts, Sailing Yachts, Catamarans, Superyachts End User: Private Owners, Charter Companies, Corporate Clients, Government Agencies Size: Small Yachts, Medium Yachts, Large Yachts, Mega Yachts Technology: AIS, Navigation Systems, Engine Type, Automation |
| Companies Covered | Azimut Benetti, Ferretti Group, Lürssen, Feadship, Sanlorenzo, Sunseeker International, Princess Yachts, Heesen Yachts, Oceanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Yacht Market Strategic Shifts & Innovations
Hybrid propulsion architectures and shore-power connectivity are reconfiguring vessel design priorities, while digital twin technology compresses sea-trial protocols and predictive maintenance cycles.
Hybrid-electric propulsion systems are integrating lithium-ion battery banks with variable-speed diesel generators to enable silent anchoring and port maneuvering. Charter operators in the French Riviera and Italian Adriatic are specifying these configurations for 40-60 meter vessels to meet marina noise restrictions. This integration is compressing the competitive gap between conventional diesel and full-electric alternatives in the 500-1500 gross ton segment.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in HVAC and galley systems, compelling shipyards to specify CO2-based cooling circuits and natural refrigerant alternatives. Hull outfitters in Italian and Dutch construction centers are retooling supplier relationships to secure compliant component streams. Superyacht segments above 3000 gross tons face the steepest compliance premiums, with owners absorbing retrofit costs during refit cycles.
Charter brokerage platforms are disintermediating traditional yacht management companies by directly connecting vessel owners with verified guests through digital verification and escrow systems. The British Virgin Islands and Bahamas circuits show the highest platform penetration, with weekly booking windows compressing from 90-day advance commitments to 14-day horizons. This behavioral shift is fragmenting demand across smaller operators and diluting fleet concentration among established management houses.
Luxury Yacht Market Segmentation
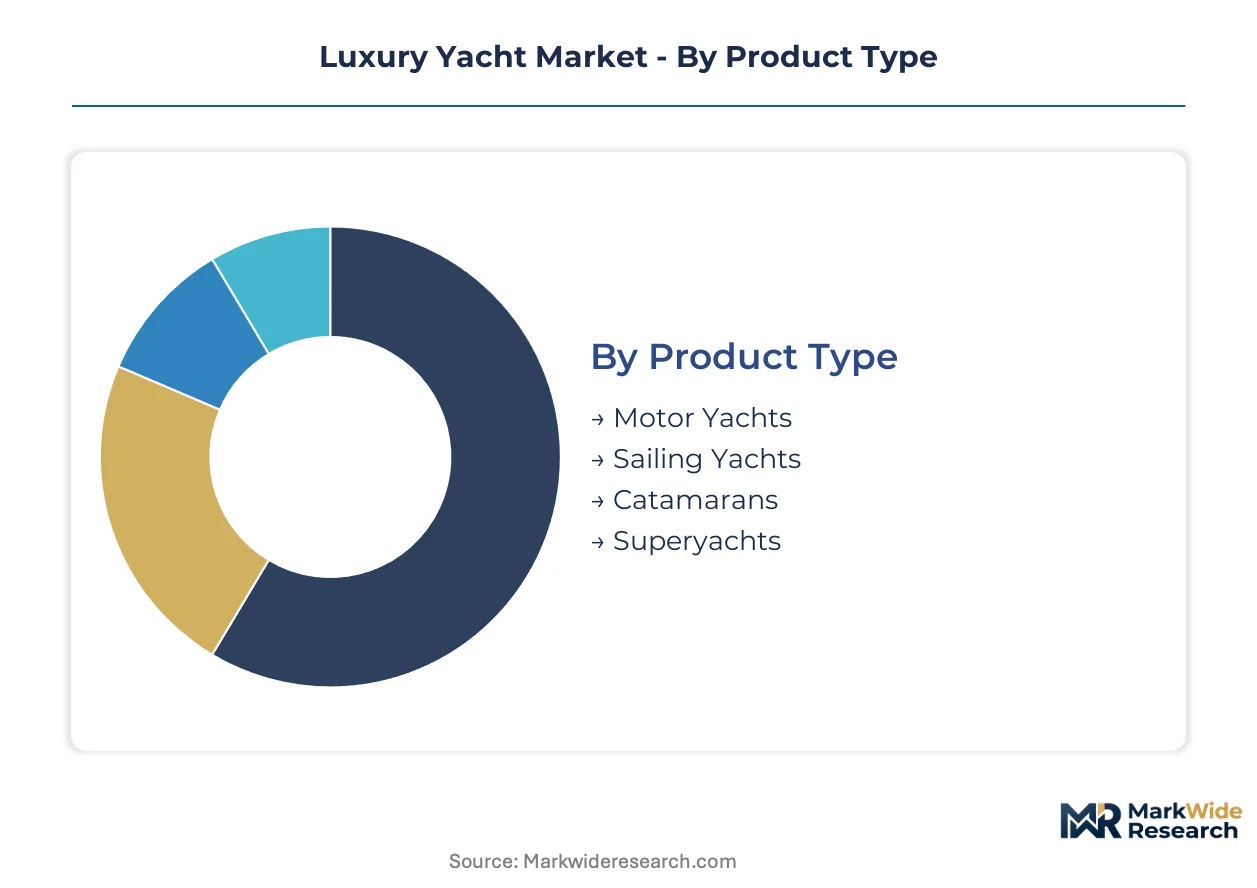
Segmentation in luxury yacht markets reveals how procurement patterns diverge between private ownership and commercial charter deployment. Each dimension—product configuration, end-use application, vessel scale, and onboard systems—carries distinct margin profiles and regulatory exposure that reshape competitive positioning across Mediterranean and Middle Eastern order books.
Product Type:
Upgrade cycles vary dramatically across hull architectures, with composite-intensive designs demanding shorter replacement timelines than steel-hulled alternatives.
- Motor Yachts:Diesel-electric and hybrid propulsion configurations dominate this category, with lithium-ion battery integration enabling silent anchoring in noise-restricted marinas. Italian shipyards along the Adriatic coast concentrate premium production for French Riviera charter circuits where guests prioritize rapid transit between ports.
- Superyachts:Custom naval architecture exceeding 60 meters commands elongated build cycles of 36-48 months, freezing substantial capital while owners absorb EU Green Deal compliance premiums for F-Gas Regulation HVAC retrofits. Saudi Arabia's Red Sea tourism corridor is absorbing new deliveries for extended multi-week itineraries.
- Sailing Yachts:Wind-assisted propulsion retains niche demand among purist owners seeking reduced environmental footprints through rigid sail and kite systems.
- Catamarans:Twin-hull stability and shallow draft access expand charter viability in Caribbean and Southeast Asian archipelagos where monohull depth constraints limit anchorage options.
Motor Yachts sits at the top of the volume ranking, with Superyachts climbing the fastest as Saudi giga-projects absorb custom builds.
End User:
Customer type determines financing structures and utilization patterns, with fractional ownership platforms fragmenting demand across previously excluded capital tiers.
- Charter Companies:Fleet operators in the British Virgin Islands and Bahamas are compressing booking windows from 90-day to 14-day horizons through digital brokerage platforms that disintermediate traditional management houses. Weekly utilization targets above 20 weeks annually drive specifications prioritizing durability over bespoke finishes.
- Private Owners:Ultra-high-net-worth individuals are shifting toward extended charter commitments rather than outright acquisition, reducing capital deployment while maintaining access to residential-grade interiors and stabilized platform systems.
- Corporate Clients:Hospitality and entertainment sectors deploy vessels for client entertainment and executive retreat programming with depreciation schedules aligned to tax jurisdictions.
- Government Agencies:Coast guard, customs, and marine research functions acquire modified hulls with surveillance and interdiction capabilities.
Charter Companies anchor current volume, while fractional ownership platforms are expanding fastest among sub-ultra-high-net-worth segments.
Size:
Hull length classification determines crew requirements, regulatory jurisdiction, and marina berthing eligibility across Mediterranean and Caribbean circuits.
- Large Yachts:Vessels spanning 40-60 meters occupy the sweet spot for hybrid-electric specification, with Italian and Dutch shipyards integrating shore-power connectivity and battery banks for silent port maneuvering. EU Green Deal mandates concentrate compliance costs in this bracket before superyacht scale economies absorb premiums.
- Mega Yachts:Exceeding 80 meters, these hulls trigger IMO Tier III selective catalytic reduction requirements and Lloyd's Register certification bottlenecks that delay commercial registration by 4-6 months.
- Small Yachts:Sub-30-meter vessels dominate Caribbean day-charter and weekend markets with reduced crew overhead and faster build cycles.
- Medium Yachts:The 30-40 meter transitional category captures owners upgrading from entry-level ownership toward extended ocean cruising capability.
Large Yachts command the steepest expansion trajectory as hybrid propulsion economics converge with charter fleet renewal cycles.
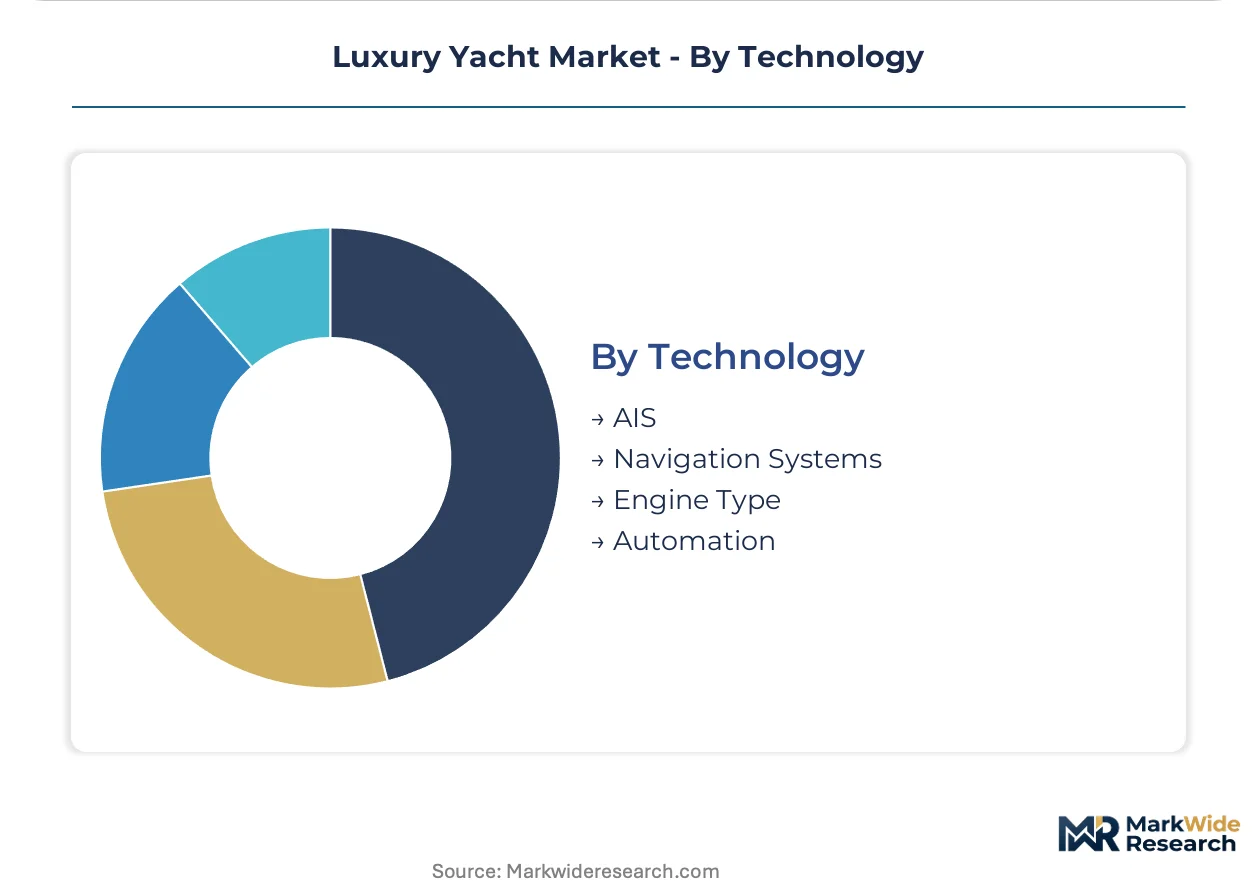
Technology:
Onboard system specification is concentrating procurement decisions around decarbonization compliance and digital operational efficiency.
- Engine Type:Hybrid-electric architectures with variable-speed diesel generators are displacing conventional mechanical propulsion in 500-1500 gross ton segments. Hydrogen fuel cell and ammonia conversion pathways face technical incompatibility with legacy installations.
- Navigation Systems:Digital twin technology compresses sea-trial protocols and enables predictive maintenance cycles that reduce dry-dock downtime for commercial operators.
- AIS:Automatic identification systems satisfy IMO collision avoidance mandates while enabling fleet tracking for charter management platforms.
- Automation:Integrated bridge and hotel load management reduce crew complements and operational expenditure for owner-operators.
Engine Type drives the most rapid specification change as shipyards retool for alternative fuel pathways under tightening emission standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyards are relocating fabrication capacity toward jurisdictions with extended compliance timelines, exploiting gaps between EU Green Deal mandates and Middle Eastern operational flexibility. This regulatory arbitrage redirects investment flows as order books stretch across divergent environmental enforcement regimes.
Italy
French Riviera charter demand and Adriatic marina expansion anchor hull production across Ligurian and Tuscan shipyard clusters. The EU Green Deal's F-Gas Regulation imposes HVAC refrigerant phase-downs that compress outfitting margins for vessels above 3000 gross tons. Ferretti Group and Azimut Benetti concentrate premium motor yacht fabrication in Viareggio and Savona, integrating shore-power connectivity for Mediterranean noise-restricted ports.
Netherlands
Custom superyacht architecture exceeding 60 meters concentrates in Amsterdam and Vlissingen fabrication centers serving Middle Eastern sovereign buyers. Bureau Veritas certification bottlenecks delay commercial registration by 4-6 months for IMO Tier III selective catalytic retrofits. Royal Van Lent and Oceanco occupy the Feadship cooperative structure, anchoring steel-aluminum hull construction for extended ocean cruising specifications.
United Kingdom
Performance-oriented craft for Caribbean charter circuits dominate Poole and Plymouth manufacturing footprints. Lloyd's Register inspection backlogs compress delivery schedules for hybrid-electric propulsion integrations. Sunseeker International and Princess Yachts specialize in 40-60 meter vessels with lithium-ion battery banks enabling silent port maneuvering in British Virgin Islands itineraries.
Germany
Refit and conversion services for legacy diesel installations cluster in Hamburg and Bremen industrial zones facing hydrogen fuel cell technical incompatibility. The country's national maritime regulator enforces MARPOL Annex VI emission standards that constrain engine specifications for vessels operating in North Sea controlled zones. Lürssen anchors custom naval architecture above 80 meters with elongated 36-48 month build cycles freezing substantial capital deployment.
Saudi Arabia
The Kingdom's Red Sea tourism corridor giga-projects are creating dedicated marina infrastructure with preferential berthing for charter operators establishing regional hubs. Domestic operational flexibility extends compliance timelines for alternative fuel conversion pathways compared to European enforcement regimes. Jeddah and NEOM fabrication partnerships are absorbing Italian and Dutch superyacht deliveries for extended multi-week itineraries targeting ultra-high-net-worth tourism segments.
Luxury Yacht Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated design-to-delivery capabilities concentrating premium motor yacht production while custom naval architecture fragments above 60 meters. The market structures around three tiers: heritage Italian houses leveraging Mediterranean manufacturing identity, British performance specialists dominating Caribbean charter circuits, and Dutch-German cooperatives anchoring steel-hulled superyacht fabrication. Competitive moves concentrate on hybrid propulsion R&D partnerships and Saudi marina infrastructure joint ventures.
Among Italian heritage fabricators, Azimut Benetti and Ferretti Group exemplify integrated design-to-delivery capabilities spanning multiple size categories. Sunseeker International occupies the performance-oriented specialist tier. These three named entities anchor competitive positioning without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Azimut Benetti |
| Ferretti Group |
| Lürssen |
| Feadship |
| Sanlorenzo |
| Sunseeker International |
| Princess Yachts |
| Heesen Yachts |
| Oceanco |
| Others |
Cost & Logistics Intelligence
Marine-grade aluminum and steel price indices cascade through Italian and Dutch shipyard tiers, compressing margins on custom superyacht builds while charter fleet operators absorb cost premiums through extended booking windows. EU Green Deal compliance costs for F-Gas HVAC retrofits stratify final vessel pricing across Mediterranean and Middle Eastern delivery corridors.
Pricing Analysis
Direct-to-owner sales for custom builds command substantial premiums over charter fleet procurement through volume aggregation discounts. Three-tier pricing structure across bespoke superyacht, premium motor yacht, and standard charter specifications reflects customization depth and certification grade. Pricing pressure stems from IMO Tier III selective catalytic retrofit mandates elevating outfitting costs. Charter operators exhibit highest price sensitivity due to utilization-rate economics, while sovereign buyers show minimal elasticity.
Supply Chain Analysis
Heavy-lift maritime freight costs from Japanese and European metallurgical suppliers constrain hull fabrication scheduling across Adriatic and North Sea construction centers. Italian, Dutch, and German shipyards anchor composite and steel-aluminum supply, drawing from Norwegian marine timber and Finnish electronics subsystems. Single-source vulnerability concentrates in lithium-ion battery integration for hybrid-electric architectures. Distribution runs through direct owner contracts and charter management house fleet agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance timelines in Italy and the Netherlands diverge from Saudi operational flexibility, creating cost differentials for alternative fuel conversion pathways.
For Market Incumbents: Cement Italian manufacturing heritage advantages through captive supply of carbon fiber pre-preg materials, insulating against Japanese quota-based allocation constraints. Deepen backward integration into battery-electric propulsion R&D partnerships to preempt emerging Dutch-German cooperative challenges in hybrid architecture dominance.
For New Entrants and Emerging Players: Capture fractional ownership platform white space in Caribbean and Southeast Asian archipelagos where digital brokerage penetration remains below Mediterranean saturation. Pursue catamaran shallow-draft specifications for sub-30-meter charter deployment, leveraging twin-hull stability advantages in reef-constrained anchorages.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized naval architecture boutiques possessing computational fluid dynamics capabilities for wind-assisted propulsion hybridization. Long-term viability hinges on Saudi Red Sea tourism corridor infrastructure commitments. Monitor Lloyd's Register and Bureau Veritas certification bottleneck resolution as inflection signal for delivery timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Italian shipyards integrating lithium-ion banks satisfy French Riviera marina noise restrictions. |
| Saudi Marina Infrastructure Joint Venture | Red Sea giga-project berthing preference secures multi-week itinerary charter positioning. |
| Backward Integration into Carbon Fiber Supply | Resin transfer molding capacity captures hull weight reduction premiums from Japanese suppliers. |
| Digital Twin Technology Adoption | Predictive maintenance compression reduces dry-dock downtime for British Virgin Islands operators. |
| Fractional Ownership Platform Launch | Sub-ultra-high-net-worth access expansion fragments demand across smaller Caribbean management houses. |
Research Approach
Coverage spans Mediterranean, Middle Eastern, North American, and Caribbean construction and charter circuits, with primary inputs from each. Naval architects, marine engineers, charter fleet operators, and marina infrastructure developers supplied operational data, cross-referenced with IMO MARPOL filings, EU Green Deal regulatory texts, Lloyd's Register classification records, and customs trade documentation. Bottom-up vessel delivery tallies and top-down tourism expenditure estimates underwent triangulation validation.
Rate-of-change decomposition across the analysis window isolated propulsion technology substitution effects, regulatory compliance cost pass-through, and experiential tourism demand elasticity. Segmentation modeling incorporated hull architecture, end-use deployment, length classification, and onboard system specification dimensions. CAGRs derived from historical build cycle analysis and forward order book visibility, with particular weighting for Saudi giga-project absorption rates and F-Gas Regulation retrofit scheduling.
Regulatory enforcement divergence, metallurgical supply quota volatility, and classification society inspection backlog resolution are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
US Low Speed Vehicle Market