
 Railway Lithium Battery Market | 2026-2036
Railway Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Lithium Battery Market Insights
Lithium iron phosphate chemistry is decoupling railway battery economics from cobalt and nickel price volatility. Saft Batteries leverages its aerospace heritage to anchor European rail certification standards. CATL sustains manufacturing scale through captive supply of cathode materials. Toshiba Infrastructure Systems differentiates through SCiB lithium titanate cells engineered for extreme temperature cycling in Shinkansen operations.
A railway lithium battery is an electrochemical energy storage system built to railway-specific shock, vibration, and fire-safety standards, typically operating at 400–800V DC with cycle lives exceeding 5,000 charge events. Its primary purpose is to replace diesel auxiliary power units and support regenerative braking energy recovery in electric and hybrid trains. Lithium iron phosphate dominates current procurement for its thermal stability and lower lifecycle cost in passenger train applications. Battery management systems represent the fastest-growing technology segment as operators demand predictive state-of-health monitoring to avoid in-service failures. Freight trains lag in adoption due to longer payback periods on electrification infrastructure, though lithium titanate gains traction where rapid charging at classification yards is critical.
The EU Green Deal and F-Gas Regulation are accelerating nickel-cadmium replacement mandates across European rail operators. China's MIIT enforces GB standards for traction battery safety, while Japan's METI subsidizes lithium titanate development through railway-specific R&D programs. India's CEA and RDSO are drafting localization requirements that will reshape procurement for the Dedicated Freight Corridor. Stakeholders must weigh chemistry selection against evolving fire-safety test protocols and country-specific content rules before committing to platform-scale supply agreements.
Market Dynamics
The EU Green Deal and China's dual carbon goals are forcing a chemistry transition from nickel-cadmium to lithium iron phosphate across auxiliary power and propulsion systems. This regulatory pressure is compressing procurement cycles and reshaping supplier qualification requirements.
Growth Catalysts
- EU F-Gas Regulation:Mandates the phase-out of fluorinated greenhouse gases in railway applications, accelerating lithium iron phosphate adoption for auxiliary power units in German and French rolling stock.
- High-speed rail electrification:China's expanding network requires auxiliary battery systems for emergency braking and onboard services, concentrating demand in East Asian manufacturing clusters.
- Regenerative braking integration:Lithium titanate chemistry enables rapid charge acceptance at classification yards, supporting energy recovery in Japanese Shinkansen and European freight corridors.
Market Restraints
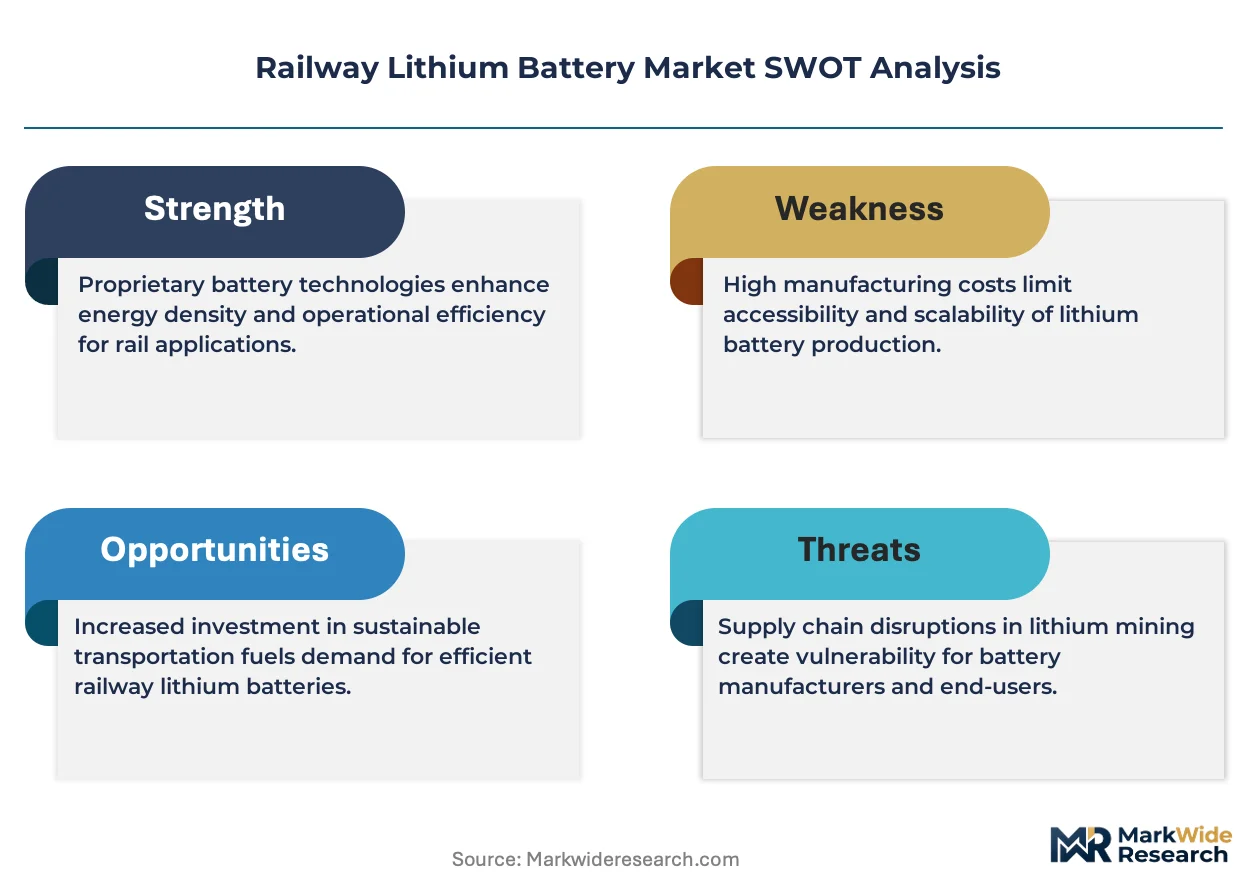
- Cobalt and nickel price volatility:Lithium iron phosphate decouples procurement from these input costs, but cathode material concentration in Chinese supply chains creates geopolitical exposure.
- Cell qualification timelines:Railway-specific shock, vibration, and fire-safety certification under EN 45545 and GB standards extends product development cycles beyond 24 months.
- Freight electrification economics:Long payback periods on classification yard infrastructure limit adoption outside rapid-charge corridors serving high-frequency routes.
Strategic Opportunities
- India's Dedicated Freight Corridor:CEA and RDSO localization requirements will reshape procurement for 3,600 route-km of new electrified track, creating openings for domestic assembly partnerships.
- Battery management system convergence:Predictive state-of-health monitoring is displacing scheduled maintenance in passenger fleets, opening recurring software revenue streams.
- Retrofit programs:European diesel-electric fleet modernization under EU Green Deal timelines creates aftermarket demand for drop-in lithium iron phosphate replacements.
Industry Challenges
- Thermal runaway containment engineering:Railway-specific fire-safety test protocols require cell-to-pack architecture redesigns that strain R&D resources.
- Legacy system integration:400–800V DC voltage matching with existing auxiliary power distribution requires custom power electronics and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Lithium Battery Market |
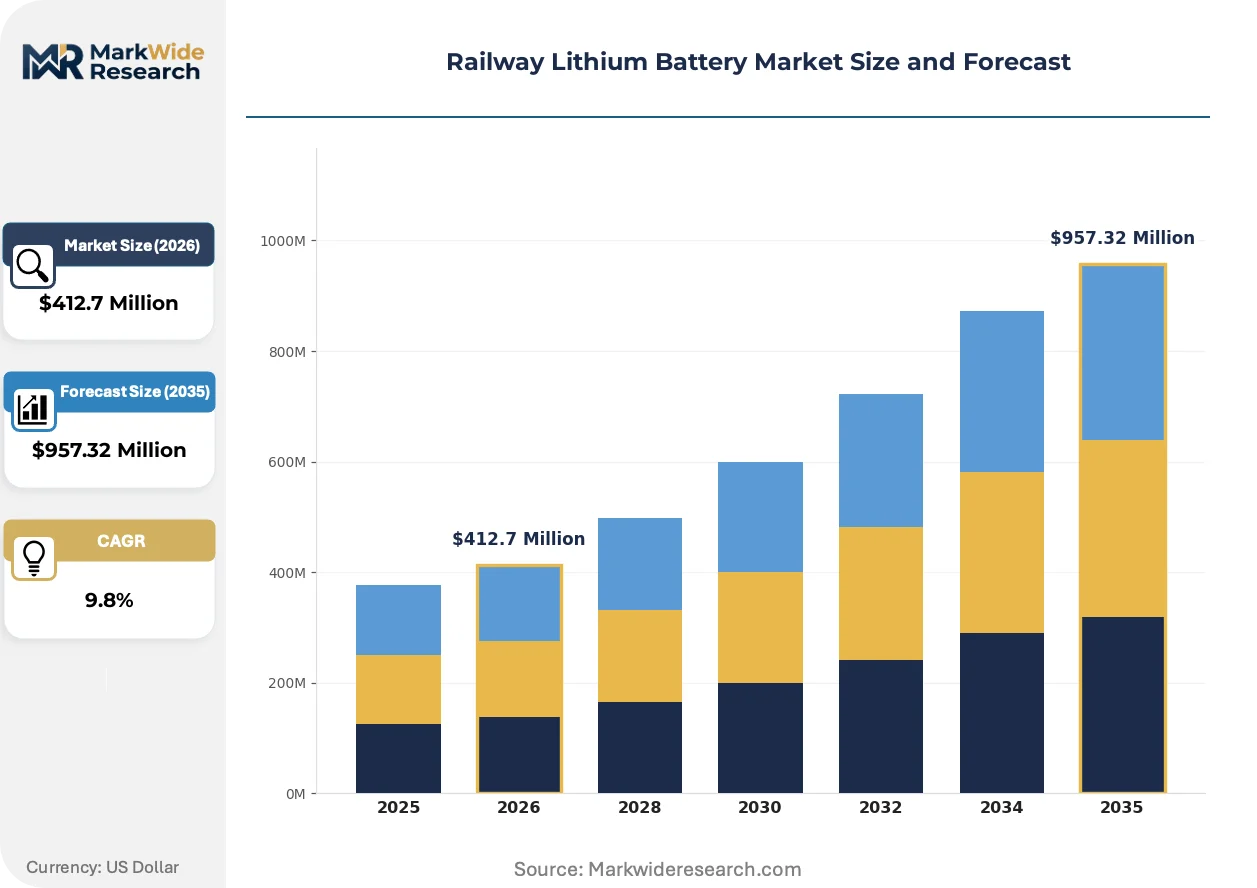
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $957.32 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Iron Phosphate, Lithium Nickel Manganese Cobalt, Lithium Titanate, Lithium Polymer Technology: Fast Charging, Energy Density, Battery Management Systems, Hybrid Technology Application: Passenger Trains, Freight Trains, High-Speed Trains, Maintenance Vehicles End User: Rail Operators, Public Transport Authorities, Freight Companies, Logistics Providers |
| Companies Covered | Saft Batteries, GS Yuasa, CATL, EnerSys, Toshiba Infrastructure Systems, Hoppecke Batterien, Hitachi Rail, Leclanché, AKASOL AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Lithium Battery Market Trends and Innovations
Battery chemistry selection is diverging sharply between passenger and freight applications. Thermal stability requirements and duty cycle profiles are forcing specialization rather than platform standardization.
Solid-state electrolyte research is converging with silicon-anode architectures to push energy density beyond 300 Wh/kg for next-generation auxiliary power units. Japanese rolling stock operators are piloting these cells for Shinkansen emergency power systems. The technology is converging with existing manufacturing infrastructure to reduce commercialization risk.
The EU F-Gas Regulation and China's MIIT GB standards are tightening fire-safety test protocols for traction battery systems. Manufacturers must now demonstrate cell-level thermal runaway propagation resistance to qualify for platform-scale supply agreements. European operators are responding by consolidating procurement around suppliers with established EN 45545 certification.
Operators are unbundling battery system procurement from rolling stock OEM contracts to secure direct control over lifecycle costs and second-life asset value. This disintermediation is concentrating purchasing power among large state rail incumbents in Germany, France, and Japan. After-sales service contracts are pivoting from fixed-fee maintenance to availability-based performance guarantees with predictive monitoring obligations.
Railway Lithium Battery Market Segmentation
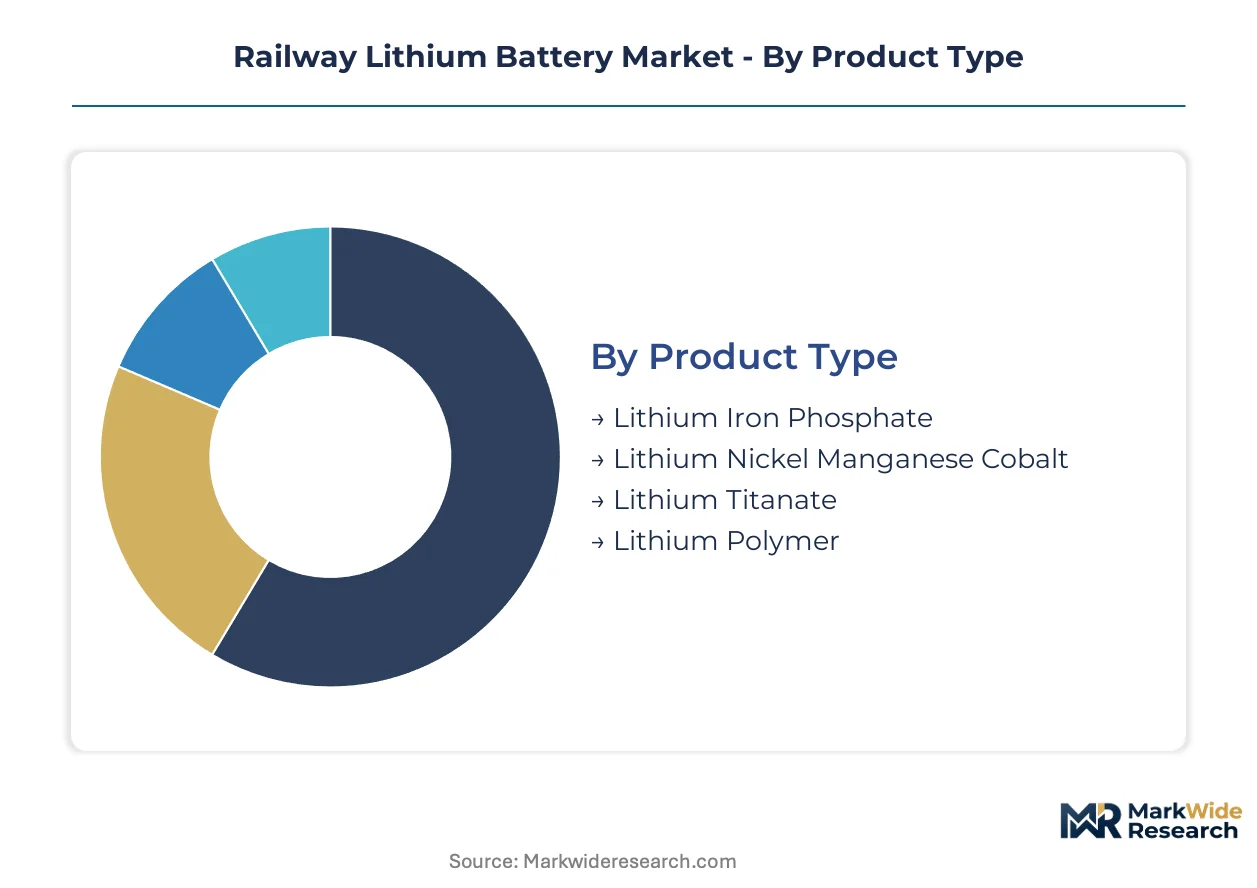
Chemistry selection and duty cycle requirements are fragmenting procurement strategies across railway battery categories. Operators now segment purchases by thermal stability needs, charging infrastructure availability, and lifecycle cost profiles rather than treating traction batteries as interchangeable commodities.
Product Type:
Volume deployment concentrates in lower-cost iron phosphate systems, while premium applications absorb higher-performance chemistries at elevated price points.
- Lithium Iron Phosphate:Cathode composition of lithium iron phosphate delivers thermal runaway resistance above 270°C, eliminating cobalt and nickel from the supply chain. Chinese high-speed rail procurement and European retrofit programs under EU F-Gas Regulation are absorbing the majority of global cell output for auxiliary power and emergency braking systems.
- Lithium Titanate:Anode substitution with lithium titanate oxide enables 10C charge rates and operating ranges spanning -30°C to 55°C. Japanese Shinkansen operators and European freight classification yards are deploying these cells where rapid energy recovery from regenerative braking justifies the 30% energy density penalty.
- Lithium Nickel Manganese Cobalt:Layered oxide cathodes with nickel-majority composition serve hybrid propulsion systems requiring maximum gravimetric energy density.
- Lithium Polymer:Gel electrolyte configurations in pouch formats occupy niche applications with severe space constraints in legacy rolling stock conversions.
Mature deployment sits with Lithium Iron Phosphate. Newer deployment is concentrated in Lithium Titanate.
Technology:
Hardware-software integration intensity separates commoditized cell supply from value-captured system architectures.
- Battery Management Systems:Predictive state-of-health algorithms and cell balancing electronics now represent the primary differentiation layer in railway tenders. German and French operators are mandating predictive maintenance capabilities as contract prerequisites, displacing scheduled replacement cycles with availability-based performance guarantees.
- Fast Charging:High-rate charge acceptance protocols require thermal management redesigns and specialized power electronics at classification yard infrastructure. Japanese METI subsidies and European freight corridor electrification are accelerating field deployment.
- Energy Density:Gravimetric and volumetric optimization targets drive solid-state electrolyte research programs for next-generation auxiliary power units.
- Hybrid Technology:Dual-chemistry architectures combining high-power and high-energy cells are gaining traction in diesel-electric conversions.
System-level value capture is climbing fastest in Battery Management Systems. Cell-level hardware specifications are stabilizing in Fast Charging.
Application:
Passenger service economics support premium battery investments that freight operations cannot yet justify.
- Passenger Trains:Onboard auxiliary power for lighting, HVAC, and control systems operates on predictable duty cycles with guaranteed route electrification. Chinese and Japanese operators are procuring lithium iron phosphate systems at platform scale for high-speed networks.
- High-Speed Trains:Emergency braking power and catenary fault ride-through requirements demand instantaneous discharge capability and EN 45545 fire-safety certification. European and East Asian procurement is concentrating around suppliers with established rolling stock integration experience.
- Freight Trains:Long-haul diesel-electric locomotives face payback period constraints on electrification infrastructure, limiting adoption to rapid-charge corridors.
- Maintenance Vehicles:Track inspection and work train applications prioritize weight reduction and modular swap capability over maximum cycle life.
Installed base concentration remains in Passenger Trains. Steepest expansion trajectory is emerging in High-Speed Trains.
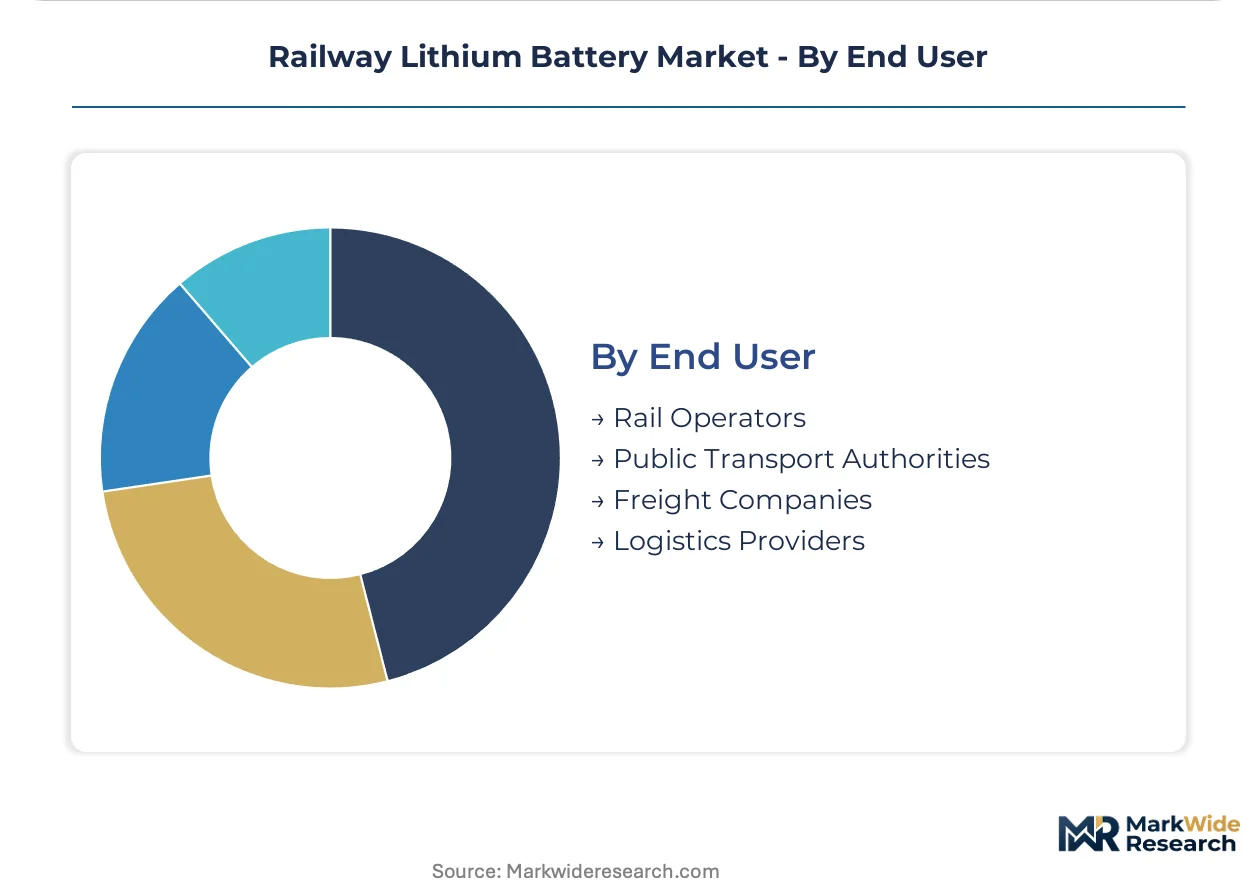
End User:
Procurement centralization among state incumbents is displacing fragmented purchasing through rolling stock OEMs.
- Rail Operators:Deutsche Bahn, SNCF, and JR East are unbundling battery procurement from trainset contracts to secure direct control over lifecycle costs and second-life asset value. Direct sourcing is concentrating purchasing power and reshaping supplier qualification requirements.
- Public Transport Authorities:Urban rail and metro systems in France and Germany are specifying lithium iron phosphate replacements for nickel-cadmium auxiliary batteries under EU Green Deal timelines.
- Freight Companies:Classification yard operators are piloting lithium titanate systems for regenerative braking recovery on high-frequency corridors.
- Logistics Providers:Intermodal terminal operators are emerging as niche demand sources for maintenance vehicle electrification.
Contracting sophistication is most advanced among Rail Operators. Regulatory mandate clarity is strongest for Public Transport Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changzhou National High-Tech District in Jiangsu Province anchors the densest concentration of railway lithium battery production, with tax incentives drawing cathode material suppliers and cell fabricators into integrated manufacturing corridors.
China
High-speed rail procurement from CRRC and auxiliary power retrofits on existing fleets absorb the majority of global lithium iron phosphate output. MIIT enforces GB standards for traction battery safety and thermal runaway containment. Changzhou and Ningbo manufacturing clusters supply complete battery systems for domestic deployment and export to Belt and Road rail projects.
Germany
Deutsche Bahn's nickel-cadmium replacement program under EU F-Gas Regulation timelines concentrates demand for EN 45545-certified auxiliary power units. KBA oversees rolling stock battery approval processes that extend qualification cycles. Saxony and Bavaria host final assembly operations serving Central European retrofit programs and new ICE fleet procurement.
Japan
JR East and JR Central specify lithium titanate cells for Shinkansen regenerative braking and extreme-temperature reliability. METI subsidizes railway-specific R&D programs through NEDO grants. Kanto region engineering centers in Tokyo and Kanagawa Prefecture coordinate SCiB cell development with rolling stock integration teams.
France
SNCF unbundles battery procurement from Alstom trainset contracts to secure direct lifecycle cost control on TGV and regional fleet auxiliary systems. EU Green Deal mandates accelerate phase-out of fluorinated greenhouse gases in rolling stock. Île-de-France and Auvergne-Rhône-Alpes regions concentrate supplier qualification activity around Paris-based engineering headquarters.
India
Dedicated Freight Corridor electrification creates procurement demand for 3,600 route-km of new track with localization requirements from CEA and RDSO. PLI scheme incentives for advanced chemistry cell manufacturing reshape supplier entry strategies. Gujarat and Maharashtra industrial corridors attract joint venture proposals for domestic battery assembly partnerships.
Railway Lithium Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with chemistry-agnostic system integrators capturing value in passenger rail while cell-focused suppliers dominate freight corridor opportunities. Railway-specific certification requirements under EN 45545 and GB standards create qualification moats that favor incumbents with multi-year approval track records. Three archetypes define competitive positioning: aerospace-derived battery specialists leveraging cross-industry certification heritage, captive cathode producers securing raw material cost advantages, and diversified industrial conglomerates offering bundled power electronics integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with operators demanding localized assembly and direct aftermarket service commitments.
Among established European specialists, Saft Batteries and Leclanché occupy positions shaped by decades of rolling stock integration experience and EN certification authority. GS Yuasa represents the Japanese industrial archetype with diversified electrochemical expertise spanning automotive and rail applications. CATL anchors the scale-driven tier with captive cathode supply chains and platform-scale manufacturing infrastructure serving Chinese high-speed rail procurement.
| Leading Market Players |
|---|
| Saft Batteries |
| GS Yuasa |
| CATL |
| EnerSys |
| Toshiba Infrastructure Systems |
| Hoppecke Batterien |
| Hitachi Rail |
| Leclanché |
| AKASOL AG |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as EN 45545 certification timelines stretch beyond 24 months and concentrate procurement among incumbents with established rolling stock integration track records. Buyers absorbing nickel-cadmium replacement mandates face constrained vendor pools that prop pricing power for certified system integrators.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with 24-month qualification cycles commanding 15-20% premiums over spot inventory from non-certified fabricators. Price differentiation hinges on EN 45545 fire-safety certification grade and volume scale, with Deutsche Bahn and SNCF direct-sourcing contracts anchoring the premium band. Cost compression in standard-tier iron phosphate cells is intensifying because Chinese cathode material suppliers are expanding captive smelting capacity. Freight operators remain most price-sensitive due to longer electrification payback periods, while high-speed rail incumbents absorb premium positioning for emergency braking reliability.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and JR East mandate multi-supplier qualification, forcing cell fabricators to maintain parallel EN 45545 and GB standard certification tracks. Geographic supply concentration centers on China, South Korea, and Japan, with Changzhou and Ningbo clusters feeding iron phosphate cathode output. Raw material dependencies rest on lithium carbonate, electrolyte salts, and copper foil substrate availability. Single-source vulnerability in Chinese cathode precursor refining creates geopolitical exposure. Distribution runs through rolling stock OEM integration contracts and direct operator procurement channels, with aftermarket service commitments increasingly bundled into initial supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway lithium battery supply remains structurally constrained by 24-month EN 45545 certification timelines, propping pricing power for incumbents with multi-year approval track records and squeezing margins for unqualified aspirants.
For Market Incumbents: Deploy backward integration into cathode material refining to lock in cost positions against Chinese supply chain volatility. Secure capacity expansion slots in Saxony and Bavaria to serve Deutsche Bahn's nickel-cadmium replacement program. Defend against emerging Chinese system integrators by deepening rolling stock OEM relationships and embedding predictive maintenance software into long-term service contracts. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for EN 45545-certified auxiliary power unit suppliers without existing OEM entanglements. Target India's Dedicated Freight Corridor localization mandates through joint venture structures with Gujarat-based industrial partners. Penetrate via battery management system software licensing to rail operators seeking to unbundle procurement from rolling stock contracts. For Investors and Strategic Acquirers: JR East's unbundling of lithium titanate procurement from Toshiba Infrastructure Systems contracts is the leading indicator that operator direct-sourcing is accelerating. Acquire mid-cap specialists with GB standard certification and existing CRRC supply relationships for 5-10 year exposure to Chinese high-speed rail expansion. Watch for METI subsidy announcements on solid-state electrolyte R&D as the inflection signal for next-generation chemistry transitions.| Strategic Initiative | Industry Significance |
|---|---|
| EN 45545 Certification Investment | Deutsche Bahn and SNCF procurement mandates require fire-safety test protocol compliance for platform-scale supply eligibility. |
| Backward Integration into Cathode Materials | CATL's captive lithium iron phosphate precursor production insulates margins from Chinese supply chain concentration risks. |
| Predictive Maintenance Software Development | German and French operators are mandating state-of-health algorithms as contract prerequisites for auxiliary power systems. |
| Joint Venture for Indian Localization | CEA and RDSO content rules for Dedicated Freight Corridor electrification reshape entry strategies for foreign cell suppliers. |
| Solid-State Electrolyte R&D Partnership | Japanese METI subsidies through NEDO grants target silicon-anode architectures for Shinkansen emergency power applications. |
Research Methodology
Independent corroboration across rolling stock procurement officers, battery system engineering directors, and railway regulatory affairs leads underwrites the qualitative findings in this study. Primary fieldwork with CRRC supply chain managers, Deutsche Bahn fleet modernization teams, and JR East maintenance planners combined with secondary validation from MIIT GB standard filings, EU F-Gas Regulation implementation timelines, and EN 45545 test protocol documentation. Bottom-up cell shipment estimates and top-down electrification infrastructure spending projections triangulate volume assumptions.
Rate-of-change decomposition across chemistry selection, application segmentation, and end-user contracting sophistication drives the analytical framework throughout the projection horizon. Segmentation dimensions modeled include lithium iron phosphate versus lithium titanate chemistry, passenger versus freight application duty cycles, and direct operator procurement versus OEM-integrated supply channels. CAGRs derive from rolling stock fleet replacement schedules, high-speed rail network expansion pipelines, and retrofit program acceleration under EU Green Deal timelines. Forecast inputs incorporate classification yard electrification economics and regenerative braking energy recovery penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state electrolyte commercialization would alter the outlook for energy density improvement trajectories. Forecasts reflect assumptions on EN 45545 certification timeline compression, Chinese GB standard harmonization progress, and India PLI scheme incentive disbursement rates. Deviation in cobalt and nickel price volatility would shift the outlook materially for hybrid propulsion system chemistry selection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
South America E-Bike Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market