
 Specialty Vehicle Market | 2026-2036
Specialty Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Vehicle Market Outlook
The gap between premium custom-engineered platforms and commodity chassis builds is rebalancing as fleet operators prioritize total cost of ownership over upfront acquisition price. Mercedes-Benz Group AG leverages its modular architecture to span luxury ambulance and armored segments without duplicate tooling. Oshkosh Corporation dominates severe-duty defense and fire apparatus through captive axle and drivetrain production. REV Group anchors the North American emergency vehicle aftermarket with distributed service networks that reduce downtime for municipal customers.
Specialty vehicles are purpose-built automotive platforms engineered to specific operational envelopes, typically incorporating reinforced frames, auxiliary power systems, and mission-specific body structures fabricated from aluminum or composite panels. These units serve critical functions where standard commercial vehicles fail to meet payload, terrain, or regulatory requirements. Recreational vehicles command the broadest consumer margin pool as discretionary buyers absorb premium finishes, while electric vehicle technology within the technology segment attracts the fastest engineering investment as range and charging infrastructure mature. Fire engines sustain the highest average selling prices due to NFPA certification complexity and low production volumes that resist commoditization.
The EPA enforces Tier 4 Final and emerging low-NOx standards that force engine recalibration or full powertrain replacement in vocational trucks. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in climate-controlled emergency and recreational units, adding compliance cost to specialized HVAC systems. Stakeholders must track how NHTSA crashworthiness rules for alternative-fuel storage reshape bodybuilder liability and chassis supplier relationships.
Market Dynamics
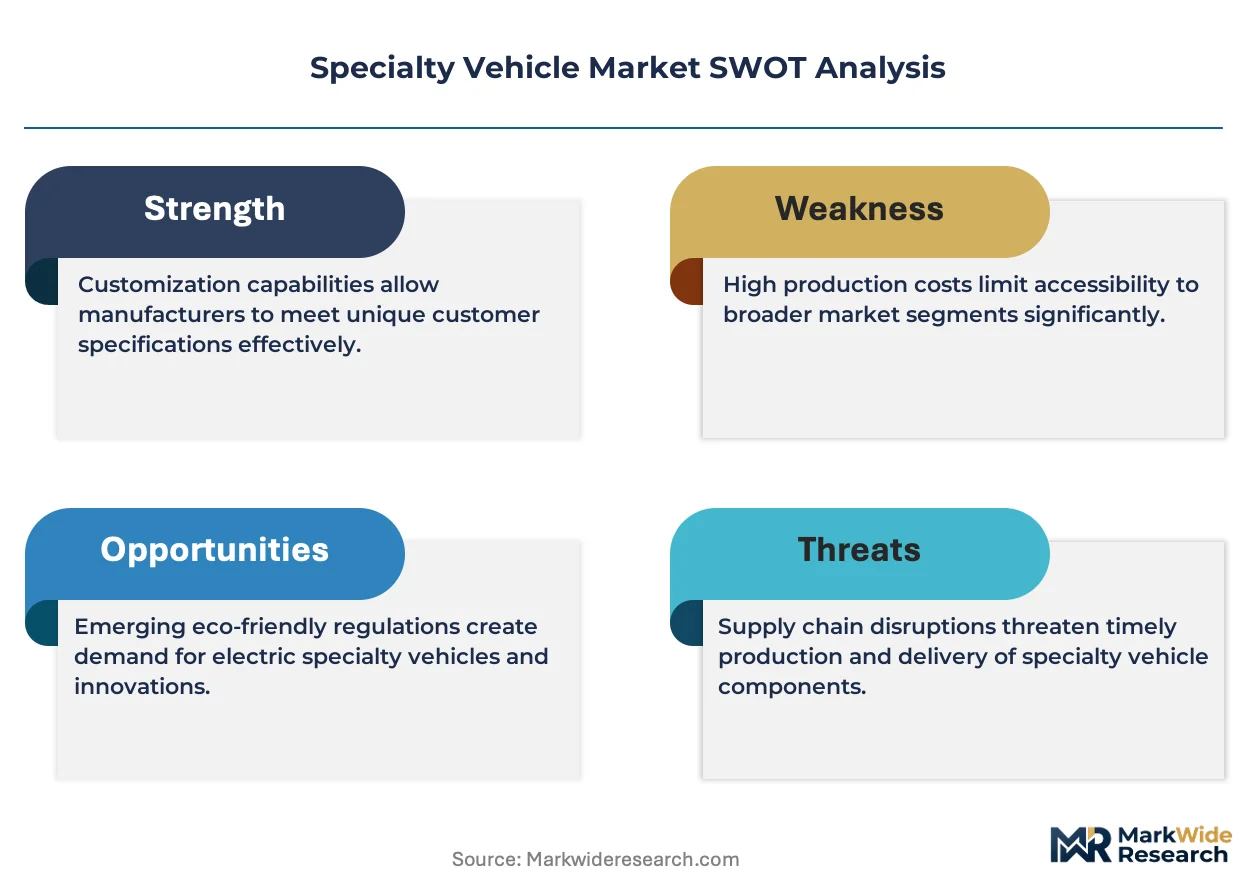
Electric powertrain retrofits are redirecting municipal procurement budgets away from internal combustion platforms, forcing bodybuilders to requalify aluminum body structures for battery placement and thermal management loads.
Growth Catalysts
- EPA Tier 4 Final mandates:Engine recalibration requirements are accelerating replacement cycles for aging fire apparatus and vocational trucks across US municipal fleets.
- Germany municipal modernization:Fire departments in Bavaria and North Rhine-Westphalia are procuring advanced aerial ladder systems with integrated command electronics.
- Lithium-ion battery energy density:Improved cell chemistry is extending electric range for emergency vehicles without payload compromise.
Market Restraints
- Aluminum sheet volatility:Body structure fabrication costs fluctuate with primary metal exchange pricing, squeezing fixed-price municipal contract margins.
- Axle supply concentration:Severe-duty drivetrain sourcing clusters among three North American foundries, creating delivery vulnerability for defense chassis.
- NFPA 1901 certification timeline:Extended pump and electrical testing protocols delay revenue recognition by four to six months.
Strategic Opportunities
- India emergency services:State-level disaster response agencies are tendering for mobile command units with satellite uplink capability.
- EU F-Gas Regulation phase-down:Low-GWP refrigerant mandates create retrofit demand for climate-controlled ambulance HVAC systems.
- Telematics-CRM convergence:Predictive maintenance platforms are opening subscription revenue streams for distributed service networks.
Industry Challenges
- Composite technician scarcity:Vacuum infusion and resin transfer molding skills lag demand for lightweight body panel production.
- Dual powertrain inventory:Bodybuilders must maintain parallel diesel and electric assembly lines until platform consolidation emerges.
- Legacy fleet interoperability:New aerial systems must interface with decades-old pump control architectures still operational in rural districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Vehicle Market |
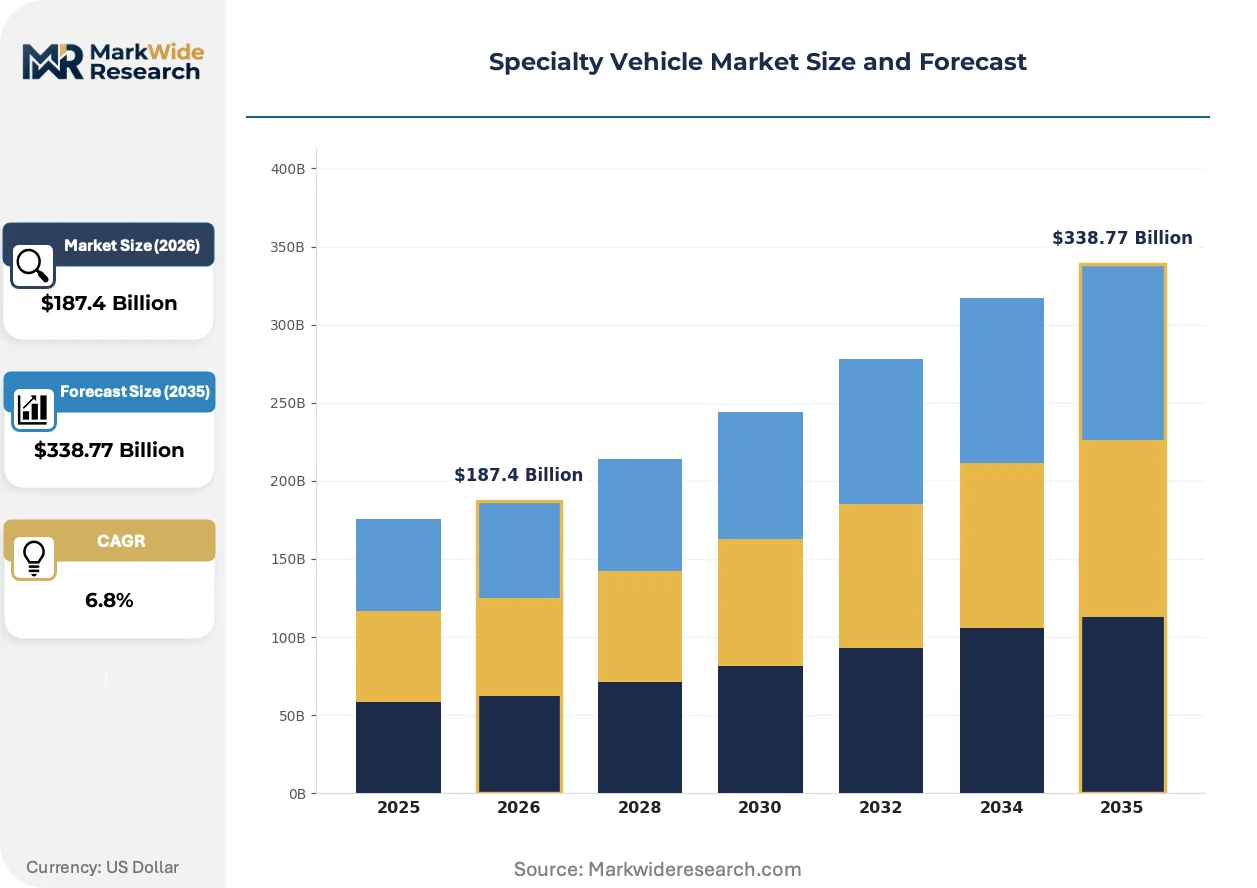
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Delivery Truck, Ambulance, Fire Engine, Recreational Vehicle End User: Government, Emergency Services, Tourism Industry, Construction Application: Healthcare, Emergency Response, Transportation, Off-Road Technology: Electric Vehicles, Hybrid Systems, Fuel Cell, Autonomous Driving |
| Companies Covered | Mercedes-Benz Group AG, Iveco Group N.V., Oshkosh Corporation, General Motors, MORITA HOLDINGS CORPORATION, REV Group, AB Volvo, Sutphen Corporation, Rosenbauer International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Vehicle Market Strategic Shifts
Modular chassis architecture is compressing development cycles as manufacturers seek to span multiple mission profiles without dedicated tooling for each variant.
Carbon fiber reinforced polymer is integrating into aerial ladder construction to reduce tip deflection while maintaining NFPA load ratings. German and Austrian fire departments are specifying these assemblies for urban deployments with tight turning radii. The material shift is integrating advanced composite fabrication into traditional steel-dominated supply chains, forcing Tier 2 suppliers to acquire autoclave capacity or exit the segment.
The EU Green Deal's 55% emissions reduction target is tightening CO2 benchmarks for vocational vehicles above 16 tonnes. Engine recalibration alone cannot bridge the gap, so manufacturers are accelerating hybrid powertrain development for fire apparatus with high idle-duty cycles. Scandinavian municipal buyers are now requiring lifecycle carbon disclosure in tender documentation.
Fleet operators are consolidating vendor relationships to secure priority build slots and standardized training protocols. Large US county emergency services are moving from transactional purchasing to multi-year framework agreements with single-source bodybuilders. California and Texas counties are piloting this model for ambulance replacement programs, trading price competition for guaranteed delivery windows and unified parts logistics.
Specialty Vehicle Market Segmentation
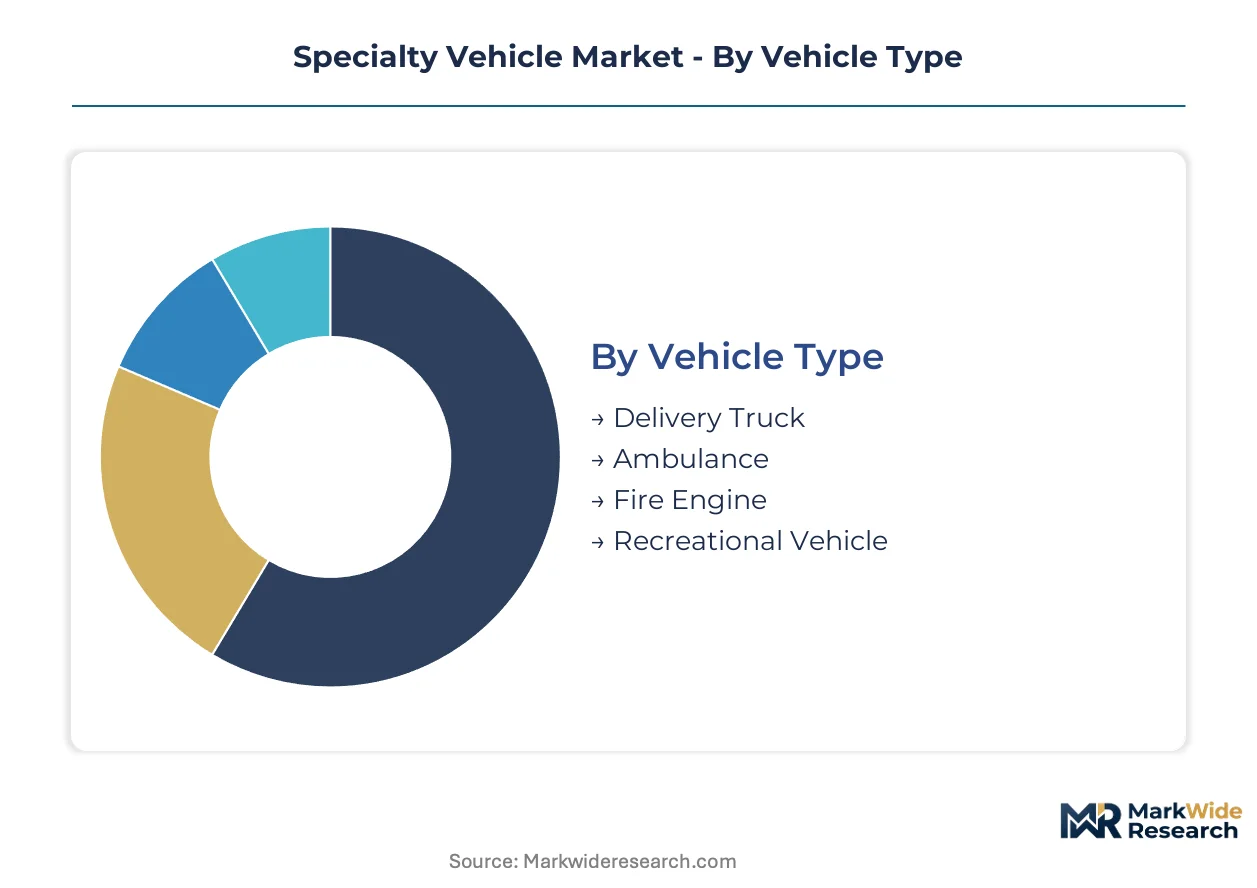
Specialty vehicle procurement follows distinct technical and operational logics that reshape how manufacturers configure chassis, body structures, and powertrain systems. Each segmentation dimension reveals where engineering investment concentrates and which customer budgets are expanding.
Vehicle Type:
Standalone purpose-built platforms dominate municipal and emergency procurement, while recreational vehicles embed consumer-grade finishes into modified commercial chassis.
- Fire Engine:NFPA-certified apparatus with integrated pump systems, aerial ladders, and command electronics. Bavarian and North Rhine-Westphalian fire departments in Germany are modernizing fleets with advanced aerial systems under municipal budget reallocations.
- Recreational Vehicle:Consumer discretionary platforms with premium interior finishes and climate-controlled living quarters. Tourism operators in coastal US counties and Mediterranean camping corridors are absorbing extended delivery timelines for custom configurations.
- Ambulance:Type I, II, and III emergency medical service vehicles with patient compartment HVAC and electrical load management.
- Delivery Truck:Last-mile vocational chassis with reinforced frames for parcel and food service routing.
Volume placements concentrate in recreational vehicles; the faster expansion belongs to fire engines.
End User:
Budget authority and procurement timelines diverge sharply between tax-funded agencies and private operators.
- Emergency Services:Municipal fire departments, EMS districts, and disaster response agencies with multi-year capital replacement cycles. US county fleets are consolidating vendor relationships to secure priority build slots under framework agreements.
- Government:Federal and state agencies procuring mobile command and defense platforms. Indian state-level disaster response authorities are tendering for satellite-equipped command units.
- Tourism Industry:RV rental operators and campground developers with seasonal demand fluctuations.
- Construction:Heavy equipment contractors requiring severe-duty chassis for material transport.
Emergency services command the highest average selling prices; government procurement is climbing the fastest as defense and disaster preparedness budgets expand.
Application:
Mission profiles dictate payload, terrain, and regulatory compliance requirements across divergent operational envelopes.
- Emergency Response:Rapid deployment platforms with auxiliary power systems and interoperable communications. Scandinavian municipal buyers now require lifecycle carbon disclosure in tender documentation under EU Green Deal benchmarks.
- Healthcare:Patient transport with climate control, oxygen supply, and infection containment systems.
- Off-Road:Severe-duty chassis with locking differentials and reinforced suspension for unpaved terrain.
- Transportation:Intermodal and last-mile logistics platforms with standardized body mounting.
Emergency response absorbs the most engineering investment per unit; healthcare applications are gaining share fastest as aging populations expand ambulance fleet requirements.
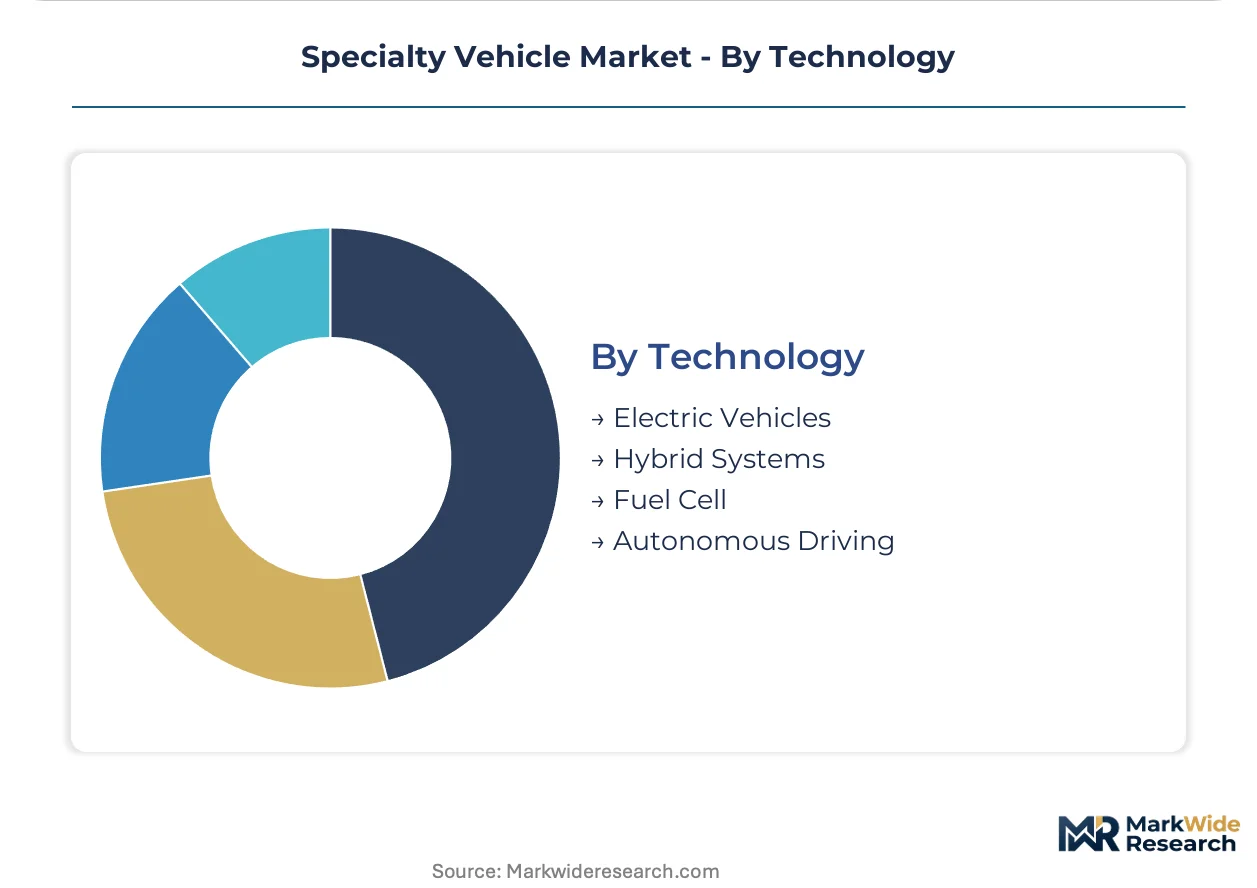
Technology:
Powertrain diversification is forcing parallel assembly lines and requalification of body structures for thermal and load management.
- Electric Vehicles:Battery-electric platforms with regenerative braking and depot charging infrastructure. Improved lithium-ion energy density is extending range without payload compromise for urban emergency fleets.
- Hybrid Systems:Parallel and series configurations for high idle-duty cycles in fire apparatus. EU CO2 benchmarks above 16 tonnes are accelerating hybrid development as engine recalibration proves insufficient.
- Fuel Cell:Hydrogen-electric powertrains for extended range without battery weight penalties.
- Autonomous Driving:Sensor-integrated platforms for convoy operations and hazardous environment entry.
Hybrid systems retain near-term volume leadership; electric vehicles are expanding most quickly as municipal procurement budgets redirect toward zero-emission platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's Fox River Valley anchors North American severe-duty chassis production, while Germany's industrial south drives European aerial ladder modernization. Municipal procurement patterns diverge sharply across these manufacturing clusters as emissions mandates and fleet replacement cycles reshape demand geography.
United States
County-level emergency services in California and Texas are consolidating vendor relationships under multi-year framework agreements for ambulance replacement programs. EPA Tier 4 Final mandates are accelerating fire apparatus replacement cycles across Midwest municipal fleets. Pierce Manufacturing's operations in Appleton, Wisconsin anchor domestic aerial ladder and pumper production for municipal buyers.
Germany
Bavarian and North Rhine-Westphalian fire departments are procuring advanced aerial ladder systems with integrated command electronics under municipal budget reallocations. EU Green Deal CO2 benchmarks above 16 tonnes are forcing hybrid powertrain development for high idle-duty fire apparatus. Rosenbauer International's manufacturing presence in Leonding, Austria supplies German-speaking markets with carbon fiber-reinforced ladder assemblies.
India
State-level disaster response agencies in Maharashtra and Gujarat are tendering for mobile command units with satellite uplink capability. The country's national automotive regulator is enforcing stricter emissions norms for commercial vehicles above 3.5 tonnes. Tata Motors' Jamshedpur facility and Mahindra's Igatpuri plant anchor domestic severe-duty chassis fabrication for government procurement.
Japan
Metropolitan fire departments in Tokyo and Osaka are modernizing aging ladder fleets with compact-turning-radius specifications for dense urban corridors. METI's carbon neutrality roadmap is pressuring vocational vehicle manufacturers toward electrified powertrains. Morita Holdings' headquarters cluster in Osaka anchors domestic fire apparatus engineering for Asian export markets.
Canada
Provincial emergency services in Ontario and Alberta are absorbing extended delivery timelines for custom-configured aerial platforms. Environment Canada's phased emissions regulations for heavy-duty vehicles align with US EPA Tier 4 Final timelines. Spartan Emergency Response's manufacturing footprint in Brandon, Manitoba serves prairie municipal fleets with severe-climate specifications.
Specialty Vehicle Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and captive component production. The market structures around three tiers: integrated chassis-bodybuilders with in-house axle and drivetrain production, specialized bodybuilders sourcing commercial chassis, and regional assemblers serving price-sensitive municipal segments. Strategic moves concentrate on multi-year framework agreements with county-level buyers and parallel diesel-electric assembly line maintenance until platform consolidation emerges.
Within the integrated chassis tier, Oshkosh Corporation and Mercedes-Benz Group AG exemplify captive production strategies that span defense, fire, and emergency medical segments without duplicate tooling investments. REV Group occupies a position among North American bodybuilders emphasizing distributed service networks for municipal aftermarket retention. Rosenbauer International AG represents European engineering concentration in aerial ladder carbon fiber integration and advanced command electronics. These three anchors illustrate how geographic manufacturing clustering and regulatory proximity shape competitive positioning across distinct procurement jurisdictions.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| Iveco Group N.V. |
| Oshkosh Corporation |
| General Motors |
| MORITA HOLDINGS CORPORATION |
| REV Group |
| AB Volvo |
| Sutphen Corporation |
| Rosenbauer International AG |
| Others |
Value Chain & Pricing Dynamics
Municipal procurement departments in Germany and the United States concentrate buying power through multi-year framework agreements, compressing margins for bodybuilders unable to offer lifecycle cost guarantees or captive component production. This buyer consolidation rewards integrated manufacturers with in-house axle and drivetrain fabrication while squeezing regional assemblers competing on transactional price alone.
Pricing Analysis
Value-based pricing anchored to apparatus uptime and total cost of ownership dominates municipal fire apparatus procurement, with NFPA 1901 certification complexity and low production volumes insulating premium tiers from commoditization. Price differentiation separates integrated chassis-bodybuilders with captive axle production from specialized bodybuilders sourcing commercial platforms, while aluminum sheet volatility on primary metal exchanges intensifies cost compression for fixed-price municipal contracts. County emergency services in California and Texas exhibit highest price sensitivity as they pilot consolidated vendor relationships, whereas Bavarian fire departments absorb premium aerial ladder specifications with integrated command electronics.
Supply Chain Analysis
Refurbishment flows for legacy pump control architectures and remanufactured aerial ladder assemblies extend asset life in rural districts, creating parallel aftermarket channels alongside new apparatus procurement. Severe-duty drivetrain sourcing clusters among foundries in the United States, Germany, and Austria, with carbon fiber-reinforced polymer ladder construction drawing from autoclave capacity expansion in German-speaking markets. Single-source vulnerability in axle supply among three North American foundries threatens defense chassis delivery timelines, while distribution runs through manufacturer-direct municipal contracts and distributed service networks for aftermarket parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EPA Tier 4 Final and EU Green Deal emissions mandates force smaller bodybuilders toward insolvency or acquisition by integrated chassis manufacturers with captive powertrain development resources.
For Market Incumbents: Acquire autoclave capacity and composite fabrication expertise to secure carbon fiber aerial ladder supply chains as German departments specify lightweight assemblies. Consolidate backward integration into battery thermal management systems before electric platform qualification requirements harden, defending against emerging entrants with modular chassis architectures. For New Entrants and Emerging Players: Begin with mobile command units for Indian state-level disaster response agencies, where satellite uplink capability requirements outpace domestic supply capacity. Target telematics-CRM convergence for predictive maintenance subscriptions, penetrating municipal aftermarket retention gaps left by incumbent distributors. For Investors and Strategic Acquirers: The window for entry favors mid-cap bodybuilders with NFPA certification infrastructure and established county framework agreements, positioned for absorption by integrated chassis manufacturers seeking geographic expansion. Monitor lithium-ion battery energy density improvements and charging infrastructure deployment as inflection signals for electric fire apparatus procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Chassis Architecture Investment | Mercedes-Benz Group AG leverages shared platforms across ambulance and armored segments without duplicate tooling. |
| Carbon Fiber Aerial Ladder Integration | Rosenbauer International AG supplies German departments with lightweight assemblies reducing tip deflection under NFPA load ratings. |
| Distributed Service Network Expansion | REV Group anchors municipal aftermarket retention through localized parts logistics and technician training programs. |
| Hybrid Powertrain Development | EU CO2 benchmarks above 16 tonnes accelerate parallel diesel-electric assembly lines for high idle-duty fire apparatus. |
| Telematics-CRM Platform Convergence | Predictive maintenance subscriptions open recurring revenue streams as county fleets consolidate vendor relationships. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of fire apparatus procurement officers, municipal fleet managers, composite fabrication technicians, and aftermarket service directors. EPA enforcement documentation, EU Green Deal implementation guidance, and NFPA certification timelines supplemented production and delivery data. Bottom-up unit shipment estimates triangulated against top-down municipal budget allocation analysis across the analysis window.
Production volume reconciliation against municipal tender databases and chassis registration records validated segmentation splits by vehicle type, end user, and powertrain technology. Modeled dimensions included fire engine, ambulance, and recreational vehicle categories; emergency services, government, and tourism industry end users; and electric, hybrid, and internal combustion propulsion architectures. CAGRs derived from replacement cycle acceleration under emissions mandates and battery energy density improvement curves.
Underlying measurement precision varies by segment; fire apparatus with NFPA certification timelines and low production volumes carry tighter precision than commoditized recreational vehicle chassis. Forecasts embed assumptions regarding aluminum price stability, axle foundry capacity expansion, and electric charging infrastructure deployment pace. Practitioners should monitor EPA enforcement intensity, EU F-Gas Regulation phase-down schedules, and lithium-ion cell chemistry announcements for early signals of procurement budget redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Asia-Pacific Motor Home Market