
 Yacht Market | 2026-2036
Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Market Analysis
Naval architecture talent is rotating from commercial shipping into luxury yacht design, tightening labor pools at Northern European yards. Feadship leverages its Dutch heritage to sustain artisanal build quality across custom commissions. Lürssen anchors German engineering credibility in the superyacht segment through in-house steel fabrication. Oceanco competes on technical complexity, specializing in hybrid-electric propulsion systems above 80 meters.
A yacht is a privately operated recreational vessel exceeding 24 meters in length, typically constructed from steel, aluminum, or advanced composites, and engineered for extended ocean cruising with crewed hospitality operations. Motor yachts dominate order books due to their superior range and interior volume allocation, while sailing yachts occupy a narrower niche among purist owners seeking wind-driven performance. The superyacht segment captures the deepest margin pools, with fiberglass construction leading volume production in smaller size classes where standardized hull platforms reduce build cycles.
The EU's F-Gas Regulation and MEE's dual carbon goals in China are tightening refrigerant and emissions standards for onboard climate systems, forcing redesigns of HVAC architectures. ISO 9001 and Lloyd's Register certification frameworks govern build quality and insurance eligibility, creating gating factors for yard market access. Stakeholders must monitor how regulatory divergence between European and Asian compliance regimes reshapes build-location decisions and supplier qualification timelines.
Market Dynamics
The EU Green Deal's emissions standards are forcing shipyards to abandon conventional diesel-electric architectures in favor of hybrid propulsion systems, compressing build cycles and reallocating engineering talent toward battery integration and shore-power compatibility.
Growth Catalysts
- EU F-Gas Regulation:Tightening refrigerant standards for onboard HVAC systems is accelerating redesign contracts for climate architecture specialists across Mediterranean yards.
- Genoa-Viareggio cluster:Concentrated superyacht construction expertise in Italy's Ligurian-Tuscan corridor sustains artisanal build quality that commands premium positioning.
- Lithium-ion battery density improvements:Energy storage advances now enable 80-meter-plus vessels to operate silent anchoring modes, expanding hybrid-electric addressable market.
Market Restraints
- Naval architect scarcity:Talent rotation from commercial shipping into yacht design has tightened labor pools at Northern European fabrication facilities.
- Steel and aluminum price volatility:Primary metal input costs fluctuate with energy markets, squeezing margin predictability on fixed-price hull contracts.
- ISO 9001 certification backlog:Lloyd's Register inspection queue delays are extending delivery timelines for new yard market entrants.
Strategic Opportunities
- Caribbean charter fleet expansion:Underpenetrated demand for crewed hospitality operations is pulling newbuild orders toward shallow-draft, high-volume interior configurations.
- China MEE dual carbon goals:Domestic emissions mandates are creating regulatory tailwind for Asian-built hybrid propulsion systems in the 40-60 meter range.
- Shore-power infrastructure convergence:Integration of vessel battery systems with marina grid connections enables new revenue models for port operators.
Industry Challenges
- Hybrid system integration complexity:Synchronizing diesel generators with battery banks and electric motors requires rare electromechanical engineering expertise that yards struggle to staff.
- Composite certification timelines:Lloyd's Register approval processes for advanced carbon-fiber superstructures extend pre-production phases by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Market |
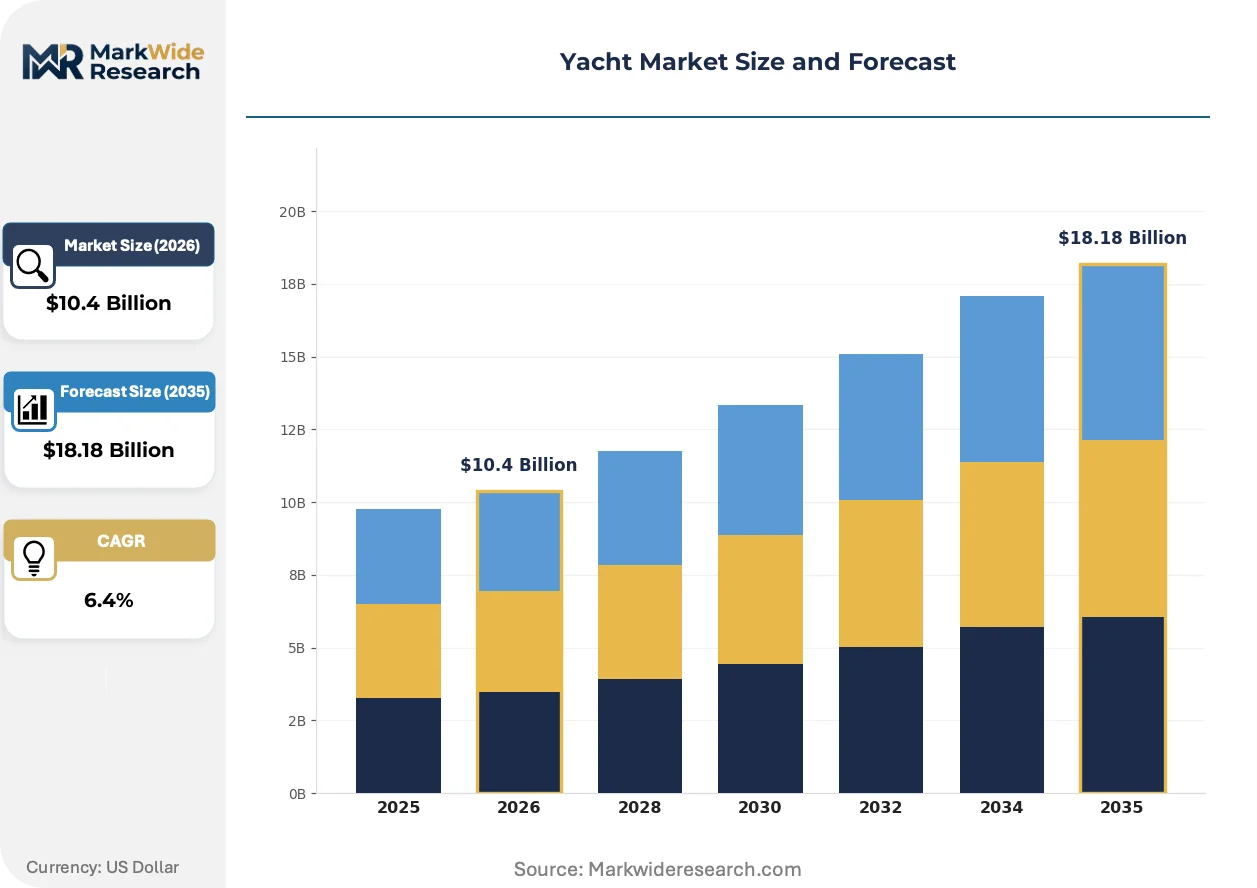
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sailing Yachts, Motor Yachts, Luxury Yachts, Catamarans Material: Fiberglass, Aluminum, Steel, Wood Size: Small Yachts, Medium Yachts, Large Yachts, Super Yachts End User: Individual Buyers, Charter Companies, Brokers, Marinas |
| Companies Covered | Amels, Damen Yachting, Lürssen, Vitters Shipyard, Oceanco, Feadship, Admiral Yachts, Fincantieri, Benetti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Market Emerging Trajectories
Propulsion technology divergence is splitting the market between conventional diesel-electric stalwarts and battery-forward architectures, with regulatory pressure accelerating the transition timeline for hulls above 500 gross tons.
Hybrid-electric propulsion is fragmenting the superyacht segment into distinct technical tiers. Battery-dominant architectures now enable silent operation at anchor for 12-18 hours, a capability that charter operators in the Mediterranean are specifying as standard. This technical divergence is compressing resale values for conventional diesel-only vessels while creating premium pricing power for yards with certified hybrid integration capabilities.
The EU F-Gas Regulation is mandating refrigerant phase-downs for onboard climate systems, forcing HVAC redesigns across all newbuilds above 24 meters. Shipyards are responding by qualifying alternative refrigerant suppliers and redesigning ducting architectures to accommodate lower-GWP compounds. Italian and Dutch facilities face the steepest compliance curves given their concentration of superyacht output.
Charter-driven procurement is displacing pure owner-commissioned builds in the 40-80 meter segment. Fleet operators now specify standardized interior platforms with modular cabin configurations, compressing design cycles and shifting margin capture toward post-delivery outfitting services. This pattern is most visible in Caribbean-focused builds, where high utilization rates justify faster depreciation schedules and more frequent refit cycles.
Yacht Market Segmentation
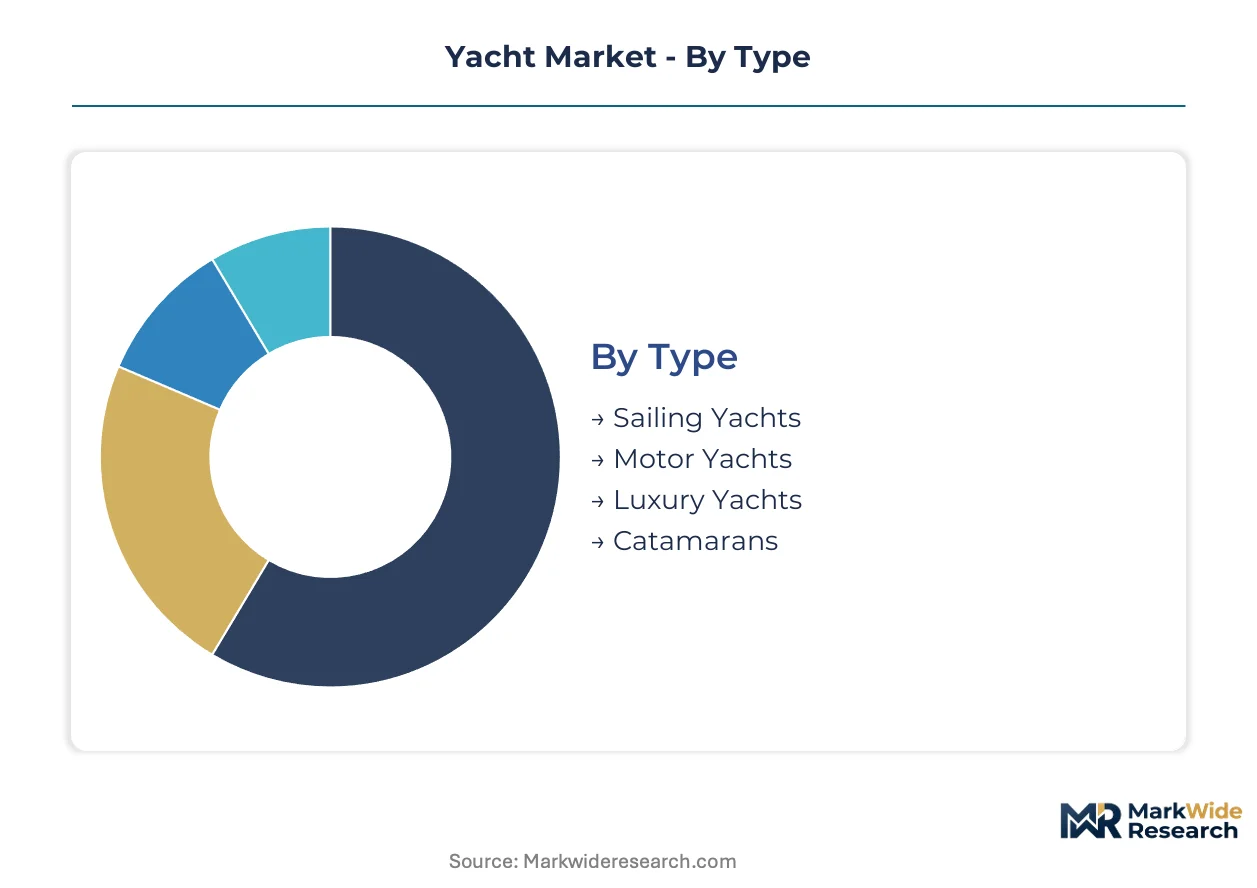
Segmentation in yacht manufacturing governs build complexity, certification pathways, and margin capture. Each dimension—propulsion type, hull material, length class, and buyer category—triggers distinct regulatory obligations and engineering resource allocations.
Type:
EU Green Deal emissions tiers and MARPOL Annex VI compliance thresholds split propulsion architectures into divergent regulatory buckets, with certification costs scaling nonlinearly across categories.
- Motor Yachts:Diesel-electric and hybrid propulsion systems dominate this segment, with hull forms optimized for interior volume and range. Demand concentrates in Mediterranean charter fleets where EU F-Gas Regulation compliance for onboard HVAC systems adds certification overhead. Steel and aluminum hulls above 500 gross tons face steepening emissions monitoring requirements.
- Sailing Yachts:Wind-driven propulsion with auxiliary diesel-electric power trains attracts purist owners seeking performance credentials. Italian yards in Viareggio and Dutch facilities in the Netherlands sustain artisanal build quality for this narrower niche. Regulatory burden lightens on sailing vessels under certain tonnage thresholds, though ISO 9001 certification remains mandatory.
- Luxury Yachts:Custom commissions above 80 meters with crewed hospitality operations and extended ocean cruising capability.
- Catamarans:Twin-hull configurations prioritizing stability and shallow-draft access for Caribbean and Southeast Asian cruising grounds.
Established volume favors Motor Yachts; emerging adoption favors Catamarans.
Material:
Primary metal and composite selection determines Lloyd's Register inspection protocols, welding qualification requirements, and supplier base geography.
- Steel:High-tensile marine grades enable hull structures above 60 meters with superior fatigue resistance. German and Dutch yards maintain in-house fabrication capability, though steel price volatility squeezes margin predictability on fixed-price contracts. Lloyd's Register certification for steel superstructures follows established timelines.
- Aluminum:Lightweight alloys reduce displacement for performance-oriented designs, particularly in 40-80 meter hybrid-electric vessels where battery mass penalties demand weight savings. Italian facilities in Genoa specialize in aluminum welding for Mediterranean builds. EU F-Gas Regulation compliance adds HVAC redesign costs regardless of hull material.
- Fiberglass:Standardized hull platforms dominate production below 24 meters, compressing build cycles through mold reuse.
- Wood:Traditional cold-molded and plank-on-frame construction persists in heritage restorations and bespoke commissions.
Steel and aluminum command premium positioning in superyacht construction; fiberglass leads volume production at smaller scales.
Size:
Length thresholds trigger stepped regulatory obligations, crew certification requirements, and marina infrastructure compatibility constraints.
- Super Yachts:Vessels exceeding 80 meters with complex hybrid-electric propulsion, extended range, and full crewed hospitality operations. Oceanco and Lürssen compete on technical integration in this segment. EU Green Deal emissions standards force battery-dominant architectures for new commissions.
- Large Yachts:60-80 meter hulls where diesel-electric stalwarts still hold resale value, though hybrid retrofit demand is climbing. Charter operators in the Caribbean specify modular interior platforms for high-utilization fleets. China MEE dual carbon goals are creating regulatory tailwind for Asian-built vessels in this range.
- Medium Yachts:24-60 meter vessels spanning owner-operated and lightly crewed configurations.
- Small Yachts:Below 24 meters where fiberglass construction and standardized platforms reduce build cycles and price points.
Super Yachts capture deepest margin pools; Large Yachts show steepest expansion trajectory from charter-driven procurement.
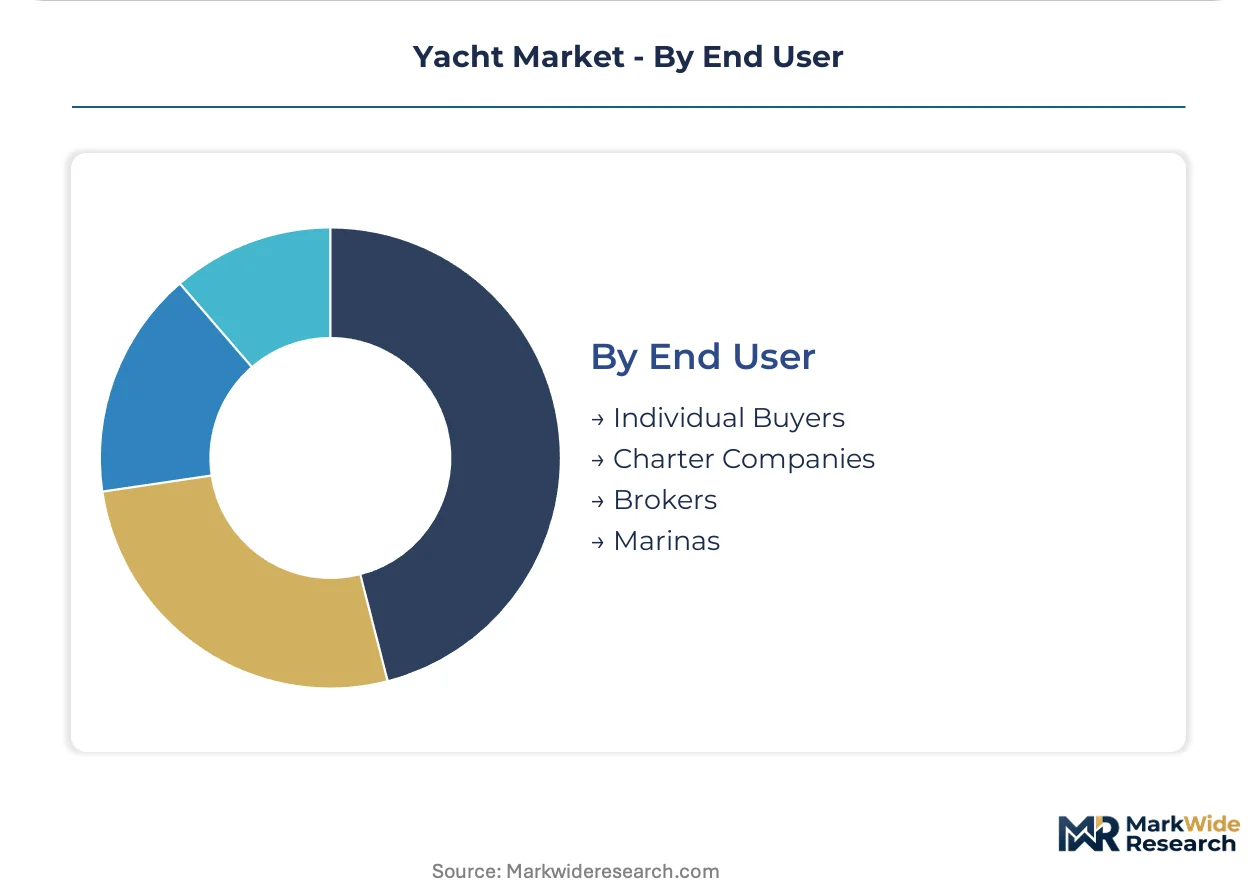
End User:
Buyer category determines specification flexibility, delivery timeline tolerance, and post-delivery service revenue potential.
- Charter Companies:Fleet operators demand standardized interior platforms with modular cabin configurations, compressing design cycles. Caribbean-focused builds prioritize shallow draft and high-volume interiors for crewed hospitality operations. High utilization rates justify faster depreciation schedules and more frequent refit cycles.
- Individual Buyers:Owner-commissioned builds retain specification flexibility, with Dutch and Italian yards competing on artisanal customization. Feadship leverages heritage positioning for this clientele. Delivery timelines extend when owners demand unique technical features or exotic materials.
- Brokers:Intermediary channels influence specification trends through resale market intelligence and buyer matching.
- Marinas:Infrastructure operators are emerging as stakeholders through shore-power integration requirements and berth allocation for hybrid vessels.
Charter Companies are displacing pure owner-commissioned builds in the 40-80 meter segment; Individual Buyers sustain premium pricing at the custom superyacht tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Mediterranean owner-operators prioritizing extended cruising range and Caribbean charter fleets demanding shallow-draft, high-volume configurations for crewed hospitality operations.
Italy
Genoa and Viareggio anchor superyacht construction with artisanal build quality commanding premium positioning. EU F-Gas Regulation mandates refrigerant phase-downs for onboard HVAC systems, accelerating redesign contracts across Ligurian-Tuscan yards. The Genoa-Viareggio cluster sustains concentrated expertise in aluminum welding and custom steel fabrication for vessels above 80 meters.
Germany
Lürssen anchors engineering credibility through in-house steel fabrication for complex hybrid-electric propulsion systems. The EU Green Deal emissions standards force battery-dominant architectures for new commissions above 500 gross tons. Northern German facilities face tightening labor pools as naval architecture talent rotates from commercial shipping into yacht design.
Netherlands
Feadship leverages Dutch heritage to sustain artisanal build quality across owner-commissioned custom commissions. ISO 9001 and Lloyd's Register certification frameworks govern build quality and insurance eligibility, creating gating factors for yard market access. Dutch facilities specialize in electromechanical engineering expertise for hybrid system integration.
United States
Caribbean-focused builds pull procurement toward shallow-draft, high-volume interior configurations for charter fleet expansion. Shore-power infrastructure convergence enables new revenue models for Florida and Caribbean port operators. US-based fleet operators specify standardized interior platforms with modular cabin configurations to compress design cycles.
China
Domestic MEE dual carbon goals create regulatory tailwind for Asian-built hybrid propulsion systems in the 40-60 meter range. Chinese facilities compete on technical complexity for battery integration and shore-power compatibility. Regulatory divergence between European and Asian compliance regimes reshapes build-location decisions for export-oriented commissions.
Yacht Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium custom yards commanding pricing power through certified hybrid capabilities while volume producers compete on standardized platform efficiency. The vendor base separates into three archetypes: heritage Dutch and Italian builders with artisanal positioning, German engineering-focused fabricators with in-house steel capability, and emerging Asian specialists leveraging regulatory tailwinds for mid-size hybrid vessels. Competitive moves concentrate on M&A for electromechanical engineering talent and strategic partnerships for battery supplier qualification.
Within the heritage custom tier, Feadship and Lürssen exemplify divergent geographic positioning strategies, with the former anchoring Dutch artisanal reputation and the latter representing German engineering credibility through captive fabrication. Oceanco occupies a position within the technical complexity archetype, specializing in hybrid-electric architectures for vessels above 80 meters. These three entities collectively illustrate how certification depth and regulatory anticipation separate premium-tier competitors from mid-market challengers.
| Leading Market Players |
|---|
| Amels |
| Damen Yachting |
| Lürssen |
| Vitters Shipyard |
| Oceanco |
| Feadship |
| Admiral Yachts |
| Fincantieri |
| Benetti |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month delivery timelines for custom superyacht commissions compress pricing power toward yards with certified hybrid capabilities, while steel and aluminum inventory cycles at Northern European fabricators amplify margin volatility on fixed-price hull contracts. This lead-time structure concentrates premium capture among Dutch and Italian builders with Lloyd's Register queue priority, forcing mid-tier competitors toward standardized platform efficiency.
Pricing Analysis
Long-term offtake contracts dominate superyacht procurement, with owner-commissioned builds locking steel and aluminum pricing at contract signature while charter fleet orders favor fixed-price agreements with modular interior options. Price differentiation separates ISO 9001-certified hybrid yards from uncertified competitors, with EU F-Gas Regulation compliance adding HVAC redesign premiums. Pricing pressure stems from lithium-ion battery cost volatility squeezing hybrid system margins. Charter companies exhibit highest price sensitivity due to faster depreciation schedules, while individual buyers tolerate premium positioning for artisanal customization.
Supply Chain Analysis
Strait of Gibraltar transit constraints for oversized hull sections from Northern European yards to Mediterranean outfitters amplify logistics risk for 80-meter-plus vessels. Supply concentration centers on Italy, Germany, and the Netherlands for steel fabrication and electromechanical integration, with China emerging for 40-60 meter hybrid propulsion systems. Raw material dependencies span marine-grade steel, aluminum alloys, and high-density lithium-ion cells. Single-source vulnerability sits with German in-house steel mills and Dutch battery integration specialists. Distribution runs through Lloyd's Register-certified shipyard networks with direct owner or charter fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shore-power infrastructure convergence is transforming yacht marinas into platform ecosystems where vessel battery systems interoperate with port grid connections, creating new revenue models that extend beyond traditional build-and-deliver economics.
For Market Incumbents: Secure electromechanical engineering talent through targeted acquisition of battery integration specialists, as hybrid system complexity outpaces organic staffing capabilities. Lock inshore-power certification partnerships with Mediterranean and Caribbean port operators to defend against Asian entrants leveraging MEE regulatory tailwinds. Priority lever rests on backward integration into lithium-ion cell qualification to reduce supplier concentration risk. For New Entrants and Emerging Players: Anchor in the 40-60 meter hybrid segment where Chinese yards face lower certification barriers and EU F-Gas Regulation compliance costs have not yet fully transferred to buyer pricing. Target Caribbean charter fleet operators specifying shallow-draft, high-volume configurations with modular interior platforms. Go-to-market angle emphasizes shore-power compatibility as standard specification, reducing operator fuel cost exposure. For Investors and Strategic Acquirers: Carve-out targets emerge from commercial shipping conglomerates with dormant yacht divisions and stranded naval architecture talent pools. Long-term viability hinges on regulatory anticipation capacity rather than build-cycle efficiency alone. Acquisition archetype: mid-size Italian or Dutch facilities with Lloyd's Register queue priority and unfilled hybrid certification capacity. Signal to watch: EU Green Deal emissions tier acceleration forcing premature diesel-electric fleet obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Certification Investment | Lloyd's Register approval for battery-dominant architectures above 80 meters unlocks premium charter pricing power. |
| Shore-Power Infrastructure Partnership | Marina grid integration agreements in Florida and the Caribbean enable recurring revenue beyond vessel delivery. |
| Naval Architecture Talent Acquisition | Recruitment from commercial shipping yards addresses electromechanical engineering scarcity at Northern European facilities. |
| Modular Interior Platform Standardization | Fleet operator specifications for Caribbean charter vessels compress design cycles and shift margin to outfitting services. |
| Alternative Refrigerant Supplier Qualification | EU F-Gas Regulation compliance for HVAC systems requires redesign contracts with lower-GWP compound specialists. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with yacht builders, charter fleet operators, and marina infrastructure developers, alongside secondary validation through Lloyd's Register certification records, EU F-Gas Regulation compliance filings, and customs data on steel and aluminum imports. Shipyard executives, naval architects, and port authority planning officers provided build-cycle and procurement intelligence. Secondary sources encompassed ISO 9001 audit disclosures, MEE dual carbon policy documents, and Mediterranean marina development permits. Bottom-up vessel delivery tallies triangulated against top-down market value estimates.
Across the projection horizon, the analytical framework modeled segmentation by propulsion architecture, hull material, length class, and buyer category, with regional regulatory clusters as an overlay dimension. CAGRs derived from build-order backlogs, fleet replacement cycles, and emissions compliance phase-in schedules. Forecast inputs incorporated lithium-ion battery density improvement curves and EU Green Deal enforcement trajectory assumptions.
Material uncertainties — steel and aluminum price volatility, Lloyd's Register inspection queue extensions, and regulatory divergence between European and Asian compliance regimes — sit outside the modeled envelope. Forecasts reflect documented assumptions on hybrid adoption rates and charter fleet expansion patterns. Practitioners should keep alternative scenarios live as shore-power infrastructure deployment and battery supplier qualification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Marine Trailers Market