
 Motorhome Market | 2026-2036
Motorhome Market Size, Share, and Industry Trends Forecast 2026-2036
Motorhome Market Intelligence
Indiana's RV manufacturing corridor is expanding production capacity to meet sustained order backlogs. Thor Motor Coach leverages its Elkhart-based assembly footprint to control component flow and shorten lead times. Forest River anchors its competitive stance through diversified brand architecture spanning entry-level to luxury price points. Jayco sustains market presence with specialized fiberglass construction techniques that reduce weight and improve fuel efficiency.
A motorhome is a self-propelled recreational vehicle integrating living quarters with a vehicle chassis, typically featuring sleeping accommodations, kitchen facilities, and bathroom systems within a unit ranging from twenty to forty-five feet in length. Manufacturers construct these vehicles on cutaway van, truck, or dedicated motorhome chassis platforms using aluminum framing, laminated sidewalls, and composite roofing to balance durability against gross vehicle weight ratings. Class A motorhomes dominate margin pools due to premium pricing and extensive customization options, while Class B camper vans represent the fastest-growing structural segment as urban buyers prioritize maneuverability and multi-use functionality. Diesel powertrains retain leadership in the over-thirty-five-foot category where torque requirements and towing capacity determine purchase decisions.
The Environmental Protection Agency and National Highway Traffic Safety Administration enforce emissions and safety standards that dictate engine specifications, braking systems, and structural integrity requirements for motorhomes sold in the United States. The Federal Communications Commission governs onboard telecommunications and entertainment systems, affecting connectivity package design and aftermarket installation protocols. Stakeholders must monitor evolving zero-emission powertrain regulations and charging infrastructure deployment timelines as these factors will determine competitive positioning and capital allocation priorities across the manufacturing base.
Market Dynamics
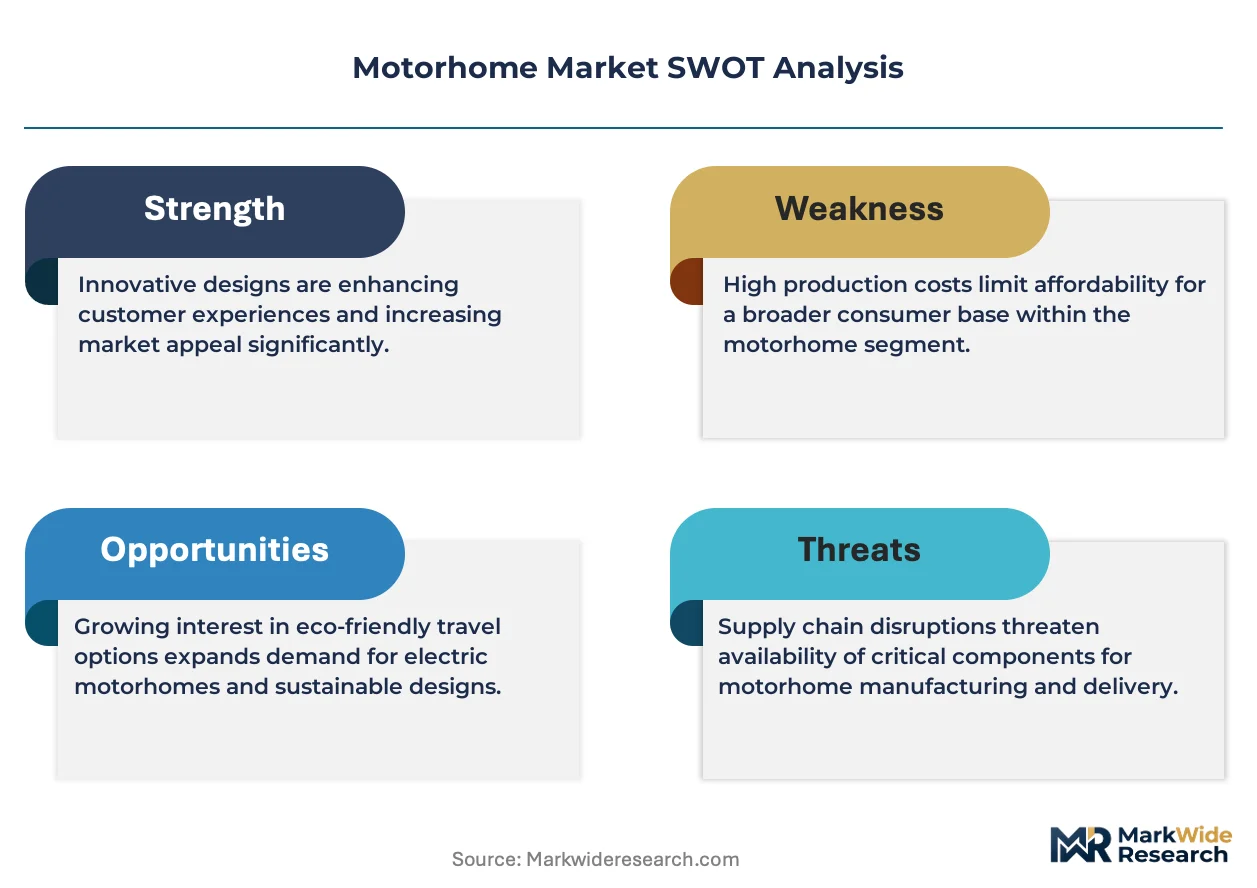
Zero-emission powertrain mandates from the EPA and NHTSA are compressing development timelines across the motorhome manufacturing base, forcing chassis suppliers and body builders to synchronize electrification roadmaps or risk model-year obsolescence.
Growth Catalysts
- Remote-work infrastructure:Employers in technology and professional services have normalized location-independent employment, expanding the addressable buyer pool beyond traditional retiree demographics.
- IRA clean vehicle credits:Federal tax incentives for commercial zero-emission vehicles reduce total cost of ownership calculations for fleet operators and rental agencies evaluating electric motorhome deployments.
- Sun Belt seasonal migration:Arizona, Florida, and Texas sustain year-round utilization rates that justify ownership economics compared to regions with weather-limited camping seasons.
Market Restraints
- Lithium-ion supply concentration:Battery cell production concentrates in China and South Korea, exposing motorhome manufacturers to raw material price volatility and geopolitical supply disruptions.
- GVWR certification bottlenecks:NHTSA vehicle classification protocols create multi-month homologation delays for new chassis architectures, extending time-to-market for redesigned platforms.
- Site-built lodging substitution:Short-term rental platforms and boutique hospitality developments compete for discretionary travel spending among younger buyer cohorts.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway exhibit low motorhome ownership density relative to camping participation rates, presenting whitespace for compact, thermally efficient product lines.
- Vehicle-to-grid integration:Bidirectional charging capabilities position motorhomes as mobile power assets, opening revenue streams from grid services and emergency backup contracts.
- Subscription-based access models:Peer-to-peer rental platforms and manufacturer-operated membership fleets reduce capital barriers for occasional users while generating recurring revenue.
Industry Challenges
- Electrification skill gaps:Service networks lack sufficient technicians certified in high-voltage systems, constraining aftermarket support capacity for battery-electric motorhomes.
- Multi-system integration complexity:Coordinating HVAC, propulsion, and living-space electronics from disparate suppliers extends engineering validation cycles and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorhome Market |
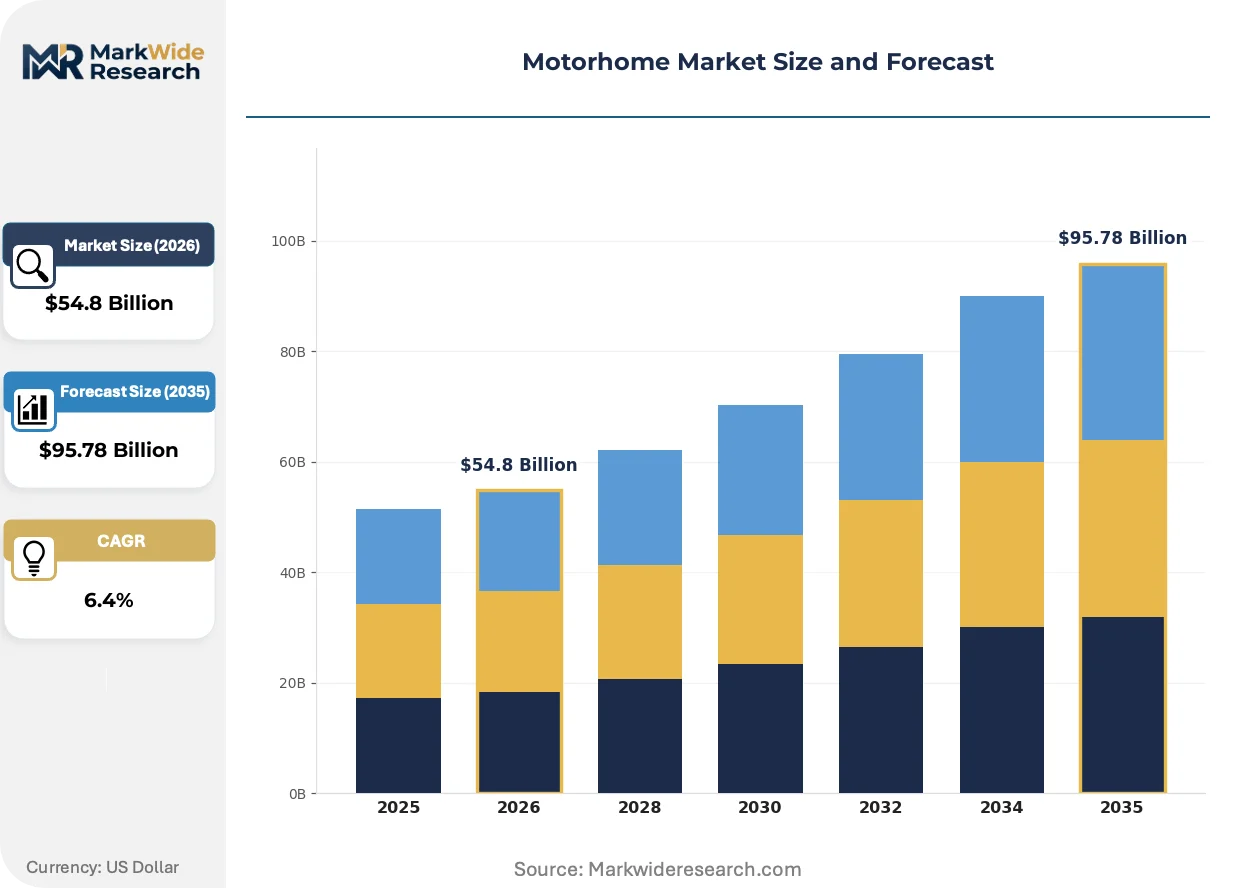
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $95.78 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class C, Camper Vans, Trailer Tents Powertrain: Diesel Engine, Gasoline Engine, Electric Motor, Hybrid System Application: Recreational Travel, Mobile Office, Temporary Living, Adventure Sports, Event Hosting Customer Type: Individual Owners, Rental Companies, Tour Operators, Corporate Clients, Custom Builders |
| Companies Covered | Jayco, Gulf Stream Coach, Thor Motor Coach, Grand Design, Tiffin, Newmar, Forest River, Airstream, Entegra Coach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorhome Market Strategic Shifts & Innovations
Active regulatory pressure and shifting buyer expectations are compressing traditional product development cycles, forcing manufacturers to prioritize modularity and software-defined features over hardware-locked configurations.
Composite monocoque construction is integrating laminated fiberglass and carbon-reinforced polymers to reduce curb weight by fifteen to twenty percent versus conventional aluminum framing. Fleet operators and fuel-conscious retail buyers are specifying these materials for Class B and compact Class C platforms. The technology is integrating chassis and body as a single stressed structure, eliminating redundant frame rails and expanding interior volumetric efficiency.
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are tightening CO2 limits for motorhome chassis above 8,500 pounds GVWR through model year 2032. Engine manufacturers must deploy advanced aftertreatment systems and cylinder deactivation technologies to maintain compliance without sacrificing torque output. The over-thirty-five-foot diesel segment faces the steepest engineering investment requirements, with some suppliers accelerating hybrid-electric development to bridge regulatory gaps.
Direct-to-consumer configuration tools are displacing traditional dealer-led specification processes, particularly among digitally native buyer segments. Manufacturers are deploying immersive 3D visualization platforms that transmit build-to-order requests directly to Elkhart-area assembly plants. This channel compression is most advanced in the United States, where Thor and Forest River have invested in configure-price-quote infrastructure that bypasses traditional inventory-heavy distribution models.
Motorhome Market Segmentation
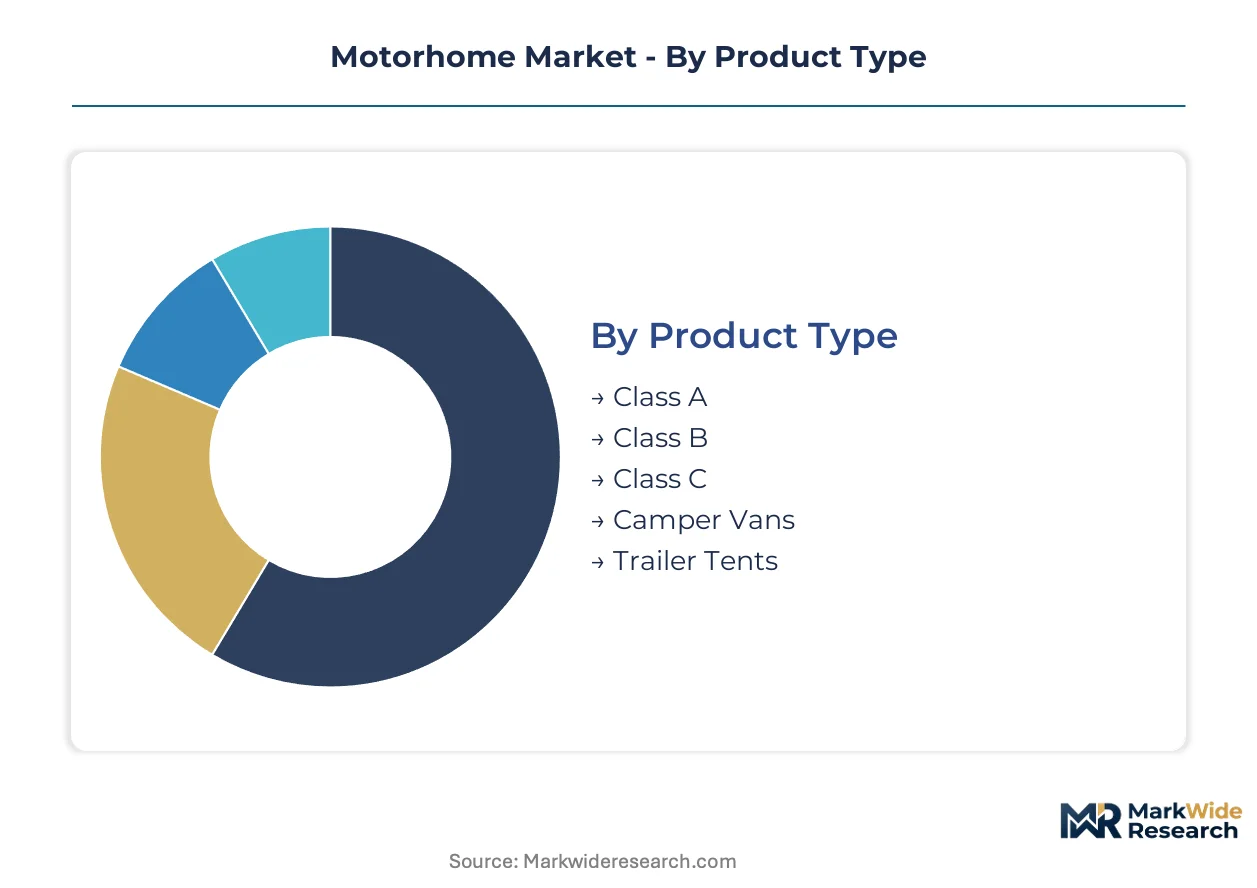
Structural segmentation in the motorhome market reveals how chassis architecture, propulsion systems, and usage patterns create distinct margin pools and service requirements. Buyers select across these dimensions based on trip duration, parking constraints, and energy infrastructure access.
Product Type:
Chassis construction and body integration methods define operational capabilities, fuel efficiency, and manufacturing cost structures across the product spectrum.
- Class A:Built on dedicated motorhome chassis with bus-style construction, these units integrate aluminum or steel framing with fiberglass exteriors. Sun Belt retirees in Arizona and Florida dominate demand, drawn by residential-scale amenities and extended-season occupancy. EPA Phase 3 emissions compliance is driving diesel powertrain upgrades in the over-35-foot category.
- Class B:Van-conversion platforms using cutaway chassis from Ford, Mercedes-Benz, and Ram. Urban remote workers prioritize these for garageability and daily drivability. The segment is expanding most quickly as digital employment normalizes location-independent lifestyles.
- Class C:Cab-over profiles built on truck or van cutaway chassis with distinctive sleeping areas above the cab. Family buyers favor these for value-engineered sleeping capacity and towing capability.
- Camper Vans:Compact conversions emphasizing stealth camping and fuel economy. Younger buyers in coastal metropolitan areas specify these for weekend recreation and dispersed camping access.
- Trailer Tents:Lightweight towable units that expand into enclosed sleeping quarters. Entry-price sensitivity and storage convenience sustain this category among occasional users.
Class A leads on scale; Class B leads on momentum.
Powertrain:
Propulsion technology selection determines range, torque availability, refueling infrastructure requirements, and regulatory compliance pathways.
- Diesel Engine:Compression-ignition architectures deliver high torque for heavy Class A platforms and mountain-grade towing. Buyers operating above 8,500 pounds GVWR specify these for thermal efficiency and durability under sustained load.
- Gasoline Engine:Spark-ignition powertrains dominate Class C and entry-level Class A production due to lower upfront cost and simpler maintenance protocols. Ford's Triton and Godzilla V8 platforms anchor this segment.
- Electric Motor:Battery-electric configurations are emerging in Class B and compact Class C formats where range requirements align with charging infrastructure density. NHTSA certification timelines and lithium supply concentration constrain near-term volume.
- Hybrid System:Parallel and series-hybrid architectures bridge regulatory gaps for over-35-foot platforms facing EPA Phase 3 CO2 limits. Torque supplementation from electric motors preserves towing performance while reducing emissions.
Diesel dominates heavy-duty applications; electric configurations are gaining share fastest in urban-accessible segments.
Application:
Usage intensity and duration patterns determine specification priorities for durability, connectivity, and climate control systems.
- Recreational Travel:Seasonal vacation use with intermittent occupancy drives demand for rapid setup systems and residential-style amenities. Sun Belt migration patterns concentrate ownership in Texas, Florida, and Arizona.
- Mobile Office:Sustained occupancy with professional connectivity requirements. Remote workers specify redundant internet, ergonomic workstations, and sound dampening for video conferencing.
- Temporary Living:Extended-stay deployment during home construction, disaster recovery, or seasonal work assignments. Durability and insulation specifications exceed recreational norms.
- Adventure Sports:Off-grid access for mountain biking, climbing, and water sports. Ground clearance, four-wheel-drive chassis, and gear storage systems differentiate these builds.
- Event Hosting:Mobile hospitality for weddings, corporate retreats, and festival accommodation. Rental operators and tour companies specify premium finishes and expandable entertaining spaces.
Recreational travel anchors volume; mobile office applications show steepest expansion trajectory.
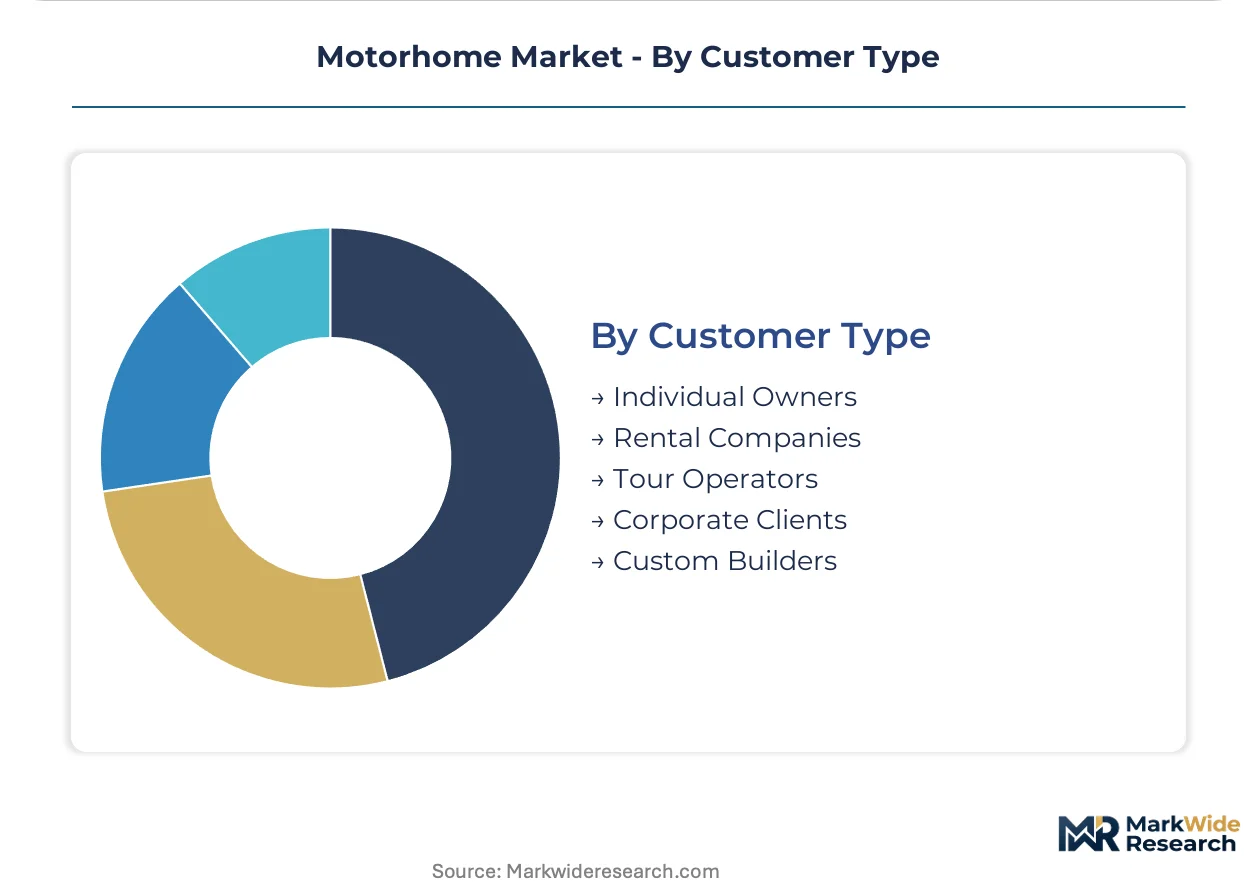
Customer Type:
Procurement scale and specification authority vary dramatically across buyer categories, shaping distribution channel design and warranty terms.
- Individual Owners:Retail purchasers selecting for personal use with high involvement in configuration decisions. Direct-to-consumer digital tools are displacing traditional dealer-led specification processes.
- Rental Companies:Fleet operators prioritizing durability, standardized maintenance protocols, and rapid turnaround. IRA clean vehicle credits reduce total cost of ownership for electric platform evaluations.
- Tour Operators:Guided experience providers specifying branded interiors and centralized fleet management systems. Seasonal utilization rates in Nordic markets and Sun Belt states justify capital deployment.
- Corporate Clients:Mobile marketing, executive transport, and remote site management applications. Custom upfitting and telematics integration dominate procurement criteria.
- Custom Builders:Specialist converters sourcing bare chassis for bespoke interior architecture. Elkhart-area suppliers control component flow for this fragmented demand channel.
Individual owners represent the largest addressable base; rental companies are scaling fastest as subscription access models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit regulatory-arbitrage opportunities as EPA emissions standards tighten faster than European equivalents, shifting component sourcing toward jurisdictions with phased compliance timelines. Production capacity concentrates where chassis homologation pathways remain most permissive.
United States
Retiree migration patterns and remote-work normalization sustain demand across Arizona, Florida, and Texas. NHTSA vehicle classification protocols govern chassis certification above 8,500 pounds GVWR. Elkhart, Indiana anchors manufacturing with synchronized component flows from regional suppliers.
Germany
Adventure tourism and alpine camping sustain premium motorhome specification. KBA homologation requirements enforce braking and structural standards distinct from US protocols. Baden-Württemberg hosts specialized chassis converters serving Nordic export markets.
Sweden
Low ownership density relative to camping participation creates whitespace for compact, thermally efficient platforms. REACH chemical regulations constrain interior material selection for export-bound production. Jönköping County clusters specialist converters targeting Arctic climate durability.
China
Domestic tourism recovery and dispersed camping policy liberalization expand addressable demand. MIIT new-energy vehicle mandates accelerate electric chassis development for sub-6-meter platforms. Yangtze River Delta assemblers integrate battery supply chains from regional cell manufacturers.
Australia
Remote-work migration from capital cities sustains caravan and motorhome order backlogs. ADR design rules govern rollover protection and occupant safety distinct from European or US frameworks. Queensland manufacturing corridors specialize in off-grid power integration for Outback deployment.
Motorhome Market Key Industry Players
US producers anchor the high-volume tier; European specialists hold premium-positioning segments. The vendor base stratifies across three tiers: integrated chassis-body builders, brand-architecture conglomerates, and specialist converters. Strategic archetypes include full-line manufacturers spanning entry to luxury price points, regional champions with climate-specific engineering, and fleet-focused rental suppliers. Competitive moves concentrate on electrification partnerships and direct-to-consumer configuration platforms.
Within the brand-architecture tier, Thor Motor Coach, Forest River, and Jayco exemplify scale-driven market presence. Thor Motor Coach leverages Elkhart-based assembly integration. Forest River diversifies across price-positioned marques. Jayco occupies a position emphasizing construction-method differentiation. These entities represent the dominant competitive archetype in North American volume production.
| Leading Market Players |
|---|
| Jayco |
| Gulf Stream Coach |
| Thor Motor Coach |
| Grand Design |
| Tiffin |
| Newmar |
| Forest River |
| Airstream |
| Entegra Coach |
| Others |
Cost & Logistics Intelligence
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles gate qualified chassis supply and premium-tier pricing access for manufacturers serving the over-35-foot diesel segment. Compliance investments in advanced aftertreatment systems and cylinder deactivation technologies concentrate cost burdens on Class A platforms, compressing margins for builders lacking backward integration into powertrain sourcing. Buyers seeking zero-emission alternatives face lithium-ion supply concentration that amplifies price premiums for battery-electric configurations.
Pricing Analysis
Distributor margins and dealer markups layer atop manufacturer invoice pricing, with direct-to-consumer configuration tools compressing this stack for digitally native buyer segments. Three-tier pricing structure across premium, standard, and economy levels separates full-custom Class A builds from value-engineered Class C platforms and entry-level camper van conversions. Price differentiation hinges on chassis GVWR certification tier and interior material grade, with EPA emissions compliance costs intensifying pressure on heavy-duty diesel offerings. Fleet rental operators exhibit lowest price sensitivity due to IRA clean vehicle credit offsets, while occasional-use individual buyers in coastal metropolitan areas drive hardest bargain on compact Class B units.
Supply Chain Analysis
Dual-sourcing mandates from NHTSA-aligned fleet operators require chassis builders to qualify multiple battery cell suppliers, complicating procurement for electric platform development. Manufacturing concentration in Indiana's Elkhart corridor, South Korea's cell production bases, and China's lithium refining capacity creates geographic dependency chains for critical inputs. Raw material exposure runs through lithium carbonate, steel framing alloys, and fiberglass resin systems, with tariff exposure on Chinese-sourced battery components representing the dominant structural risk. Distribution runs through manufacturer-owned regional service centers, independent dealership networks, and emerging peer-to-peer rental platforms that displace traditional inventory-heavy models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on composite monocoque construction methods that reduce curb weight and material input costs while enabling premium positioning through fuel-efficiency claims.
For Market Incumbents: Anticipate EPA Phase 3 compliance deadlines by accelerating hybrid-electric development partnerships with chassis suppliers, locking in powertrain roadmaps before model-year obsolescence risks materialize. Defend position by deepening backward integration into laminated fiberglass and carbon-reinforced polymer sourcing, capturing the 15-20 percent weight reduction premium that fleet operators now specify. Channel control investments in direct-to-consumer configuration platforms will determine which builders retain specification authority as dealer-led processes erode. For New Entrants and Emerging Players: Begin with thermally efficient compact platforms targeting Sweden and Norway, where low motorhome ownership density relative to camping participation rates creates whitespace unguarded by established brand architecture. Nordic buyers prioritize Arctic climate durability and stealth camping capability, specifications that favor specialist converters over full-line manufacturers with standardized US-centric designs. A subscription-based access model partnership with regional rental aggregators accelerates brand recognition without capital-intensive dealership network buildout. For Investors and Strategic Acquirers: Roll-up economics work for regional specialist converters with climate-specific engineering capabilities because fragmented ownership across Jönköping County, Baden-Württemberg, and Queensland manufacturing corridors prevents scale-driven procurement leverage. Target acquisition archetypes include compact-platform specialists with proven vehicle-to-grid integration prototypes and established service technician certification programs for high-voltage systems. The signal to watch is NHTSA homologation timeline compression for new chassis architectures, which would elevate the scarcity value of existing certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Lithium cell offtake contracts with South Korean producers anchor electric Class B production scaling. |
| Direct-to-Consumer Launch | Immersive 3D configuration platforms bypass dealer inventory models and compress order-to-delivery cycles. |
| Charging Infrastructure Partnership | Vehicle-to-grid integration agreements with utility operators unlock grid services revenue for bidirectional-capable motorhomes. |
| Backward Integration into Composites | In-house production of laminated fiberglass monocoque structures captures weight-reduction premiums and insulates margin from resin price volatility. |
| Geographic Manufacturing Footprint | Elkhart-based assembly expansion synchronizes component flow from regional suppliers to meet sustained order backlogs. |
Research Approach
Bottom-up remote-worker and retiree buyer segment modeling reconciled against top-down chassis production tracking forms the analytical core of this study. Primary interviews with motorhome platform engineers, fleet procurement directors at rental operators, NHTSA certification specialists, Elkhart-area component suppliers, and Sun Belt dealership principals combined with secondary validation against EPA emissions filings, NHTSA vehicle classification databases, IRA credit utilization records, and IHS Markit registration data. Triangulation across these sources ensures demand-side assumptions align with supply-side capacity constraints.
Historical trendline analysis of Class A, B, and C production volumes established baseline growth patterns across the projection horizon. The analytical framework models segmentation across chassis architecture, propulsion system, application intensity, and customer procurement scale, with CAGRs derived from regression against macroeconomic indicators and regulatory compliance timelines. Industry-specific forecast inputs include lithium-ion cell price trajectories, NHTSA homologation queue lengths, and Sun Belt seasonal migration pattern stability.
Several conditions sit outside the modeled scope, including unannounced EPA rulemaking beyond Phase 3, geopolitical disruption of lithium supply corridors, and abrupt shifts in employer remote-work policies. Forecasts reflect documented assumptions regarding charging infrastructure deployment density and technician certification program scaling. Deviation in NHTSA vehicle classification protocol timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
United States Luxury Yacht Market