
 North America Motorhome Market | 2026-2036
North America Motorhome Market Size, Share, and Industry Trends Forecast 2026-2036
North America Motorhome Market Insights
Digital nomads is rotating toward Class B van conversions as remote work normalizes mobile office configurations. Thor Industries leverages vertical integration across chassis supply and interior assembly to protect margin pools. Winnebago Industries anchors its position through R&D intensity in lithium-compatible electrical architectures. Forest River competes on manufacturing scale, operating multiple production facilities across Indiana and Oregon to match regional demand patterns.
A motorhome constitutes a self-propelled recreational vehicle built on a motorized chassis, integrating living quarters with drivetrain systems and typically offering sleeping capacity for two to eight occupants alongside kitchen, bathroom, and climate control functions. Class A units dominate value pools through premium pricing and full-time residential capability, while Class B segments attract the fastest expansion among digital nomad and solo traveler cohorts seeking fuel efficiency and urban maneuverability. Solar power and lithium-ion battery technology segments are deepening as buyers demand off-grid autonomy independent of campground hookups.
NHTSA governs vehicle safety standards including brake performance and structural integrity for motorhomes operating on US highways, while EPA tailpipe emissions rules shape engine and alternative-fuel strategies for manufacturers. The US Department of Transportation enforces weight classification protocols that determine licensing requirements and interstate access for heavier Class A platforms. Stakeholders must monitor evolving state-level zero-emission vehicle mandates and campground infrastructure electrification timelines to align product portfolios with emerging access restrictions and buyer expectations.
Market Dynamics
The North America motorhome market is contending with a fundamental chassis supply constraint that is compressing production schedules and forcing manufacturers toward captive aluminum fabrication partnerships. This supply-side pressure intersects with EPA Tier 4 Final emissions compliance timelines, creating a dual squeeze on engineering bandwidth and capital allocation.
Growth Catalysts
- Lithium-ion electrical architectures:Off-grid power systems are extending boondocking range for remote workers across Arizona and Utah corridor campgrounds.
- NHTSA brake performance mandates:Upgraded stopping requirements are accelerating disc-brake adoption across Class A diesel pusher platforms.
- Digital nomad cohort expansion:Remote employment normalization is rotating younger buyers toward compact Class B van conversions with cellular boosters and workstation modules.
Market Restraints
- Steel and aluminum price volatility:Raw material input swings are compressing gross margins for mid-tier Class C manufacturers without long-term supply agreements.
- Chassis supplier concentration:Ford and Mercedes-Benz Sprinter platforms dominate Class B underpinnings, creating single-source vulnerability for van conversion specialists.
- ICE drivetrain technical ceiling:Thermal efficiency limits in gasoline powertrains are constraining fuel economy gains for weight-intensive Class A units.
Strategic Opportunities
- Canadian prairie provinces:Saskatchewan and Manitoba exhibit underpenetrated dealer networks relative to comparable US state density metrics.
- Campground electrification tailwinds:Federal infrastructure spending on rural charging corridors is enabling battery-electric motorhome pilot programs.
- Solar-lithium convergence:Integrated rooftop PV with 48V battery banks is opening extended off-grid applications for dispersed camping on Bureau of Land Management territory.
Industry Challenges
- RVIA certification timeline compression:New electrical standards are extending product validation cycles by four to six months for manufacturers updating platform architectures.
- Skilled fiberglass technician scarcity:Mold fabrication and composite repair expertise is concentrating among retiring workers in northern Indiana production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Motorhome Market |
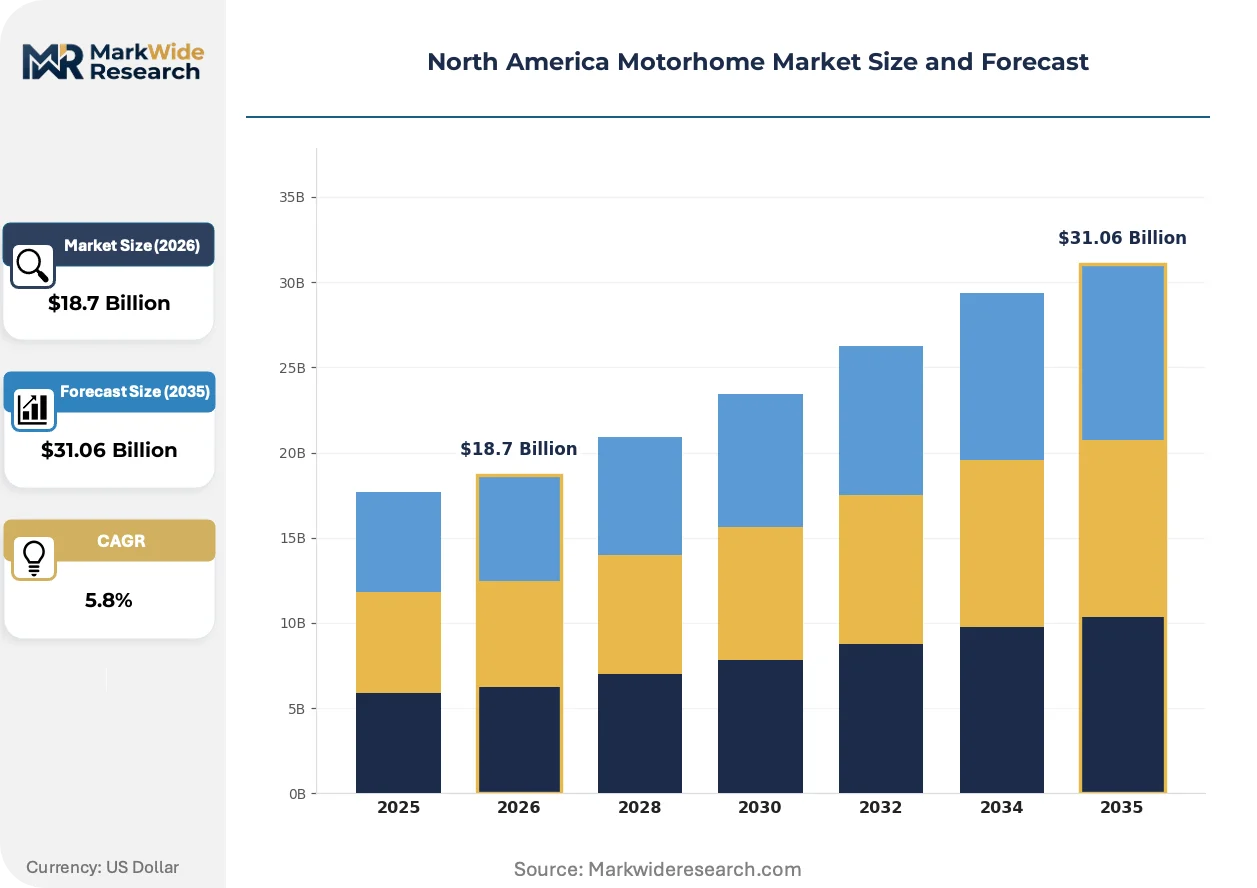
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class C, Truck Campers, Teardrop Trailers Technology: Solar Power, Lithium-Ion Batteries, GPS Navigation, Satellite Connectivity, Backup Cameras Application: Leisure Travel, Mobile Office, Seasonal Living, Adventure Sports, Long-Term Travel Customer Type: Retirees, Digital Nomads, Families, Solo Travelers, Rental Companies |
| Companies Covered | Thor Industries, Winnebago Industries, Forest River, REV Group, Tiffin Motorhomes, Newmar, Entegra Coach, Nexus RV, Gulf Stream Coach, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Motorhome Market Trends and Innovations
Electrification and connectivity are reconfiguring motorhome value propositions, shifting competitive advantage from floor plan innovation toward energy autonomy and mobile office functionality. Manufacturers are racing to integrate lithium-compatible systems ahead of infrastructure maturation.
Lithium iron phosphate battery packs are displacing traditional lead-acid house batteries across all three motorhome classes. Solo travelers and remote worker segments are adopting these systems fastest, with 48V architectures now standard in premium Class B builds. This chemistry shift is compressing generator runtime requirements and enabling multi-day off-grid occupancy without shore power hookups.
EPA Tier 4 Final emissions standards are forcing diesel engine redesigns with selective catalytic reduction and diesel exhaust fluid systems. Class A diesel pusher manufacturers are absorbing compliance costs through platform consolidation, reducing engine supplier diversity from three to two primary sources. The Southwest US full-time residential segment faces the steepest price adjustment as these powertrains dominate their towing and mountain-grade requirements.
Direct-to-consumer configuration tools are fragmenting traditional dealer channel control over option packaging. Younger buyers in coastal urban markets are specifying solar, lithium, and connectivity bundles online before contacting regional inventory holders. This pattern is most pronounced in Colorado and Pacific Northwest markets where van conversion specialists operate with minimal brick-and-mortar presence.
North America Motorhome Market Segmentation
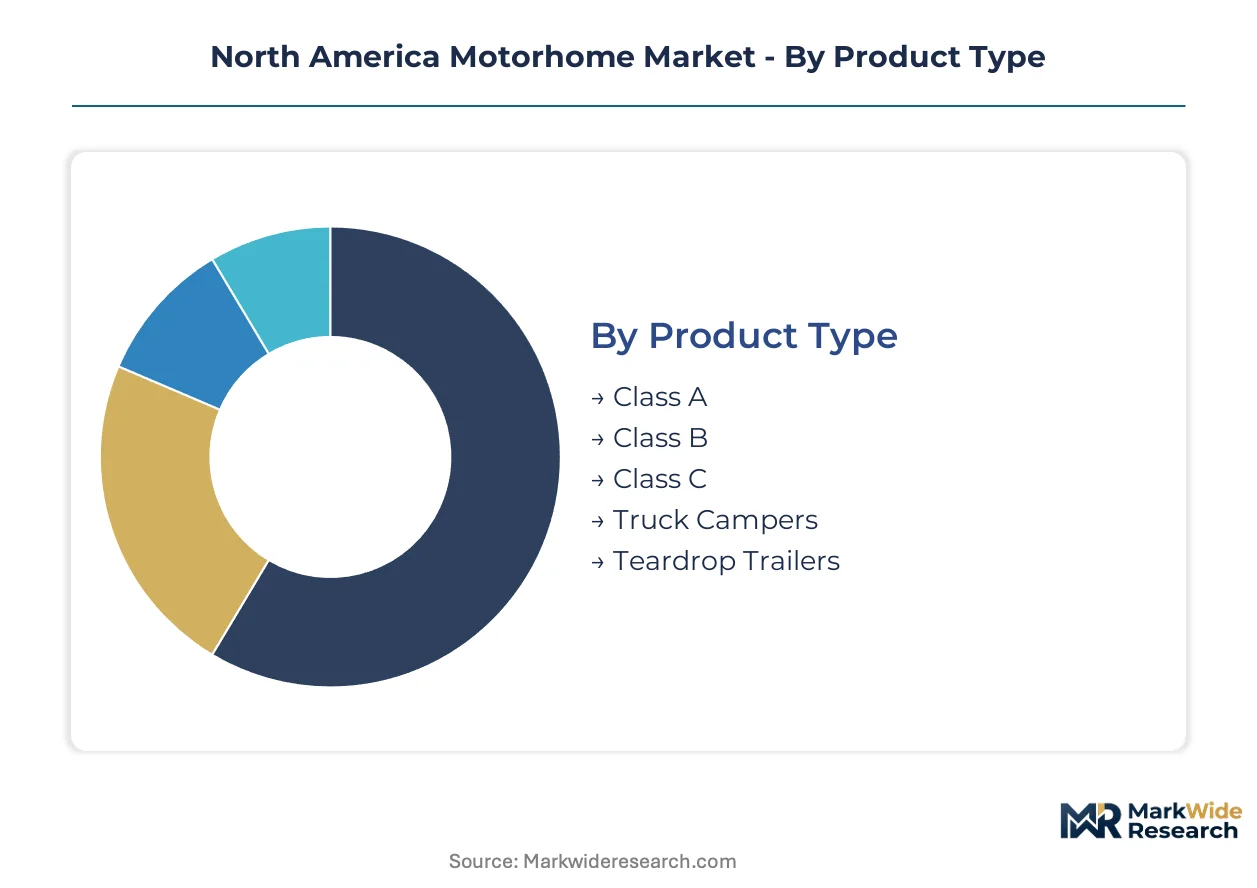
Segmentation in the North America motorhome market determines how manufacturers allocate chassis supply, electrical architecture R&D, and dealer channel investments across divergent buyer requirements. Each dimension reveals distinct margin profiles and infrastructure dependencies that shape competitive positioning.
Product Type:
Dealer networks in Arizona and Florida seasonal corridors stock heavier Class A and Class C inventories, while direct-to-consumer specialists in Colorado and Pacific Northwest urban markets push Class B van conversions through online configuration platforms.
- Class A:Built on commercial bus or truck chassis with integrated living quarters above the driver's cabin, these units command premium pricing through residential-scale floor plans and diesel pusher drivetrains. Demand concentrates among full-time retirees in southwestern US snowbird corridors where towing capacity and climate control systems face extreme thermal loads.
- Class B:Van conversions on Ford Transit or Mercedes-Benz Sprinter platforms maximize urban maneuverability and fuel efficiency for remote workers. Digital nomads in Denver, Portland, and Austin are rotating toward these configurations fastest, prioritizing lithium electrical systems and cellular boosters over traditional RV amenities.
- Class C:Distinctive overcab sleeping area built on cutaway van chassis offers mid-tier pricing with family-friendly capacity. Families in Midwest lake regions favor these for seasonal weekend use.
- Truck Campers:Slide-in units mounted on pickup beds enable off-road access to dispersed Bureau of Land Management camping. Adventure sports enthusiasts in Utah and Idaho backcountry drive this segment.
- Teardrop Trailers:Compact towable units without self-propulsion appeal to entry-level buyers seeking minimal investment. Solo travelers in Appalachian corridor state parks represent core demand.
Class A dominates installed base. Class B is where expansion concentrates.
Technology:
Cost tier stratification separates premium lithium-solar bundles from standard lead-acid configurations, with GPS and connectivity modules penetrating across all price levels as baseline expectations.
- Solar Power:Rooftop photovoltaic arrays integrated with charge controllers enable off-grid autonomy for boondocking on western public lands. Arizona and Utah campgrounds without electrical hookups are driving fastest uptake among remote worker segments seeking multi-day dispersed camping.
- Lithium-Ion Batteries:Lithium iron phosphate house battery banks displace lead-acid chemistry through superior depth-of-discharge tolerance and cycle life. Premium Class B builds in Pacific Northwest markets now specify 48V architectures as standard, compressing generator runtime requirements for mobile office configurations.
- GPS Navigation:RV-specific routing algorithms account for vehicle height, weight restrictions, and propane regulations. Rental companies operating cross-country fleets mandate these systems for liability reduction.
- Satellite Connectivity:Starlink and legacy geostationary systems enable broadband in remote corridors without cellular coverage. Long-term travelers in Montana and Wyoming backcountry prioritize these installations.
- Backup Cameras:Multi-camera surround-view systems address Class A rear visibility constraints. NHTSA safety mandates are accelerating adoption across diesel pusher platforms.
Solar-lithium bundles command premium pricing. Satellite connectivity is climbing the fastest as infrastructure-dependent remote work normalizes.
Application:
Volume concentration varies sharply by season, with leisure travel peaking in summer months while mobile office demand sustains year-round production scheduling for van conversion specialists.
- Leisure Travel:Traditional vacation use concentrated in national park corridors and coastal resort destinations. Families in Great Lakes states drive seasonal demand spikes.
- Mobile Office:Dedicated workstation modules with ergonomic seating and cellular amplification enable full-time remote employment from vehicle. Digital nomads are gaining share fastest in this application, particularly among tech workers in Colorado and California markets.
- Seasonal Living:Snowbird migration patterns between northern US states and Arizona or Florida establish predictable annual demand cycles. Retirees dominate this application with extended-stay campground commitments.
- Adventure Sports:Toy hauler configurations and enhanced ground clearance support mountain biking, climbing, and water sports access. Utah and British Columbia mountain towns anchor demand.
- Long-Term Travel:Extended continental exploration without fixed itinerary appeals to post-career cohorts with accumulated leave or retirement flexibility. Solo travelers in this category prioritize reliability and service network density.
Leisure travel dominates transaction volume. Mobile office is where expansion concentrates.
Customer Type:
Margin structure varies by customer sophistication, with rental companies extracting fleet discounts while digital nomads pay premiums for customized electrical and connectivity specifications.
- Retirees:Post-career buyers with accumulated home equity financing Class A diesel pushers for full-time residential use. Southwestern US snowbird corridors concentrate this cohort's seasonal purchasing decisions.
- Digital Nomads:Remote-employed professionals under 45 seeking mobility without career interruption. This segment is expanding most quickly, driving lithium battery and Starlink installation rates above market averages.
- Families:Multi-occupant units prioritizing sleeping capacity and kitchen functionality for weekend recreation. Midwest and southeastern US lake regions anchor demand.
- Solo Travelers:Single-occupant efficiency seekers minimizing fuel and maintenance costs. Compact Class B and teardrop configurations dominate this profile.
- Rental Companies:Fleet purchasers including Cruise America and regional operators specifying standardized configurations for maintenance efficiency. Their procurement concentrates in Indiana and California production facilities.
Retirees dominate installed base. Digital nomads are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retirees and remote workers concentrate demand in southwestern states and Florida seasonal corridors, while Canadian prairie provinces and Mexican manufacturing zones present divergent growth trajectories. The United States dominates transaction volume through established dealer networks and chassis supply infrastructure.
United States
Arizona and Florida anchor snowbird migration patterns that sustain Class A diesel pusher demand through predictable winter purchasing cycles. EPA Tier 4 Final emissions compliance timelines are compressing engineering schedules for manufacturers updating powertrain architectures. Northern Indiana production clusters around Elkhart and Goshen concentrate fiberglass mold fabrication and final assembly operations for Thor Industries and Forest River platforms.
Canada
Saskatchewan and Manitoba exhibit dealer network underpenetration relative to comparable US state density metrics, creating whitespace for regional distributors. Transport Canada vehicle safety standards align with NHTSA brake performance mandates while adding bilingual labeling requirements for Quebec market access. Alberta mountain corridor campgrounds near Banff and Jasper are driving lithium-solar bundle adoption among adventure tourism operators serving international visitors.
Mexico
Baja California and Sonora coastal corridors attract US retirees seeking lower-cost seasonal living alternatives to Arizona RV parks. Mexican federal highway infrastructure spending is expanding toll road capacity along the Transpeninsular Highway connecting Tijuana to Cabo San Lucas. Querétaro manufacturing zones host aluminum fabrication suppliers serving captive chassis partnerships with Indiana-based motorhome assemblers.
North America Motorhome Market Competitive Landscape
Player mix skews toward vertically integrated conglomerates controlling chassis supply and interior assembly through captive production networks. Three to four holding-company structures dominate volume manufacturing, while van conversion specialists fragment the Class B segment through direct-to-consumer configuration platforms. Competitive moves center on aluminum fabrication partnerships securing chassis allocation and lithium-compatible electrical architecture R&D racing ahead of infrastructure maturation.
Among Indiana-based diversified manufacturers, Thor Industries, Winnebago Industries, and Forest River exemplify distinct strategic archetypes. Thor Industries represents holding-company scale through multi-brand portfolio management across price tiers. Winnebago Industries occupies a position defined by R&D intensity in energy-autonomous platform development. Forest River anchors the manufacturing-throughput archetype through distributed production footprinting across multiple Midwest facilities. These three entities collectively structure competitive dynamics for chassis allocation, dealer network coverage, and electrical system specification standards.
| Leading Market Players |
|---|
| Thor Industries |
| Winnebago Industries |
| Forest River |
| REV Group |
| Tiffin Motorhomes |
| Newmar |
| Entegra Coach |
| Nexus RV |
| Gulf Stream Coach |
| Others |
Pricing and Supply Chain Analysis
Ninety-day chassis allocation windows now govern production scheduling across Indiana assembly clusters, compressing pricing power for Class B van conversion specialists while amplifying margin capture for manufacturers with captive aluminum fabrication partnerships. This lead-time rigidity intersects with EPA Tier 4 Final compliance costs to reshape how electrical architecture tiers command premium positioning.
Pricing Analysis
Lithium-compatible electrical architectures command three-generation pricing separation against lead-acid baseline configurations, with 48V house battery systems extracting substantial premiums over 12V legacy platforms. Three-tier pricing structure across premium lithium-solar bundles, mid-tier AGM configurations, and economy lead-acid setups differentiates primarily on off-grid autonomy duration and cycle life certification. Pricing pressure stems from steel and aluminum input volatility squeezing mid-tier Class C manufacturers without long-term supply agreements. Digital nomads exhibit lowest price sensitivity for connectivity and energy autonomy features, while family weekend buyers in Midwest lake regions drive hardest bargain on base vehicle cost.
Supply Chain Analysis
Indiana and Oregon anchor fiberglass mold fabrication and final motorhome assembly, while Querétaro manufacturing zones in Mexico supply captive aluminum chassis components to Indiana-based holding companies. Chassis supply draws from Ford Transit and Mercedes-Benz Sprinter platforms concentrated in US and German production networks, with lithium iron phosphate cells sourcing primarily from South Korean and Chinese battery specialists. Single-source vulnerability runs through Ford and Mercedes-Benz van platform concentration for Class B underpinnings. Distribution runs through Arizona and Florida seasonal corridor dealer networks for Class A and C inventory, while direct-to-consumer configuration platforms fragment Class B van conversion channels in Colorado and Pacific Northwest urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions compliance timelines and lithium-electrical convergence are disrupting competitive positioning faster than infrastructure maturation, creating asymmetric opportunity for energy-autonomous platform developers.
For Market Incumbents: Shield margin pools through backward integration into aluminum chassis fabrication partnerships that secure allocation priority during supply-constrained periods. Prioritize R&D bandwidth toward 48V lithium-compatible electrical architectures ahead of campground electrification infrastructure buildout, as NHTSA brake performance mandates accelerate platform consolidation costs that smaller competitors cannot absorb.
For New Entrants and Emerging Players: Differentiate on direct-to-consumer configuration platforms targeting digital nomad cohorts in Denver, Portland, and Austin with cellular-booster and workstation module bundles. White-space concentration sits in Saskatchewan and Manitoba dealer network underpenetration, where comparable US state density metrics suggest unmet demand for seasonal living configurations. Pursue van conversion specialization with minimal brick-and-mortar presence to bypass traditional dealer channel control over option packaging.
For Investors and Strategic Acquirers: Long-term, this sits as a electrification-transition play because lithium-solar convergence is displacing generator-dependent architectures faster than incumbent R&D cycles can adapt. Acquisition target archetype: van conversion specialists with established direct-to-consumer configuration platforms and lithium system integration expertise. Watch for federal infrastructure spending disbursement velocity on rural charging corridors as inflection indicator for battery-electric motorhome pilot program viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Fabrication Partnership | Secures chassis allocation priority during ninety-day supply windows compressing competitor production. |
| 48V Lithium Architecture R&D | Positions ahead of campground electrification timelines enabling multi-day Bureau of Land Management boondocking. |
| Direct-to-Consumer Configuration Platform | Fragments dealer channel control over option packaging in Colorado and Pacific Northwest urban markets. |
| Saskatchewan Dealer Network Expansion | Captures underpenetrated prairie province demand relative to comparable US state density metrics. |
| Starlink Integration Partnership | Addresses satellite connectivity demand climbing fastest among Montana and Wyoming backcountry long-term travelers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with motorhome platform engineers, chassis procurement directors, campground electrification planners, and RVIA certification specialists; and secondary validation against EPA emissions filings, NHTSA safety standard updates, SEC manufacturer disclosures, and campground infrastructure spending databases. Bottom-up unit economics triangulated against top-down regional demand modeling to anchor volume and value projections.
Across the analysis window, the forecast framework modeled motorhome segmentation by product class, electrical architecture generation, customer cohort, and regional corridor demand pattern. CAGRs derived from installed base replacement cycles, demographic cohort expansion rates, and technology substitution curves for lithium-solar systems against lead-acid baseline. Key inputs included chassis allocation lead-time observations, RVIA certification timeline compression effects, and federal infrastructure spending velocity on rural charging corridors.
The analysis sits within stated boundaries; outcomes outside EPA Tier 4 Final compliance timeline adherence, lithium cell supply continuity, or campground electrification infrastructure buildout rates would require recalibration. Forecasts reflect assumptions regarding digital nomad cohort expansion and retiree snowbird migration pattern stability. Recalibration cycles align with material shifts in NHTSA safety mandate timelines, raw material input volatility, and zero-emission vehicle mandate propagation across state-level jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market