
 Asia-Pacific Personal Watercraft Market | 2026-2036
Asia-Pacific Personal Watercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Personal Watercraft Market Outlook
A capital-intensity divergence between integrated engine manufacturers and assembly-dependent brands is bifurcating the competitive landscape. Yamaha Motor Co., Ltd. leverages its in-house marine engine foundries to control propulsion supply chains across Japan and Thailand. BRP Inc. (Sea-Doo) anchors its Asia-Pacific position through dedicated distribution infrastructure in Australia and localized hull fabrication. Kawasaki Heavy Industries, Ltd. differentiates via jet pump engineering depth inherited from industrial turbine operations.
Personal watercraft denote motorized vessels under four meters in length, propelled by an inboard jet drive drawing water through an intake grate and expelling it through a steerable nozzle at velocities exceeding 100 km/h, designed for recreational surface navigation in coastal and inland waterways. Sit-down configurations dominate volume across family-oriented buyers, while electric engine types capture margin expansion as harbor authorities restrict two-stroke emissions near marine reserves. Touristic end users in Thailand and Indonesia drive rental fleet turnover, whereas commercial operators in Japanese fishing cooperatives favor utility hull designs for nearshore patrol.
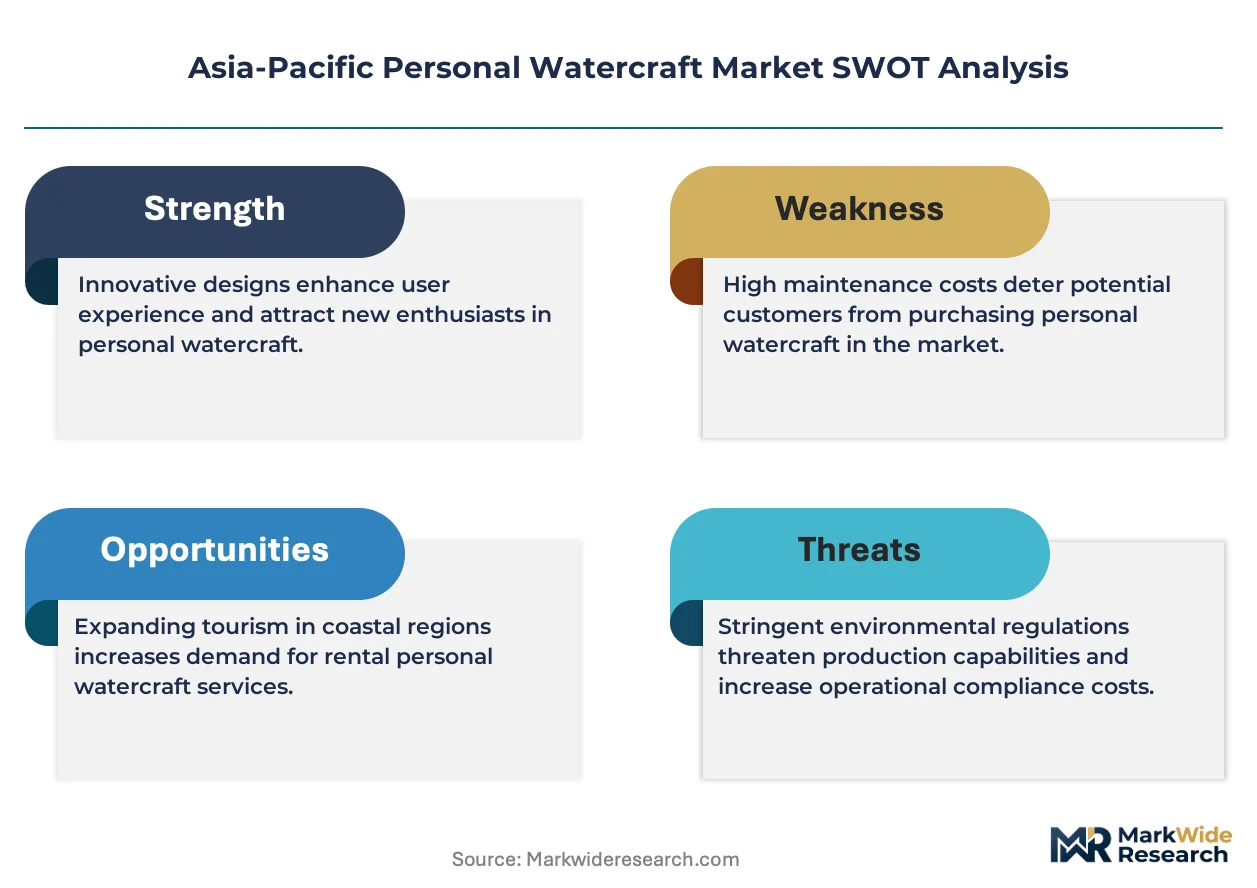
Japan's METI enforces marine engine emission benchmarks under its Small Vessel Safety Act, while Australia's AMSA implements design and construction standards for recreational craft operating in territorial waters. China's MIIT GB standards for outboard and inboard propulsion systems now require type approval for all imported personal watercraft, creating compliance barriers for non-certified manufacturers. Stakeholders must monitor regulatory divergence between Japan's technology-forcing standards and Southeast Asia's enforcement gaps when allocating product development resources.
Market Dynamics
China's MIIT emission mandates for marine propulsion systems are forcing certification redesigns across the supply base, while recreational tourism operators in Southeast Asia accelerate fleet procurement ahead of peak season demand windows.
Growth Catalysts
- Marine reserve buffer zones:Harbor authorities in Queensland and New South Wales are restricting two-stroke emissions near protected ecosystems, creating replacement demand for cleaner propulsion systems among commercial rental operators.
- Thailand's tourism infrastructure:Coastal provinces from Phuket to Krabi are expanding marina capacity to accommodate international visitor volume recovery, directly lifting personal watercraft procurement for guided tour fleets.
- GB standard harmonization:China's MIIT type-approval requirements for imported personal watercraft are consolidating supplier bases around certified manufacturers, reducing competitive fragmentation in premium segments.
Market Restraints
- Aluminum hull input volatility:Sheet aluminum prices fluctuate with energy-intensive smelting costs, compressing margin buffers for assembly-dependent brands without captive foundry operations.
- Jet pump engineering concentration:Specialized impeller machining capabilities cluster in Japanese industrial corridors, creating supply vulnerability for non-integrated manufacturers seeking component sourcing alternatives.
- Small Vessel Safety Act compliance:Japan's METI emission benchmarks require exhaust after-treatment systems that add unit cost and technical complexity for models targeting family recreational buyers.
Strategic Opportunities
- Indonesia's archipelago tourism:Underdeveloped rental infrastructure across Bali, Lombok, and Komodo corridor presents first-mover positioning for fleet-service business models targeting international resort partnerships.
- Electric propulsion convergence:Battery energy density improvements combined with brushless motor thermal management are opening harbor-restricted operating zones previously inaccessible to combustion-powered craft.
- AMSA construction standard alignment:Australia's design and construction standards for recreational craft create certification pathway advantages for manufacturers already compliant with Japanese or Chinese regulatory frameworks.
Industry Challenges
- Marine technician certification gaps:Jet pump diagnostics and composite hull repair skills remain scarce in Southeast Asian service networks, extending downtime for commercial rental operators and elevating total cost of ownership.
- Multi-jurisdiction type approval:Divergent emission testing protocols between Japan's METI, China's MIIT, and Australia's AMSA extend product launch timelines and fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Personal Watercraft Market |
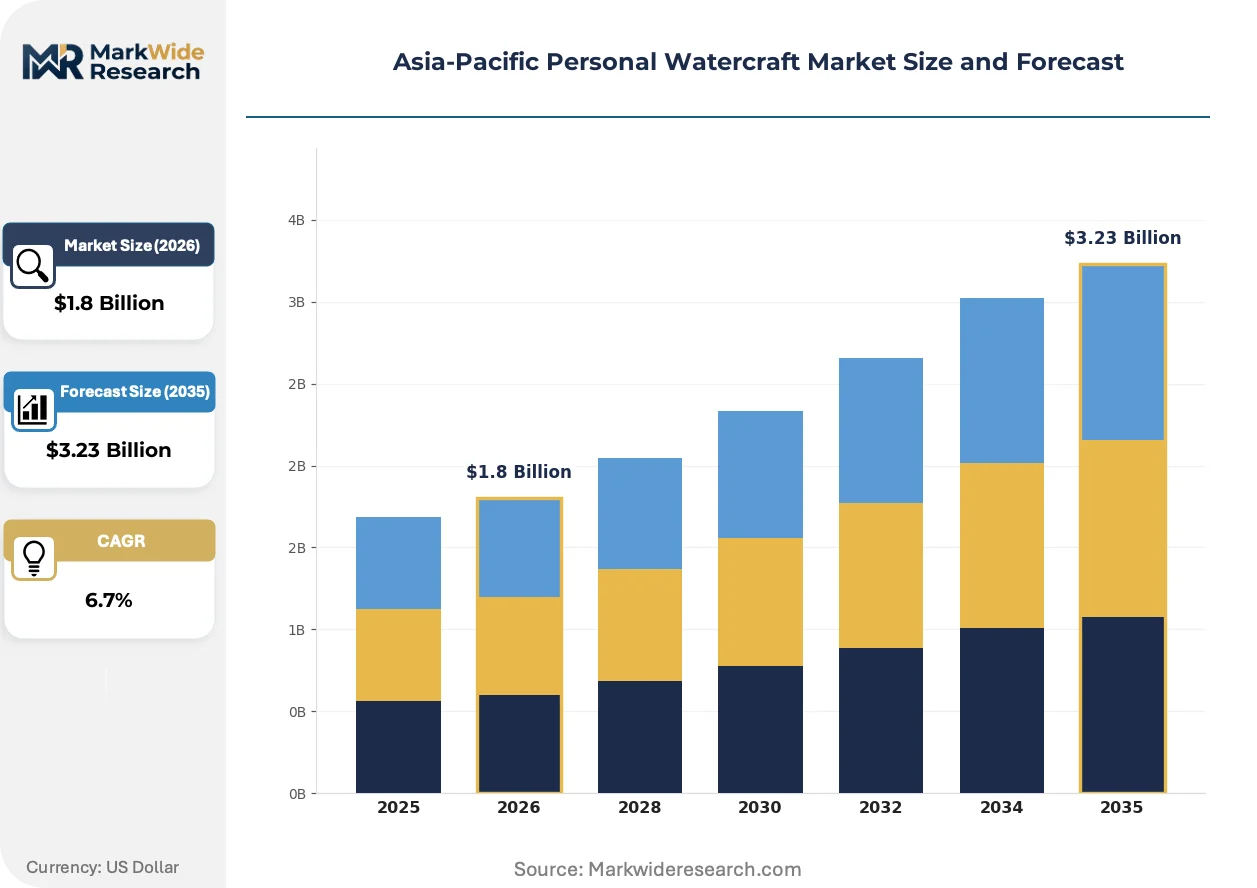
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up, Sit-Down, Sports, Utility Engine Type: Two-Stroke, Four-Stroke, Electric, Hybrid End User: Recreational, Commercial, Racing, Touristic Distribution Channel: Online, Dealerships, Rental Services, Exhibition |
| Companies Covered | BRP Inc. (Sea-Doo), Yamaha Motor Co., Ltd., Kawasaki Heavy Industries, Ltd., Polaris Inc., Honda Motor Co., Ltd., Taiga Motors, Belassi GmbH, Krash Industries, Narke, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Personal Watercraft Market Strategic Shifts
Propulsion system electrification is fragmenting traditional competitive advantages rooted in engine manufacturing scale, while regulatory divergence between Northeast Asian technology-forcing standards and Southeast Asian enforcement gaps creates strategic positioning tension.
Electric marine propulsion is fragmenting established market boundaries between personal watercraft and adjacent recreational vessel categories. Battery-electric systems with integrated thermal management are penetrating harbor-restricted operating zones near marine reserves in Queensland and New South Wales. Family-oriented buyers and commercial rental operators are adopting these platforms at accelerating pace, compressing the addressable market for conventional two-stroke powertrains in coastal tourism corridors.
China's MIIT GB standards for inboard propulsion systems are tightening certification requirements for all imported personal watercraft, creating compliance barriers for non-certified manufacturers. The industrial consequence is supplier base consolidation around entities with established type-approval capabilities and testing infrastructure. Premium and performance-oriented segments targeting Chinese coastal marinas are most affected, with distributors prioritizing inventory from pre-certified supply chains to avoid customs clearance delays.
Rental fleet procurement patterns are compressing traditional retail channel dominance in Southeast Asian markets. Tourism operators in Thailand and Indonesia are negotiating direct supply relationships with manufacturers, bypassing established dealer networks for volume procurement. This disintermediation is most visible in Phuket and Bali corridor marinas, where international resort chains are consolidating vendor relationships to standardize fleet specifications and service support.
Asia-Pacific Personal Watercraft Market Segmentation
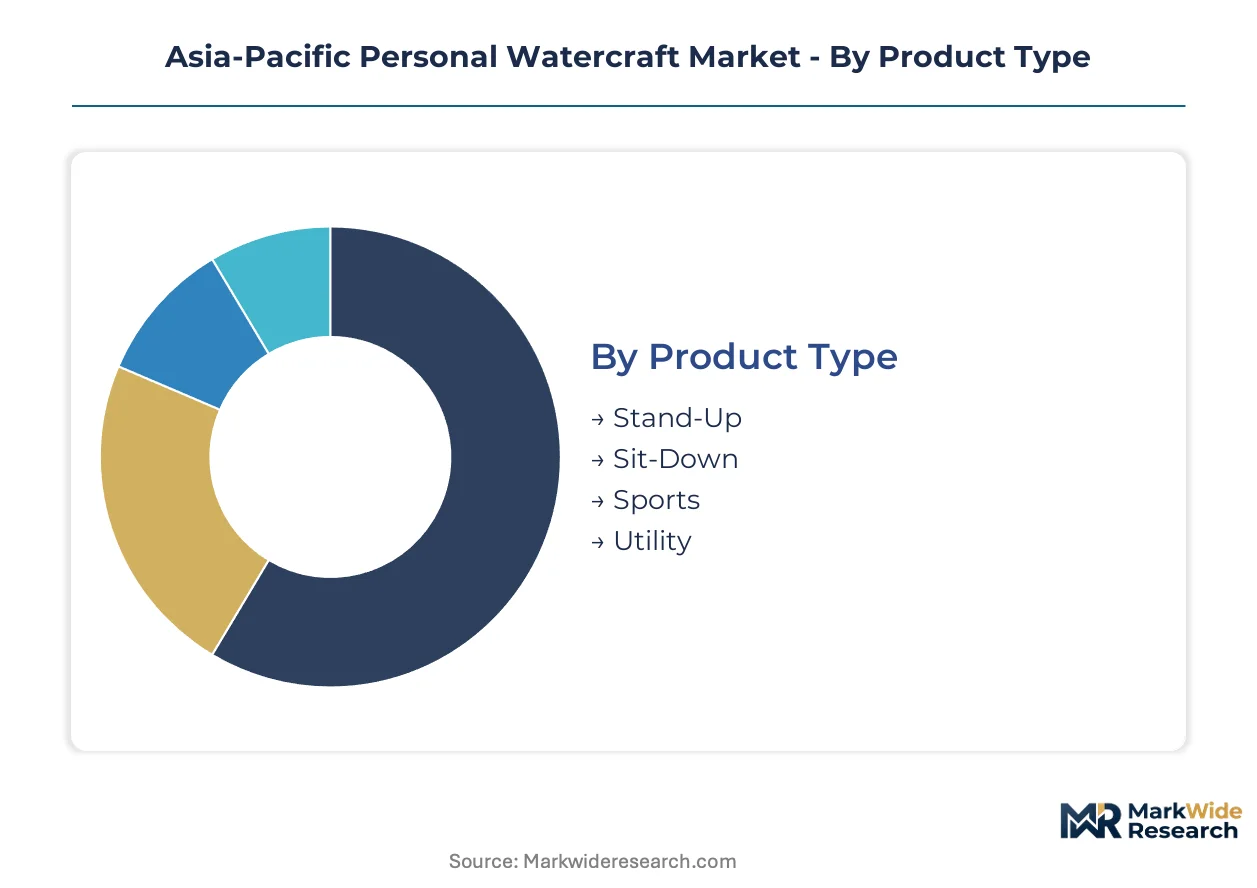
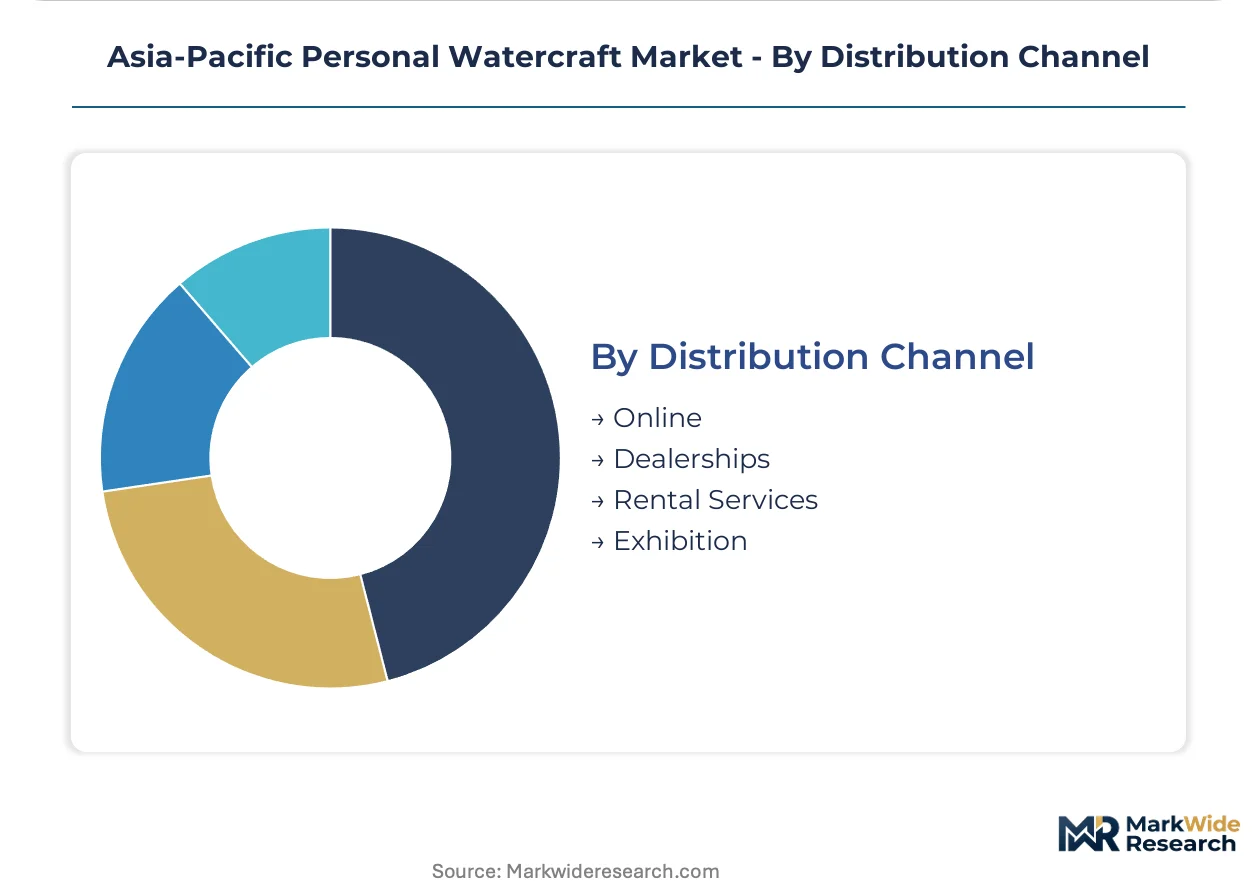
Channel configuration across Asia-Pacific personal watercraft distribution varies sharply by segment, with rental services capturing volume in touristic corridors while dealerships retain margin in premium recreational sales. Understanding these flow patterns enables manufacturers to align product development with procurement behavior.
Product Type:
Channel mix diverges by hull configuration, with sit-down models flowing through dealership networks for family buyers while stand-up units concentrate in rental fleet procurement for coastal tourism operators.
- Sit-Down:Enclosed hull designs with integrated seating for 2-3 passengers dominate family recreational procurement across Australia's Gold Coast marina clusters. Queensland leisure corridors drive replacement cycles as harbor authorities restrict two-stroke emissions near marine reserves.
- Stand-Up:Compact hulls with rider-operated handlebar steering and no seated accommodation target athletic users and commercial rental training fleets. Thailand's Phuket-to-Krabi tourism corridor accelerates fleet turnover for guided tour operations.
- Sports:Performance-tuned hull geometries with reinforced composite construction for high-speed maneuverability.
- Utility:Modified hull designs with expanded cargo capacity and stable platforms for nearshore patrol applications.
Sit-Down dominates installed base. Stand-Up is where expansion concentrates.
Engine Type:
Cost tier stratification separates premium four-stroke and electric systems from economy two-stroke platforms, with regulatory pressure reshaping the technology mix across Northeast Asian versus Southeast Asian markets.
- Four-Stroke:Inboard combustion engines with closed-loop fuel injection and catalytic after-treatment meeting Japan's METI emission benchmarks. Australia's AMSA construction standards create certification pathway advantages for compliant manufacturers targeting family buyers.
- Electric:Battery-electric propulsion with integrated thermal management and brushless DC motors opening harbor-restricted operating zones. Queensland and New South Wales marine reserve buffer zones displace conventional powertrains in coastal tourism corridors.
- Two-Stroke:Lightweight crankcase-compression engines facing phase-out pressure from China's MIIT GB standards for imported personal watercraft.
- Hybrid:Dual-mode systems combining combustion range with electric harbor maneuverability for specialized commercial applications.
Four-Stroke commands current revenue concentration. Electric is climbing the fastest as regulatory pressure intensifies.
End User:
Application-based segmentation reveals diverging procurement patterns, with touristic operators negotiating direct manufacturer relationships while recreational buyers remain anchored in traditional retail channels.
- Touristic:Fleet operators across Indonesia's Bali-Lombok-Komodo corridor procuring standardized specifications for international resort partnerships. Underdeveloped rental infrastructure creates first-mover positioning for volume suppliers.
- Recreational:Individual and family buyers in Japan's coastal prefectures prioritizing emission-compliant platforms under Small Vessel Safety Act requirements. METI benchmarks add unit cost and technical complexity for this price-sensitive segment.
- Commercial:Japanese fishing cooperatives and nearshore patrol services favoring utility hull designs with extended maintenance intervals.
- Racing:Organized competition circuits and performance enthusiasts driving demand for specialized sports configurations.
Recreational anchors historical volume. Touristic is gaining share fastest through fleet disintermediation.
Distribution Channel:
Customer-type concentration shapes channel viability, with rental services consolidating vendor relationships while exhibition channels capture high-consideration recreational purchases.
- Rental Services:Direct procurement relationships bypassing established dealer networks for volume fleet standardization. Phuket and Bali corridor marinas consolidate specifications to reduce service support complexity.
- Dealerships:Branded retail networks retaining premium recreational sales in Japan and Australia where after-sales service capability influences purchase decisions.
- Online:Digital configuration and ordering platforms penetrating accessory and parts replacement segments.
- Exhibition:Trade show and marina demonstration events capturing high-involvement buyers in premium product categories.
Dealerships retain margin concentration. Rental Services is where procurement volume is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australia's premium marina clusters while Southeast Asian tourism corridors compete on volume procurement terms. This asymmetry shapes manufacturer resource allocation between emission-compliant premium platforms and fleet-standardized economy configurations.
Australia
Queensland's Gold Coast and New South Wales leisure corridors drive replacement demand as harbor authorities restrict two-stroke emissions near marine reserves. AMSA construction standards for recreational craft create certification pathway advantages for pre-compliant manufacturers. Sydney and Melbourne marina clusters anchor premium retail channel dominance.
China
Coastal marina developments in Hainan and Guangdong provinces attract international tourism investment, lifting procurement for harbor-compatible electric platforms. MIIT GB standards for inboard propulsion systems require type approval for all imported personal watercraft. Qingdao and Xiamen yachting infrastructure concentrates distribution network expansion.
Japan
Family recreational buyers in coastal prefectures prioritize emission-compliant platforms under METI's Small Vessel Safety Act benchmarks. Exhaust after-treatment requirements add unit cost and technical complexity for domestic manufacturers. Tokyo Bay and Osaka Bay industrial corridors retain jet pump machining capability concentration.
Thailand
Phuket-to-Krabi tourism corridor accelerates fleet turnover for guided tour operations as international visitor volumes recover. Coastal provinces expand marina capacity to accommodate charter fleet procurement. Pattaya and Samui marina clusters consolidate direct manufacturer relationships bypassing traditional dealer networks.
Indonesia
Bali-Lombok-Komodo corridor presents first-mover positioning for fleet-service business models targeting international resort partnerships. Underdeveloped rental infrastructure creates procurement volume opportunities for standardized specifications. Jakarta and Surabaya distribution hubs service emerging commercial operator demand.
Asia-Pacific Personal Watercraft Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated engine manufacturers command supply chain control through captive foundry operations, while assembly-dependent brands compete on distribution reach and localized hull fabrication. Two strategic archetypes dominate: vertically integrated propulsion specialists and regional assembly-scale operators. Competitive moves concentrate on certification pre-positioning for MIIT and METI emission standards, plus direct fleet procurement relationships disintermediating dealer networks.
Among integrated marine propulsion manufacturers, Yamaha Motor Co., Ltd. and Kawasaki Heavy Industries, Ltd. exemplify the technology-forcing archetype with in-house engineering depth, while BRP Inc. (Sea-Doo) occupies a position spanning integrated design with regional assembly scale. These three anchors represent divergent approaches to regulatory compliance and channel strategy across the Asia-Pacific corridor.
| Leading Market Players |
|---|
| BRP Inc. (Sea-Doo) |
| Yamaha Motor Co., Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| Polaris Inc. |
| Honda Motor Co., Ltd. |
| Taiga Motors |
| Belassi GmbH |
| Krash Industries |
| Narke |
| Others |
Value Chain & Pricing Dynamics
Captive foundry utilization rates in Japan and Thailand determine propulsion system cost floors across the Asia-Pacific corridor, concentrating margin power with Yamaha Motor and Kawasaki Heavy Industries while assembly-dependent brands absorb aluminum sheet volatility. This scale asymmetry stratifies pricing power between integrated manufacturers and regional hull fabricators.
Pricing Analysis
Configured-to-order premium spreads of 15-25% separate emission-certified four-stroke platforms from standard two-stroke configurations in Australia's Gold Coast marina clusters. Three-tier pricing structure across premium, standard, and economy levels reflects METI certification grade, volume procurement scale, and after-sales service bundling. Cost compression in economy tiers is intensifying because China's MIIT GB standards force redesign expenditure for non-certified imports. Family recreational buyers in Japan demonstrate highest price sensitivity due to Small Vessel Safety Act compliance costs, while commercial rental operators in Thailand prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites logistics risk for aluminum sheet and composite resin flows into Southeast Asian assembly operations. Component concentration centers on Japan for jet pump machining, China for battery cell supply, and Thailand for hull fabrication. Raw material dependencies span marine-grade aluminum, carbon fiber reinforced polymers, and lithium-ion cells. Single-source vulnerability concentrates in Japanese industrial corridors for precision impeller manufacturing. Distribution runs through direct fleet procurement relationships disintermediating traditional dealer networks in Phuket and Bali corridor marinas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric propulsion platform economics are redefining competitive boundaries as battery-swapping interoperability emerges across Queensland and New South Wales harbor authorities, creating ecosystem lock-in opportunities for first-mover fleet operators.
For Market Incumbents: Shield premium positioning in Australia's AMSA-compliant marina clusters through accelerated certification pre-positioning for China's MIIT GB standards. Defensive consolidation should prioritize backward integration into battery thermal management systems to offset jet pump engineering concentration risk in Japanese supply corridors. Channel control through direct rental fleet relationships in Indonesia's Bali-Lombok-Komodo corridor protects against disintermediation. For New Entrants and Emerging Players: Differentiate on electric harbor-maneuverability platforms targeting Queensland marine reserve buffer zones where combustion restrictions create protected demand. White-space concentration sits in Indonesia's underdeveloped rental infrastructure and utility hull applications for Japanese fishing cooperatives. Fleet-service business models with standardized specifications offer the most penetrable go-to-market angle against established dealer networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-service operators with direct resort partnerships in Thailand and Indonesia, suggesting superior cash-flow quality versus retail-dependent distribution models. Long-term viability over the next decade hinges on regulatory alignment with technology-forcing emission standards across Northeast Asia. Acquisition targets should emphasize pre-certified supply chains and established type-approval infrastructure. The signal to watch is MIIT certification backlog duration as a proxy for competitive access to Chinese coastal marina developments.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Type-Approval Pre-Positioning | Secures customs clearance priority for Hainan and Guangdong marina procurement. |
| Direct Fleet Procurement Relationships | Bypasses dealer network fragmentation in Phuket and Bali corridors. |
| Battery Thermal Management Investment | Opens harbor-restricted operating zones in Queensland marine reserves. |
| Jet Pump Machining Capability Acquisition | Reduces single-source dependency on Japanese industrial corridors. |
| Resort Partnership Fleet Standardization | Locks in recurring revenue from Indonesia's archipelago tourism expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, AMSA construction standards documentation, and customs import records for personal watercraft across the analysis window. Interviews with marina fleet procurement managers, marine engine engineering directors, harbor authority compliance officers, and composite hull manufacturing plant managers inform demand-side validation. Secondary sources include METI emission benchmark publications, trade association fleet surveys, and manufacturer type-approval disclosures. Bottom-up unit shipment estimates triangulate against top-down tourism expenditure allocation models.
Segmentation dimensions modeled span hull configuration, propulsion architecture, end-use application, and distribution channel structure across the projection horizon. CAGRs derive from regression analysis against tourism arrival trajectories, regulatory phase-in schedules, and marina infrastructure investment pipelines. Industry-specific forecast inputs incorporate jet pump replacement cycle timing and battery energy density improvement curves for electric platform penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained tourism recovery in Southeast Asia, accelerated MIIT enforcement timelines, or aluminum price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding emission standard harmonization and fleet procurement pattern persistence. Specific risks that could revise projections include multi-jurisdiction type-approval protocol divergence and marine technician certification gap persistence in Indonesian service networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
North America Youth ATV and UTV Market