
 Light Car Trailer Market | 2026-2036
Light Car Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Light Car Trailer Market Intelligence
Aluminum-intensive chassis construction is narrowing the weight gap between steel and composite alternatives in light car trailer engineering. Aluma Ltd. leverages its dedicated aluminum fabrication focus to sustain premium positioning in the single-axle category. Felling Trailers, Inc. anchors its competitive stance through custom-configured open-deck designs for commercial transport buyers. Pace American, Inc. differentiates via controlled distribution networks spanning personal-use and rental channels.
A light car trailer constitutes a towed vehicle with gross vehicle weight rating below 3,500 pounds, typically manufactured with steel box-tube frames, aluminum skin panels, or molded composite floors, designed for hauling passenger vehicles, recreational equipment, or light cargo behind standard consumer automobiles. Enclosed trailer configurations command margin concentration due to weather protection premiums and customization complexity, while aluminum material adoption accelerates fastest among weight-sensitive personal-use buyers seeking improved fuel economy during towing. Double-axle designs occupy the structural center of commercial transport applications where load stability and braking redundancy justify higher acquisition costs.
The National Highway Traffic Safety Administration governs federal lighting, braking, and conspicuity standards that shape baseline safety equipment requirements, while state-level departments of transportation impose varying registration, width, and speed-limit rules that fragment market access protocols across jurisdictions. The Federal Motor Carrier Safety Administration additionally regulates commercial operators, creating dual compliance pathways that manufacturers must navigate. Stakeholders should monitor evolving electrified tow vehicle compatibility standards as battery-electric trucks enter the consumer and fleet mainstream.
Market Dynamics
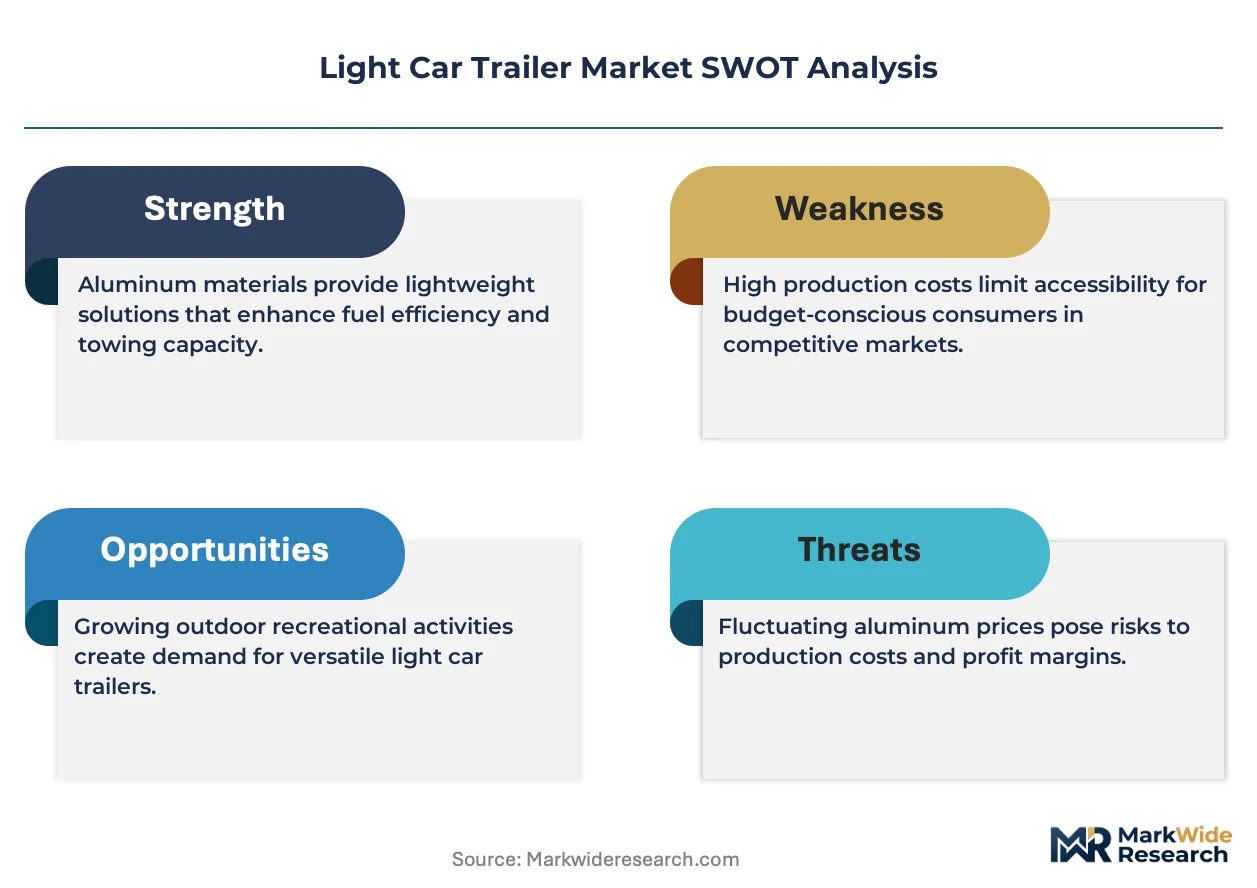
Aluminum-intensive chassis construction is compressing weight differentials against steel alternatives, forcing manufacturers to reposition on customization speed and configuration flexibility rather than material hierarchy alone.
Growth Catalysts
- Recreational Vehicle Towing Expansion:Sun Belt states from Florida to Arizona sustain elevated outdoor recreation participation rates, concentrating replacement-cycle demand among personal-use buyers seeking enclosed configurations for weather-sensitive cargo.
- Federal Motor Carrier Safety Administration Compliance Pathways:Dual regulatory tracks for commercial and consumer operators create specialized product lines, allowing manufacturers to capture premium pricing through purpose-built braking and lighting configurations.
- Electrified Tow Vehicle Compatibility:Battery-electric truck penetration into consumer and fleet segments is generating trailer-side power management requirements, opening specification windows for integrated charging and energy recovery systems.
Market Restraints
- Aluminum Input Cost Volatility:Primary aluminum pricing sensitivity on the London Metal Exchange transmits directly to chassis fabrication costs, compressing margin buffers for mid-tier producers without long-term supply agreements.
- State-Level Registration Fragmentation:Department of Transportation width limits, speed restrictions, and title transfer protocols vary across jurisdictions, elevating compliance overhead for interstate distribution networks.
- Composite Floor Substitution Threat:Molded polymer decking materials from specialized chemical processors are capturing share in corrosion-critical applications, displacing traditional aluminum skin panels in salt-exposure environments.
Strategic Opportunities
- Underpenetrated Mountain West Corridors:Colorado, Utah, and Idaho exhibit recreational vehicle density growth without proportional trailer service infrastructure, creating whitespace for mobile configuration and direct-to-consumer fulfillment models.
- Integrated Telematics Convergence:Combination of cellular connectivity modules with axle-mounted load sensors enables real-time tire pressure and brake temperature monitoring, differentiating premium offerings for commercial fleet operators.
- Rental Channel Expansion:Home improvement and equipment rental chains are consolidating trailer fleet ownership, shifting procurement toward standardized specifications with volume maintenance agreements.
Industry Challenges
- Aluminum Welding Certification Bottlenecks:American Welding Society qualification requirements for structural trailer fabrication create 12-18 month workforce development timelines, constraining production scaling for specialized manufacturers.
- Legacy Steel Inventory Integration:Remaining box-tube frame production lines require parallel tooling investments to accommodate aluminum extrusion profiles, elevating capital intensity during material transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Car Trailer Market |
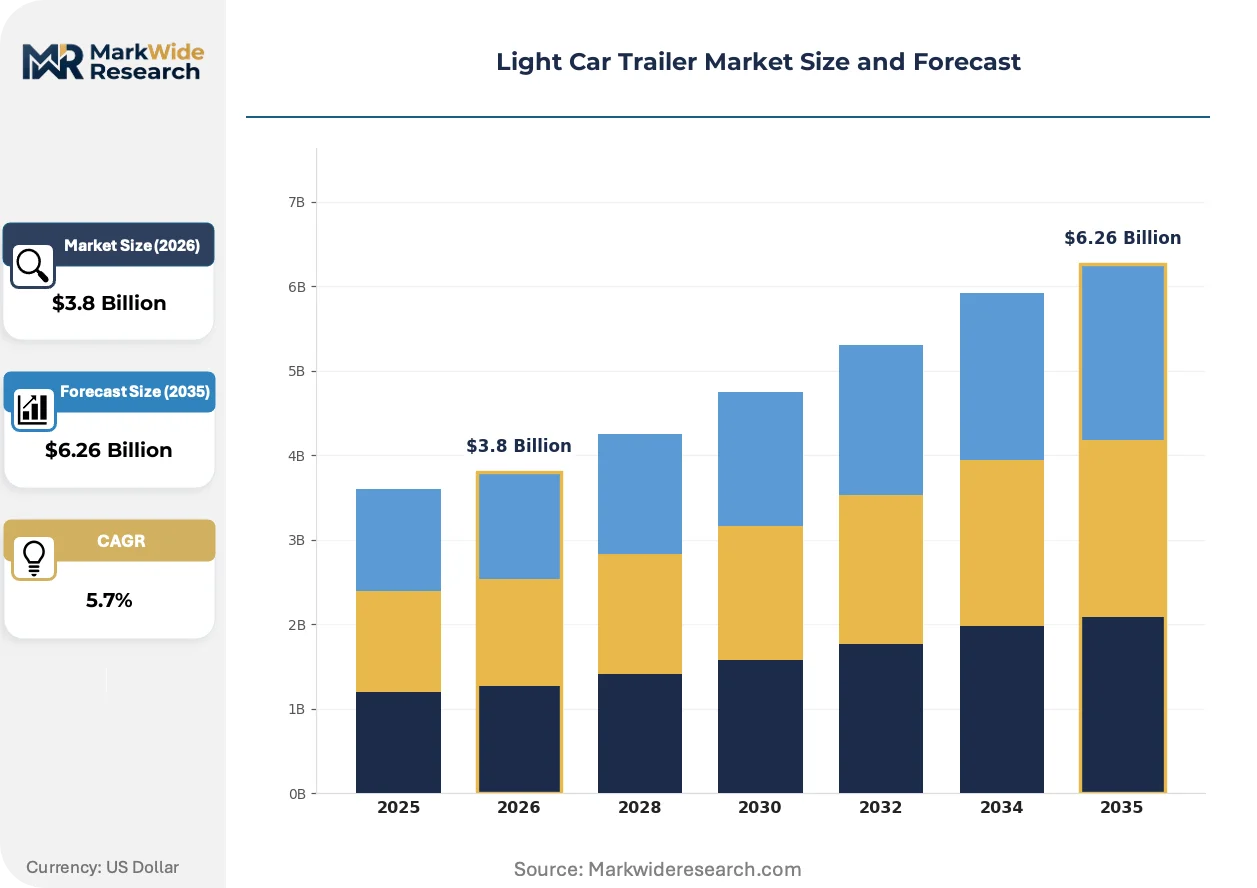
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trailer Type: Single-Axle, Double-Axle, Enclosed, Open Material: Aluminum, Steel, Composite, Wood End User: Personal Use, Commercial Transport, Rentals, Dealerships Product Feature: Foldable, Lightweight, Weather-Resistant, Customizable |
| Companies Covered | Aluma Ltd., ATC Trailers Holdings, Inc., Felling Trailers, Inc., Haulmark Industries, Inc., Kaufman Trailers, Inc., Pace American, Inc., Woodford Trailers Ltd., SylvanSport, Sundowner Trailers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Car Trailer Market Strategic Shifts & Innovations
Connected trailer architectures and predictive maintenance systems are redefining ownership economics, shifting value capture from initial transaction toward lifecycle service relationships.
Telematics-embedded axle assemblies are digitizing load monitoring and brake performance tracking for commercial transport operators. Fleet managers across Texas and California are adopting cellular-enabled units at accelerating rates. This connectivity layer is digitizing maintenance scheduling from reactive repair toward predictive intervention, compressing downtime costs.
National Highway Traffic Safety Administration conspicuity tape and lighting mandates are tightening enforcement protocols for interstate commercial operators. Manufacturers must now certify LED configurations against FMVSS 108 standards prior to shipment, extending pre-delivery timelines. Double-axle commercial configurations face the highest compliance scrutiny, driving consolidation toward pre-certified platform designs.
Direct manufacturer-to-consumer configuration portals are displacing traditional dealer specification workflows. Personal-use buyers in recreational vehicle markets now expect 48-hour customization quotes with visual rendering tools. This channel compression is most visible across Sun Belt states, where outdoor recreation demand concentrates and dealer network coverage remains uneven.
Light Car Trailer Market Segmentation
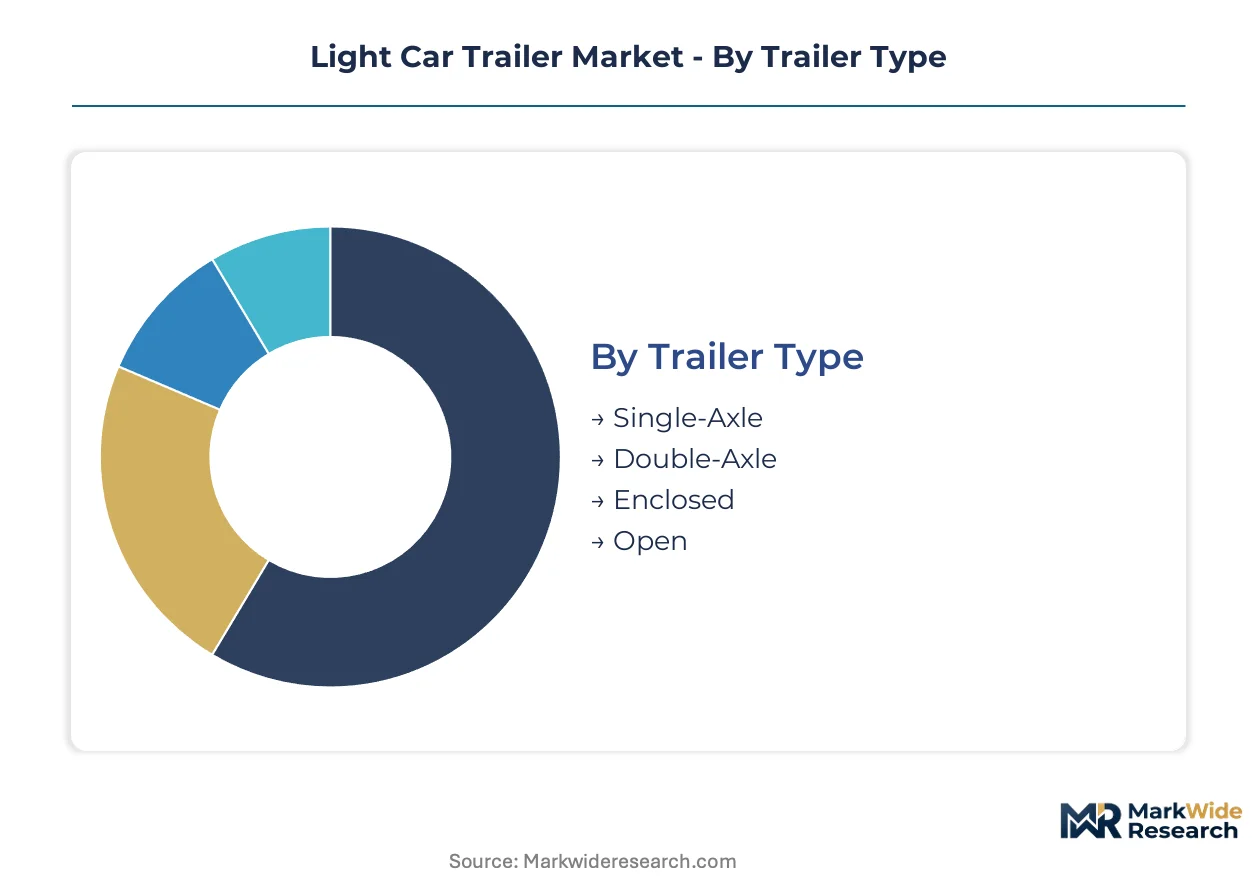
Segmentation in the light car trailer market reveals how material preferences, axle configurations, and end-use applications fragment procurement patterns across recreational and commercial buyers. Understanding these divides exposes where margin concentrates and where volume scales.
Trailer Type:
Mature configurations dominate commercial logistics while emerging formats reshape personal-use expectations around maneuverability and cargo protection.
- Single-Axle:Constructed with one load-bearing axle rated typically below 3,500 pounds GVWR, these trailers suit compact passenger vehicles and light recreational equipment. Demand clusters among Sun Belt personal-use buyers prioritizing fuel economy and garage storage compatibility. Aluminum chassis variants command premium positioning against steel alternatives.
- Double-Axle:Dual-axle architectures distribute load across four wheels with integrated braking redundancy for heavier cargo. Commercial transport operators across Texas and California specify these for equipment hauling and interstate logistics where stability regulations tighten. The configuration anchors fleet procurement for rental channel consolidation.
- Enclosed:Box-frame structures with weather-sealed cargo compartments protect sensitive equipment from road debris and climate exposure.
- Open:Flat-deck or ramp designs maximize payload accessibility for landscaping, construction, and utility applications.
Double-axle configurations handle the majority of throughput; enclosed trailers are expanding most quickly on share.
Material:
Cost tiers stratify sharply between commodity inputs and performance-engineered alloys, with procurement shifting upstream for supply security.
- Aluminum:Extruded and welded aluminum chassis construction reduces curb weight by 30-40 percent against comparable steel designs, directly improving tow vehicle fuel economy. Personal-use buyers in Florida and Arizona increasingly specify aluminum-intensive builds for corrosion resistance in coastal and desert climates. London Metal Exchange pricing volatility transmits immediately to manufacturer margins.
- Steel:Box-tube mild steel frames remain the baseline for price-sensitive commercial fleets and rental operators amortizing equipment over high-utilization cycles. Legacy production lines in the Midwest retain steel-dominant capacity.
- Composite:Molded polymer decking and skin panels from specialized chemical processors displace metal in salt-exposure environments.
- Wood:Treated lumber flooring persists in agricultural and utility segments where point-load durability and field repairability outweigh weight penalties.
Steel retains the highest shipment volumes; aluminum is climbing the fastest on specification share.
End User:
Customer type determines configuration complexity, with direct-to-consumer channels compressing traditional dealer intermediaries.
- Personal Use:Recreational vehicle enthusiasts and motorsport participants drive specification toward enclosed, aluminum-intensive builds with customization options. Direct manufacturer configuration portals now displace dealer workflows across Colorado and Utah corridors where service infrastructure remains sparse.
- Commercial Transport:Fleet operators and independent contractors prioritize double-axle, open-deck designs with FMCSA-compliant braking and lighting for interstate commerce. Telematics integration is emerging as a procurement differentiator for large fleet accounts.
- Rentals:Home improvement and equipment rental chains consolidate fleet ownership toward standardized specifications with volume maintenance agreements.
- Dealerships:New and used vehicle dealers stock entry-level open trailers as transaction add-ons or trade-in accommodations.
Commercial transport moves the greatest unit volumes; personal use is gaining share fastest on revenue per unit.
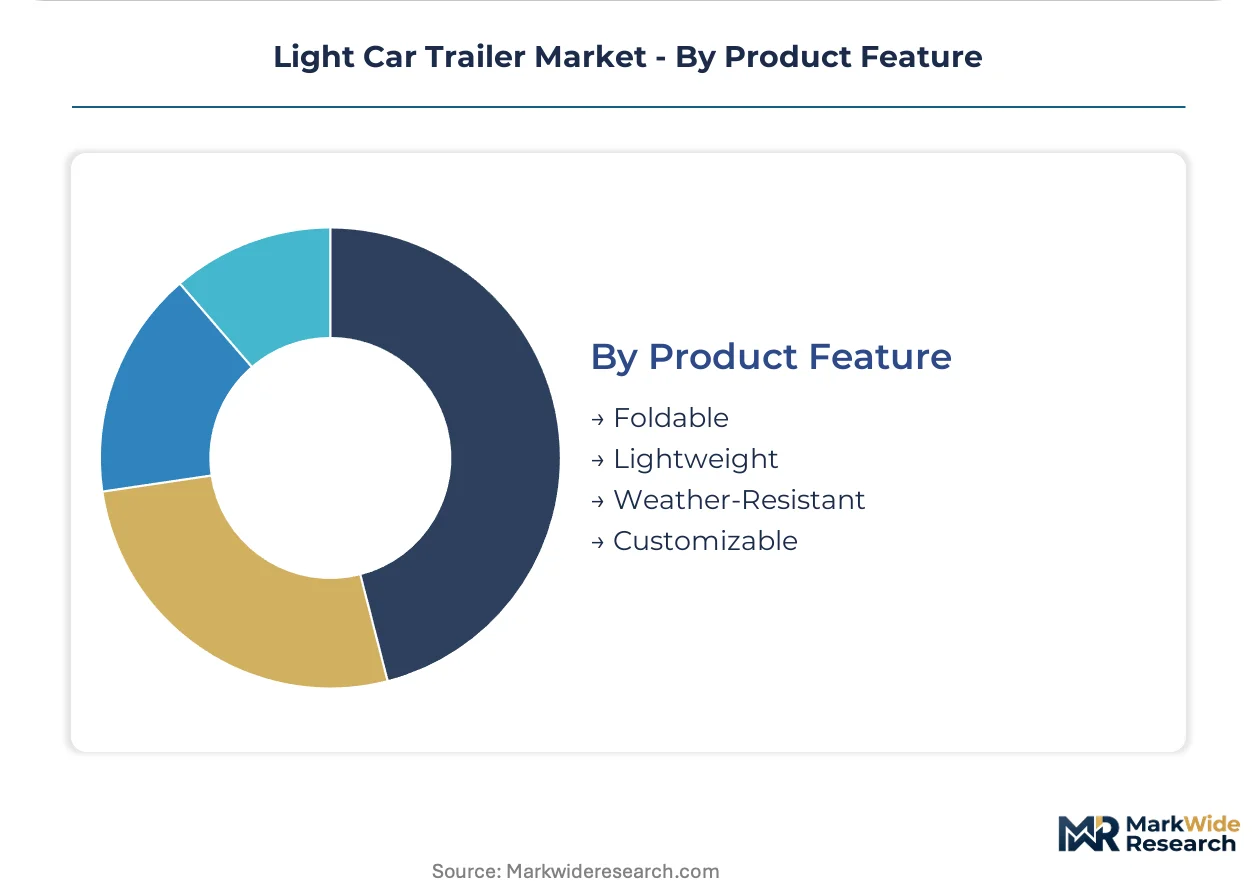
Product Feature:
Feature differentiation increasingly determines margin capture, with premium tiers separating on engineering integration rather than material alone.
- Weather-Resistant:Sealed enclosures, galvanized hardware, and marine-grade coatings extend service life in coastal and northern climates. Specifications from NHTSA conspicuity mandates and state DOT corrosion standards elevate baseline requirements.
- Lightweight:Advanced aluminum extrusion profiles and composite floor assemblies target electric vehicle towing compatibility where payload capacity constraints tighten.
- Foldable:Collapsible frame designs reduce storage footprint for urban buyers with limited parking availability.
- Customizable:Modular interior fitments, ramp configurations, and color options enable buyer-specified builds through direct manufacturer portals.
Weather-resistant specifications anchor the revenue base; lightweight engineering shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export aluminum-intensive trailers to Canadian recreational vehicle buyers through cross-border distribution corridors. This trade flow concentrates premium chassis fabrication in Midwest production clusters serving North American outdoor recreation demand.
United States
Sun Belt states from Florida to Arizona sustain replacement-cycle demand among personal-use buyers seeking enclosed configurations for weather-sensitive cargo. The National Highway Traffic Safety Administration governs federal lighting, braking, and conspicuity standards that shape baseline safety equipment requirements. Manufacturing concentrates in Indiana and Ohio where aluminum welding certification programs feed specialized fabrication facilities.
Canada
Recreational vehicle density in British Columbia and Alberta drives specification toward lightweight aluminum builds compatible with electric vehicle towing constraints. Transport Canada aligns with FMVSS 108 standards while imposing additional provincial width limits that fragment market access protocols. Toronto-area distributors are consolidating procurement toward standardized fleet specifications with volume maintenance agreements.
Germany
Commercial transport operators prioritize double-axle designs with integrated braking redundancy for equipment hauling across autobahn corridors. The Kraftfahrt-Bundesamt enforces type-approval requirements for trailer lighting and braking systems under EU regulatory frameworks. Manufacturing clusters in Baden-Württemberg specialize in precision aluminum extrusion for premium chassis applications.
Australia
Corrosion-critical applications in coastal Queensland and Western Australia accelerate molded polymer decking substitution against traditional aluminum panels. The Australian Design Rules mandate compliance with ADR 62/02 for trailer braking performance in interstate commerce. Melbourne-based fabricators are expanding telematics-embedded axle assemblies for mining sector fleet operators.
China
Export-oriented production in Shandong and Jiangsu provinces supplies steel-dominant box-tube frames for price-sensitive commercial fleets across Southeast Asia. The Ministry of Industry and Information Technology regulates GB standards for trailer structural integrity and lighting configurations. Yangtze River Delta manufacturing hubs are scaling aluminum extrusion capacity for domestic recreational vehicle market expansion.
Light Car Trailer Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement networks. The vendor base spans dedicated aluminum fabricators, steel-centric volume producers, and custom-configured open-deck specialists. Three archetypes dominate: premium aluminum-intensive manufacturers, commercial fleet-oriented scale producers, and rental channel consolidators. Competitive moves center on direct-to-consumer portal development and telematics integration partnerships.
Within the premium aluminum fabrication tier, Aluma Ltd. and ATC Trailers Holdings, Inc. exemplify material-specialist positioning. Felling Trailers, Inc. occupies a position among custom-configured open-deck providers serving commercial transport buyers. These three entities anchor distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Aluma Ltd. |
| ATC Trailers Holdings, Inc. |
| Felling Trailers, Inc. |
| Haulmark Industries, Inc. |
| Kaufman Trailers, Inc. |
| Pace American, Inc. |
| Woodford Trailers Ltd. |
| SylvanSport |
| Sundowner Trailers, Inc. |
| Others |
Cost & Logistics Intelligence
Aluminum extrusion capacity concentration in Indiana and Ohio fabrication clusters directly determines margin distribution between chassis manufacturers and downstream assemblers. London Metal Exchange pricing volatility transmits immediately through long-term supply agreements, compressing buffers for mid-tier producers without captive smelter relationships.
Pricing Analysis
Steel-to-aluminum generational pricing gaps separate three-tier pricing structure across premium, standard, and economy levels. Premium aluminum-intensive builds from Aluma Ltd. and ATC Trailers Holdings command material-grade and corrosion-resistance premiums against steel-dominant economy tiers. Cost compression in the mid-market is intensifying because aluminum welding certification scarcity constrains scalable production. Rental channel buyers exhibit the highest price sensitivity through volume maintenance agreements, while personal-use recreational buyers in Sun Belt states show lowest sensitivity to customization premiums.
Supply Chain Analysis
Tariff exposure between primary aluminum suppliers in Canada and Midwest fabrication facilities dominates supply-side risk assessment. The supply chain draws from bauxite processing in Australia, primary smelting in Canada, and extrusion finishing in Indiana and Ohio. Single-source vulnerability concentrates in specialized aluminum alloy formulations for corrosion-resistant chassis. Distribution runs through dealer networks in Sun Belt states, direct-to-consumer portals in Mountain West corridors, and consolidated fleet procurement for rental channel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance services are expanding faster than hardware unit growth, creating recurring-revenue pools that outpace trailer shipment economics. Fleet operators and commercial transport buyers increasingly bundle connectivity subscriptions with initial procurement.
For Market Incumbents: Insulate premium positioning through captive aluminum extrusion capacity and American Welding Society certification pipelines that constrain competitor scaling. Composite floor substitution from molded polymer processors threatens corrosion-application share; backward integration into specialized alloy supply secures margin buffers against London Metal Exchange volatility. For New Entrants and Emerging Players: Mountain West corridors in Colorado, Utah, and Idaho represent the most penetrable entry point given sparse dealer infrastructure and accelerating recreational vehicle density. Direct-to-consumer configuration portals with 48-hour quote turnaround displace traditional dealer workflows. Target telematics-embedded axle assemblies for commercial fleet accounts seeking predictive maintenance differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum fabrication specialists lacking integrated downstream channel control. Five-to-ten year viability hinges on electrified tow vehicle compatibility positioning and telematics service attach rates. Monitor battery-electric truck penetration curves as the critical inflection signal for trailer-side power management specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | Cellular-enabled axle assemblies differentiate fleet offerings for Texas and California operators. |
| Aluminum Welding Certification Pipeline | American Welding Society qualification programs constrain competitor production scaling in Midwest clusters. |
| Direct-to-Consumer Portal Launch | Configuration tools with visual rendering compress dealer intermediaries in Colorado and Utah corridors. |
| Composite Floor Manufacturing Scale-Up | Molded polymer decking captures share in coastal Queensland and Florida salt-exposure environments. |
| Electrified Tow Vehicle Compatibility Program | Integrated charging systems align with battery-electric truck penetration in consumer and fleet segments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with trailer manufacturing executives, fleet procurement managers, and rental channel operators; and secondary validation through NHTSA regulatory filings, FMCSA compliance databases, and aluminum trade flow records. Bottom-up shipment estimates from state-level registration data triangulated against top-down recreational vehicle ownership correlations.
Forecast inputs include material substitution rates, electrified tow vehicle adoption curves, and telematics penetration across commercial fleet segments. Segmentation dimensions span trailer type, material composition, axle configuration, and end-user channel. CAGRs derive from regression analysis against macroeconomic indicators and outdoor recreation participation indices.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and aluminum commodity pricing would shift the trajectory. Forecasts reflect assumptions about regulatory stability and recreational vehicle ownership trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Kick Scooter Market