
 North America Recreational Vehicle Market | 2026-2036
North America Recreational Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Recreational Vehicle Market Intelligence
The substitution of traditional aluminum with lightweight composite materials for body panels and structural components is broadening design possibilities for manufacturers, enabling more fuel-efficient and aerodynamic profiles. Thor Industries leverages its vast portfolio of brands to cover multiple consumer segments across North America. Winnebago Industries differentiates through sustained R&D in electric RV concepts and accessibility-enhanced models. Forest River Inc. anchors its market presence through an expansive dealership network and diverse product offerings.
A recreational vehicle is a motorized or towable vehicle that combines transportation with temporary living quarters for travel and camping. These units are engineered with self-contained systems for water, electricity, and waste management, enabling off-grid use. Towable travel trailers command the largest market volume due to their relative affordability, while motorhomes define the premium segment. Demand from family vacationers constitutes the primary end-user base, supplemented by individual enthusiasts seeking specialized models.
Regulations from the U.S. Environmental Protection Agency (EPA) dictate stringent engine emission standards, pushing manufacturers toward cleaner powertrain technologies like hybrid systems. Concurrently, safety mandates from the National Highway Traffic Safety Administration (NHTSA) and Transport Canada govern vehicle construction, weight limits, and occupant protection. Key decisions for industry stakeholders revolve around balancing investments in electrification against the persistent consumer demand for traditional internal combustion engine vehicles.
Market Dynamics
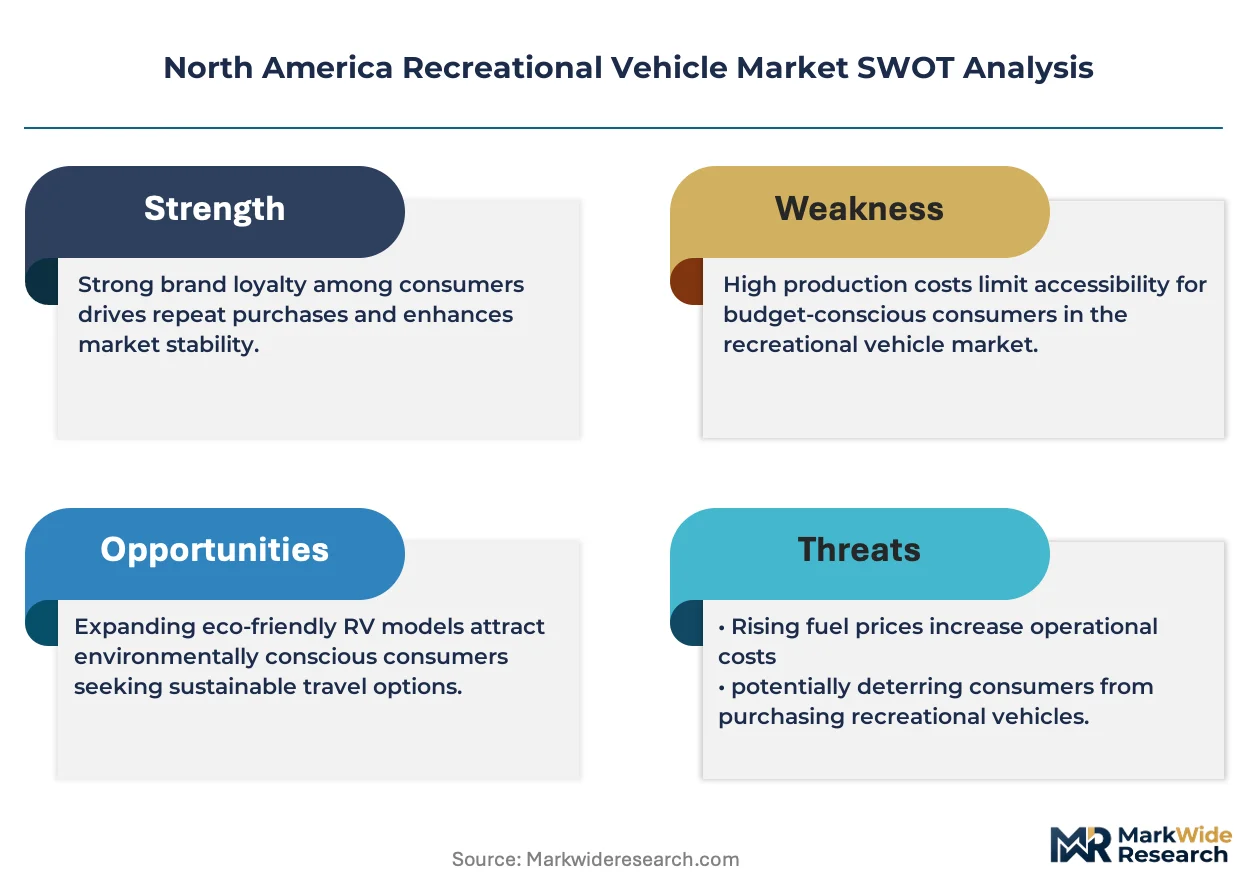
The central tension in the North America recreational vehicle market lies between the regulatory push for cleaner, more efficient powertrains and persistent consumer demand for affordable, traditionally powered models, forcing manufacturers to balance R&D investments with current market preferences.
Growth Catalysts
- Family Vacationer Segment:Sustained interest from family vacationers, particularly for travel within popular Sun Belt destinations like Florida and Arizona, provides a consistent demand base for both towable trailers and entry-level motorhomes.
- Lightweight Materials:The substitution of traditional aluminum with advanced composite materials for body panels and frames enables manufacturers to produce more fuel-efficient vehicles with greater design flexibility and aerodynamic profiles.
- Emissions Standards:Stricter engine emission mandates from the U.S. Environmental Protection Agency (EPA) accelerate the product replacement cycle and drive innovation in powertrain technologies, creating demand for newer, compliant models.
Market Restraints
- High Initial Cost:The significant upfront investment required for motorhomes, especially premium Class A models, serves as a primary barrier to entry, confining a large portion of the market to more affluent consumer segments.
- Infrastructure Gaps:A lack of widespread, reliable charging infrastructure for electric RVs and inconsistent campsite utility hookups in remote regions constrain the practical adoption of next-generation, electrified vehicle platforms.
- Input Price Volatility:Fluctuations in the cost of crucial raw materials, including aluminum for framing and petroleum-based composites for bodywork, introduce margin uncertainty and production cost challenges for manufacturers.
Strategic Opportunities
- Accessibility-Enhanced Models:Designing and marketing RVs with features catering to travelers with disabilities and mobility challenges opens an underserved and loyal market segment with specific needs not met by standard models.
- Compact and Urban-Friendly Units:Developing smaller, more maneuverable camper vans and lightweight towables appeals to younger, urban-based consumers who value versatility and ease of use over the large footprint of traditional RVs.
- Subscription and Fractional Ownership:Introducing flexible usage models like subscription services or fractional ownership can lower the barrier to entry for consumers hesitant about the total cost and commitment of full ownership.
Industry Challenges
- Technician Skill Shortage:A persistent shortage of qualified service technicians capable of repairing complex onboard systems, from modern electronics to powertrain components, leads to extended service delays and customer dissatisfaction across North America.
- Supply Chain Complexity:Managing a diverse and fragmented supply chain for thousands of components, from chassis and engines to appliances and furniture, poses significant logistical hurdles and risks of production disruption.
- Regulatory Divergence:Navigating differing vehicle weight, length, and safety standards between the United States (NHTSA) and Canada (Transport Canada) complicates product design, testing, and certification for manufacturers operating across both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Recreational Vehicle Market |
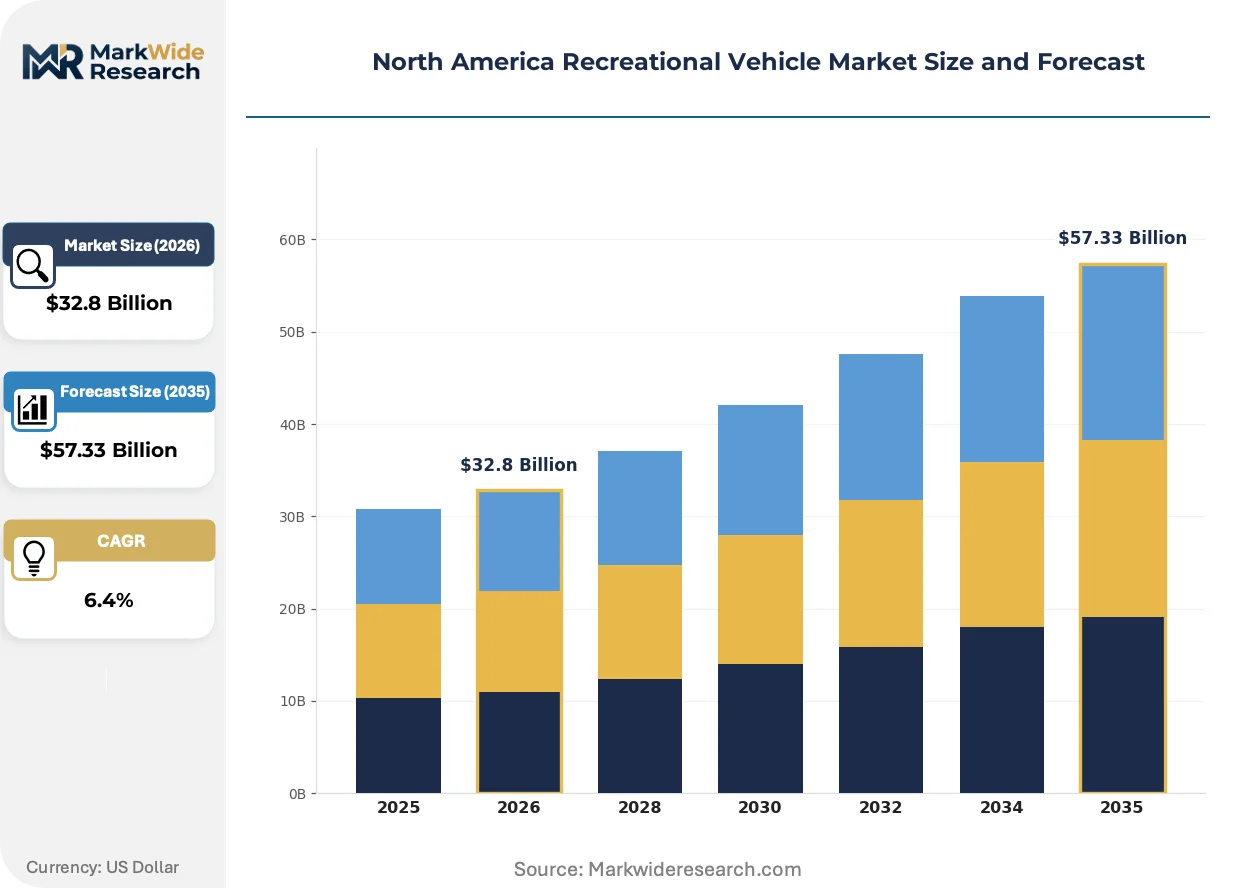
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorhomes, Travel Trailers, Truck Campers, Pop-up Campers, Folding Camping Trailers Application: Outdoor Camping, Road Trips, Tailgating, Seasonal Vacations, Mobile Housing Distribution Channel: Dealership Networks, Online Marketplaces, Specialty Retail Stores, Rental Agencies, Direct Sales End User: Individual Enthusiasts, Family Vacationers, Adventure Tour Operators, Corporate Retreats, Educational Groups |
| Companies Covered | REV Group, Keystone RV Company, Thor Industries, Newmar Corporation, Tiffin Motorhomes Inc., Forest River Inc., Grand Design RV, Jayco Inc., Winnebago Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Recreational Vehicle Market Strategic Shifts & Innovations
The market is being redefined by the convergence of automotive engineering advancements with evolving consumer lifestyle demands. This dynamic pushes product development toward greater efficiency, connectivity, and versatility, moving beyond traditional vacation use cases to support more flexible living and working arrangements.
Lightweight composite materials are being integrated into body panels and structural components to reduce overall vehicle mass. Manufacturers of both motorhomes and towable trailers are increasingly adopting these materials to meet fuel economy targets. This technological shift is absorbing the design limitations of conventional aluminum construction, enabling more aerodynamic and innovative vehicle profiles.
The U.S. Environmental Protection Agency (EPA) continues to enforce stringent emissions standards for heavy-duty engines common in motorhomes. This regulatory pressure compels manufacturers to invest in cleaner powertrain technologies, such as advanced diesel after-treatment systems and hybrid-electric concepts. Class A and Class C motorhome segments are most affected, forcing a balance between the high cost of compliance and consumer price expectations.
A notable behavioral shift is the rise of remote work, which extends RV usage beyond traditional seasonal vacations into year-round mobile living. This trend disrupts established rental patterns and creates new demand for vehicles equipped with reliable onboard internet connectivity and dedicated office spaces. The pattern is most visible among younger buyers in the United States and Canada, directly influencing interior design priorities.
North America Recreational Vehicle Market Segmentation
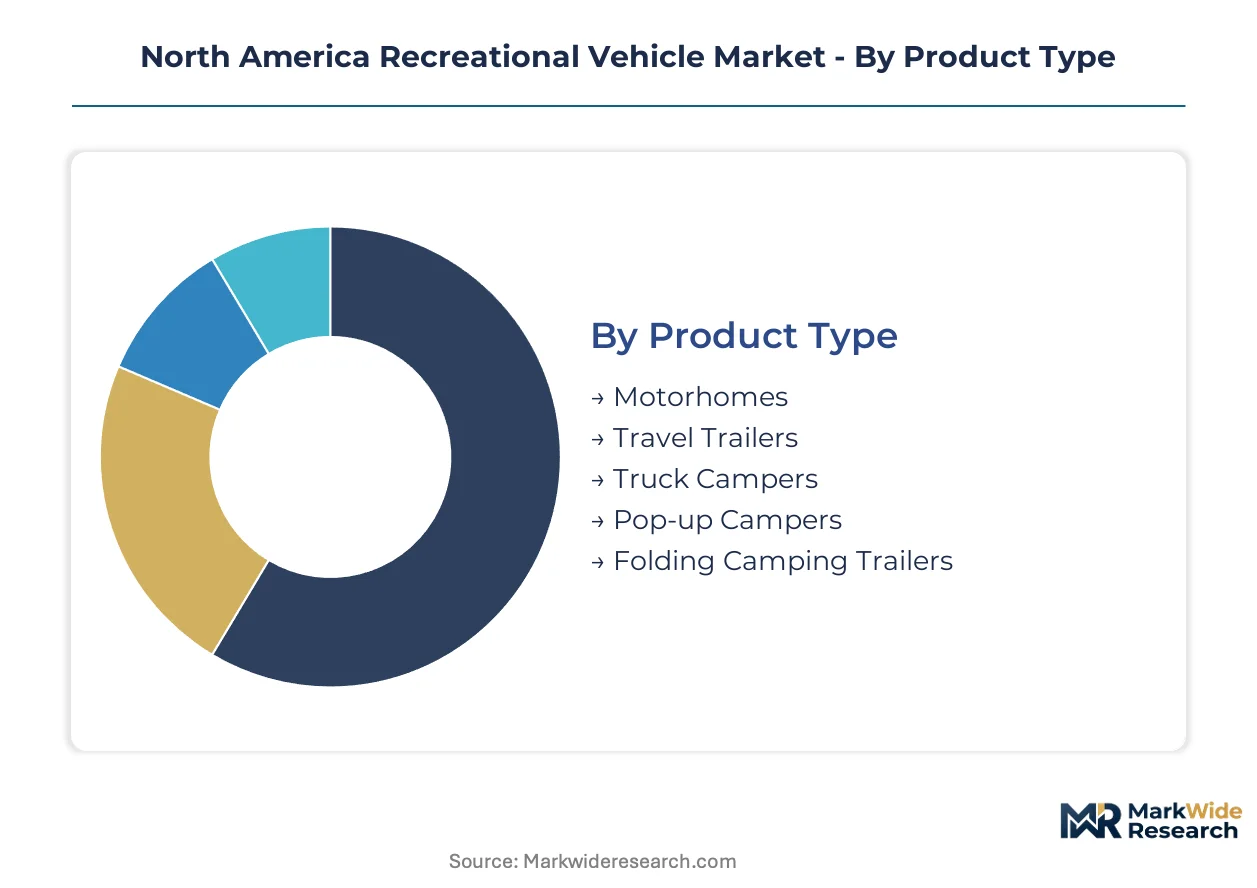
Understanding the North America recreational vehicle market through segmentation provides critical insights into diverse consumer preferences and operational requirements. This detailed breakdown helps manufacturers tailor product development and distribution strategies to specific buyer needs and usage patterns. Each segment presents unique opportunities and challenges within the broader market landscape.
Product Type:
The product type segmentation highlights how different vehicle designs cater to varying upgrade cycles and replacement priorities within the North American market.
- Travel Trailers:These towable units offer flexible living space without an integrated engine, providing a cost-effective entry point into RV ownership. Demand concentrates heavily among family vacationers in Sun Belt states like Florida, driven by their relative affordability compared to motorhomes.
- Motorhomes:Self-propelled recreational vehicles combine transportation with comprehensive living quarters, often featuring advanced onboard systems for extended travel. Demand is strong within the premium segment, particularly from affluent consumers seeking comprehensive travel solutions and enhanced comfort.
- Truck Campers:Detachable living units designed to be mounted on the bed of a pickup truck, appealing to adventurers seeking off-road capability and flexible vehicle use.
- Pop-up Campers:Collapsible towable units offer compact storage and expanded living space when deployed, favored by budget-conscious entry-level buyers.
- Folding Camping Trailers:Lightweight, towable units with rigid sides that fold down for transport, providing a balance of portability and enhanced amenities for casual campers.
Volume placements concentrate in Travel Trailers; the faster expansion belongs to Motorhomes.
Application:
Segmentation by application reflects diverse consumer lifestyles and specific usage scenarios for recreational vehicles across North America.
- Outdoor Camping:Recreational vehicles provide self-contained living for extended stays in natural environments, with demand driven by outdoor enthusiasts seeking wilderness access and convenience.
- Mobile Housing:RVs serve as primary or secondary residences, supporting remote work and flexible living arrangements, particularly among younger buyers in the United States and Canada.
- Road Trips:Vehicles facilitate multi-destination journeys, offering flexible accommodation and transportation for extended travel experiences.
- Tailgating:RVs provide mobile entertainment and hospitality setups for sporting events and concerts, popular for social gatherings.
- Seasonal Vacations:Units cater to recurrent leisure travel during specific times of the year, especially to popular Sun Belt destinations.
While Outdoor Camping remains a foundational use, Mobile Housing applications are expanding most quickly.
Distribution Channel:
The distribution channel segmentation illustrates the primary avenues through which recreational vehicles reach consumers, influencing market access and sales strategies.
- Dealership Networks:These established physical locations offer sales, financing, and after-sales service, anchoring market presence for major manufacturers.
- Online Marketplaces:Digital platforms facilitate vehicle discovery and purchase, appealing to a tech-savvy consumer base seeking convenience and broader inventory access.
- Specialty Retail Stores:Focused outlets offer niche RV products or accessories, catering to specific enthusiast segments.
- Rental Agencies:Businesses provide short-term access to RVs for vacationers and event-goers, lowering the barrier to entry for temporary use.
- Direct Sales:Manufacturers sell vehicles directly to consumers, allowing for customization and a more controlled customer experience.
Dealership Networks maintain their dominance, but Online Marketplaces are gaining share fastest in North America.
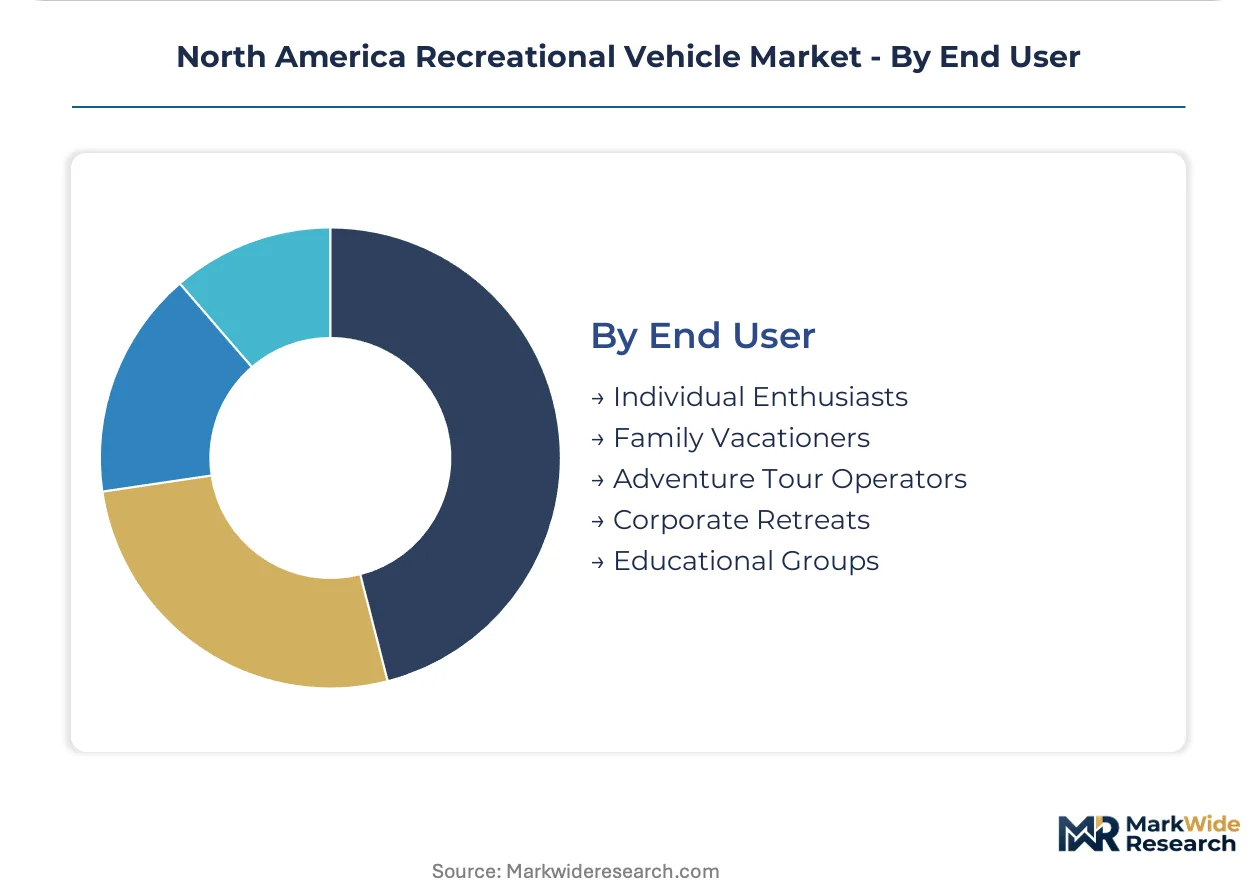
End User:
This end-user segmentation delineates the distinct groups driving demand for recreational vehicles, each with specific requirements and purchasing motivations.
- Family Vacationers:This segment represents the primary end-user base, seeking affordable and convenient travel options for multi-person trips, often to popular destinations.
- Individual Enthusiasts:Consumers in this segment prioritize specialized models and features tailored for specific hobbies or solitary travel, often driving demand for compact units.
- Adventure Tour Operators:Businesses utilize RVs for guided expeditions and specialized travel packages, requiring robust and reliable fleet vehicles.
- Corporate Retreats:Companies employ RVs for mobile meeting spaces or employee incentives, valuing amenities and comfort for team-building activities.
- Educational Groups:Institutions use recreational vehicles for field trips, research expeditions, or mobile learning environments, needing adaptable and durable units.
Family Vacationers constitute the largest volume segment, while Individual Enthusiasts are climbing the fastest for specialized models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for recreational vehicles in North America concentrates heavily within the United States, particularly within Sun Belt states like Florida and Arizona. This regional focus is driven by favorable climates and established travel destinations. Canada and Mexico also contribute to the market, albeit with distinct consumer preferences and regulatory environments.
United States
Demand for motorhomes and towable travel trailers is robust across the United States, fueled by family vacationers and the growing remote work trend. The U.S. Environmental Protection Agency (EPA) mandates stringent engine emission standards, pushing innovation in powertrain technologies. Indiana's Elkhart County serves as a major manufacturing hub, where numerous RV producers focus on efficiency and design flexibility.
Canada
Canadian consumers prioritize smaller, more maneuverable RVs suitable for diverse terrains and shorter travel seasons. Transport Canada's safety mandates govern vehicle construction and weight limits, influencing local product offerings. British Columbia's Fraser Valley region sees localized growth in specialized camper van conversions, catering to outdoor enthusiasts.
Mexico
Mexico's RV market primarily caters to cross-border tourism and a niche domestic segment seeking affordable travel solutions. The country's vehicle import regulations affect the availability and pricing of new and used recreational vehicles. Baja California Norte experiences sustained interest for RV parks and tourism, attracting North American travelers.
Florida
Florida experiences high demand for seasonal RV usage and retirement living, particularly for larger motorhomes and permanent park models. State-specific vehicle registration and titling laws impact ownership costs and processes for residents. The Orlando metropolitan area functions as a central point for RV sales and rental services, supporting tourist activity.
Arizona
Arizona's dry climate attracts snowbirds and outdoor enthusiasts, driving strong demand for both new and used RVs, especially during winter months. Local zoning ordinances in popular destinations like Quartzsite influence the development and availability of RV parks. Phoenix and Tucson serve as key service and sales centers, accommodating a large seasonal RV population.
North America Recreational Vehicle Market Key Industry Players
Portfolio diversification dominates the current North American recreational vehicle competitive landscape, as manufacturers seek to cover multiple consumer segments. The market exhibits a tiered structure, with a few large integrated players alongside numerous specialized producers. Strategic archetypes include full-line manufacturers, premium segment specialists, and niche innovators. Geographic expansion and strategic partnerships represent key competitive moves as companies navigate evolving consumer preferences and regulatory pressures.
Within the full-line manufacturer archetype, Thor Industries anchors a significant market presence across North America, leveraging its vast brand portfolio to reach diverse buyer groups from entry-level towables to premium motorhomes. Winnebago Industries exemplifies a focus on sustained R&D in electric RV concepts and accessibility-enhanced models, targeting evolving consumer needs. Forest River Inc. occupies a strong position through its expansive dealership network and diverse product offerings, catering to a broad base of consumers seeking various types of recreational vehicles.
| Leading Market Players |
|---|
| REV Group |
| Keystone RV Company |
| Thor Industries |
| Newmar Corporation |
| Tiffin Motorhomes Inc. |
| Forest River Inc. |
| Grand Design RV |
| Jayco Inc. |
| Winnebago Industries |
| Others |
Cost & Logistics Intelligence
Affluent consumers seeking premium motorhomes drive a value-based pricing model, while family vacationers prioritize transactional per-unit pricing for towable travel trailers. This dual demand structure influences overall market dynamics.
Pricing Analysis
Volume-centric segments like travel trailers operate on tighter margins, driven by per-unit transactional pricing and consumer affordability expectations. Price differentiation stems from brand premium and enhanced features such as advanced onboard systems. Pricing softness runs through entry-level models due to intense competition and input cost volatility. Family vacationers exhibit the highest price sensitivity, contrasting with affluent motorhome buyers who prioritize comprehensive comfort.
Supply Chain Analysis
US domestic content mandates and Canadian safety regulations significantly influence sourcing decisions for recreational vehicle components. Geographic supply concentrates predominantly in the United States, particularly Indiana's Elkhart County, with some input from Mexico and Canada. Raw material dependencies include aluminum, advanced composite materials, and specialized chassis. Commodity price volatility presents a structural risk for manufacturers. Distribution runs through established dealership networks across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America recreational vehicle market presents a cost-of-compliance narrative, with stringent U.S. Environmental Protection Agency (EPA) emissions standards creating a significant barrier to entry for new engine technologies. This regulatory environment favors established manufacturers with R&D capabilities.
For Market Incumbents: Extend investment in advanced powertrain technologies to meet evolving EPA emissions standards, mitigating the threat of regulatory penalties. Consolidate supply chain relationships for critical components like chassis and composite materials to buffer against input price volatility. Vertical integration into specialized repair training programs can address the persistent technician skill shortage. Focus R&D on electric RV concepts to preempt emerging competitor archetypes.
For New Entrants and Emerging Players: Electric RV concepts offer a technology-first wedge into the North American market, appealing to environmentally conscious consumers. Target the underserved accessibility-enhanced model segment, which remains largely overlooked by established players, particularly in Canada. Develop compact, urban-friendly units for younger, urban-based consumers seeking versatility. A direct-to-consumer online sales model presents an efficient go-to-market angle for specialized offerings.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist manufacturers in the United States focusing on niche segments like custom camper vans. Long-term viability hinges on companies demonstrating adaptability to evolving consumer preferences and regulatory shifts over the next decade. Identify acquisition targets with strong intellectual property in electrification or advanced materials. A key signal to watch is the sustained growth in order backlogs for electric RV models, indicating market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Powertrain R&D | Investing in hybrid-electric systems ensures compliance with U.S. EPA emissions standards and appeals to eco-conscious buyers. |
| Composite Material Integration | Adopting lightweight composites reduces vehicle mass, improving fuel efficiency and aerodynamic profiles for new models. |
| Dealership Network Expansion | Broadening dealership reach strengthens market presence and provides comprehensive after-sales service across North America. |
| Accessibility Model Development | Designing RVs for travelers with disabilities opens an underserved market segment and enhances brand loyalty. |
| Subscription Service Launch | Introducing flexible ownership models lowers the barrier to entry for younger consumers hesitant about full RV ownership. |
Research Approach
Document review covered U.S. Environmental Protection Agency (EPA) reports, National Highway Traffic Safety Administration (NHTSA) publications, and financial statements of major RV manufacturers, complemented by interviews with industry stakeholders. Primary research involved conversations with RV dealership owners, materials suppliers, and product development executives. This approach ensured bottom-up and top-down triangulation of market data.
The analytical model produced detailed volume and value projections for the North America recreational vehicle market across the analysis window. Segmentation dimensions modeled included product type, application, distribution channel, end user, and regional market dynamics within the United States and Canada. Compound annual growth rates were derived from historical trends and projected economic indicators. Key forecast inputs included consumer discretionary spending and raw material price forecasts.
Several conditions sit outside the modeled scope, including unforeseen global economic crises and rapid shifts in transportation infrastructure for electric RVs. Forecasts reflect assumptions regarding stable regulatory environments and sustained consumer interest in outdoor recreation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Electric Golf Cart Market