
 Automatic High Beam Control Market | 2026-2036
Automatic High Beam Control Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic High Beam Control Market Analysis
Market Context
Germany is fragmenting as new engineering centers and sensor calibration facilities multiply across Bavaria and Baden-Württemberg. Robert Bosch GmbH leverages its integrated semiconductor and software stack to control module design for European OEM programs. HELLA GmbH & Co. KGaA anchors its competitive position through specialized optical component manufacturing that supplies multiple Tier-1 platforms. Continental AG competes by extending its ADAS portfolio into fused camera-radar headlight control architectures.
Technical Definition and Structural Segments
Automatic high beam control constitutes an intelligent forward lighting system that uses optical sensors, image processing algorithms, and electromechanical actuators to modulate headlamp intensity between high and low beams based on detected traffic, ambient conditions, and road geometry, typically operating within detection ranges of 100-400 meters depending on sensor configuration. Camera-based technology leads current installation volumes across passenger vehicles due to mature supply chains and declining CMOS sensor costs, while hybrid systems integrating lidar represent the fastest-expanding segment as automakers pursue higher automation levels. Among applications, luxury vehicles concentrate margin pools where multi-zone matrix LED and laser headlamp integration commands premium pricing, whereas electric vehicles emerge as a volume growth vector as platform designs prioritize aerodynamic lighting enclosures and reduced energy draw.
Regulatory Frame and Forward Outlook
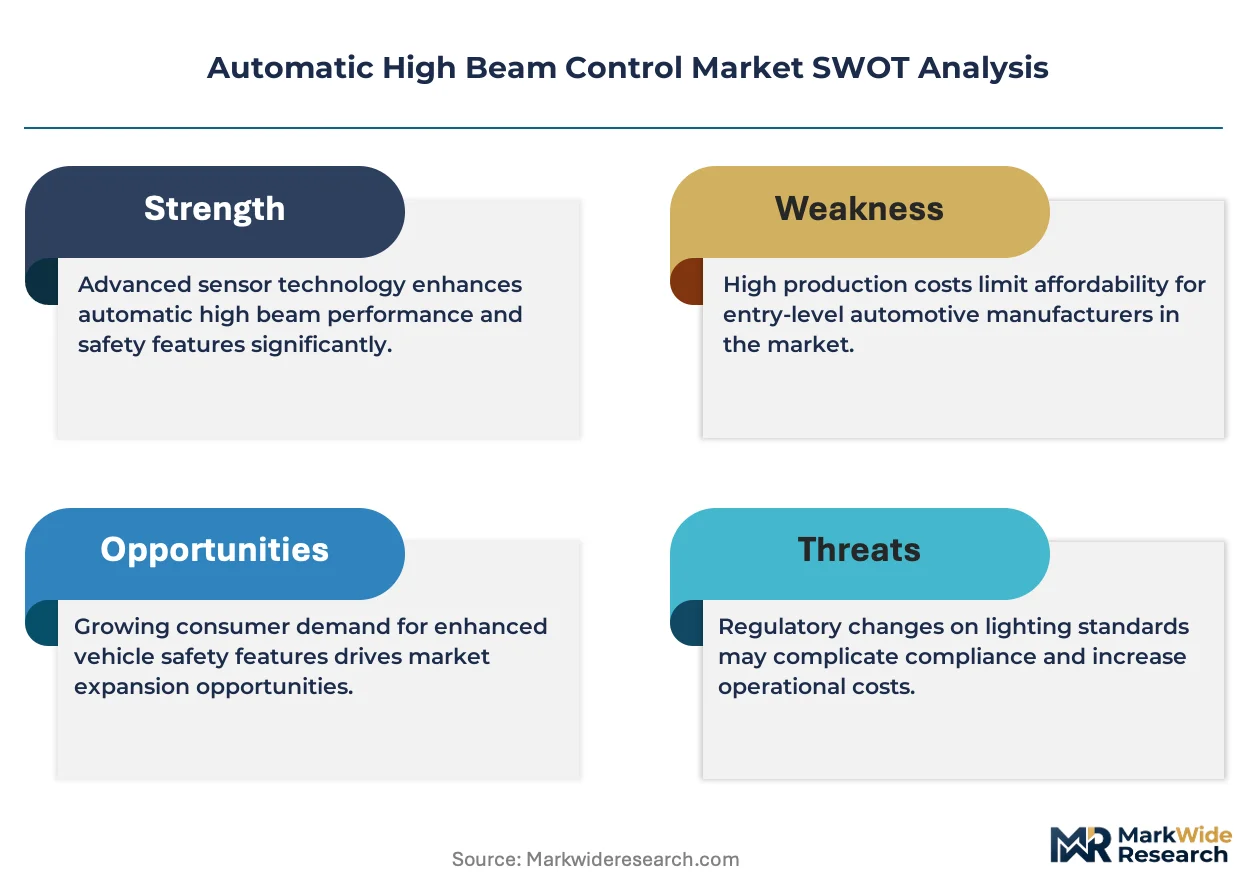
Euro NCAP assessment protocols, ECE R48 vehicle lighting regulations, and EU General Safety Regulation mandates collectively shape product specifications by requiring automatic beam adaptation for maximum safety ratings and type approval. NHTSA Federal Motor Vehicle Safety Standard 108 in the United States creates parallel compliance obligations for exporters seeking North American market access. Stakeholders must monitor divergence between European performance-based standards and U.S. prescriptive beam pattern requirements as this regulatory asymmetry determines regional product variant economics and platform commonality feasibility.
Market Dynamics
Euro NCAP safety rating protocols now mandate automatic beam adaptation for maximum scores, compelling Tier-1 suppliers to accelerate camera-based adaptive lighting development and compress integration timelines across European OEM programs.
Growth Catalysts
- EU General Safety Regulation:Mandates automatic high beam functionality for new vehicle type approvals, creating compliance-driven procurement pull across German, French, and Italian passenger vehicle platforms.
- Matrix LED technology:Multi-zone optical engines enable precise beam shaping without mechanical shutters, reducing component count while expanding addressable vehicle segments.
- Electric vehicle platform designs:Aerodynamic lighting enclosures and reduced energy draw requirements prioritize intelligent headlamp control as a standard feature rather than optional upgrade.
Market Restraints
- CMOS sensor cost volatility:Semiconductor supply concentration in East Asian foundries exposes module pricing to wafer allocation disruptions and foundry capacity constraints.
- NHTSA beam pattern prescriptivism:U.S. Federal Motor Vehicle Safety Standard 108 imposes fixed beam geometry requirements that conflict with European performance-based adaptation standards, forcing dual-variant engineering.
- Lidar unit economics:Hybrid camera-lidar architectures remain cost-prohibitive for mass-market vehicle segments, capping penetration below premium price tiers.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced driver assistance systems attract module assembly investments serving domestic and export markets.
- Camera-radar fusion architectures:Integration of forward-facing radar with optical sensing enables predictive beam adjustment before visual detection, opening highway automation applications.
- Aftermarket retrofit channels:Regulatory grandfathering of older vehicle fleets in Germany and France creates demand for dealer-installed upgrade kits with certified calibration protocols.
Industry Challenges
- Optical sensor calibration expertise:Shortage of technicians qualified for camera-radar alignment and dynamic beam pattern verification extends service center bottlenecks.
- ISO 26262 functional safety certification:ASIL-B compliance for lighting control modules demands redundant software architectures that extend development cycles and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic High Beam Control Market |
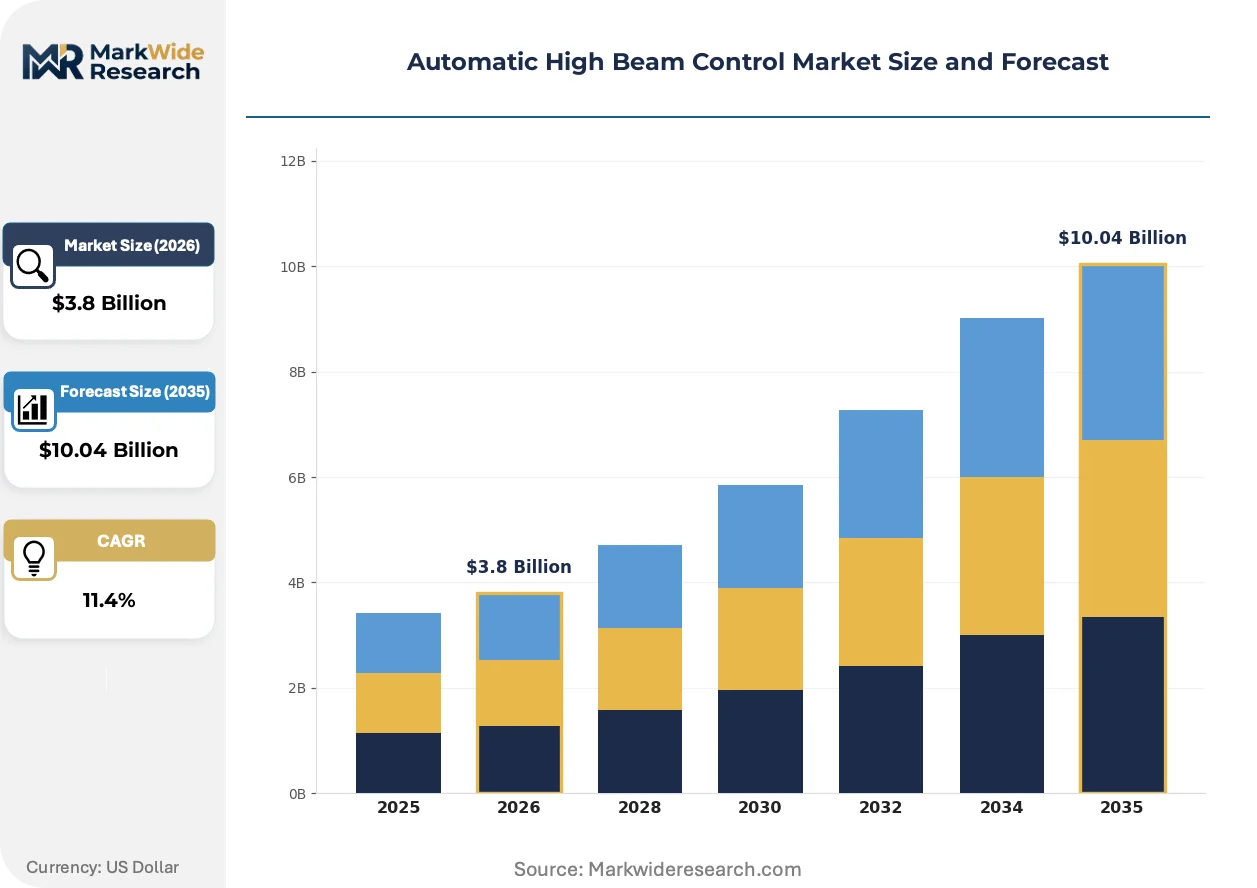
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Radar-Based, Lidar-Based, Hybrid Systems Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles End User: Automotive Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Feature: Adaptive Lighting, Glare Control, Night Vision Assistance, Automatic Switching |
| Companies Covered | HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Valeo, Continental AG, DENSO Corporation, Koito Manufacturing Co., Ltd., Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., HYUNDAI MOBIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic High Beam Control Market Emerging Trajectories
Technology trajectories in automatic high beam control center on sensor fusion sophistication, regulatory harmonization pressures, and procurement model evolution as OEMs consolidate lighting system sourcing under ADAS platform contracts.
Digital micromirror devices are migrating from cinema projection applications into automotive headlamp modules, enabling pixel-precise beam shaping with over one million individually addressable mirrors. German luxury marques have adopted this Texas Instruments technology for flagship programs since 2022. The shift from mechanical shutter systems to solid-state optical engines compresses module depth and enables new vehicle front-end packaging geometries.
REACH substance restrictions on heavy metals in electronics manufacturing are reshaping LED phosphor formulations and solder compositions across European supply chains. Component suppliers must reformulate optical coatings and thermal interface materials to maintain compliance without degrading lumen output or thermal dissipation performance. German Tier-1 suppliers have absorbed the highest compliance costs, passing reformulation investments through to OEM platform pricing.
Fleet procurement of lighting systems through consolidated ADAS platform contracts is displacing standalone headlamp module sourcing. Automakers now bundle high beam control within comprehensive forward sensing packages encompassing camera, radar, and compute. This concentration favors suppliers with integrated semiconductor and software stacks, compressing margins for pure-play optical component manufacturers serving as second-tier vendors.
Automatic High Beam Control Market Segmentation
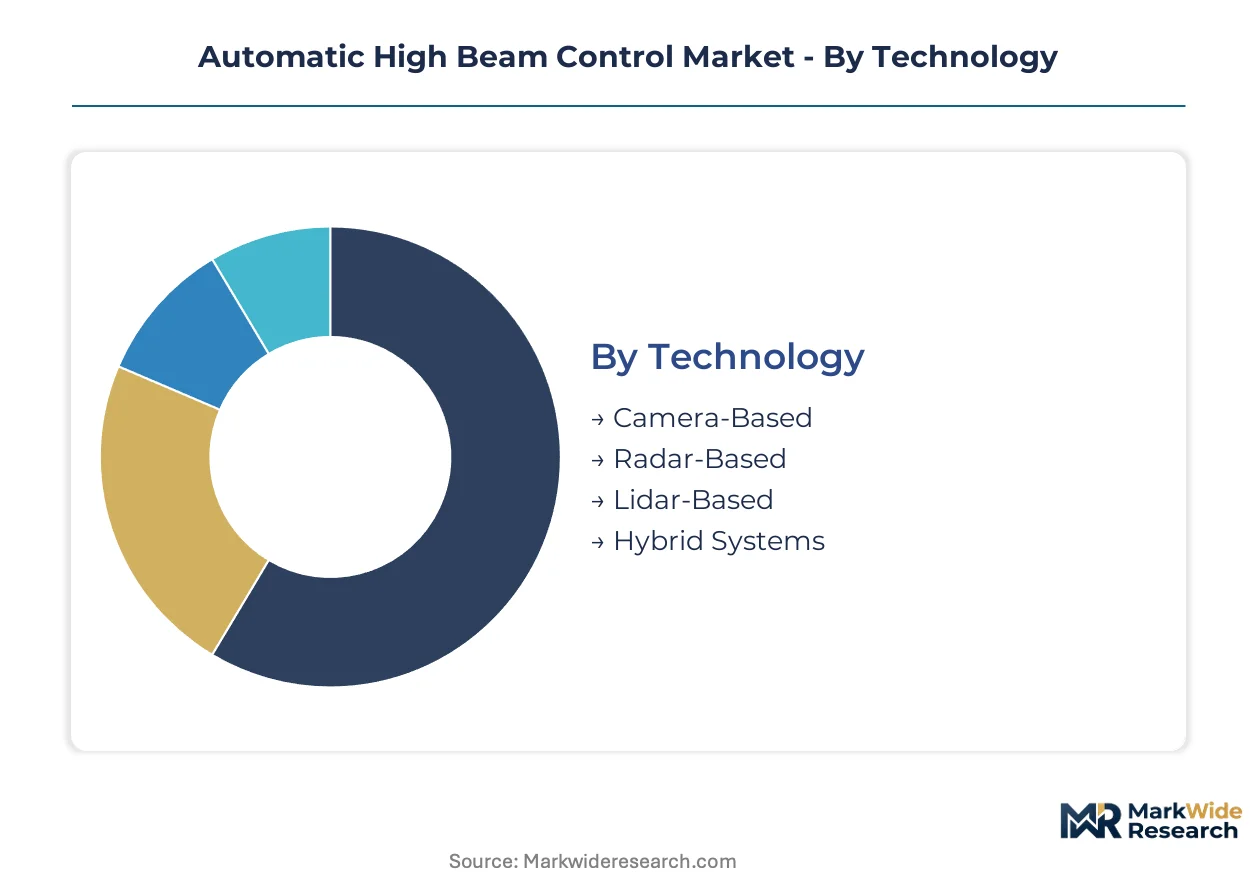
Automatic high beam control systems fragment across sensor technologies, vehicle applications, and procurement channels. Each dimension shapes engineering specifications, margin structures, and integration complexity for suppliers competing across European OEM programs.
Technology:
Cost tier determines sensor sophistication and algorithmic processing requirements across module architectures.
- Camera-Based:CMOS image sensors paired with machine vision algorithms detect oncoming traffic and ambient light conditions. German luxury marques concentrate procurement here, driven by Euro NCAP compliance deadlines and declining semiconductor costs from East Asian foundries.
- Hybrid Systems:Fused camera-radar-lidar architectures enable predictive beam adjustment beyond visual range. Demand concentrates in Level 2+ automation programs where highway-speed reaction times mandate redundant sensing, though lidar unit economics constrain penetration to premium vehicle tiers.
- Radar-Based:Forward-facing radar supplements optical detection in adverse weather conditions.
- Lidar-Based:Solid-state lidar enables pixel-precise beam mapping for matrix LED applications.
Camera-based modules command the established base. The steepest expansion runs through hybrid systems.
Application:
Vehicle segment dictates thermal management requirements, aerodynamic packaging constraints, and energy draw priorities.
- Passenger Vehicles:High-volume compact and mid-size platforms drive CMOS sensor standardization and software-defined beam control. French and Italian OEMs accelerate integration here, responding to EU General Safety Regulation mandates for new type approvals.
- Luxury Vehicles:Multi-zone matrix LED and laser headlamp architectures command premium module pricing. German marques specify digital micromirror devices and adaptive driving beam functionality, prioritizing brand differentiation over cost optimization.
- Electric Vehicles:Reduced energy budgets and aerodynamic front-end designs prioritize intelligent lighting control as standard equipment.
- Commercial Vehicles:Long-haul duty cycles and regulatory grandfathering create retrofit demand alongside factory fitment.
Passenger vehicles anchor volume procurement. Electric vehicles are climbing the fastest as platform designs mandate intelligent lighting.
End User:
Customer type shapes procurement concentration, validation requirements, and service network dependencies.
- Automotive Manufacturers:Consolidated ADAS platform contracts bundle high beam control with forward sensing suites. BMW, Mercedes-Benz, and Volkswagen Group specify integrated semiconductor and software stacks, compressing margins for pure-play optical vendors.
- Tier-1 Suppliers:Robert Bosch GmbH, HELLA GmbH & Co. KGaA, and Continental AG compete for module assembly contracts, absorbing REACH compliance costs and ISO 26262 ASIL-B certification investments.
- Aftermarket Providers:Dealer-installed upgrade kits serve regulatory grandfathering in Germany and France.
- Fleet Operators:Commercial vehicle leasing companies specify retrofit protocols for safety compliance across aging assets.
Automotive manufacturers dominate direct procurement. Aftermarket providers gain share fastest as fleet grandfathering extends addressable vehicle populations.
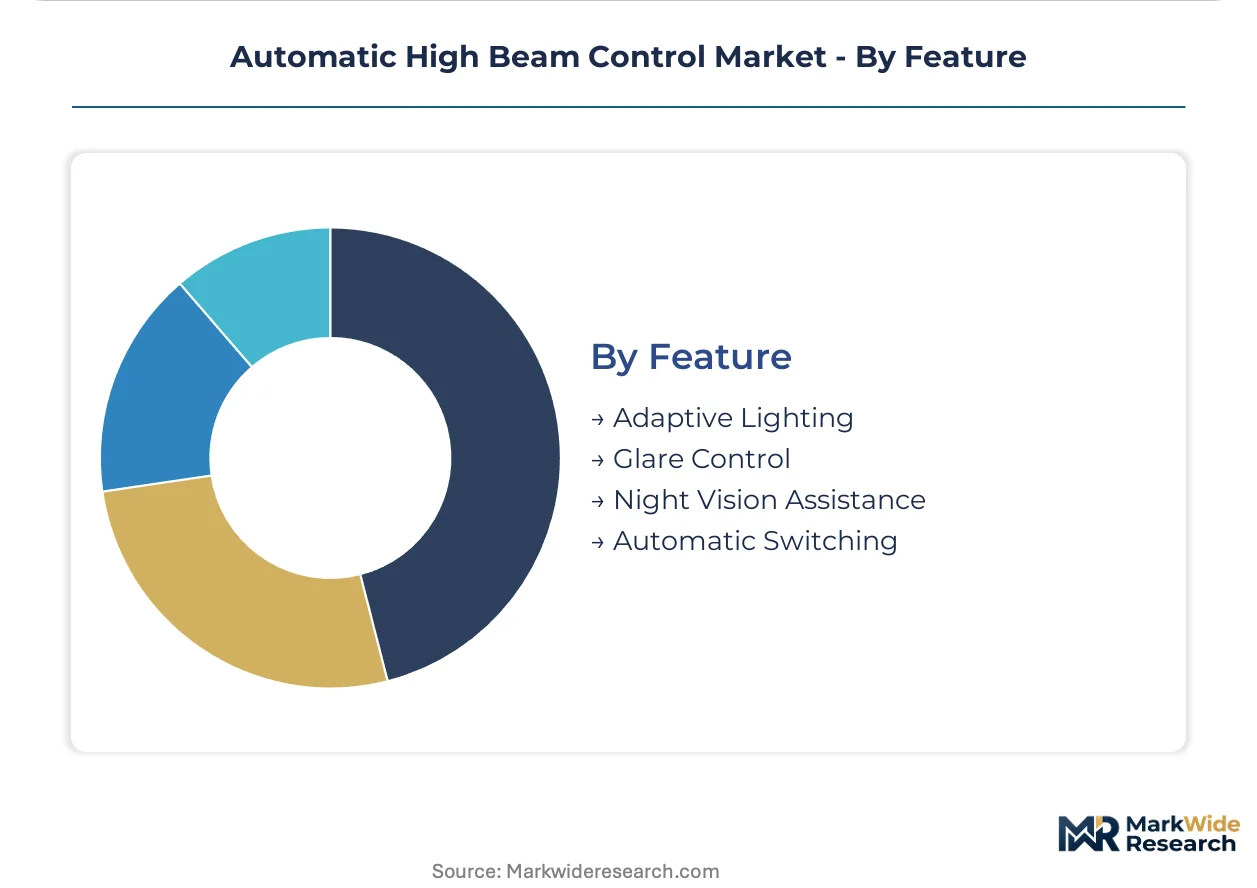
Feature:
Functional sophistication determines software complexity, calibration protocols, and regulatory validation burden.
- Adaptive Lighting:Dynamic beam shaping responds to steering angle, vehicle speed, and road curvature through electromechanical actuators. Bavarian engineering centers concentrate development here, serving German OEM matrix LED specifications.
- Glare Control:Selective dimming of individual LED segments masks oncoming vehicles without full beam shutdown. ECE R48 compliance and Euro NCAP scoring protocols mandate this functionality for top safety ratings.
- Night Vision Assistance:Thermal imaging integration extends detection range beyond visible spectrum limitations.
- Automatic Switching:Binary high-low beam transition based on ambient light thresholds represents baseline functionality.
Adaptive lighting holds the installed base. Glare control expands most quickly as matrix LED penetration accelerates across vehicle tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Euro NCAP protocols anchor European procurement patterns, while divergent regulatory frameworks across major automotive markets force dual-variant engineering strategies for suppliers seeking cross-border market access.
Germany
KBA type-approval requirements and Euro NCAP scoring mandates accelerate camera-based adaptive lighting integration across BMW, Mercedes-Benz, and Volkswagen Group platforms. Bavarian engineering centers in Munich and Ingolstadt concentrate matrix LED development, while Baden-Württemberg hosts sensor calibration facilities serving Tier-1 module assembly operations.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 imposes prescriptive beam geometry requirements that conflict with European performance-based standards. Michigan-based engineering operations and California technology clusters drive aftermarket retrofit demand as fleet operators seek compliance pathways for aging commercial vehicle assets.
China
MIIT vehicle certification standards and GB automotive lighting regulations shape domestic OEM specifications. Yangtze River Delta manufacturing corridors concentrate CMOS sensor packaging operations, while Beijing-Tianjin-Hebei clusters host emerging lidar integration facilities serving domestic electric vehicle platforms.
Japan
METI industrial policy supports advanced driver assistance system development through targeted R&D subsidies. Kanto region headquarters operations anchor Koito Manufacturing and Stanley Electric engineering centers, while Nagoya-area Chubu clusters supply optical component fabrication for hybrid camera-radar architectures.
India
PLI scheme production-linked incentives for automotive components attract module assembly investments serving domestic passenger vehicle programs and export markets. Tamil Nadu and Maharashtra manufacturing corridors concentrate Tier-1 supplier operations, while Karnataka technology clusters develop software-defined beam control algorithms for cost-optimized vehicle segments.
Automatic High Beam Control Market Vendor Landscape
Capability concentration sits with integrated semiconductor-software stack providers; scale advantage sits with diversified automotive component conglomerates. The vendor base organizes around three strategic archetypes: full-stack ADAS platform suppliers, specialized optical component manufacturers, and diversified electronics conglomerates with captive lighting divisions. Consolidation pressure intensifies as OEM procurement shifts toward bundled forward sensing contracts. Competitive moves center on backward integration into CMOS sensor sourcing and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Among German-based engineering-intensive suppliers, HELLA GmbH & Co. KGaA and Robert Bosch GmbH exemplify divergent strategic positions—HELLA representing specialized optical component manufacturing depth, Bosch representing integrated semiconductor-software stack control. Continental AG occupies a position spanning both archetypes through fused camera-radar headlight control architectures. Japanese specialists Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. anchor Asia-Pacific supply relationships, while Valeo represents European diversified conglomerate positioning with multi-regional manufacturing footprints.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Valeo |
| Continental AG |
| DENSO Corporation |
| Koito Manufacturing Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| HYUNDAI MOBIS |
| Others |
Supply Flow & Price Mechanics
CMOS sensor cost volatility in East Asian foundries compresses module pricing tiers while simultaneously forcing dual-sourcing investments across European Tier-1 suppliers. This semiconductor supply concentration widens spreads between camera-based standard modules and hybrid lidar-enabled premium configurations.
Pricing Analysis
Price spreads between German-engineered premium modules and Asian-assembled economy variants span three distinct tiers based on certification grade and software complexity. Premium-mid-economy pricing differentiation separates ASIL-B certified matrix LED systems from basic automatic switching functionality. Pricing pressure stems from foundry capacity constraints and REACH compliance cost absorption. Fleet operators exhibit highest price sensitivity, while German luxury marques prioritize performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at Robert Bosch semiconductor facilities in Reutlingen, HELLA optical component plants in Lippstadt, and Continental module assembly operations in Regensburg. German engineering centers feed from Taiwan CMOS sensor packaging, South Korean LED phosphor suppliers, and Japanese thermal interface material specialists. Single-source vulnerability in East Asian wafer foundries threatens module availability. Distribution runs through consolidated ADAS platform contracts bundling lighting with forward sensing suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as OEM procurement shifts from standalone headlamp modules toward bundled ADAS platform contracts. This consolidation trend fragments addressable niches for specialized component suppliers and regional aftermarket providers.
For Market Incumbents: Insulate margin pools by deepening backward integration into CMOS sensor sourcing and securing captive calibration facility capacity in Baden-Württemberg. Defend against pure-play optical vendor displacement by embedding software-defined beam control within consolidated forward sensing contracts. Prioritize ISO 26262 ASIL-B certification investments as a compliance moat. For New Entrants and Emerging Players: India's PLI-subsidized manufacturing corridors offer the most penetrable entry vector for module assembly serving domestic and export markets. Target aftermarket retrofit channels in Germany and France where regulatory grandfathering extends addressable vehicle populations. Pursue dealer-certified upgrade kit partnerships as a low-capital go-to-market pathway. For Investors and Strategic Acquirers: EU General Safety Regulation mandates reshapes the acquisition landscape by converting automatic high beam from optional premium feature to baseline compliance requirement. Long-term viability favors targets with integrated semiconductor-software stacks over pure-play optical component manufacturers. Monitor Euro NCAP protocol evolution as the primary inflection signal for technology valuation step-changes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CMOS Sourcing | Reduces exposure to Taiwan foundry allocation disruptions and stabilizes module cost structures. |
| Camera-Radar Fusion Architecture Development | Enables predictive beam adjustment for Level 2+ highway automation programs at Continental and Bosch. |
| PLI Scheme Manufacturing Footprint Expansion | Captures production-linked incentives in Tamil Nadu corridors serving Indian OEM and export demand. |
| Digital Micromirror Device Platform Adoption | Texas Instruments technology migration enables pixel-precise beam shaping for German luxury marques. |
| Aftermarket Retrofit Channel Partnership | Dealer-installed upgrade kits address regulatory grandfathering in German and French fleet segments. |
Methodological Framework
Desk research of regulatory filings from KBA and NHTSA, vehicle production databases, and Tier-1 supplier technical disclosures preceded structured interviews with OEM platform engineers, Tier-1 procurement directors, and aftermarket distribution heads. Primary fieldwork across Bavarian engineering centers and Baden-Württemberg calibration facilities combined with secondary validation from Euro NCAP assessment protocols and ECE R48 documentation. Bottom-up module shipment estimates triangulated against top-down ADAS platform contract values.
Assumptions held fixed include current Euro NCAP scoring protocols and EU General Safety Regulation enforcement timelines, while sensor cost trajectories and lidar unit economics varied across sensitivity scenarios. Segmentation dimensions encompassed technology tier, vehicle application, and procurement channel. CAGRs derived from installed base expansion and content-per-vehicle growth across passenger and electric vehicle platforms. Forecast inputs incorporated CMOS sensor pricing indices and REACH compliance cost absorption rates.
Practitioners should monitor East Asian foundry capacity allocation announcements and Euro NCAP protocol revision drafts for early signals of supply constraint or regulatory step-change. Forecasts reflect these documented assumptions and baseline conditions. Quarterly review of semiconductor spot pricing and Tier-1 module contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market