
 Construction Machinery Wiring Harness Market | 2026-2036
Construction Machinery Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Machinery Wiring Harness Market Outlook
IP67-rated and high-voltage specification tiers is rotating through the construction machinery wiring harness market as electrified equipment penetrates earthmoving fleets. Leoni AG leverages its European manufacturing footprint to supply sealed harness systems for hybrid excavators. Yazaki Corporation anchors its position through backward integration into connector design for severe-duty applications. TE Connectivity Ltd. competes on sensor-integration density within power distribution harnesses.
A construction machinery wiring harness is an engineered assembly of conductors, connectors, and protective sheathing—typically rated for 12V to 800V operation—that transmits electrical power and control signals between engine components, hydraulic systems, and operator interfaces in mobile heavy equipment. Copper conductor bundles with cross-linked polyethylene insulation dominate where thermal cycling and abrasion resistance prove critical. Power harnesses for electrified drivetrains capture expanding margin pools as voltage ratings climb, while signal harnesses for telematics and machine control sustain premium positioning through shielding complexity. Excavator applications lead unit volume given the segment's sensor density and boom articulation demands.
The EPA, EU Green Deal, and China's MEE collectively enforce emissions thresholds and energy-efficiency benchmarks that compel harness redesigns for electrified powertrains and regenerative systems. ISO 6722 and SAE J1128 standards govern conductor sizing and insulation grades, creating compliance barriers for non-certified suppliers. Stakeholders must monitor regulatory divergence between North American voltage standards and European high-voltage architectures when allocating R&D across product platforms.
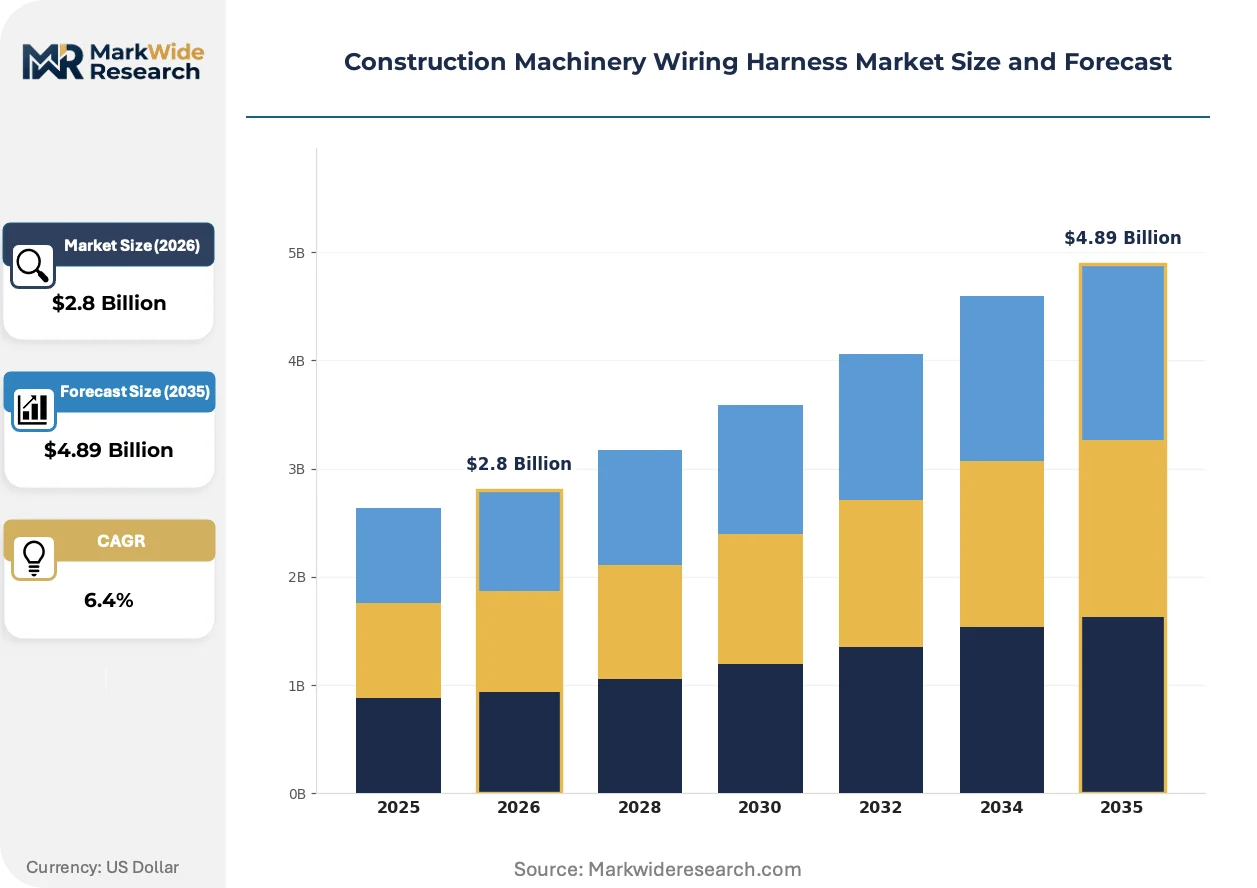
Market Dynamics
Electrification mandates from the EPA and EU Green Deal are forcing harness manufacturers to reengineer product architectures for high-voltage compatibility, compressing development cycles and rewiring supplier relationships across construction equipment supply chains.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emissions frameworks:These regulations compel OEMs to integrate electrified powertrains, generating demand for 800V-rated harness systems with enhanced thermal management.
- China's intelligent construction equipment rollout:Domestic OEMs in this market are scaling production of sensor-dense excavators and autonomous dozers, requiring complex signal harness bundles for machine control and telematics.
- Copper-clad aluminum conductor technology:This material innovation reduces harness weight by 30-40% compared to pure copper, enabling fuel efficiency gains in hybrid earthmoving fleets.
Market Restraints
- Copper price volatility:Raw material cost swings compress margin pools for harness assemblers, particularly those locked into fixed-price contracts with heavy equipment OEMs.
- Connector supply concentration in East Asia:Specialized high-voltage connector production clusters in Taiwan and South Korea create single-source vulnerability for European and North American harness manufacturers.
- Cross-linked polyethylene insulation limitations:Current XLPE formulations face durability challenges in Arctic operating conditions, restricting addressable market penetration for extreme-climate equipment.
Strategic Opportunities
- India's infrastructure build-out:The country's National Infrastructure Pipeline is accelerating excavator and motor grader deployment, creating demand for cost-optimized harness configurations suited to tropical humidity and dust exposure.
- Battery-electric construction equipment telematics integration:Convergence of high-voltage power distribution with real-time battery management systems enables premium-priced smart harness architectures.
- EU Green Deal carbon border adjustments:These mechanisms favor regional harness suppliers with verified low-carbon production footprints, creating competitive moats against imports.
Industry Challenges
- High-voltage safety engineering talent scarcity:The specialized skill set for 800V system design and arc-fault prevention remains concentrated among automotive EV engineers, forcing construction harness makers to compete for limited personnel.
- ISO 6722 and SAE J1128 certification timelines:Extended validation periods for new conductor grades delay product launches, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Machinery Wiring Harness Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Harness, Signal Harness, Control Harness, Combination Harness Application: Excavators, Bulldozers, Cranes, Loaders Material: Copper, Aluminum, PVC, Polyethylene End User: OEMs, Aftermarket Providers, Construction Companies, Fleet Managers |
| Companies Covered | Furukawa Electric Co. ltd., Leoni AG, Motherson Sumi Systems Limited, AME Systems Proprietary Limited, Electronic Technologies International, Inc., Sumitomo Wiring Systems Limited, Yazaki Corporation, TE Connectivity Ltd., Amphenol-CTI Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Machinery Wiring Harness Market Strategic Shifts
Silicone-based insulation compounds and modular connector architectures are reshaping harness durability standards, while digital thread technologies enable predictive maintenance integration across electrified construction fleets.
Silicone rubber insulation is supplanting traditional XLPE in high-voltage construction equipment harnesses due to superior thermal stability across -60°C to 200°C operating ranges. Hybrid excavator OEMs in Germany and Japan are adopting these compounds fastest, driven by warranty extension requirements. This material transition is supplanting legacy harness designs optimized solely for cost, compressing supplier margins on standard-grade products while opening premium tiers.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of harness jacketing materials across European-sourced equipment. Manufacturers must now qualify phosphorus-nitrogen intumescent systems that maintain UL94 V-0 ratings without brominated compounds. Excavator and wheel loader segments face the steepest compliance curves, with German OEMs already mandating full halogen-free harness architectures in 2025 model year machines.
Construction fleet managers are consolidating harness procurement under single-source agreements with integrated power distribution suppliers, displacing fragmented component sourcing. Equipment rental companies in the United States are driving this consolidation fastest, seeking unified warranty coverage and simplified field service logistics. This buyer concentration is visible most acutely in the North American compact equipment segment, where telematics-enabled harness bundles now anchor multi-year service contracts.
Construction Machinery Wiring Harness Market Segmentation
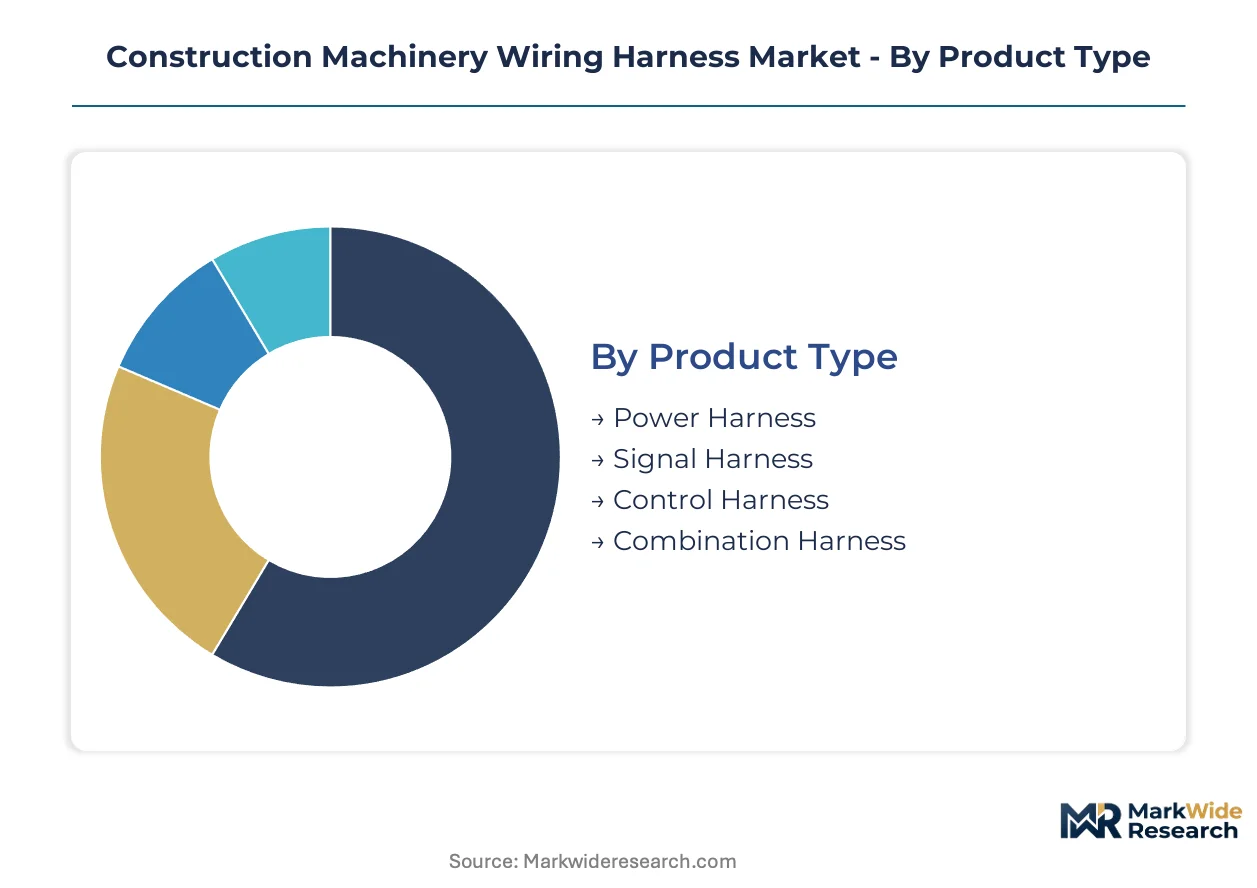
Wiring harness segmentation in construction machinery reflects divergent technical requirements across electrified powertrains, sensor-dense control systems, and severe-duty environmental exposure. Product architecture choices directly determine voltage tolerance, thermal cycling durability, and field service complexity for heavy equipment OEMs.
Product Type:
Signal harness architectures face intensifying substitution pressure from wireless telemetry modules and CAN bus consolidation, while power harnesses defend their physical wire necessity through high-current safety mandates.
- Power Harness:Engineered for 12V to 800V current transmission with cross-linked polyethylene insulation and braided copper conductors. Demand concentrates in German and Japanese hybrid excavator programs where EPA Tier 4 Final and EU Stage V electrification requirements mandate high-voltage distribution architectures. Thermal management specifications now exceed 150°C continuous operation for battery-electric drivetrains.
- Signal Harness:Multi-conductor bundles with twisted-pair shielding for sensor data, control inputs, and telematics transmission. China's intelligent construction equipment rollout absorbs the densest sensor harness configurations, with domestic OEMs specifying 40+ conductor counts for autonomous dozer machine control systems. Shielding complexity sustains premium positioning against wireless alternatives.
- Control Harness:Relays command signals between operator interfaces and hydraulic actuators, typically operating at 24V with abrasion-resistant jacketing.
- Combination Harness:Integrates power, signal, and control functions within unified cable assemblies for compact equipment footprints.
Power harness retains volume leadership; signal harness holds the steepest expansion curve.
Application:
Equipment type dictates harness routing complexity, with boom articulation and cab rotation creating divergent flex-cycle durability requirements across earthmoving categories.
- Excavators:Harness systems must survive 180-degree boom swing cycles and stick-to-bucket hydraulic routing across 10,000+ hour service lives. Japanese OEMs specify the most demanding flex-test protocols, driving adoption of silicone-insulated conductor bundles for thermal stability across -40°C to 180°C ranges. Sensor density for grade control and telematics integration elevates harness mass by 15-20% versus standard configurations.
- Loaders:Articulated chassis designs concentrate harness stress at the pivot joint, requiring reinforced strain relief and sealed connector architectures. North American compact wheel loader production scales fastest for rental fleet telematics integration, with unified warranty coverage driving single-source procurement consolidation.
- Bulldozers:Track vibration and blade impact exposure demand heavy-gauge jacketing and grommet-protected pass-through points.
- Cranes:Telescoping boom sections require retractable cable carriers and slip-ring assemblies for continuous power transmission.
Excavators dominate unit volume; loaders gain share fastest through compact equipment electrification.
Material:
Conductor and insulation material selection trades electrical performance against weight reduction targets and regulatory compliance burdens.
- Copper:Pure electrolytic copper remains the conductivity benchmark for high-current power harnesses, with oxygen-free grades specified for critical signal integrity applications. Price volatility on the London Metal Exchange compresses assembler margins, particularly for North American OEMs locked into annual contract pricing.
- Aluminum:Copper-clad aluminum conductors reduce harness mass by 30-40% versus pure copper, enabling fuel efficiency gains in hybrid earthmoving fleets. German OEMs have qualified aluminum power distribution for auxiliary circuits, though main drivetrain harnesses retain copper for termination reliability.
- Polyethylene:Cross-linked formulations dominate abrasion-resistant jacketing for severe-duty construction exposure.
- PVC:Standard-grade insulation persists in cost-optimized harnesses for emerging market equipment, though REACH Annex XVII halogen restrictions constrain European-sourced applications.
Copper retains volume leadership; aluminum climbs the fastest on weight-reduction engineering.
End User:
Procurement authority concentration distinguishes integrated OEM specification from fragmented aftermarket replacement demand.
- OEMs:Original equipment manufacturers specify harness architectures during platform development, locking in 5-7 year production commitments. China's domestic construction equipment OEMs are scaling fastest, with Sany and XCMG qualifying new supplier bases for intelligent machine sensor integration.
- Fleet Managers:Large rental and contractor fleets in the United States are consolidating harness procurement under multi-year service contracts, displacing fragmented component sourcing. Telematics-enabled harness bundles now anchor unified warranty coverage agreements.
- Aftermarket Providers:Independent distributors serve repair and replacement demand, typically competing on availability rather than specification innovation.
- Construction Companies:Owner-operators with captive fleets represent sporadic demand concentrated in emerging market infrastructure projects.
OEMs retain volume leadership; fleet managers hold the steepest expansion curve through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harness assembly capacity clusters in Germany, China, Japan, and the United States, with supplier networks radiating from established automotive electrification corridors into construction equipment supply chains.
United States
EPA Tier 4 Final emissions frameworks drive OEM electrification programs across excavator and wheel loader fleets. The Infrastructure Investment and Jobs Act channels federal funding toward domestic equipment manufacturing. Detroit-area harness suppliers are scaling high-voltage production lines to serve hybrid earthmoving programs.
Germany
EU Stage V regulations and the EU Green Deal carbon border adjustment mechanism reshape procurement toward low-carbon harness architectures. REACH Annex XVII halogen restrictions mandate jacketing reformulation for export-bound equipment. Stuttgart and Munich industrial corridors host specialized suppliers for sealed harness systems in hybrid excavators.
China
Domestic OEMs scale intelligent construction equipment production with dense sensor integration for autonomous machine control. MEE emissions thresholds and dual carbon goals accelerate battery-electric drivetrain adoption. Xuzhou and Changsha manufacturing clusters concentrate harness demand from Sany and XCMG production lines.
Japan
JIS standards and METI energy-efficiency benchmarks govern conductor sizing and thermal management specifications. Japanese OEMs specify the most demanding flex-test protocols for boom articulation durability. Nagoya-area suppliers anchor production for silicone-insulated harness bundles in premium excavator platforms.
India
The National Infrastructure Pipeline accelerates excavator and motor grader deployment across highway and rail projects. BIS certification requirements and PLI scheme incentives attract component localization. Pune and Chennai industrial zones emerge as assembly hubs for cost-optimized harness configurations suited to tropical operating conditions.
Construction Machinery Wiring Harness Market Competitive Environment
Concentration sits with diversified electrical component conglomerates that leverage automotive EV engineering capabilities into construction equipment applications. The vendor base stratifies across three tiers: integrated global suppliers with full power distribution portfolios, regional specialists focused on severe-duty sealing technologies, and cost-optimized assemblers serving emerging market OEMs. Dominant competitive moves include backward integration into connector design and strategic partnerships with battery-electric drivetrain developers.
Within the integrated global tier, Leoni AG and Yazaki Corporation exemplify archetypes with European and Asian manufacturing footprints respectively. TE Connectivity Ltd. occupies a position emphasizing sensor-integration density. Among diversified Japanese electrical conglomerates, Furukawa Electric Co., Ltd. and Sumitomo Wiring Systems Limited represent scale-driven anchors with cross-sector harness capabilities extending from automotive into heavy equipment verticals.
| Leading Market Players |
|---|
| Furukawa Electric Co. ltd. |
| Leoni AG |
| Motherson Sumi Systems Limited |
| AME Systems Proprietary Limited |
| Electronic Technologies International, Inc. |
| Sumitomo Wiring Systems Limited |
| Yazaki Corporation |
| TE Connectivity Ltd. |
| Amphenol-CTI Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Copper-clad aluminum conductor substitution is redrawing procurement geography toward East Asian smelters while compressing pricing power for European harness assemblers locked into fixed-cost copper contracts. This material transition simultaneously elevates margin pressure on legacy copper-dependent suppliers and opens cost-advantaged tiers for hybrid equipment fleets.
Pricing Analysis
EPA Tier 4 Final and EU Stage V dictate the pricing tier structure across certification-grade harness architectures. Three-tier pricing stratifies across IP67-sealed premium bundles, standard XLPE-insulated configurations, and economy-grade PVC alternatives for emerging market equipment. Price differentiation hinges on voltage rating tier and ISO 6722 certification status. Cost compression in economy tiers is intensifying because Chinese OEMs are qualifying domestic connector sources. Fleet managers in North America exhibit lowest price sensitivity due to unified warranty bundling, while Indian infrastructure contractors drive hardest bargain negotiations.
Supply Chain Analysis
Just-in-time inventory protocols dominate harness assembly for German and Japanese OEM platforms, while Chinese and Indian suppliers maintain strategic copper conductor stockpiles against London Metal Exchange volatility. Production gravity centers on Germany, China, and Japan, with connector fabrication concentrated in Taiwan and South Korea. Raw material flows draw from Chilean copper cathode, Japanese silicone rubber compounds, and German cross-linking equipment. Single-source vulnerability in high-voltage connector supply creates structural risk for Western assemblers. Distribution runs through captive OEM supply agreements and consolidated fleet service contracts rather than fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction machinery wiring harness market is entering a cyclical upswing driven by infrastructure stimulus deployment across India and the United States. Recovery durability hinges on electrification program continuity through regulatory enforcement cycles.
For Market Incumbents: Secure backward integration into high-voltage connector design to defend against Taiwanese single-source chokepoints. Anchor capacity expansion in Xuzhou and Stuttgart industrial corridors to capture Chinese intelligent equipment rollout and EU carbon border adjustment advantages. Certification investment in 800V arc-fault prevention engineering addresses talent scarcity threats from automotive EV competition. For New Entrants and Emerging Players: Lead with cost-optimized aluminum conductor harnesses for India's National Infrastructure Pipeline excavator deployments. Target motor grader and compact loader segments where incumbent coverage remains thin and specification barriers sit lower than premium excavator tiers. Partner with domestic Indian OEMs on tropical-grade sealing validation to accelerate qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier regional specialists with captive silicone compounding capabilities and verified low-carbon production footprints. Long-term viability favors suppliers positioned across battery-electric and hybrid architectures rather than pure ICE legacy exposure. Watch EPA enforcement intensity on Tier 4 Final compliance deadlines as inflection indicator for electrification capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Connector Design | Reduces single-source dependency on Taiwanese high-voltage component suppliers for 800V harness architectures. |
| Silicone Insulation Compounding Capacity | Captures premium tier positioning as REACH Annex XVII halogen restrictions displace legacy XLPE formulations. |
| Regional Manufacturing Footprint Expansion | Positions suppliers to qualify for EU Green Deal carbon border adjustments and Indian PLI scheme incentives. |
| Battery-Electric Drivetrain Partnership | Locks in specification influence during OEM platform development for telematics-integrated smart harness bundles. |
| High-Voltage Safety Engineering Talent Acquisition | Addresses scarcity of 800V arc-fault prevention expertise concentrated among automotive EV engineering pools. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and OEM procurement disclosures. Primary inputs drew from harness engineering directors at Tier 1 suppliers, procurement leads at Sany and XCMG, fleet maintenance managers at United States rental companies, and silicone materials specialists at German compounding firms. Secondary validation incorporated EPA enforcement data, EU ECHA REACH registration databases, London Metal Exchange copper price series, and construction equipment production registries. Bottom-up unit demand modeling triangulated against top-down OEM capex projections.
Segmentation dimensions modeled span product type (power, signal, control, combination), application equipment category (excavator, loader, bulldozer, crane), conductor material (copper, aluminum), and end-user procurement authority (OEM, fleet manager, aftermarket). CAGRs were derived from regression analysis of historical OEM production volumes against electrification penetration curves and infrastructure spending forecasts. Industry-specific inputs included hybrid excavator program launch schedules, MEE emissions threshold implementation timelines, and copper-clad aluminum qualification status at German OEMs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement on EPA Tier 4 Final and EU Stage V compliance deadlines would require recalibration. Forecasts assume continued copper price volatility within historical bands and stable connector supply from East Asian manufacturing clusters. Revision becomes warranted when high-voltage safety engineering talent migration from automotive to construction sectors crosses threshold levels that compress development cycle timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market