
 Segway Market | 2026-2036
Segway Market Size, Share, and Industry Trends Forecast 2026-2036
Segway Market Analysis
Chinese manufacturing capacity is shifting toward higher-output lithium-ion assembly lines for personal electric vehicles. Segway-Ninebot leverages its integrated supply chain to dominate urban mobility deployments across Asia-Pacific. Razor anchors the North American consumer channel through established retail partnerships. Apollo competes on performance-tier specifications, sustaining R&D intensity in suspension and motor systems.
A Segway is a self-balancing, battery-powered personal transporter built around gyroscopic stabilization sensors, dual electric motors, and a lithium-ion or lithium-polymer pack typically rated between 54V and 74V, designed to carry one rider at speeds up to 20 km/h for short-distance commercial and recreational transit. Electric scooters lead product type revenue due to fleet-scale purchases by shared mobility operators, while personal transporters retain premium margins in enterprise security and guided tourism. Tour operators represent the fastest-growing end user segment as European cities expand pedestrian-zone access permits for supervised group circuits.
The National Highway Traffic Safety Administration in the United States classifies certain Segway-type devices as motor vehicles when operated on public roads, triggering compliance requirements that vary by municipality and constrain interstate sales. China's Ministry of Industry and Information Technology enforces GB standards for electric vehicle battery safety and electromagnetic compatibility, directly shaping export-ready product configurations. Stakeholders must monitor evolving municipal access rules and battery certification reciprocity agreements to anticipate which geographies will open or restrict sidewalk and roadway operation.
Market Dynamics
Fleet operators in shared mobility are consolidating procurement decisions around UL 2272-certified electric scooters, compressing supplier qualification timelines and reshaping competitive access to urban deployment contracts.
Growth Catalysts
- Last-mile fleet electrification:Urban logistics operators are replacing gasoline-powered last-mile vehicles with electric scooters to comply with municipal zero-emission zones in Barcelona, Paris, and Milan.
- GB standard alignment:China's MIIT battery safety mandates for personal electric vehicles are creating export-ready product configurations that satisfy electromagnetic compatibility requirements in multiple destination markets.
- Lithium-ion energy density gains:Solid-state electrolyte research is extending single-charge range capabilities for commercial security patrol applications requiring extended duty cycles.
Market Restraints
- Cobalt and lithium price volatility:Raw material input costs for battery cathodes fluctuate with Democratic Republic of Congo mining output and Chilean brine extraction quotas.
- Shenzhen-Suzhou supply concentration:Over 70 percent of personal transporter controller board and motor assembly capacity sits within a 200-kilometer corridor, creating single-point-of-failure exposure.
- NHTSA motor vehicle classification:Federal treatment of Segway-type devices as motor vehicles on public roads triggers disparate municipal compliance requirements that constrain interstate commerce.
Strategic Opportunities
- Indian urban micromobility:Metro rail expansion in Bengaluru, Delhi, and Mumbai is creating first-mile-last-mile connectivity gaps that electric scooter fleets could address through station-based rental hubs.
- Guided tourism permit liberalization:European cities including Lisbon, Prague, and Vienna are expanding pedestrian-zone access for supervised group circuits using self-balancing transporters.
- EU Green Deal procurement incentives:Public sector fleet replacement mandates for municipal security and postal services are creating preferential purchasing frameworks for zero-emission personal mobility devices.
Industry Challenges
- Embedded systems firmware expertise:Gyroscopic stabilization algorithm development requires scarce talent pools combining control theory and real-time sensor fusion capabilities.
- UL 2272 certification timeline compression:Third-party electrical systems safety testing for lithium-ion battery packs and charging circuits extends product launch schedules by four to six months.
- Patent thickets in self-balancing control:Licensing complexity around inverted pendulum stabilization intellectual property creates barriers for new entrants in personal transporter segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Segway Market |
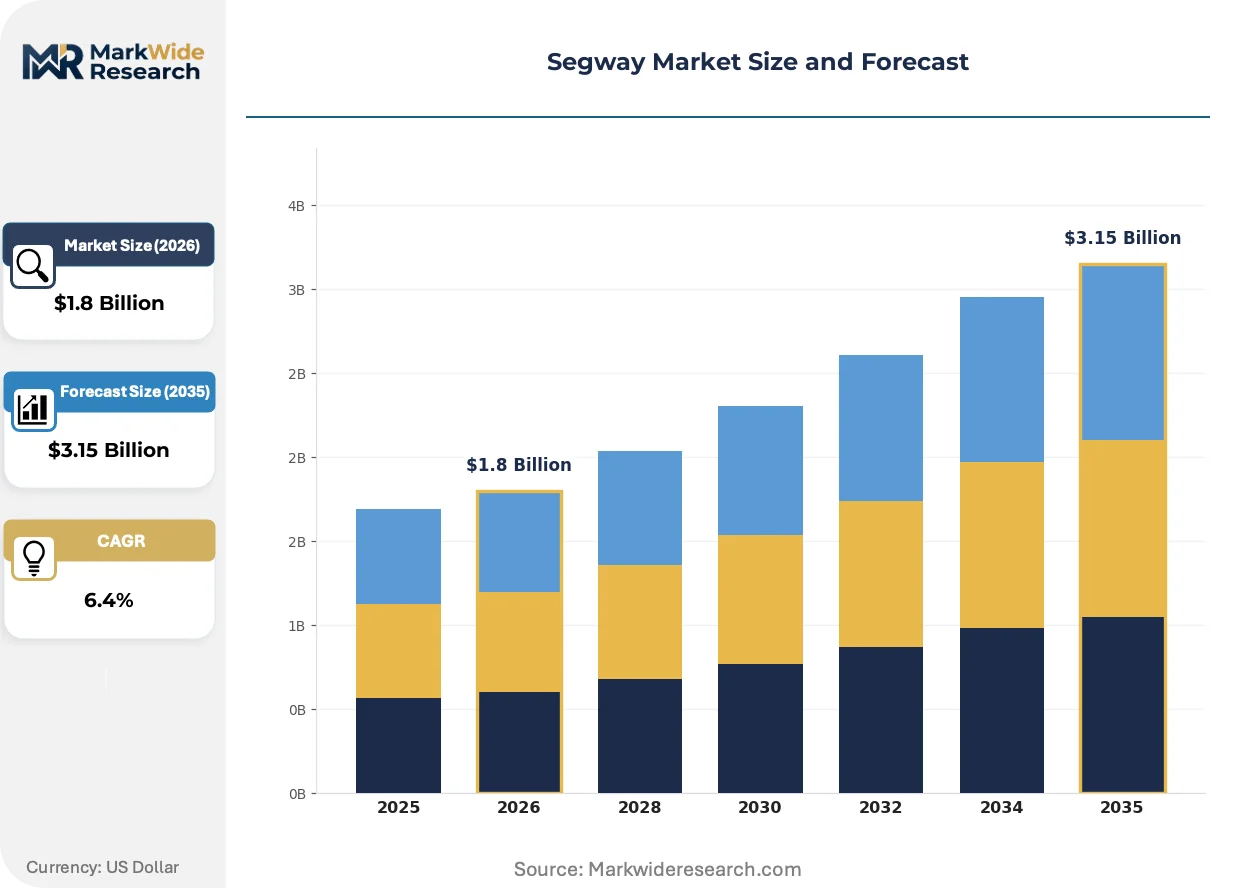
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Scooters, Electric Scooters, Personal Transporters, Mini Segways End User: Consumers, Enterprises, Tour Operators, Government Agencies Application: Parks & Recreation, Urban Mobility, Tourism, Security Services Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Razor, Dualtron, Segway-Ninebot, Gotrax, Apollo, Xiaomi, Boosted, Hiboy, Unagi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Segway Market Emerging Trajectories
Solid-state battery chemistry and artificial intelligence-based predictive maintenance are converging to extend asset lifecycles in commercial fleet deployments. Regulatory frameworks are simultaneously tightening battery safety certification requirements while opening new urban access corridors.
Solid-state lithium-metal cells are replacing conventional liquid electrolyte architectures in premium fleet specifications. Shared mobility operators in Singapore and Dubai are piloting these packs for reduced thermal runaway risk and faster charging protocols. This chemistry transition is rewriting total cost of ownership calculations for operators running 24-hour utilization models.
The EU's forthcoming battery passport requirements under the CSRD will mandate full supply chain traceability for lithium, cobalt, and nickel inputs. Manufacturers serving European markets must deploy blockchain-verified chain-of-custody systems by 2027. Personal electric vehicle importers in Germany and the Netherlands are front-loading compliance investments to secure preferential fleet procurement status.
Subscription-based fleet management is displacing outright purchase models among North American campus security departments and European tour operators. Equipment-as-a-service contracts bundle hardware, maintenance, and insurance into per-vehicle monthly fees. This shift is most visible in California and Florida where municipal liability concerns favor operational expenditure treatment over capital asset ownership.
Segway Market Segmentation
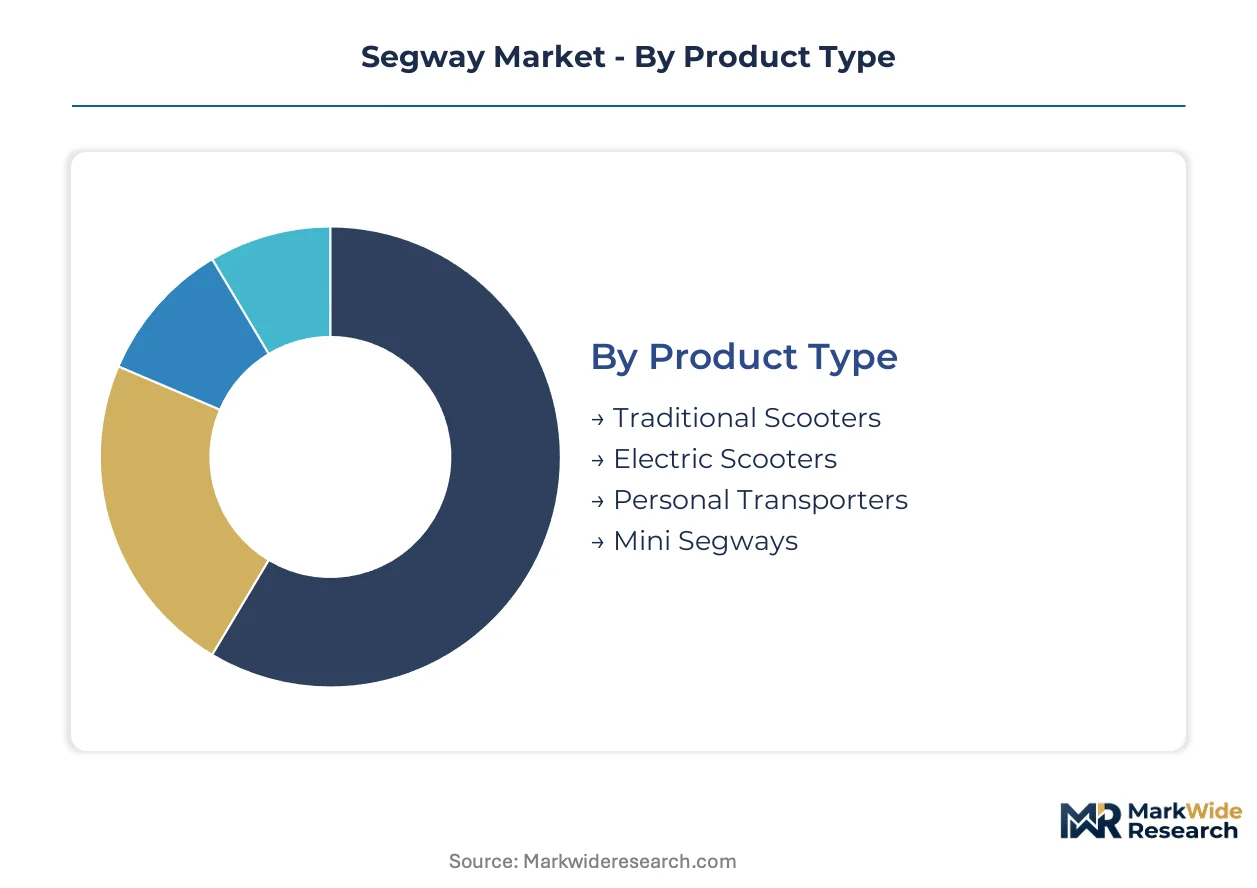
Segmentation in the Segway market reveals divergent commercial logics across procurement channels and use cases. Fleet-scale deployments demand certified durability and standardized service protocols, while consumer purchases prioritize portability and price accessibility.
Product Type:
Volume leadership concentrates in electric scooters, yet premium margins attach to specialized personal transporters engineered for extended duty cycles.
- Electric Scooters:These devices integrate 54V-74V lithium-ion packs with brushless hub motors rated for 250W-500W continuous output. Shared mobility operators in Barcelona, Paris, and Milan are consolidating procurement around UL 2272-certified models to satisfy municipal zero-emission zone mandates.
- Personal Transporters:Self-balancing platforms deploy gyroscopic stabilization algorithms and dual-motor architectures for enterprise security patrols. Commercial fleets in Singapore and Dubai are piloting solid-state battery configurations to extend single-charge range for 24-hour utilization models.
- Traditional Scooters:Unpowered kick-scooter designs retain niche demand in recreational retail channels where price sensitivity dominates purchase decisions.
- Mini Segways:Compact form factors with reduced wheel diameters target adolescent consumers and indoor facility applications requiring maneuverability over speed.
Mature deployment sits with personal transporters in enterprise security. Newer deployment is concentrated in electric scooters for urban mobility fleets.
End User:
Procurement authority is fragmenting across customer types with divergent specification requirements and contract structures.
- Tour Operators:Supervised group circuit operators in Lisbon, Prague, and Vienna are securing expanded pedestrian-zone access permits from municipal authorities. Equipment-as-a-service contracts are displacing outright purchases among European guided tourism providers.
- Enterprises:Campus security departments and logistics operators demand predictive maintenance capabilities and fleet management dashboards. North American procurement is shifting toward subscription-based models that bundle insurance and maintenance into operational expenditures.
- Consumers:Individual purchasers prioritize retail availability and price accessibility through established sporting goods channels.
- Government Agencies:Postal services and municipal security departments are accessing EU Green Deal procurement incentives for zero-emission fleet replacement.
Contract maturity sits with enterprise fleet operators. Permit-driven expansion is climbing fastest among tour operators.
Application:
Use case segmentation tracks regulatory access corridors and infrastructure availability across urban environments.
- Urban Mobility:Last-mile connectivity deployments integrate with metro rail systems in Bengaluru, Delhi, and Mumbai. Station-based rental hubs are emerging around expanding mass transit networks.
- Security Services:Patrol applications require extended-range battery configurations and ruggedized suspension systems for continuous duty cycles.
- Tourism:Supervised circuit operations depend on municipal permit liberalization for pedestrian-zone access in historic city centers.
- Parks & Recreation:Recreational use concentrates in controlled environments with limited regulatory complexity and lower duty cycle requirements.
Established deployment sits with security services. Steepest expansion trajectory is gaining share in urban mobility.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and certification documentation needs.
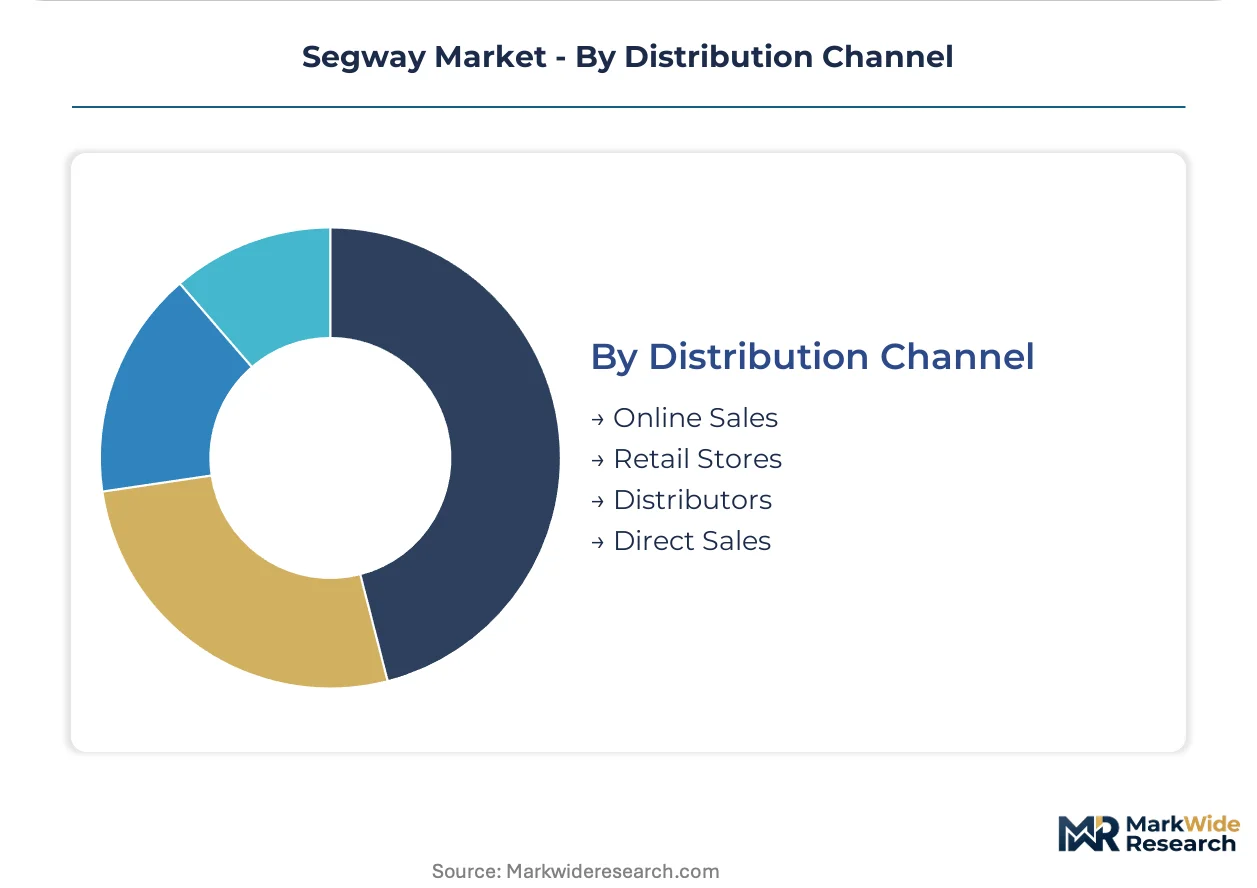
- Distributors:Fleet operators rely on regional distributors for bulk procurement, localized service networks, and UL 2272 certification documentation.
- Direct Sales:Large enterprise and government accounts negotiate equipment-as-a-service contracts directly with manufacturers for customized fleet management integration.
- Online Sales:Consumer purchases flow through direct-to-consumer platforms with price transparency and shipping logistics for compact form factors.
- Retail Stores:Sporting goods and electronics retailers anchor consumer channel access with immediate product availability and hands-on evaluation.
Volume concentration sits with distributor networks. Newer deployment is concentrated in direct sales for enterprise subscription contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cobalt and lithium extraction in the Democratic Republic of Congo and Chilean brine fields anchors upstream material flows for battery assembly. Manufacturing gravity concentrates in Chinese coastal provinces, while deployment clusters emerge around metropolitan transit networks in Europe and North America.
United States
Campus security departments in California and Florida are adopting subscription-based fleet management models. NHTSA classification of certain Segway-type devices as motor vehicles triggers disparate municipal compliance requirements that constrain interstate commerce. Manufacturing concentrates around West Coast electronics assembly corridors serving consumer retail channels.
Germany
EU Green Deal procurement incentives are driving municipal security and postal service fleet replacement programs. KBA enforcement of CE marking and battery passport requirements under CSRD mandates shapes import documentation standards. Industrial clustering in Baden-Württemberg supports precision controller board fabrication for premium fleet specifications.
China
Domestic tour operator adoption and manufacturing cluster density sustain volume leadership in personal transporter production. MIIT enforcement of GB standards for battery safety and electromagnetic compatibility directly shapes export-ready product configurations. The Shenzhen-Suzhou corridor houses over seventy percent of controller board and motor assembly capacity within a two-hundred-kilometer radius.
France
Paris municipal zero-emission zone mandates are accelerating last-mile fleet electrification among urban logistics operators. ANSM oversight of product safety notification procedures affects import clearance timelines for lithium-ion powered devices. Manufacturing presence concentrates in Île-de-France assembly facilities serving Western European distribution networks.
India
Metro rail expansion in Bengaluru, Delhi, and Mumbai is creating first-mile-last-mile connectivity gaps for station-based rental hub deployment. BIS certification requirements for electrical vehicle components establish technical barriers for imported personal transporter configurations. Industrial activity clusters in Maharashtra and Karnataka around electronics manufacturing zones with battery pack assembly capabilities.
Segway Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue performance-tier differentiation through suspension and motor system specialization. Market structure reflects a bifurcated pattern with integrated supply chain operators commanding fleet procurement channels while retail-focused entities anchor consumer accessibility. Three archetypes dominate: vertically integrated manufacturers with captive battery assembly, performance-tier specialists emphasizing technical specifications, and retail-channel anchors leveraging established distribution partnerships. Competitive dynamics center on certification timeline acceleration and geographic expansion into permit-liberalizing municipal markets.
Among Asia-Pacific-based integrated manufacturers, Segway-Ninebot exemplifies the vertically integrated archetype with captive supply chain control, while Xiaomi occupies a position bridging consumer electronics scale with personal mobility diversification. Apollo represents the performance-tier specialist archetype, anchoring R&D-intensive positioning in suspension and motor system engineering. These three entities collectively illustrate the strategic segmentation between scale-driven manufacturing, technical specialization, and ecosystem leverage that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Razor |
| Dualtron |
| Segway-Ninebot |
| Gotrax |
| Apollo |
| Xiaomi |
| Boosted |
| Hiboy |
| Unagi |
| Others |
Supply Flow & Price Mechanics
Solid-state battery chemistry transitions are compressing cost curves for premium fleet specifications while simultaneously redrawing supplier qualification maps around UL 2272 and GB standard compliance. This dual transformation concentrates pricing power among vertically integrated manufacturers with captive cell assembly, while fragmenting margin pools for modular assemblers dependent on third-party certification timelines.
Pricing Analysis
Warranty and predictive maintenance bundling now separates subscription-based fleet contracts from transactional hardware sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and battery chemistry, with UL 2272-certified solid-state configurations commanding service-inclusive premiums. Pricing pressure stems from cobalt and lithium price volatility feeding through cathode costs. Shared mobility operators exhibit lowest price sensitivity due to operational expenditure treatment, while consumer retail channels face acute margin compression.
Supply Chain Analysis
UL 2272 and GB standard certification gating compresses qualified supplier lists to manufacturers with in-house electrical systems testing. Controller board and motor assembly concentrates in China, South Korea, and Taiwan, with battery cell supply anchored in Chinese coastal provinces and South Korean chemical complexes. Raw material flows draw from Chilean brine fields and DRC mining operations for lithium and cobalt respectively. Single-source vulnerability runs through the Shenzhen-Suzhou corridor where over seventy percent of controller capacity sits within two hundred kilometers. Distribution runs through regional distributors for fleet procurement and direct manufacturer contracts for enterprise subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as UL 2272 certification timeline compression and battery passport compliance investments force sub-scale modular assemblers toward exit or acquisition.
For Market Incumbents: Deploy captive battery assembly capacity as the primary defensive lever. Accelerate solid-state chemistry roadmaps to outpace performance-tier specialists in range-sensitive security patrol segments. Consolidate distributor relationships in permit-liberalizing European municipal markets before emerging entrants establish service networks. For New Entrants and Emerging Players: AI-based predictive maintenance algorithms offer a technology-first wedge into the equipment-as-a-service subscription layer where incumbent hardware margins are unbundling. White-space concentrates in Indian station-based rental hubs around metro rail expansion in Bengaluru, Delhi, and Mumbai. Target government agency procurement frameworks accessing EU Green Deal incentives through direct sales channels with compliance-frontloaded proposals. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated manufacturers seeking controller board and motor assembly capacity. Long-term viability favors entities with backward integration into battery cell production or exclusive solid-state chemistry partnerships. The signal to watch is municipal permit liberalization velocity in historic European city centers as an inflection indicator for tour operator fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Frontloading Investment | UL 2272 pre-certification compresses procurement qualification timelines for municipal fleet contracts. |
| Solid-State Battery Partnership | Exclusive cell supply agreements differentiate premium fleet specifications in 24-hour utilization models. |
| Equipment-as-a-Service Launch | Subscription bundling of hardware, maintenance, and insurance displaces capital expenditure treatment in North American campuses. |
| Permit-Driven Geographic Expansion | Municipal pedestrian-zone access liberalization in Lisbon, Prague, and Vienna unlocks supervised tourism circuit deployment. |
| Blockchain Supply Chain Traceability | EU battery passport compliance under CSRD mandates full lithium, cobalt, and nickel chain-of-custody documentation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet procurement managers, UL certification engineers, shared mobility operators, and battery supply chain directors. Secondary sources included MIIT GB standard documentation, NHTSA classification rulings, EU CSRD battery passport drafts, and lithium carbonate import records. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, and application dimensions.
Segment-level modeling tracked electric scooters, personal transporters, and mini Segways across tour operator, enterprise, consumer, and government agency channels. Urban mobility, security services, tourism, and parks applications were modeled separately with distinct regulatory access assumptions. CAGRs derived from logistic curve penetration rates applied to metro rail expansion timelines and municipal zero-emission zone enforcement schedules. Solid-state chemistry adoption curves and subscription model displacement rates served as industry-specific forecast inputs over the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt lithium price spikes or sudden municipal access restriction reversals. Forecasts reflect documented assumptions regarding certification timeline stability and permit liberalization continuity. A model refresh is warranted upon material change in EU battery passport implementation schedules or NHTSA classification precedent shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Electric Baby Car Market