
 US Low Speed Vehicle Market | 2026-2036
US Low Speed Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
US Low Speed Vehicle Market Analytics
Dealer networks for low speed vehicles is narrowing as manufacturers consolidate aftermarket support and direct fleet contracting. Polaris Industries controls a substantial portion of utility task vehicle distribution through its in-house dealer footprint. Club Car leverages its golf cart heritage to sustain brand recognition across resort and residential segments. Kubota Corporation anchors its position in agricultural-adjacent utility applications with diesel-electric hybrid offerings.
Low speed vehicles are motor vehicles designed for operation at speeds typically below 25 miles per hour, incorporating reinforced passenger compartments, seat belts, and lighting systems compliant with federal neighborhood electric vehicle standards. These vehicles serve closed-campus transportation, property maintenance, and short-distance mobility where full-speed automobile operation remains impractical or prohibited. Golf carts retain the largest installed base though battery electric neighborhood electric vehicles capture the fastest expansion as lithium-ion pack costs decline and range anxiety diminishes. Utility task vehicles command premium pricing due to payload ratings and all-terrain capability, while personal transporters remain a niche with concentrated demand at resorts and planned communities.
NHTSA FMVSS 500, EPA emissions thresholds for non-road engines, and state-level DMV classifications collectively determine where low speed vehicles may operate legally and what equipment manufacturers must install. California Air Resources Board zero-emission mandates and Texas DOT street-use permits illustrate how fragmented state rules create compliance complexity for national distributors. Stakeholders must monitor pending federal rulemakings on autonomous low speed vehicle operation and evolving state access to public roadways as these decisions will reshape addressable market boundaries and product development priorities.
Market Dynamics
Fleet electrification mandates across Sun Belt municipalities are compressing replacement cycles for legacy gasoline-powered utility vehicles, forcing manufacturers to reconfigure powertrain supply chains around lithium-ion pack sourcing.
Growth Catalysts
- Texas DOT Street-Use Permits:Expanded roadway access classifications for neighborhood electric vehicles in master-planned communities are accelerating residential fleet turnover.
- Campus Mobility Consolidation:University facilities departments are standardizing on single-vendor electric platforms to reduce maintenance training overhead and parts inventory complexity.
- Lithium-Ion Cost Curves:Battery pack economics have reached parity with lead-acid for 50-mile range configurations, erasing the historical price penalty for electric propulsion.
Market Restraints
- Charging Infrastructure Gaps:Rural retirement communities lack Level 2 installation density, constraining electric vehicle penetration outside urban corridors.
- NHTSA FMVSS 500 Speed Limitations:The 25 mph federal cap restricts addressable trip distances, excluding applications requiring arterial road access.
- Steel and Aluminum Input Volatility:Chassis material costs fluctuate with construction sector demand, compressing assembler margins on fixed-price municipal contracts.
Strategic Opportunities
- Autonomous Low Speed Vehicle Rulemaking:Pending NHTSA frameworks for driverless campus shuttles would open closed-loop transportation contracts to technology-enabled fleet operators.
- Florida Retirement Community Density:The Villages and comparable developments represent concentrated demand for medical transport and grocery shuttle services.
- Solar-Canopy Integration:Photovoltaic roof structures are extending effective range for property maintenance vehicles operating in Arizona and Nevada desert environments.
Industry Challenges
- High-Voltage Technician Certification:Dealer networks face 18-month training pipelines for EV-specific service credentials, delaying aftermarket support expansion.
- State-by-State Equipment Variance:California Air Resources Board zero-emission mandates conflict with Texas windshield and mirror specifications, forcing platform fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Low Speed Vehicle Market |
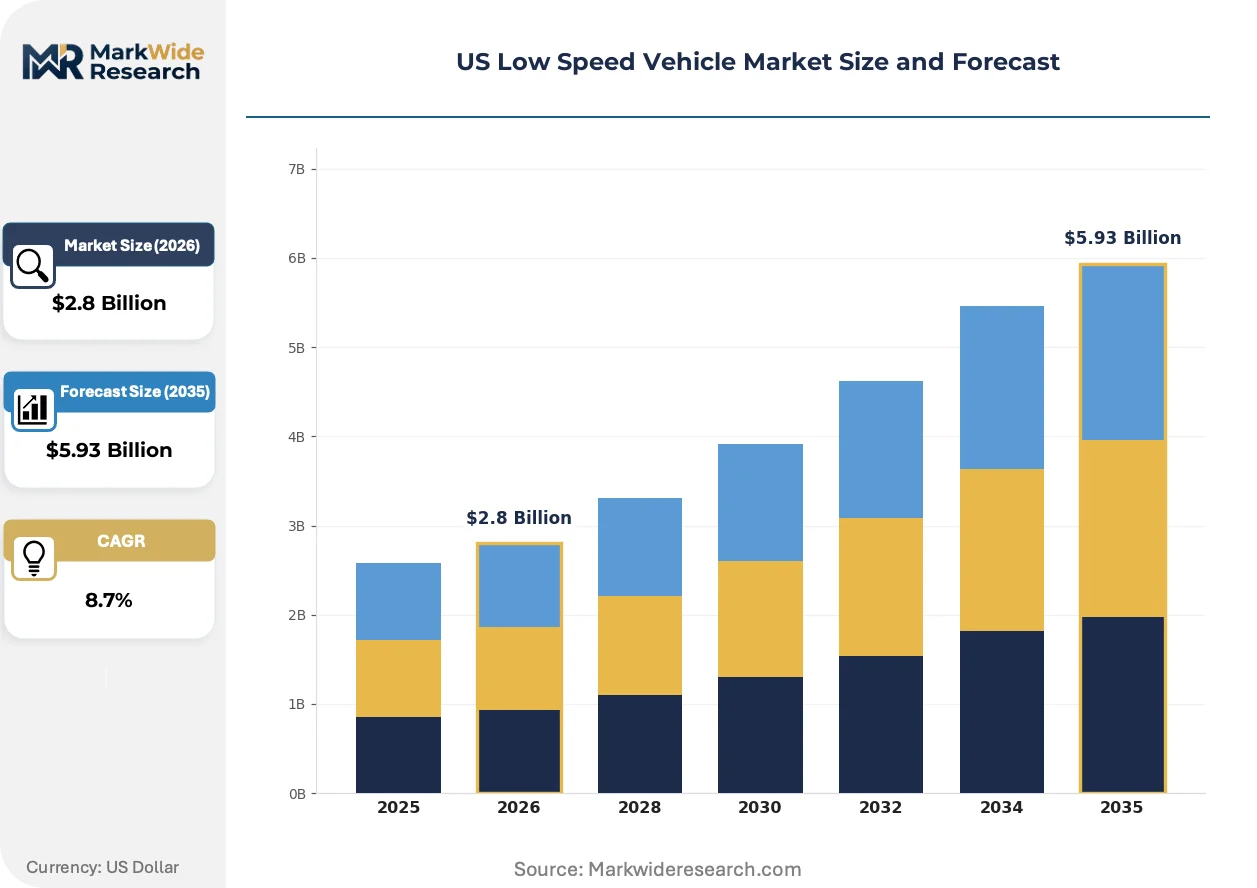
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neighborhood Electric Vehicles, Golf Carts, Utility Task Vehicles, Personal Transporters End User: University Campuses, Resorts, Airports, Residential Communities Technology: Battery Electric, Solar-Powered, Hybrid Power, Fuel Cell Distribution Channel: Direct Sales, Online Retail, Dealerships, Rental Services |
| Companies Covered | Textron Inc., Deere & Company, Club Car, Kubota Corporation, The Toro Company, Yamaha Motor Co., Ltd, Polaris Industries Inc., Columbia Vehicle Group Inc., Evolution Electric Vehicles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Low Speed Vehicle Market Evolving Landscape
Powertrain architecture decisions are bifurcating the installed base into sealed lithium-ion platforms and serviceable lead-acid legacy fleets, with implications for residual value forecasting and remarketing channels.
Lithium iron phosphate cell chemistry is migrating from premium neighborhood electric vehicles into mid-range utility task vehicles as pack integrators achieve module standardization. Agricultural cooperatives in California's Central Valley are adopting these configurations for irrigation inspection routes. The technology is compressing maintenance intervals and reshaping dealer revenue models away from battery replacement toward software diagnostics.
California Air Resources Board fleet electrification mandates are prohibiting new gasoline-powered utility vehicle registrations in state-controlled properties beginning with 2027 model years. Municipal procurement departments are front-loading orders to secure grandfathered internal combustion units. School districts and park systems face the steepest compliance timelines and are accelerating pilot programs with electric alternatives.
Facilities managers are consolidating vendor relationships around full-service fleet management contracts that bundle vehicles, charging infrastructure, and predictive maintenance software. Golf course operators and resort properties are displacing traditional equipment leasing arrangements with per-mile operational expense models. This restructuring is most pronounced in Arizona and Florida where seasonal demand fluctuations favor variable cost structures over capital deployment.
US Low Speed Vehicle Market Segmentation
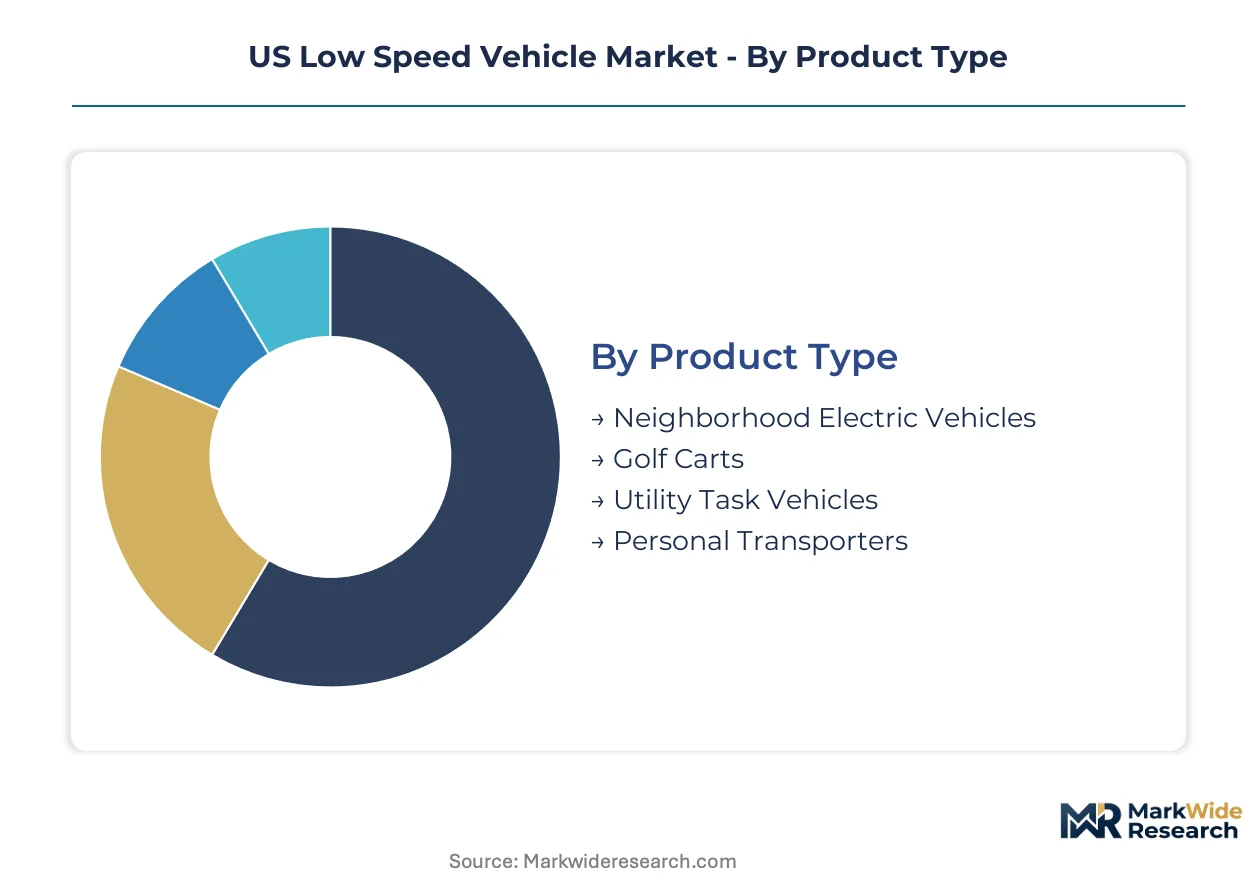
Segmentation in the US Low Speed Vehicle Market reveals divergent replacement dynamics across product categories and customer bases. Fleet operators prioritize total cost of ownership metrics while residential buyers respond to charging accessibility and local street-use regulations. Understanding these segment-specific purchase cycles enables manufacturers to align production capacity with demand timing.
Product Type:
Golf carts turn over every 7-10 years in residential settings, while utility task vehicles compress replacement to 4-6 years under commercial duty cycles. Neighborhood electric vehicles occupy a middle position with 6-8 year fleet depreciation schedules.
- Neighborhood Electric Vehicles:Battery-electric platforms with reinforced passenger compartments, seat belts, and lighting systems meeting NHTSA FMVSS 500 requirements. Demand concentrates in Texas master-planned communities and Florida retirement developments where expanded street-use permits enable grocery and medical shuttle services. Lithium-ion pack cost parity with lead-acid has erased the historical price penalty for electric propulsion in this segment.
- Golf Carts:Open-air or enclosed designs optimized for 18-hole course coverage and short-distance residential transport. The installed base remains largest across Arizona and Florida resort properties, though fleet electrification mandates are compressing replacement cycles for legacy gasoline-powered units. Golf course operators are shifting from equipment leasing to per-mile operational expense models.
- Utility Task Vehicles:Payload-rated platforms with all-terrain capability for property maintenance and agricultural inspection. Diesel-electric hybrid configurations serve California Central Valley irrigation routes where range requirements exceed pure-electric feasibility.
- Personal Transporters:Compact single- or dual-rider designs for resort and planned community mobility. Demand concentrates at The Villages and comparable Florida developments with dedicated path networks.
Golf carts dominate installed base. Neighborhood electric vehicles are where expansion concentrates.
End User:
Cost tier stratification separates capital-rich institutional buyers from price-sensitive residential associations. University procurement departments command volume discounts while homeowner associations negotiate through group purchasing organizations.
- University Campuses:Facilities departments standardize on single-vendor electric platforms to reduce maintenance training overhead and parts inventory complexity. Texas and Florida public university systems are expanding fleet procurement of battery electric models for student transport and facilities maintenance.
- Residential Communities:Master-planned developments in Sun Belt states generate concentrated demand for medical transport and grocery shuttle services. Charging infrastructure gaps in rural retirement communities constrain electric vehicle penetration outside urban corridors.
- Resorts:Seasonal demand fluctuations favor variable cost structures over capital deployment. Arizona and Florida properties are displacing traditional equipment leasing with full-service fleet management contracts bundling vehicles, charging infrastructure, and predictive maintenance software.
- Airports:Ground support and terminal shuttle applications require compliance with FAA operational safety protocols alongside NHTSA street-legal standards. Procurement cycles align with federal aviation facility upgrade timelines.
University campuses anchor premium pricing through consolidated vendor relationships. Residential communities represent the steepest volume expansion trajectory.
Technology:
Application requirements determine powertrain selection more than upfront cost differentials. Continuous-duty commercial operations favor battery electric while intermittent-use rural deployments retain hybrid flexibility.
- Battery Electric:Sealed lithium-ion platforms with lithium iron phosphate cell chemistry migrating into mid-range utility configurations. Pack integrators achieve module standardization that compresses maintenance intervals and shifts dealer revenue toward software diagnostics.
- Solar-Powered:Photovoltaic roof structures extending effective range for property maintenance vehicles operating in Arizona and Nevada desert environments. Solar-canopy integration addresses charging infrastructure gaps without grid dependency.
- Hybrid Power:Diesel-electric architectures serving agricultural-adjacent utility applications where payload ratings and all-terrain capability command premium pricing. California Air Resources Board zero-emission mandates are forcing transition planning despite residual demand.
- Fuel Cell:Hydrogen fuel cell configurations remain experimental for low-speed applications, with pilot programs constrained by refueling infrastructure availability and high-voltage technician certification requirements.
Battery electric dominates new procurement. Solar-powered configurations are gaining share fastest in desert Southwest deployments.
Distribution Channel:
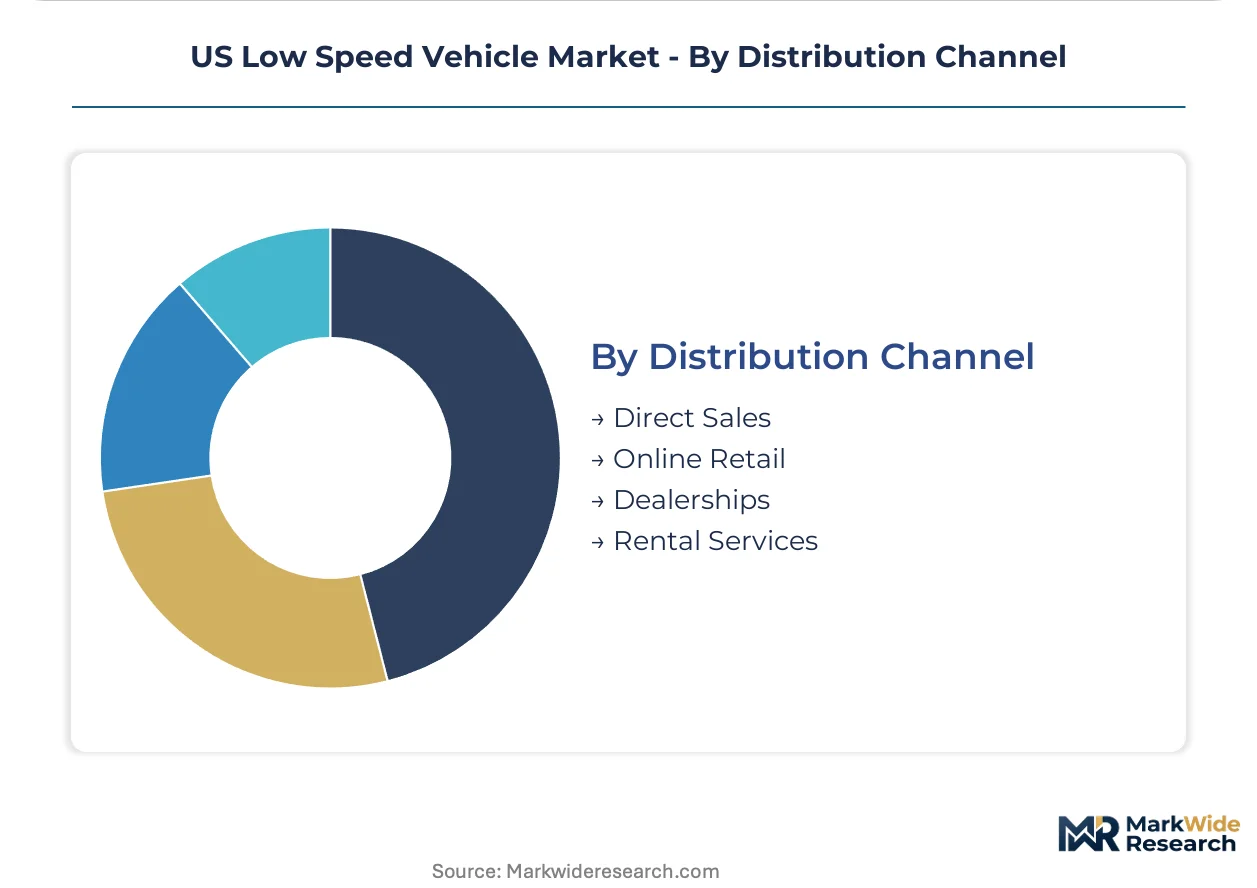
Customer type dictates channel preference with institutional buyers favoring direct contracting while residential purchasers rely on local dealership relationships for service accessibility.
- Direct Sales:Fleet contracting to municipalities, universities, and corporate campuses bypassing dealer markups. Manufacturers consolidate aftermarket support through in-house service networks to capture recurring revenue.
- Dealerships:Local service infrastructure remains critical for residential buyers prioritizing maintenance accessibility over purchase price. Dealer networks face 18-month training pipelines for EV-specific service credentials.
- Rental Services:Seasonal demand in resort markets favors operational expense models over capital deployment. Golf course operators and Arizona properties structure per-mile agreements aligned with utilization patterns.
- Online Retail:Configurator-based purchasing with remote delivery to dealer partners for final assembly and inspection. Channel growth constrained by high-voltage system transport regulations and state-level registration requirements.
Direct sales capture institutional volume. Dealerships retain residential loyalty through service proximity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA FMVSS 500 provides the federal framework governing street-legal low speed vehicle operation across the United States, while state-level DOT classifications and municipal fleet mandates create substantial variation in adoption patterns. Regional demand concentrates in Sun Belt states with favorable climate conditions and expanding master-planned communities.
Texas
Texas DOT street-use permits for neighborhood electric vehicles in master-planned communities accelerate residential fleet turnover. University facilities departments across the Texas public university system standardize procurement of battery electric platforms. The Austin-San Antonio corridor anchors concentrated demand for campus mobility consolidation.
Florida
The Villages and comparable retirement developments generate concentrated demand for medical transport and grocery shuttle services. Seasonal resort properties favor variable cost fleet management structures over capital deployment. Miami-Dade and Orange County municipalities compress replacement cycles through electrification mandates.
California
California Air Resources Board zero-emission mandates prohibit new gasoline-powered utility vehicle registrations on state-controlled properties beginning with 2027 model years. Agricultural cooperatives in the Central Valley adopt lithium iron phosphate configurations for irrigation inspection routes. Municipal procurement departments front-load orders to secure grandfathered internal combustion units.
Arizona
Solar-canopy integration extends effective range for property maintenance vehicles operating in desert environments. Golf course operators shift from equipment leasing to per-mile operational expense models. The Phoenix-Tucson corridor leads residential community adoption of photovoltaic roof structures.
Nevada
Charging infrastructure gaps in rural retirement communities constrain electric vehicle penetration outside Las Vegas and Reno urban corridors. Resort properties bundle vehicles, charging infrastructure, and predictive maintenance software through full-service fleet management contracts. Clark County facilities managers consolidate vendor relationships around single-source electric platforms.
US Low Speed Vehicle Market Competitive Landscape
Diversified industrial conglomerates and specialized mobility manufacturers split the market between utility-focused and recreational applications. The vendor base organizes around three strategic archetypes: agricultural-equipment diversifiers, powersports specialists, and dedicated low-speed vehicle pure-plays. Capacity expansion in lithium-ion pack integration and direct fleet contracting to institutional buyers represent the dominant competitive moves reshaping channel economics.
Among diversified industrial players, Deere & Company and Kubota Corporation exemplify the agricultural-equipment archetype with positions in utility-adjacent applications. Polaris Industries Inc. anchors the powersports specialist tier, leveraging distribution infrastructure across recreational and commercial segments. These three companies occupy positions that reflect distinct strategic origins while converging on electrification platforms for institutional fleet procurement.
| Leading Market Players |
|---|
| Textron Inc. |
| Deere & Company |
| Club Car |
| Kubota Corporation |
| The Toro Company |
| Yamaha Motor Co., Ltd |
| Polaris Industries Inc. |
| Columbia Vehicle Group Inc. |
| Evolution Electric Vehicles |
| Others |
Value Network & Pricing Analysis
The I-10 corridor freight dynamics connecting Texas manufacturing clusters to Arizona and Nevada distribution hubs compress logistics cost differentials between coastal and inland suppliers, concentrating bargaining power among lithium-ion pack integrators and forcing assemblers into configured-to-order pricing models that widen spreads between standard fleet contracts and customized municipal specifications.
Pricing Analysis
The customization-premium spread separates standard neighborhood electric vehicle fleet contracts from configured municipal specifications by 15-25 percent, with lithium iron phosphate battery configurations commanding additional premiums over lead-acid baselines. Pricing stratifies across premium lithium-ion platforms, standard lead-acid replacements, and economy-grade refurbished units, with Texas DOT permit-compliant street-legal packages adding certification-driven uplifts. Cost compression in the standard tier is intensifying because steel and aluminum input volatility erodes fixed-price contract margins. University procurement departments exhibit lowest price sensitivity due to consolidated vendor relationships, while rural retirement associations face acute budget constraints that favor economy-tier acquisitions.
Supply Chain Analysis
Upstream feedstock for lithium-ion cells draws from Chilean lithium brine operations, Australian spodumene concentrate, and Indonesian nickel processing, creating geographic concentration risk across three continents. Chassis fabrication rests on Mexican steel stamping, Chinese aluminum extrusion, and domestic welding assembly. Single-source vulnerability in lithium hydroxide refining exposes pack integrators to export restriction shocks. Distribution runs through manufacturer-direct fleet contracting for institutional buyers and regional dealership networks for residential purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Low Speed Vehicle Market sits in early-cycle expansion as NHTSA autonomous rulemaking and CARB electrification mandates compress replacement timelines and expand addressable use cases beyond traditional golf and utility applications.
For Market Incumbents: Pre-empt emerging pure-play electric specialists by consolidating charging infrastructure bundling capabilities and locking multi-year fleet management contracts with Texas and Florida university systems. Backward integration into lithium iron phosphate cell sourcing defends margin position against commodity volatility. Secure CARB certification pathways ahead of 2027 gasoline prohibition deadlines to grandfather service revenue streams. For New Entrants and Emerging Players: Mid-market Arizona property maintenance fleets represent the most penetrable entry point, with solar-canopy configurations addressing charging infrastructure gaps without grid dependency. Nevada resort properties seeking operational expense models over capital deployment offer second-mover advantages through per-mile service structures. Target facilities managers consolidating vendor relationships around predictive maintenance software bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural-equipment parents seeking to divest non-core utility vehicle divisions amid electrification capital intensity. Long-term viability hinges on lithium-ion platform transition completion and autonomous shuttle regulatory clarity. Watch NHTSA autonomous low speed vehicle rulemaking publication as inflection indicator for technology-enabled fleet operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Fleet Contracting Consolidation | Manufacturer bypass of dealer markups captures recurring service revenue from Texas university systems. |
| Lithium Iron Phosphate Platform Migration | Cell chemistry standardization compresses maintenance intervals and shifts dealer revenue toward software diagnostics. |
| Solar-Canopy Integration | Photovoltaic roof structures extend range for Arizona property maintenance without grid dependency. |
| Autonomous Shuttle Pilot Programs | Technology-enabled fleet operators position for NHTSA rulemaking expansion of closed-loop transportation contracts. |
| CARB Compliance Pathway Investment | Zero-emission certification secures California municipal procurement access ahead of 2027 gasoline prohibition. |
Research Methodology
Operator-level perspectives from university facilities directors, municipal fleet managers, golf course superintendents, and lithium-ion pack integrators anchored the qualitative base. Primary interviews combined with secondary validation from NHTSA FMVSS 500 regulatory filings, EPA non-road engine certification databases, Texas DOT permit records, and California Air Resources Board fleet registration data. Bottom-up unit shipment modeling and top-down value chain triangulation cross-checked segment-level estimates.
Scenario-bracketing framed low, base, and high penetration assumptions across the projection horizon, with segmentation modeling across product type, end user, technology, and distribution channel dimensions. CAGRs derived from replacement cycle compression analysis and fleet electrification mandate timelines. Forecast inputs incorporated lithium-ion cost curve trajectories and state-level street-use permit expansion schedules.
Stress conditions across steel input volatility, lithium supply disruption, and NHTSA autonomous rulemaking delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding electrification compliance timelines and fleet turnover acceleration. Cross-checking against state DMV registration databases and university procurement disclosure records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
US Recreational Boating Market