
 Automotive Airbag Gas Generators Market | 2026-2036
Automotive Airbag Gas Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag Gas Generators Market Insights
Modular inflator packaging is consolidating buyer choice around integrated gas-generator-and-diffuser assemblies that reduce assembly-line complexity for vehicle manufacturers. Autoliv Inc. leverages its vertically controlled propellant chemistry and global foundry network to anchor supply contracts with premium OEM platforms. ZF Friedrichshafen AG competes through dual-source architectures that sustain procurement flexibility for multinational assemblers.
Automotive airbag gas generators are sealed pyrotechnic or hybrid devices that produce controlled volumes of inert gas—typically nitrogen or argon blends—within milliseconds to inflate protective cushions, with operating pressures calibrated to 150-300 kPa depending on installation position and occupant classification. Solid propellant formulations dominate current production volumes due to decades of ballistic stability and compact form factors, though hybrid propellant systems are capturing structural attention as OEMs seek to reduce particulate emissions during deployment. Pyrotechnic ignition technology leads the technology dimension with mature supply chains, while compressed gas architectures represent the fastest-growing segment as cold-gas designs address thermal degradation concerns in electric vehicle battery-adjacent mounting locations.
NHTSA Federal Motor Vehicle Safety Standard 208 and the EU's General Safety Regulation mandate multi-stage inflation and out-of-position occupant detection, forcing continuous redesign cycles across supplier engineering teams. China's GB/T standards and MIIT certification protocols impose additional propellant composition disclosure requirements that shape market access for non-domestic manufacturers. Stakeholders must monitor the divergence between regional chemical disclosure regimes and the accelerating shift toward electric-vehicle-specific thermal management in inflator housing design.
Market Dynamics
Multi-point airbag mandates from NHTSA and Euro NCAP are compressing inflator refresh cycles, forcing suppliers to redesign venting architectures and propellant chemistry simultaneously across multiple vehicle platforms.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 208:Mandates for multi-stage inflation and out-of-position occupant detection compel continuous engineering investment across supplier portfolios.
- Hybrid propellant systems:OEM demand for reduced particulate emissions during deployment accelerates substitution of conventional solid propellants in battery-adjacent mounting locations.
- China's MIIT certification protocols:Accelerated enforcement of GB/T standards propels domestic vehicle production toward localized gas generator sourcing faster than Western replacement cycles.
Market Restraints
- Strontium nitrate price volatility:Primary oxidizer in azide-free propellants faces supply concentration from Chinese chemical processors, compressing margin buffers for Western inflator manufacturers.
- Dual-source procurement mandates:Multinational assemblers fragment contract volumes across competing suppliers, preventing scale economies in specialized housing foundries.
- Thermal runaway containment:Electric vehicle battery proximity imposes hard temperature ceilings on inflator housing materials that pyrotechnic designs struggle to satisfy without hybrid architecture adoption.
Strategic Opportunities
- India's PLI scheme for automotive components:Localization incentives attract inflator assembly investments to serve Maruti Suzuki and Tata Motors expansion in domestic airbag fitment.
- Cold-gas compressed nitrogen architectures:Convergence with thermal management systems for EV battery packs creates cross-selling pathways into adjacent vehicle safety electronics.
- Integrated gas-generator-and-diffuser assemblies:Modular packaging reduces OEM assembly-line complexity, opening direct-tier contracting opportunities previously held by seat and steering column integrators.
Industry Challenges
- Ballistics simulation expertise:Shortage of engineers combining pyrotechnic chemistry with finite element analysis for rapid-deployment modeling extends product validation timelines.
- Propellant composition disclosure:China's GB/T standards demand formula transparency that conflicts with Western suppliers' IP protection protocols, complicating market entry documentation.
- Legacy inflator recall liability:Takata-era replacement programs consume technical resources and capital that could otherwise deploy toward next-generation hybrid system development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag Gas Generators Market |
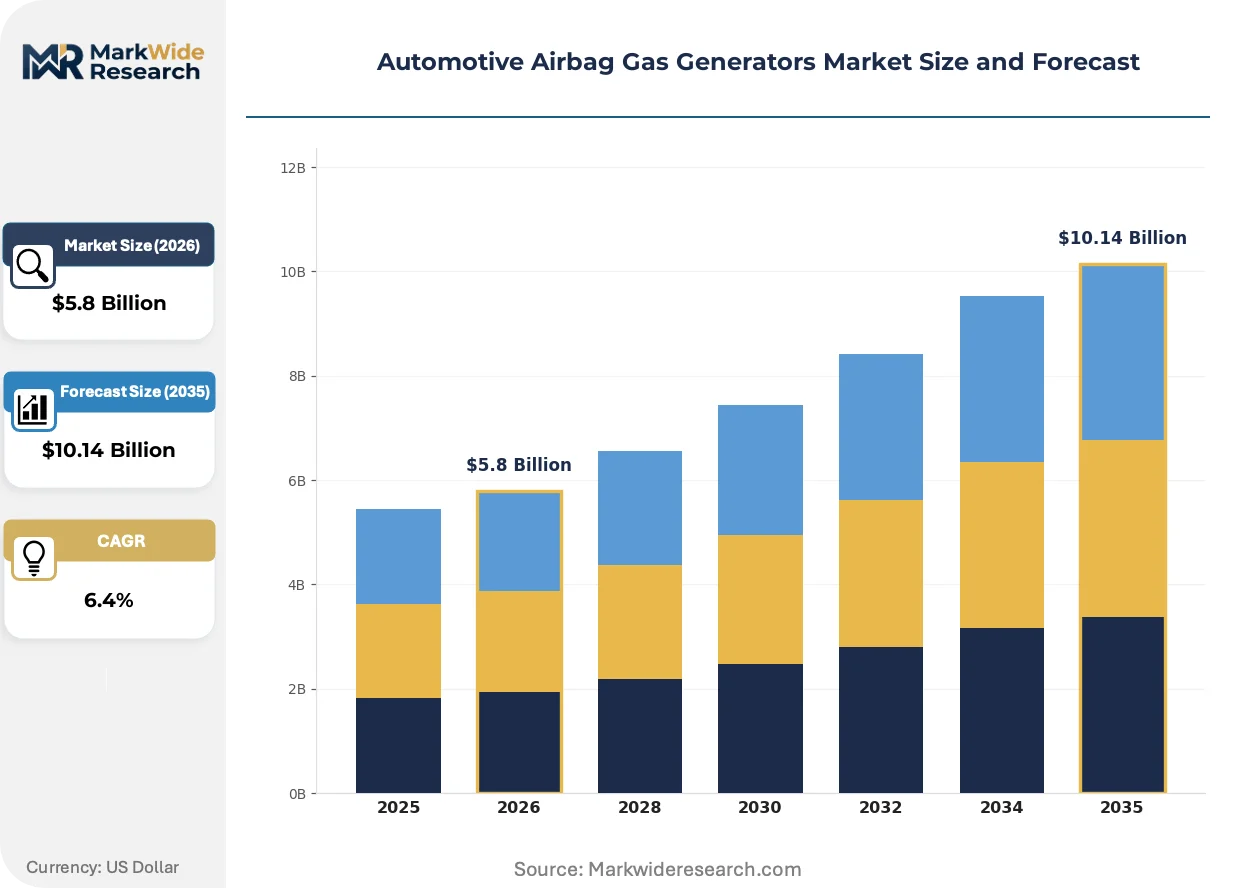
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Propellant, Hybrid Propellant, Gas Generators, Inflators Technology: Pyrotechnic, Chemical Reaction, Electric, Compressed Gas End User: OEMs, Aftermarket, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Front Airbags, Side Airbags, Curtain Airbags, Knee Airbags |
| Companies Covered | Autoliv Inc., ZF Friedrichshafen AG, Joyson Safety Systems, Daicel Corporation, Toyoda Gosei Co., Ltd., Hyundai Mobis Co., Ltd., Robert Bosch GmbH, Continental Aktiengesellschaft, ARC Automotive Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag Gas Generators Market Trends and Innovations
Gas generator architecture is bifurcating between refined pyrotechnic efficiency and emergent cold-gas thermal compatibility, with regulatory disclosure requirements and electric vehicle packaging constraints driving divergent R&D investment priorities.
Smart venting systems with real-time pressure modulation are automating occupant-classification-responsive deployment curves. Premium OEM platforms in Germany and Japan adopt these for front passenger and rear seat applications. The technology is automating the trade-off between cushioning effectiveness and injury risk that previously required fixed-orifice mechanical design compromises.
Euro NCAP's 2026 roadmap for far-side impact protection mandates side-curtain inflation sequences that synchronize with seat-mounted thorax bags. European assemblers accelerate pre-development programs with inflator suppliers to secure five-star ratings ahead of protocol enforcement. Component suppliers face compressed validation windows as vehicle programs lock architectures eighteen months before assessment deadlines.
Fleet procurement of aftermarket replacement inflators is consolidating around certified remanufacturing programs that displace independent distributor channels. North American collision repair networks and European insurance-approved body shops now source exclusively through OEM-authorized rebuilders. The shift is most pronounced in Germany and the United States, where liability exposure from non-certified deployments has driven insurer-mandated sourcing protocols.
Automotive Airbag Gas Generators Market Segmentation
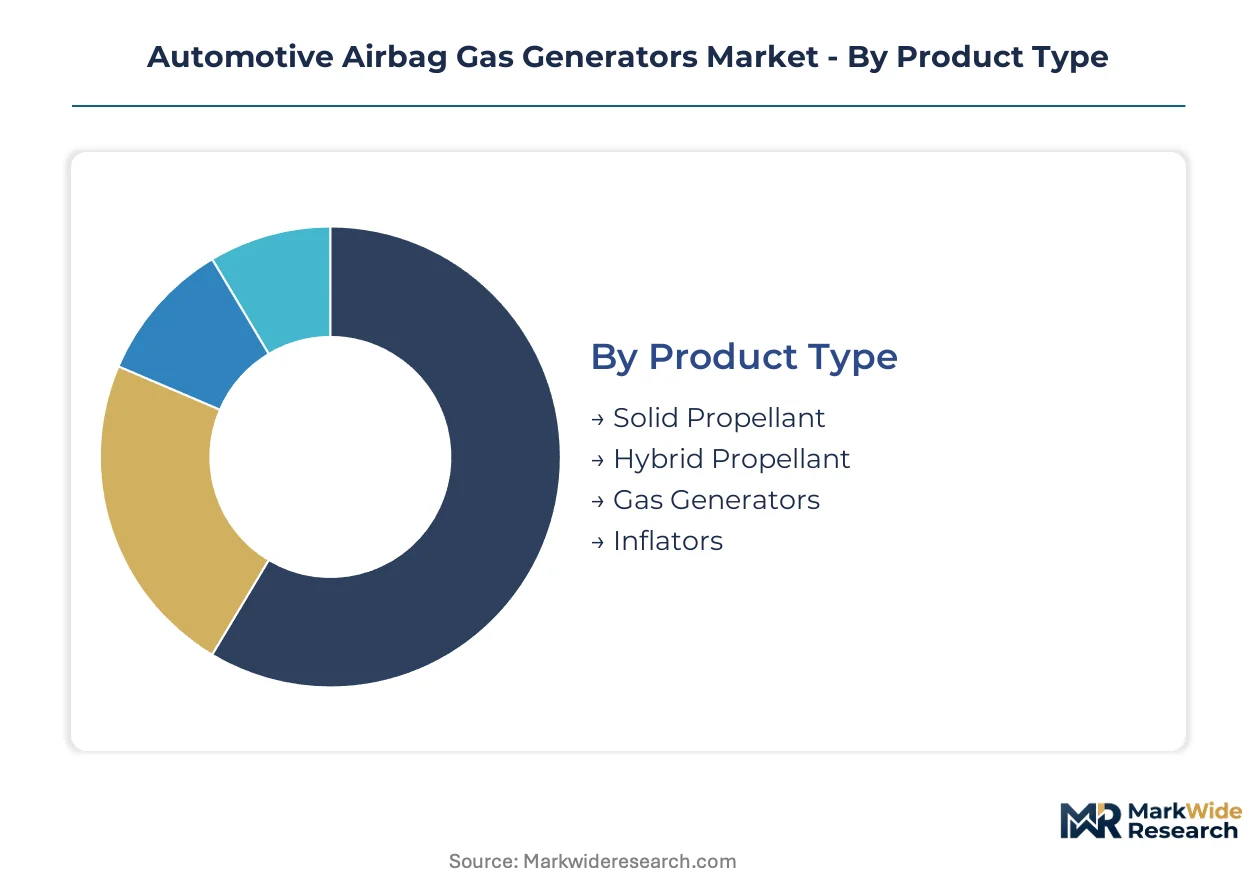
Gas generator procurement patterns diverge sharply between legacy vehicle platforms and next-generation electric architectures, with chemistry selection and packaging density driving supplier contract allocation. Component sourcing for multi-point airbag systems now requires simultaneous qualification across four to six installation positions per vehicle program.
Product Type:
Upgrade cycles for inflator chemistry are compressing as NHTSA and Euro NCAP mandates force simultaneous refresh of propellant formulations and housing geometries across multiple model years.
- Solid Propellant:Azide-free sodium azide replacements dominate current production with compact cylindrical geometries optimized for steering wheel and dashboard integration. Demand concentrates in North American and European passenger vehicle OEMs facing Takata-era recall replacement schedules that prioritize proven ballistic stability over chemistry transitions.
- Hybrid Propellant:Dual-chamber designs combining stored gas reservoirs with reduced pyrotechnic charges address thermal degradation constraints in battery-adjacent mounting locations. Chinese EV manufacturers and German premium platforms are the primary volume destinations as these architectures satisfy MIIT certification protocols while reducing particulate emissions during deployment.
- Gas Generators:Standalone pressurized vessels with rupture-disc ignition serve specialized commercial vehicle and heavy-duty applications requiring extended storage life.
- Inflators:Complete integrated assemblies with pre-attached diffusers capture direct-tier contracts from OEMs seeking assembly-line simplification.
Volume placements concentrate in Solid Propellant; the faster expansion belongs to Hybrid Propellant.
Technology:
Cost tier differentiation separates mature pyrotechnic supply chains from emerging compressed gas architectures requiring capital-intensive pressure vessel manufacturing.
- Pyrotechnic:Combustion-based ignition using sodium azide or nitroguanidine propellants delivers millisecond response times through established foundry networks. North American and Japanese OEMs maintain procurement concentration here due to validated supply continuity and lower unit costs at scale.
- Chemical Reaction:Hypergolic or catalytic decomposition systems generate gas through controlled exothermic reactions without flame propagation. European suppliers are advancing this architecture for side-curtain applications where reduced thermal signature matters.
- Electric:Resistive heating elements initiate propellant combustion with precise temporal control for multi-stage inflation sequences. German and Japanese premium platforms specify this technology for occupant-classification-responsive deployment curves.
- Compressed Gas:Cold-gas nitrogen or argon systems eliminate combustion residues entirely, satisfying emerging thermal management requirements for EV battery pack proximity. South Korean and Chinese manufacturers are expanding capacity fastest.
Procurement weight rests with Pyrotechnic; Compressed Gas is climbing the fastest as EV architectures proliferate.
End User:
Customer type determines contract structure complexity, with direct OEM relationships demanding full engineering collaboration versus aftermarket channels prioritizing inventory velocity.
- OEMs:Original equipment manufacturers specify complete inflator systems with platform-integrated venting and sensor communication protocols. German, Japanese, and US-based vehicle assemblers drive specification authority through multi-year supply agreements.
- Aftermarket:Certified remanufacturing programs now dominate collision repair procurement in Germany and the United States, displacing independent distributor channels through insurer-mandated sourcing protocols.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source pre-configured modules from Tier-1 integrators rather than direct inflator suppliers.
- Tier-1 Suppliers:Seat, steering column, and interior module integrators purchase gas generators as subcomponents for assembly into larger safety systems.
Contract value pools deepest with OEMs; Aftermarket channels are gaining share fastest through certified rebuild programs.
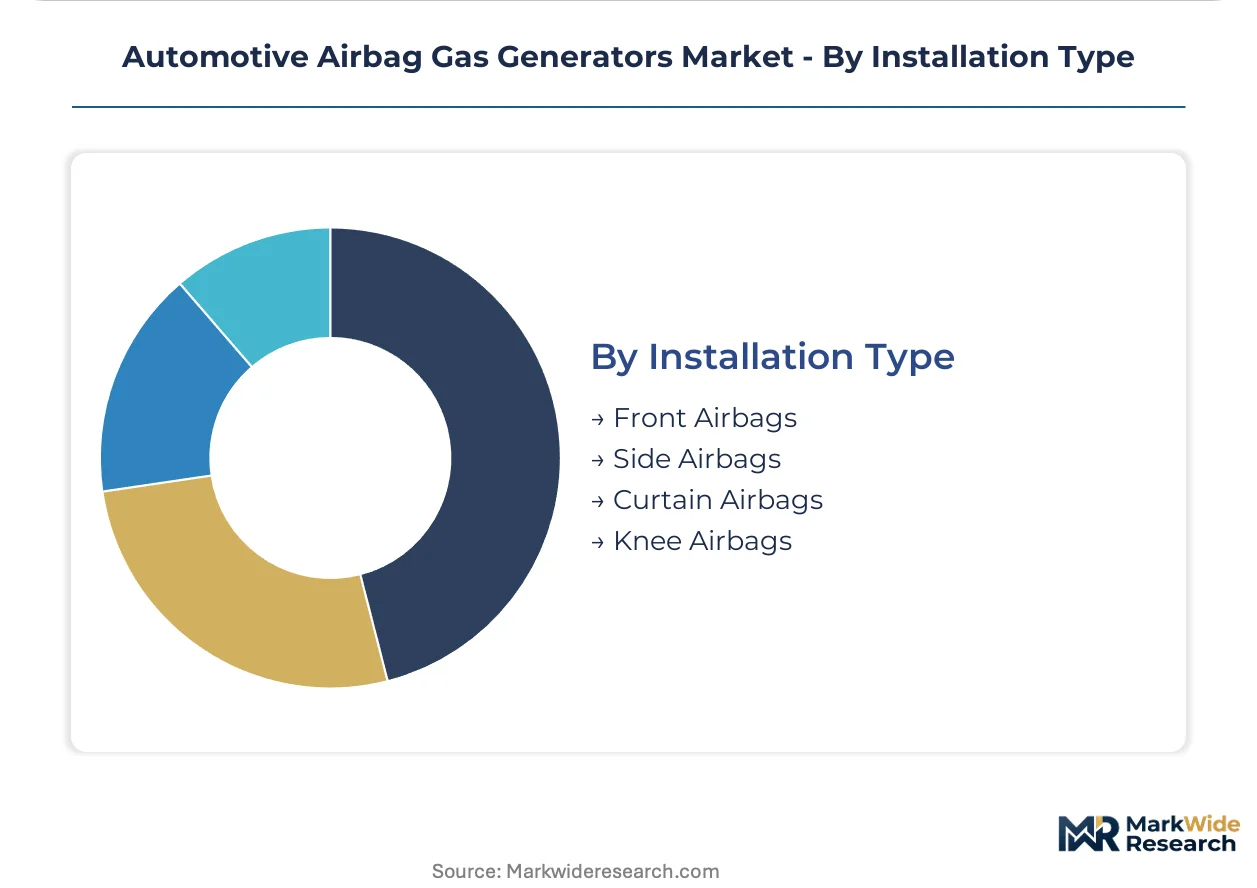
Installation Type:
Application-specific thermal and spatial constraints are fragmenting inflator design requirements across mounting positions within the same vehicle cabin.
- Front Airbags:Driver and passenger positions require compact cylindrical or toroidal geometries with rapid pressure rise rates for 30-50 millisecond cushion inflation. Global production volume concentrates here across all major vehicle markets.
- Side Airbags:Seat-mounted thorax protection systems demand elongated tubular inflators with directed venting to avoid occupant contact injuries. European assemblers lead specification complexity for Euro NCAP side-impact protocols.
- Curtain Airbags:Overhead-mounted systems spanning pillar-to-pillar require extended linear inflators with uniform gas distribution along the cushion length. Chinese and European OEMs are expanding fitment fastest.
- Knee Airbags:Lower dashboard mounting positions specify smaller-diameter units with reduced output pressure to mitigate lower extremity injury risk. Premium segment penetration exceeds mass-market adoption.
Deployment frequency peaks with Front Airbags; Curtain Airbags are expanding most quickly as far-side impact mandates approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-certified industrial parks and Germany's automotive manufacturing clusters concentrate gas generator assembly capacity near major OEM final assembly lines. NHTSA-mandated recall replacement programs sustain aftermarket demand across North American collision repair networks. Japanese Tier-1 suppliers anchor hybrid propellant development through keiretsu-linked chemical processors.
United States
NHTSA Federal Motor Vehicle Safety Standard 208 enforcement drives multi-stage inflator retrofits across domestic light-truck platforms. The Takata replacement program continues to channel certified remanufacturing volume through insurer-mandated collision repair networks. Detroit's supplier corridor hosts concentrated housing foundry and ballistic testing infrastructure for steering wheel and dashboard integration.
Germany
Euro NCAP's 2026 far-side impact roadmap accelerates side-curtain pre-development with Munich and Stuttgart-based premium OEMs. The EU's General Safety Regulation mandates out-of-position detection that compresses engineering validation windows. Baden-Württemberg's supplier belt anchors pyrotechnic ignition expertise alongside chemical reaction system development for reduced thermal signature applications.
China
MIIT certification protocols and GB/T standards enforce propellant composition disclosure that shapes market access documentation. Domestic EV manufacturers specify hybrid propellant architectures for battery-adjacent mounting locations. Shanghai and Guangzhou industrial zones concentrate localized gas generator sourcing faster than Western replacement cycles.
Japan
METI-coordinated safety technology roadmaps align keiretsu chemical processors with inflator housing foundries for occupant-classification-responsive deployment. Premium OEM platforms specify electric ignition technology for multi-stage inflation sequences. Nagoya and Osaka manufacturing clusters sustain pyrotechnic supply chain continuity through validated propellant chemistry networks.
India
The PLI scheme for automotive components attracts inflator assembly investments to serve Maruti Suzuki and Tata Motors expansion in domestic airbag fitment. BIS certification requirements shape import substitution strategies for non-domestic manufacturers. Haryana and Tamil Nadu automotive corridors concentrate Tier-1 module integration capacity for steering column and seat-mounted applications.
Automotive Airbag Gas Generators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, with procurement fragmentation preventing scale concentration in specialized housing foundries. The vendor base stratifies between vertically integrated chemistry-to-assembly operators and modular packaging integrators serving direct-tier OEM contracts. Three archetypes dominate: global safety system conglomerates with captive propellant production, regional foundry specialists with OEM-authorized remanufacturing licenses, and hybrid technology developers addressing EV thermal constraints. Competitive intensity centers on dual-source procurement mandates from multinational assemblers and MIIT certification compliance for Chinese market access.
Within the conglomerate tier, Autoliv Inc. and ZF Friedrichshafen AG occupy positions reflecting divergent strategic postures toward supply chain control. Autoliv exemplifies the chemistry-integrated archetype through vertically controlled propellant operations, while ZF represents procurement-flexibility positioning via dual-source architectures. Joyson Safety Systems sits within the Asia-Pacific expansion vector, reflecting Chinese domestic market prioritization through localized certification compliance. These three anchors illustrate how geographic regulatory alignment and supply chain configuration shape contract allocation across premium OEM platforms.
| Leading Market Players |
|---|
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| Daicel Corporation |
| Toyoda Gosei Co., Ltd. |
| Hyundai Mobis Co., Ltd. |
| Robert Bosch GmbH |
| Continental Aktiengesellschaft |
| ARC Automotive Inc. |
| Others |
Pricing and Supply Chain Analysis
Hybrid propellant adoption for electric vehicle battery-adjacent mounting simultaneously elevates housing material costs and concentrates qualified supplier pools around MIIT-certified Chinese foundries and German premium-tier specialists. NHTSA-mandated multi-stage inflation architectures compress procurement timelines, forcing OEMs to accept premium positioning for validated supply continuity or absorb qualification delays from unproven entrants.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with OEMs paying substantial markups for validated six-week delivery windows versus standard sixteen-week procurement cycles. Pricing stratifies across premium, standard, and economy tiers based on propellant chemistry disclosure depth and thermal management certification grade. Cost compression in solid propellant segments is intensifying because strontium nitrate supply concentration from Chinese chemical processors limits Western manufacturer margin buffers. Aftermarket certified remanufacturing programs exhibit highest price sensitivity due to insurer-mandated sourcing protocols, while premium OEM direct-tier contracts prioritize ballistic performance over unit cost.
Supply Chain Analysis
MIIT certification and NHTSA validation gates fragment supplier qualification, restricting approved manufacturing to German housing foundries, Chinese industrial zones, and Japanese keiretsu-linked chemical processors. Raw material dependencies center on strontium nitrate oxidizers, nitroguanidine propellants, and specialized aluminum housing alloys. Single-source vulnerability concentrates in Chinese strontium nitrate processing, where export licensing shifts create supply discontinuity risks. Distribution runs through OEM-authorized Tier-1 integrators for direct-tier contracts, with certified remanufacturing channels serving collision repair networks in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where NHTSA Federal Motor Vehicle Safety Standard 208 and China's GB/T propellant disclosure protocols erect regulatory moats that reward incumbent investment in multi-jurisdiction certification infrastructure.
For Market Incumbents: To counter dual-source procurement mandates fragmenting contract volumes, anchor supply relationships through captive strontium nitrate sourcing or long-term offtake agreements with Chinese chemical processors. Accelerate hybrid propellant foundry capacity in MIIT-certified industrial parks to preempt Chinese EV manufacturer sourcing decisions. For New Entrants and Emerging Players: Tier-1 seat and steering column integrators represent the most penetrable channel for modular gas-generator-and-diffuser assemblies, as these buyers seek assembly-line simplification without full propellant chemistry investment. Target India's PLI scheme localization incentives for inflator assembly partnerships with Maruti Suzuki and Tata Motors expansion programs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified automotive safety conglomerates seeking MIIT certification assets. Long-term viability hinges on hybrid propellant IP portfolios addressing EV thermal constraints. Monitor South Korean and Chinese cold-gas capacity buildout as inflection signal for pyrotechnic architecture displacement timeline.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | Unlocks Chinese EV manufacturer procurement channels ahead of GB/T enforcement acceleration. |
| Hybrid Propellant Foundry Expansion | Captures battery-adjacent mounting specifications from German premium and Chinese domestic OEMs. |
| Strontium Nitrate Backward Integration | Insulates margin buffers from Chinese chemical processor export licensing volatility. |
| Modular Assembly Direct-Tier Contracts | Displaces seat and steering column integrators through assembly-line complexity reduction. |
| Cold-Gas Capacity Buildout | Positions for EV thermal management convergence with adjacent battery pack safety systems. |
Research Methodology
Multi-period observation of inflator chemistry transition timelines, OEM platform airbag fitment rates, and regional certification protocol enforcement anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and MIIT certification consultants. Secondary validation drew from NHTSA recall databases, vehicle production registries, SEC supplier filings, and customs trade flow records. Bottom-up segment sizing triangulated against top-down OEM procurement budget allocations across the analysis window.
Input-output matrices mapped propellant chemistry adoption curves to vehicle platform electrification timelines, with segmentation across solid-hybrid-cold-gas technology tiers, front-side-curtain-knee installation positions, and OEM-direct versus aftermarket channel structures. CAGRs derived from regression against historical fitment penetration and regulatory mandate enforcement schedules. Industry-specific forecast inputs incorporated Euro NCAP roadmap pre-development commitments and Chinese EV battery pack thermal management specifications.
Caveats apply where NHTSA rulemaking acceleration or MIIT disclosure requirement tightening could materially shift the outlook for chemistry transition timelines and supplier qualification burdens. A model refresh is warranted upon material change in strontium nitrate export licensing protocols or Euro NCAP far-side impact mandate enforcement deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive Door Guards Market