
 Caravan and Motorhome Market | 2026-2036
Caravan and Motorhome Market Size, Share, and Industry Trends Forecast 2026-2036
Caravan and Motorhome Market Outlook
Thor Industries leverages its vertically integrated chassis and component manufacturing to sustain margin control across North American production. Winnebago Industries anchors its position through R&D intensity in off-grid power systems, while Bailey of Bristol competes on brand strength within the UK touring segment. Tiffin Motorhomes dominates the premium Class A niche with handcrafted interior configurations that differentiate it from mass-market rivals.
Caravans and motorhomes comprise self-propelled or towed recreational vehicles engineered on dedicated chassis with habitation modules built to gross vehicle weight ratings and thermal insulation standards. Aluminum and fiberglass panel construction dominates current output due to strength-to-weight ratios that preserve fuel efficiency across travel trailers and motorhome classes. Travel trailers occupy the largest volume tier, while solar power features represent the fastest-growing specification as buyers demand off-grid autonomy. Class C motorhomes concentrate margin pools through chassis-cab integration that limits third-party supplier dependence.
US NHTSA governs vehicle safety standards for motorhome chassis and tow ratings, while EPA tailpipe regulations shape powertrain choices for self-propelled units. EU F-Gas Regulation and REACH compliance constrain refrigerant and interior material selections for European-bound products. Stakeholders must monitor evolving battery-electric chassis availability from commercial vehicle suppliers, as electrification timelines in the base truck segment will determine motorhome product roadmaps.
Market Dynamics
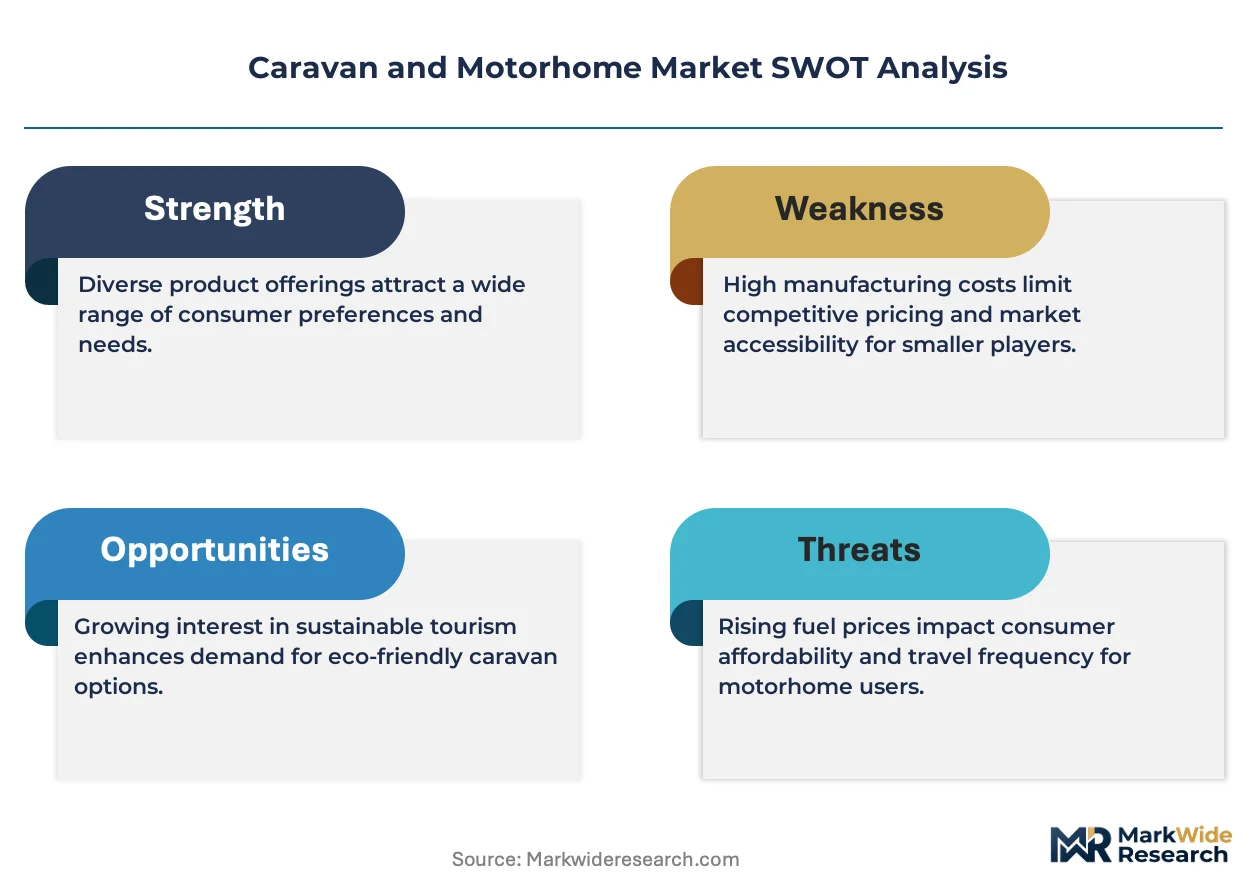
The EU F-Gas Regulation is forcing refrigerant transitions across climate-control supply chains, while chassis availability from commercial vehicle manufacturers dictates motorhome production scheduling and model-year planning.
Growth Catalysts
- Retiree demographic expansion:Aging populations in Germany, France, and the UK prioritize mobile leisure lifestyles, sustaining replacement cycles for touring vehicles and driving premium specification upgrades.
- EU Green Deal alignment:Low-GWP refrigerant mandates under F-Gas Regulation accelerate component innovation, creating competitive differentiation for early-adopting manufacturers.
- Solar integration:Photovoltaic roof systems are virtualizing power autonomy expectations, with off-grid capability becoming a standard specification rather than premium option.
Market Restraints
- Chassis supply concentration:Dependence on Fiat Ducato, Mercedes Sprinter, and Ford Transit platforms from limited commercial vehicle suppliers creates production bottlenecks and pricing leverage.
- Aluminum input volatility:Panel construction relies on aluminum sheet and extrusion supply subject to energy-cost-driven price swings, compressing margin predictability.
- Towing license fragmentation:National variations in BE license requirements across EU member states create friction for caravan buyers in markets with restrictive regimes.
Strategic Opportunities
- Battery-electric chassis convergence:Integration of electric commercial vehicle platforms with habitation modules offers zero-emission touring propositions as urban low-emission zones expand.
- UK club-culture channel:Touring club membership networks provide direct-to-consumer distribution bypassing traditional dealer infrastructure.
- REACH material innovation:Interior component suppliers developing compliant surface materials gain preferential placement with manufacturers facing substance restriction deadlines.
Industry Challenges
- Electrical systems integration:Complex lithium battery management, inverter sizing, and load balancing require specialized technician training that dealer networks lack at scale.
- Homologation timeline compression:Whole Vehicle Type Approval processes for modified chassis extend lead times, constraining responsiveness to demand fluctuations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caravan and Motorhome Market |
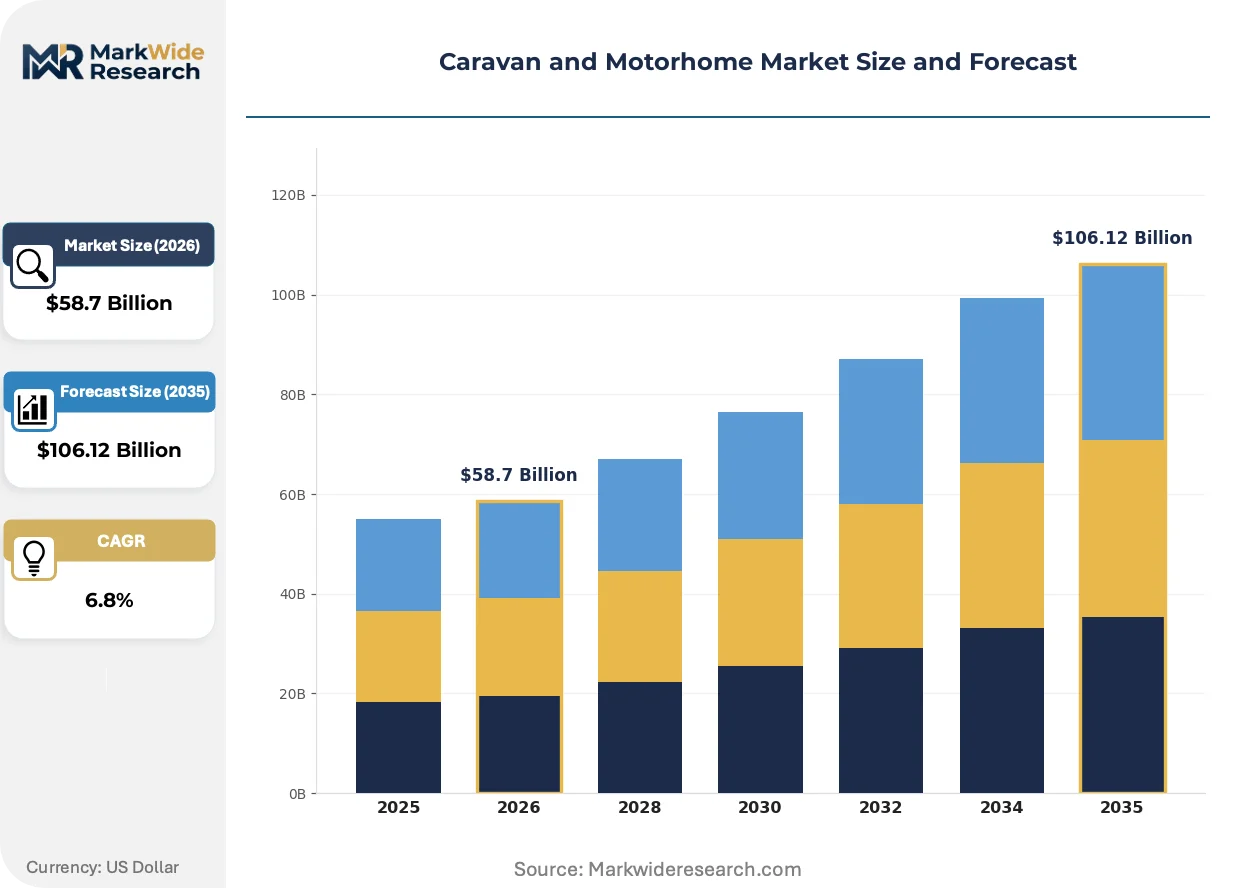
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Trailers, Fifth-Wheel Trailers, Class A Motorhomes, Class C Motorhomes Material: Aluminum, Fiberglass, Wood, Composite End User: Families, Retirees, Adventurers, Rental Services Feature: Solar Power, Entertainment Systems, Kitchen Facilities, Heated Floors |
| Companies Covered | Tiffin Motorhomes, Bailey of Bristol, Winnebago Industries, Coachman, Swift, Thor Industries, Newmar Corporation, Knaus, Forest River Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caravan and Motorhome Market Strategic Shifts
Digital control architectures are virtualizing habitation system management, compressing the traditional electromechanical supply base while enabling remote diagnostics and over-the-air feature activation.
Smart power management platforms using lithium iron phosphate batteries and predictive load algorithms are virtualizing the traditional generator-dependent off-grid experience. Retiree buyers and remote-worker segments adopt these systems fastest, treating electrical autonomy as essential infrastructure. The technology is virtualizing aftermarket generator sales and reshaping dealer service revenue toward software subscriptions.
REACH substance restrictions and CSRD reporting obligations are tightening material traceability requirements across European supply chains. Manufacturers must document chemical composition through tier-three suppliers, increasing procurement overhead. The German and Benelux markets show fastest compliance adaptation due to existing automotive supplier discipline.
Direct manufacturer-to-consumer configuration tools are compressing traditional dealer specification roles. Buyers now finalize floor plans, finishes, and option packages through online portals before dealership contact. This pattern concentrates in the UK and Scandinavian markets where digital commerce penetration in automotive purchase journeys already exceeds continental European norms.
Caravan and Motorhome Market Segmentation
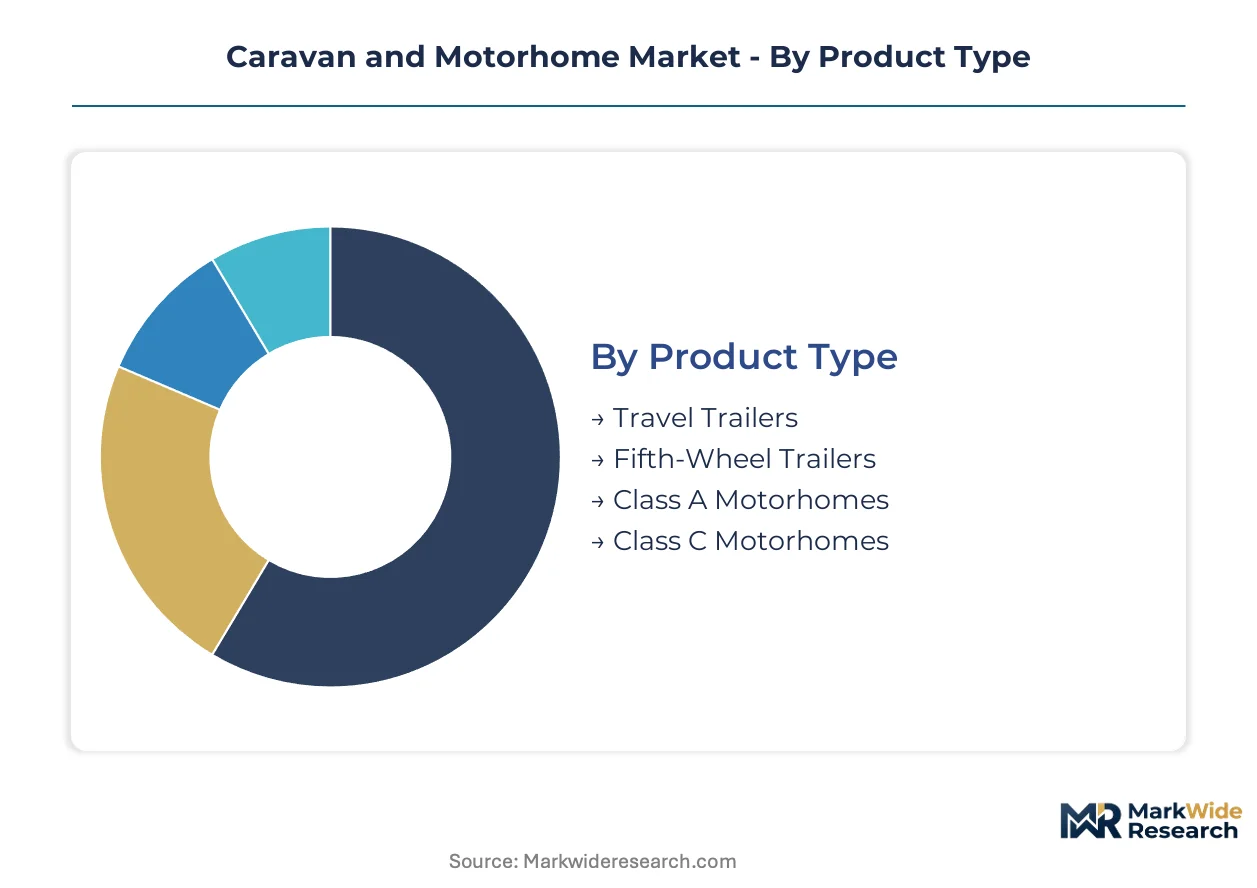
Product architecture in the caravan and motorhome market determines manufacturing complexity, chassis sourcing requirements, and margin structure. Segmentation by construction material and buyer use-case further shapes supply chain configuration and specification bundling across regional markets.
Product Type:
Volume tiering across product categories reflects tow-versus-self-propelled economics and chassis integration depth.
- Travel Trailers:Towed recreational vehicles built on dedicated frames with aluminum or fiberglass habitation modules. Demand concentrates in Germany and the UK where dense campsite infrastructure supports touring cultures and BE license accessibility drives replacement cycles.
- Class C Motorhomes:Self-propelled units constructed on cutaway chassis-cab platforms from commercial vehicle suppliers. European buyers prioritize these for urban maneuverability and lower fuel consumption versus Class A alternatives, concentrating margin pools through limited third-party supplier dependence.
- Fifth-Wheel Trailers:Heavy-duty towed units requiring pickup truck hitch compatibility, dominant in North American markets with distinct towing infrastructure.
- Class A Motorhomes:Integrated coach-built vehicles on proprietary or commercial bus chassis, commanding premium positioning through interior volume and amenity density.
Travel Trailers hold installed capacity. Class C Motorhomes is rotating up the share rankings.
Material:
Construction substrate selection balances strength-to-weight optimization against thermal performance and panel manufacturing throughput.
- Aluminum:Extruded frame members and sheet paneling deliver favorable strength-to-weight ratios that preserve fuel efficiency across travel trailer and motorhome classes. German manufacturers favor aluminum for its recycling compatibility under EU Green Deal circularity expectations.
- Fiberglass:Gel-coated reinforced plastic panels enable complex curvature and seamless weather sealing. French and Italian producers lead fiberglass adoption for premium motorhome exterior finishing where dent resistance and color stability matter.
- Wood:Traditional framing substrate retained in entry-level trailers and internal cabinetry, facing displacement from moisture-resistant alternatives.
- Composite:Multi-layer sandwich panels combining insulation cores with structural skins, gaining specification in off-grid focused builds for thermal efficiency.
Aluminum dominates current production volume. Composite is climbing the fastest as insulation standards tighten.
End User:
Buyer archetype segmentation determines feature bundling intensity, distribution channel preference, and financing structure.
- Retirees:Aging demographic prioritizing extended touring duration and premium climate-control specifications. German and UK retirees drive replacement cycles with club-culture membership influencing brand loyalty and direct manufacturer engagement.
- Families:Multi-occupancy users seeking flexible sleeping configurations and entertainment integration. Demand clusters in school holiday periods with rental services capturing trial-to-purchase conversion.
- Adventurers:Remote-destination seekers requiring off-grid power autonomy and ruggedized chassis modifications. Solar power specification rates exceed market averages among this cohort.
- Rental Services:Fleet operators optimizing for damage resistance, standardized maintenance protocols, and rapid turnaround configurations.
Retirees anchor revenue concentration. Adventurers is rotating up the share rankings.
Feature:
Specification bundling is virtualizing traditional option hierarchies as electrical autonomy becomes baseline expectation.
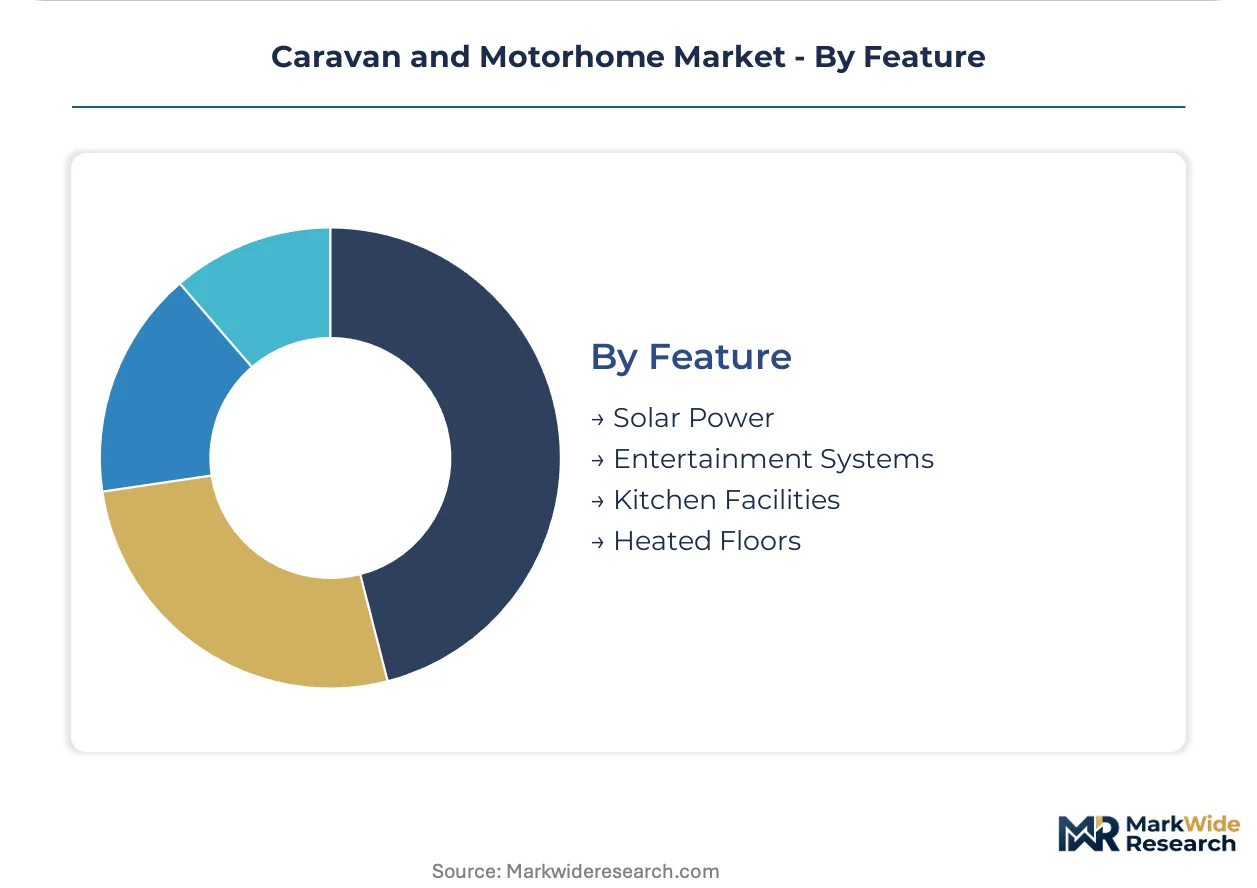
- Solar Power:Photovoltaic roof-integrated systems with lithium battery storage and inverter management. Retiree and remote-worker buyer segments treat electrical autonomy as essential infrastructure, displacing aftermarket generator sales.
- Kitchen Facilities:Compact appliance integration including refrigeration, cooking surfaces, and water systems. European Whole Vehicle Type Approval requirements constrain layout flexibility and supplier qualification.
- Entertainment Systems:Digital media integration with mobile connectivity and streaming compatibility, standard in family-oriented configurations.
- Heated Floors:Hydronic or electric underfloor warming systems, specified heavily in Nordic markets and premium Class A builds for seasonal extension.
Kitchen Facilities hold installed capacity. Solar Power is gaining share fastest as off-grid capability standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA in Germany enforces Whole Vehicle Type Approval standards that shape production specifications across Europe's largest caravan market. The regulator's technical requirements influence chassis modifications and habitation module integration throughout the manufacturing base.
Germany
Retiree demographic expansion and dense campsite infrastructure sustain replacement cycles for touring vehicles. KBA homologation processes govern chassis-cab integration for Class C motorhomes produced in Baden-Württemberg. The Stuttgart industrial cluster concentrates aluminum panel fabrication and climate-control component assembly serving domestic and export demand.
United Kingdom
Club-culture membership networks drive direct manufacturer engagement and brand loyalty among touring enthusiasts. BE license accessibility constraints shape caravan specifications and towing vehicle pairings. The West Midlands manufacturing corridor around Bristol anchors fiberglass motorhome production and interior module assembly for UK and Irish markets.
France
Extended seasonal touring patterns prioritize thermal insulation and climate-control system performance in buyer specifications. ANSM and CNIL oversight intersect with product safety and data privacy in connected vehicle features. The Alsace-Lorraine industrial basin hosts composite panel manufacturing and refrigerator subsystem integration for European-bound products.
United States
Fifth-wheel trailer demand concentrates in states with established RV park infrastructure and pickup truck ownership density. NHTSA governs motorhome chassis safety standards and tow rating certifications affecting product liability exposure. The Indiana manufacturing corridor—centered on Elkhart—hosts concentrated travel trailer and Class A motorhome assembly operations serving North American distribution channels.
Italy
Adventure-oriented buyer segments prioritize off-grid power autonomy and ruggedized chassis modifications for Alpine and Mediterranean touring. ECHA REACH compliance constrains interior material selections and surface coating formulations. The Lombardy industrial cluster around Milan concentrates fiberglass exterior finishing and compact appliance integration for premium motorhome configurations.
Caravan and Motorhome Market Competitive Environment
Capability concentration sits with handcrafted interior specialists; scale advantage sits with chassis-integrated volume producers. The vendor base stratifies across three tiers: premium coach-builders commanding margin through customization depth, mid-market chassis-cab integrators optimizing production velocity, and entry-level trailer assemblers competing on dealer network coverage. Two dominant competitive moves define current positioning: backward integration into aluminum extrusion and panel manufacturing to control input costs, and direct-to-consumer configuration platforms that compress traditional dealer specification roles.
Within the premium coach-builder tier, Tiffin Motorhomes and Newmar Corporation exemplify handcrafted interior differentiation strategies. Thor Industries and Winnebago Industries occupy positions at the scale-driven end, with the former representing chassis-cab integration efficiency and the latter anchoring off-grid power system R&D intensity. Bailey of Bristol sits within the UK-focused brand loyalty segment, illustrating club-culture channel leverage.
| Leading Market Players |
|---|
| Tiffin Motorhomes |
| Bailey of Bristol |
| Winnebago Industries |
| Coachman |
| Swift |
| Thor Industries |
| Newmar Corporation |
| Knaus |
| Forest River Inc. |
| Others |
Value Chain & Pricing Dynamics
Elkhart, Indiana anchors North American travel trailer and Class A motorhome assembly, with its concentrated manufacturing base translating into pricing leverage for chassis-integrated volume producers while compressing margin pools for smaller assemblers dependent on third-party component sourcing.
Pricing Analysis
Geographic price spreads between German and UK markets exceed those within North America due to KBA homologation costs and BE license accessibility constraints. Pricing stratifies across premium coach-built configurations, mid-market chassis-cab integrators, and entry-level trailer assemblers. Cost compression in the aluminum-intensive segment is intensifying because energy-price volatility feeds directly into panel fabrication economics. Rental fleet operators exhibit highest price sensitivity, while retiree buyers purchasing through club-culture channels show lowest elasticity.
Supply Chain Analysis
Aluminum sheet and extrusion feedstock draws from German, Chinese, and North American smelting capacity, with energy-cost differentials driving regional sourcing shifts. Chassis-cab platforms rest on Fiat Ducato, Mercedes Sprinter, and Ford Transit supply from limited commercial vehicle manufacturers. Single-source vulnerability concentrates in lithium battery cell supply for off-grid power systems. Distribution runs through dealer networks in North America and touring club channels in the UK.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled service layers including predictive maintenance subscriptions and over-the-air feature activation are expanding faster than hardware unit economics, repositioning manufacturer value capture toward recurring revenue streams.
For Market Incumbents: Harden chassis-cab integration efficiency through captive aluminum extrusion capacity in the Stuttgart industrial cluster, insulating margin pools from energy-price volatility. Deepen direct-to-consumer configuration platform investment to compress dealer specification roles before club-culture channels consolidate further. Battery-electric chassis availability timelines from commercial vehicle suppliers represent the critical external dependency to monitor.
For New Entrants and Emerging Players: Build out off-grid power system specialization targeting the adventurer buyer segment where solar specification rates exceed market averages and incumbent R&D intensity remains concentrated at Winnebago Industries. The UK club-culture channel offers the most penetrable distribution pathway, bypassing traditional dealer infrastructure through direct manufacturer engagement with touring club membership networks.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic-anchored play because retiree population expansion in Germany, France, and the UK sustains replacement cycle visibility independent of cyclical consumer discretionary pressures. Acquisition targets should concentrate on handcrafted interior specialists with customization depth and established KBA homologation capabilities. The signal to watch is battery-electric chassis availability timelines from commercial vehicle suppliers, as electrification roadmaps in the base truck segment will determine motorhome product viability windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of panel fabrication inputs insulates margin pools from energy-price volatility in European smelting. |
| Direct-to-Consumer Configuration Platform Launch | Online portal specification bypasses dealer roles, concentrating in UK and Scandinavian digital commerce markets. |
| Off-Grid Power System R&D Intensification | Lithium iron phosphate battery management and predictive load algorithms displace aftermarket generator sales. |
| REACH-Compliant Material Supplier Partnership | Preferential placement with manufacturers facing substance restriction deadlines secures tier-three supply chain position. |
| Battery-Electric Chassis Integration Program | Zero-emission touring propositions align with urban low-emission zone expansion across EU member states. |
Study Parameters
Desk research of customs and trade databases, vehicle production registries, and regulatory filing repositories preceded structured interviews with chassis-cab platform engineers, touring club procurement directors, aluminum extrusion plant managers, and aftermarket service heads. Primary fieldwork with dealer network operators and direct-to-consumer platform specialists validated secondary data on specification bundling trends. Bottom-up unit economics modeling triangulated against top-down market sizing from industry association membership and registration databases.
Assumptions around chassis availability from commercial vehicle suppliers, aluminum input price trajectories, and BE license regulatory stability were held fixed across baseline scenarios, with electrification timeline acceleration and REACH compliance deadline shifts modeled as sensitivity variables. Segmentation dimensions included product architecture, construction material, buyer archetype, and feature specification bundling. CAGRs were derived from regression analysis against demographic and macroeconomic drivers, with solar power penetration rates and club-culture membership density serving as industry-specific forecast inputs.
Stress conditions across aluminum price volatility bands, chassis supply disruption scenarios, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with battery-electric chassis availability and F-Gas Regulation refrigerant transition compliance representing specific risk factors that could revise trajectories. Cross-checking against KBA registration data and national touring club membership disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Towable Tubes Market