
 Asia-Pacific Motor Home Market | 2026-2036
Asia-Pacific Motor Home Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Motor Home Market Outlook
Australian chassis builders and Thai assembly plants is restructuring regional supply chains to cut lead times on imported European components. Thor Industries Inc. leverages its North American design heritage to anchor premium Class A positioning across Australian dealerships. SAIC Motor competes through domestic manufacturing scale and localized after-sales networks in China. Great Wall Motor Co., Ltd. specializes in pickup-based camper platforms that dominate price-sensitive segments in Southeast Asia.
A motor home is a self-propelled recreational vehicle combining living quarters with automotive drivetrain, typically featuring integrated sleeping, cooking, and sanitation systems within a gross vehicle weight rating framework. These units serve extended mobility needs across tourism, remote work, and temporary accommodation applications. Class A configurations occupy the premium tier with highest per-unit margins, while Class B van conversions represent the fastest-expanding segment among urban mobile professionals. Solar power integration now sits at the center of technology differentiation, particularly for off-grid adventure tourism deployments across Australia's remote interior.
China's MIIT and Australia's Department of Infrastructure both administer vehicle compliance frameworks that shape motor home homologation, weight limits, and road access permissions across the region. Japan's METI energy-efficiency guidelines further influence power system specifications for imported and domestically produced units. Stakeholders must monitor evolving cross-border type-approval reciprocity between Australia, New Zealand, and ASEAN markets, as regulatory alignment will determine which manufacturers can scale regional distribution without redundant certification burdens.
Market Dynamics
MIIT vehicle classification reforms across China are expanding RV registration access, while Australian chassis builders restructure supply chains around Thai assembly plants to compress lead times on European components. This regulatory-supply nexus is redrawing competitive positioning across the region.
Growth Catalysts
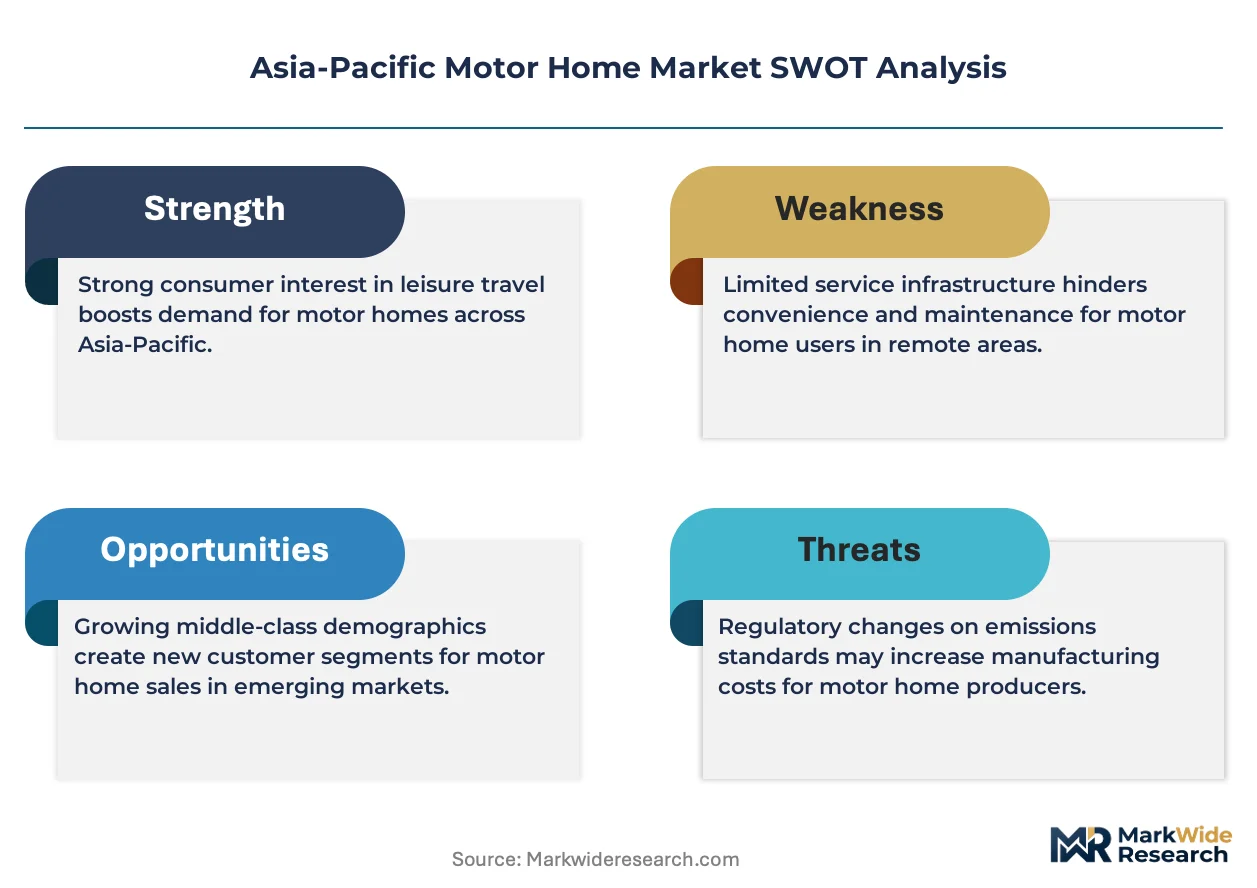
- Extended road tourism:Retirees and leisure travelers across Australia and New Zealand are accelerating motor home adoption for multi-week coastal itineraries.
- MIIT reclassification:China's Ministry of Industry and Information Technology reforms are expanding access to RV registration and road permissions for domestic manufacturers.
- Solar power integration:Off-grid adventure tourism deployments across Australia's remote interior are driving lithium battery and photovoltaic system uptake.
Market Restraints
- European component dependency:Australian and Thai assembly plants face lead time volatility from specialized chassis and appliance suppliers concentrated in Germany and Italy.
- Weight limit heterogeneity:Divergent gross vehicle weight rating frameworks between Australia, New Zealand, and ASEAN markets create redundant engineering requirements.
- Caravan park infrastructure gaps:Southeast Asian markets outside Thailand lack networked service stations and overnight facilities for self-contained units.
Strategic Opportunities
- Pickup-based camper platforms:Price-sensitive segments in Indonesia, Vietnam, and Philippines present white space for compact, locally assembled units on existing truck chassis.
- Cross-border type-approval reciprocity:Emerging alignment between Australia, New Zealand, and ASEAN regulators could eliminate redundant certification burdens for regional manufacturers.
- Remote work mobility:Urban mobile professionals across Australian capital cities are converting Class B van platforms into mobile offices with cellular connectivity packages.
Industry Challenges
- Homologation timeline compression:Australia's Department of Infrastructure compliance frameworks require 12-18 month certification cycles that delay product launches against faster-moving competitors.
- Skilled chassis modification labor:Thai assembly plants face shortages of certified welders and automotive electricians capable of integrating European appliances with Japanese drivetrains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Motor Home Market |
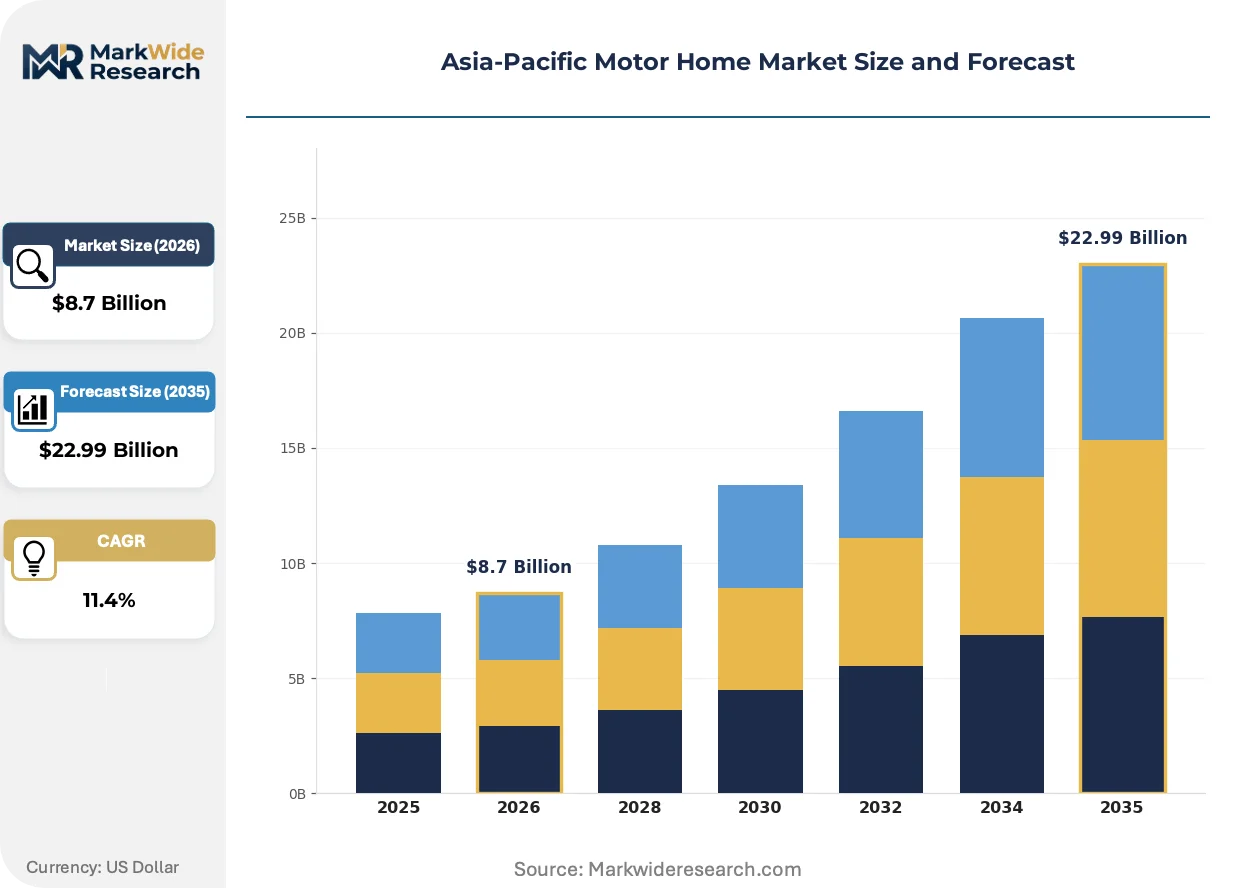
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class C, Truck Camper, Pop-Up Camper Technology: Solar Power, Lithium-Ion Battery, GPS Navigation, Smart Connectivity, Advanced Suspension Application: Recreational Travel, Mobile Office, Temporary Housing, Adventure Tourism, Film Production End User: Leisure Travelers, Small Business Owners, Event Organizers, Mobile Professionals |
| Companies Covered | Thor Industries Inc., SAIC Motor, Great Wall Motor Co., Ltd., Zhongtian Gaoke Special Vehicle Co., Ltd., Baoding Zhongjin Braun RV Manufacturing Co., Ltd., JCBL PLA Motorhome, Zhongyu Automobile, ShanDong Dream Trip RV Co., Ltd., Kalapuraparambil Automobiles, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Motor Home Market Strategic Shifts
Solar power systems are displacing generator-dependent architectures across premium and mid-tier segments, while regulatory alignment efforts and remote work adoption reshape demand patterns. Three forces are restructuring product development priorities.
Lithium-ion battery packs paired with rooftop photovoltaic arrays are integrating into standard factory specifications rather than aftermarket add-ons. Australian adventure tourism operators and New Zealand rental fleets are specifying 400-600 amp-hour systems as baseline equipment. This technology convergence is compressing the addressable market for portable generator manufacturers and elevating electrical system integration to a core purchasing criterion.
Japan's METI energy-efficiency guidelines are tightening standby power consumption limits for imported recreational vehicles. Manufacturers serving the Japanese market must redesign inverter and climate control architectures to meet sub-50-watt idle draw thresholds. Australian exporters targeting Japan are responding by partnering with domestic electronics suppliers for compliant power management systems.
Direct-to-consumer rental platforms are fragmenting traditional dealership and caravan park booking channels. Peer-to-peer motor home sharing networks across Queensland and Victoria are capturing younger travelers who reject package tourism formats. This behavioral shift is most visible in Australian coastal corridors where digital-native operators now coordinate vehicle pickup, insurance, and route planning through unified mobile applications.
Asia-Pacific Motor Home Market Segmentation
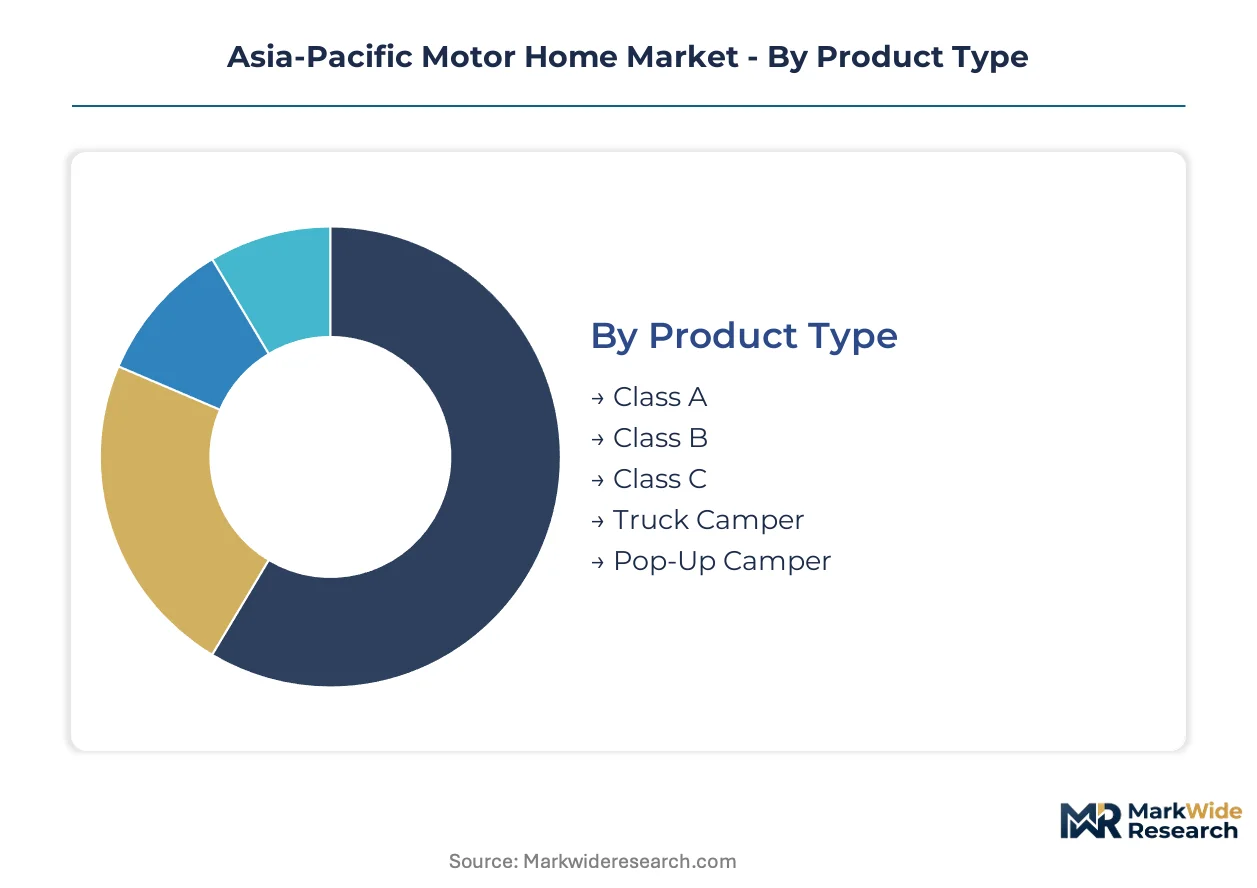
Product architecture and user purpose define competitive boundaries in the Asia-Pacific motor home market. Segment-specific technology integration and regulatory compliance requirements create distinct margin profiles across configuration tiers.
Product Type:
Volume concentrates in compact, chassis-derivative platforms while premium margins anchor integrated coachbuilt designs.
- Class A:Integrated coachbuilt architecture on commercial truck or bus chassis delivers maximum living space and amenity density. Australian retirees and luxury rental operators in Queensland concentrate demand here, though European chassis dependency compresses margins.
- Class B:Van conversion platforms integrate living modules within standard commercial van envelopes. Mobile professionals across Australian capital cities and New Zealand urban centers are converting these into cellular-connected offices, driving the steepest expansion trajectory in the region.
- Class C:Cab-over designs on cutaway van chassis balance space and drivability for family recreational travel.
- Truck Camper:Demountable units on pickup beds dominate Southeast Asian price-sensitive segments, particularly in Thailand assembly networks.
- Pop-Up Camper:Collapsible roof systems reduce storage footprint and aerodynamic drag for occasional users.
Today's leader: Class A. Tomorrow's challenger: Class B.
Technology:
Power system architecture now determines product tier more than chassis specification or interior finish.
- Solar Power:Rooftop photovoltaic arrays paired with lithium storage displace generator dependence across Australian adventure tourism deployments. Queensland rental fleets specify 400-600 amp-hour baseline systems, compressing addressable demand for portable generator suppliers.
- Lithium-Ion Battery:High-density storage enables extended off-grid operation without weight penalties of lead-acid alternatives. New Zealand's Department of Conservation camping restrictions favor self-sufficient electrical architectures, accelerating factory integration over aftermarket retrofit.
- GPS Navigation:Integrated routing systems optimize fuel efficiency and caravan park proximity for extended itineraries.
- Smart Connectivity:Cellular boosters and WiFi infrastructure support remote work functionality in mobile office configurations.
- Advanced Suspension:Air-ride and adaptive damping systems improve stability on unsealed roads prevalent in Australia's remote interior.
Current standard: Solar-lithium integration. Emerging differentiator: Smart connectivity packages.
Application:
Recreational use anchors volume while professional applications command pricing premiums through specialized fit-out requirements.
- Recreational Travel:Multi-week coastal itineraries by retirees across Australia and New Zealand constitute the foundational demand pool. Victoria's Great Ocean Road and Queensland's tropical corridors concentrate visible deployment.
- Mobile Office:Class B van conversions with dedicated workspace, power redundancy, and cellular connectivity serve remote work adoption. Australian capital city professionals are the primary adopters, with uptake accelerating in Sydney and Melbourne metropolitan rings.
- Temporary Housing:Disaster relief and seasonal worker accommodation deploy modified Class C and truck camper platforms.
- Adventure Tourism:Off-grid capability requirements in Western Australia and Northern Territory drive solar-electrical specification intensity.
- Film Production:Mobile dressing rooms and equipment transport units require custom bodywork and climate control beyond standard recreational specifications.
Volume foundation: Recreational travel. Margin expansion: Mobile office.
End User:
Leisure travelers dominate unit volume while commercial operators concentrate in rental and event service niches.
- Leisure Travelers:Retirees and extended holiday-takers across Australia and New Zealand purchase or rent for multi-week itineraries. This segment absorbs the majority of Class A and Class C production through Queensland and Victoria dealership networks.
- Small Business Owners:Tradespeople and mobile service operators deploy truck camper and Class C units as combined transport and accommodation for remote job sites.
- Event Organizers:Temporary command centers and hospitality units for outdoor festivals require rapid deployment capability and self-contained servicing.
- Mobile Professionals:Knowledge workers leveraging remote work policies select Class B platforms with integrated connectivity and ergonomic workspace design.
Core purchaser: Leisure travelers. Fastest-climbing category: Mobile professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai assembly plants attract Australian chassis builders seeking lower-cost homologation pathways than European alternatives, while China's MIIT reforms compress domestic RV certification timelines. This regulatory-arbitrage dynamic redistributes production capacity across the region.
Australia
Queensland's coastal corridors and Victoria's Great Ocean Road concentrate retiree demand for extended multi-week itineraries. The Department of Infrastructure administers 12-18 month vehicle compliance frameworks that shape homologation timelines. Brisbane and Melbourne dealership networks anchor Class A and Class C distribution, with solar-lithium specifications now standard for remote interior deployments.
China
Domestic manufacturers leverage MIIT vehicle classification reforms to expand RV registration access and road permissions. The Ministry of Industry and Information Technology oversees weight limit frameworks and type-approval reciprocity negotiations. Yangtze River Delta assembly clusters around Shanghai integrate localized after-sales networks with captive manufacturing scale.
New Zealand
Department of Conservation camping restrictions favor self-sufficient electrical architectures for adventure tourism operators. The country's national transport regulator coordinates cross-border type-approval alignment with Australian counterparts. Auckland and Christchurch urban centers drive Class B van conversion demand among mobile professionals seeking cellular-connected remote work platforms.
Thailand
Price-sensitive pickup-based camper segments dominate regional assembly output for Southeast Asian export markets. The national industrial standards body facilitates component import licensing for European chassis and appliance suppliers. Bangkok-adjacent manufacturing zones specialize in welding and automotive electrical integration for Japanese drivetrain compatibility.
Japan
METI energy-efficiency guidelines tighten standby power consumption limits below 50-watt idle draw thresholds for imported recreational vehicles. The Ministry of Economy, Trade and Industry shapes inverter and climate control redesign requirements. Kanto region distributors partner with domestic electronics suppliers for compliant power management system integration.
Asia-Pacific Motor Home Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pickup-based platform specialization and solar-electrical integration. The vendor base stratifies across three tiers: North American design heritage anchors premium Class A positioning, Chinese manufacturing scale dominates domestic volume, and Thai-integrated specialists serve Southeast Asian price sensitivity. Three archetypes define competitive boundaries: chassis-derivative assemblers, integrated coachbuilt manufacturers, and van conversion specialists. Dominant moves include backward integration into lithium battery supply chains and geographic expansion through Australian dealership network acquisition.
Within the premium-tier vector, Thor Industries Inc. represents North American design heritage positioning. SAIC Motor exemplifies domestic manufacturing scale archetypes. Great Wall Motor Co., Ltd. anchors pickup-based camper specialization for price-sensitive segments. These three entities collectively illustrate how geographic origin and structural form shape strategic options across the regional market.
| Leading Market Players |
|---|
| Thor Industries Inc. |
| SAIC Motor |
| Great Wall Motor Co., Ltd. |
| Zhongtian Gaoke Special Vehicle Co., Ltd. |
| Baoding Zhongjin Braun RV Manufacturing Co., Ltd. |
| JCBL PLA Motorhome |
| Zhongyu Automobile |
| ShanDong Dream Trip RV Co., Ltd. |
| Kalapuraparambil Automobiles |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy pricing benchmarks cascade through Thai assembly plants into Australian dealership markups, compressing margins on European chassis-dependent Class A units while pickup-based camper platforms in Southeast Asia absorb cost volatility through localized steel sourcing.
Pricing Analysis
Dealer markup layers absorb 18-25% of factory gate pricing across Australian distribution networks, with three-tier pricing structure across premium, standard, and economy levels separating integrated coachbuilt designs from chassis-derivative conversions. Price differentiation hinges on solar-lithium electrical specification intensity and MIIT certification tier for China-bound units. Cost compression in mid-tier Class C segments is intensifying because Thai assembly plants compete on labor-adjusted landed costs. Fleet rental operators exhibit lowest price sensitivity; individual retirees in Queensland and Victoria show highest elasticity to financing terms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Queensland rental fleets, while specialized distributors serve fragmented retail demand across Australian capital cities. Manufacturing gravity centers on Thailand for ASEAN export markets, China for domestic volume, and Germany plus Italy for chassis and appliance inputs. European component dependencies rest on German commercial vehicle chassis and Italian climate-control systems. Single-source vulnerability concentrates in lithium battery cell supply from South Korean and Japanese producers. Distribution runs through Bangkok-adjacent assembly zones into Australian dealership networks and Chinese MIIT-licensed registration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Solar-lithium integration specifications now function as baseline purchasing criteria rather than premium upgrades across Australian adventure tourism operators.
For Market Incumbents: Anticipate margin compression from Chinese domestic manufacturers leveraging MIIT reclassification for faster product cycles. Defend positioning through backward integration into lithium battery supply chains and captive control of Queensland dealership networks. Certification investment in cross-border type-approval reciprocity between Australia and New Zealand reduces redundant engineering burdens against emerging Thai-integrated competitors.
For New Entrants and Emerging Players: Begin with pickup-based camper platform specialization for Indonesia, Vietnam, and Philippines price-sensitive segments. White space concentrates in compact demountable units on existing Japanese drivetrain chassis with localized welding and electrical integration. Go-to-market angle targets small business owner segments requiring combined transport-accommodation for remote job sites, bypassing saturated leisure traveler channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with Thai-integrated specialists possessing Japanese drivetrain compatibility and European appliance integration capabilities. Long-term viability favors entities with captive assembly capacity and cross-border type-approval alignment across the analysis window. Acquisition target archetype: mid-scale assemblers with certified welder and automotive electrician labor pools. Signal to watch: MIIT reciprocity negotiations with ASEAN regulators as inflection indicator for regional scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Battery Supply | Captive electrical system sourcing reduces dependency on South Korean cell producers and compresses lead times for Queensland rental fleet specifications. |
| Cross-Border Type-Approval Reciprocity Investment | Alignment between Australia's Department of Infrastructure and New Zealand's national transport regulator eliminates redundant certification cycles. |
| Pickup-Based Platform Specialization | Compact demountable designs on Japanese drivetrains penetrate Indonesian and Vietnamese price-sensitive segments with localized assembly economics. |
| Direct-to-Consumer Rental Platform Launch | Peer-to-peer motor home sharing networks across Victoria and Queensland coastal corridors capture digital-native travelers outside traditional dealership channels. |
| MIIT Certification Fast-Track Partnership | Domestic Chinese manufacturers leverage Ministry of Industry and Information Technology reclassification for accelerated RV registration and road permission access. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with RV fleet procurement managers, chassis builder operations directors, Thai assembly plant supervisors, Australian dealership principals, and MIIT regulatory affairs specialists. Secondary validation draws from vehicle production databases, customs and trade flow records, Department of Infrastructure compliance filings, and MIIT type-approval registries. Triangulation between demand-side itinerary pattern analysis and supply-side component import licensing data anchors volume estimates.
Input-output matrices map chassis sourcing flows through Thai welding integration into Australian homologation cycles, with segmentation dimensions spanning product architecture, power system technology, application purpose, and end-user archetype. CAGRs derive from installed base retirement curves and replacement demand modeling across the projection horizon. Forecast inputs include MIIT regulatory timeline assumptions and lithium battery cost curve trajectories for solar-electrical specification penetration.
Several conditions sit outside the modeled scope, including geopolitical disruption to European chassis supply, abrupt MIIT policy reversals, and pandemic-scale mobility restrictions. Forecasts reflect assumptions around regulatory alignment momentum and commodity price stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Caravan and Motorhome Market