
 Europe Luxury Yacht Market | 2026-2036
Europe Luxury Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Yacht Market Intelligence
Italian superyacht builders is repositioning their composite and steel fabrication lines toward low-emission hull designs. Fincantieri Yachts leverages its Trieste shipyard infrastructure to dominate large custom builds. Azimut Benetti sustains production agility across multiple Mediterranean facilities. Ferretti S.p.A. specializes in flybridge and megayacht segments with integrated design-to-delivery control.
Europe luxury yachts are privately commissioned vessels exceeding 24 meters in length, constructed from advanced composites, steel, or aluminum alloy with diesel-electric or hybrid propulsion architectures designed for extended blue-water cruising and charter operations. Motor yachts occupy the dominant revenue position due to higher unit values and customization depth, while explorer yachts represent the fastest-expanding product type as owners prioritize polar-capable range and expedition-grade hull forms. Hybrid engine technology commands concentrated R&D investment as builders respond to tightening emission controls in EU territorial waters and Monaco's port authority restrictions.
EMA environmental guidelines, EU Green Deal maritime provisions, and REACH chemical compliance for antifouling coatings collectively elevate material costs and certification burdens for hull construction across European yards. The F-Gas Regulation restricts refrigerant choices in onboard climate systems, pushing suppliers toward CO2-based alternatives. Stakeholders must monitor how IMO carbon intensity indicators reshape buyer specifications and yard order books without assuming uniform regulatory timelines across Mediterranean flag states.
Market Dynamics
The EU Green Deal's maritime decarbonization timeline is compressing yard investment cycles, forcing composite hull fabricators and steel specialists to retool for hybrid-electric propulsion before 2030 compliance deadlines bite.
Growth Catalysts
- IMO Carbon Intensity Indicators:The maritime regulator's vessel efficiency standards are accelerating buyer preference for diesel-electric architectures in the 40-80 meter charter segment.
- Mediterranean charter circuit expansion:Ultra-high-net-worth individuals are commissioning extended-range explorer hulls capable of polar itineraries beyond traditional Côte d'Azur routes.
- F-Gas Regulation phase-down:The EU's refrigerant restrictions are creating aftermarket retrofit demand for CO2-based climate systems across existing superyacht fleets.
Market Restraints
- Advanced composite input costs:Pre-preg carbon fiber and epoxy resin prices fluctuate with aerospace sector demand, squeezing margin on custom builds under 50 meters.
- Viareggio-La Spezia supply concentration:Italian hull fabrication clusters face capacity bottlenecks during peak commissioning seasons, extending delivery timelines.
- REACH antifouling compliance:ECHA chemical restrictions on copper-based hull coatings are eliminating proven formulations before biofouling alternatives achieve equivalent performance.
Strategic Opportunities
- Norwegian fjord expedition cruising:Underdeveloped charter infrastructure above the Arctic Circle rewards polar-capable hull designs with ice-class certification.
- EMA environmental guideline alignment:Builders achieving early compliance with EU maritime sustainability frameworks secure preferential mooring access in Monaco and Barcelona.
- Solid-state battery integration:Converging lithium-metal cell chemistry with diesel-electric gensets enables overnight silent anchorage without generator noise.
Industry Challenges
- Naval architect talent scarcity:Specialized designers fluent in computational fluid dynamics for hybrid propulsion integration command premium compensation, constraining yard expansion.
- CE marking timeline compression:Revised recreational craft directives extend certification review periods, delaying hull delivery and charter revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Yacht Market |
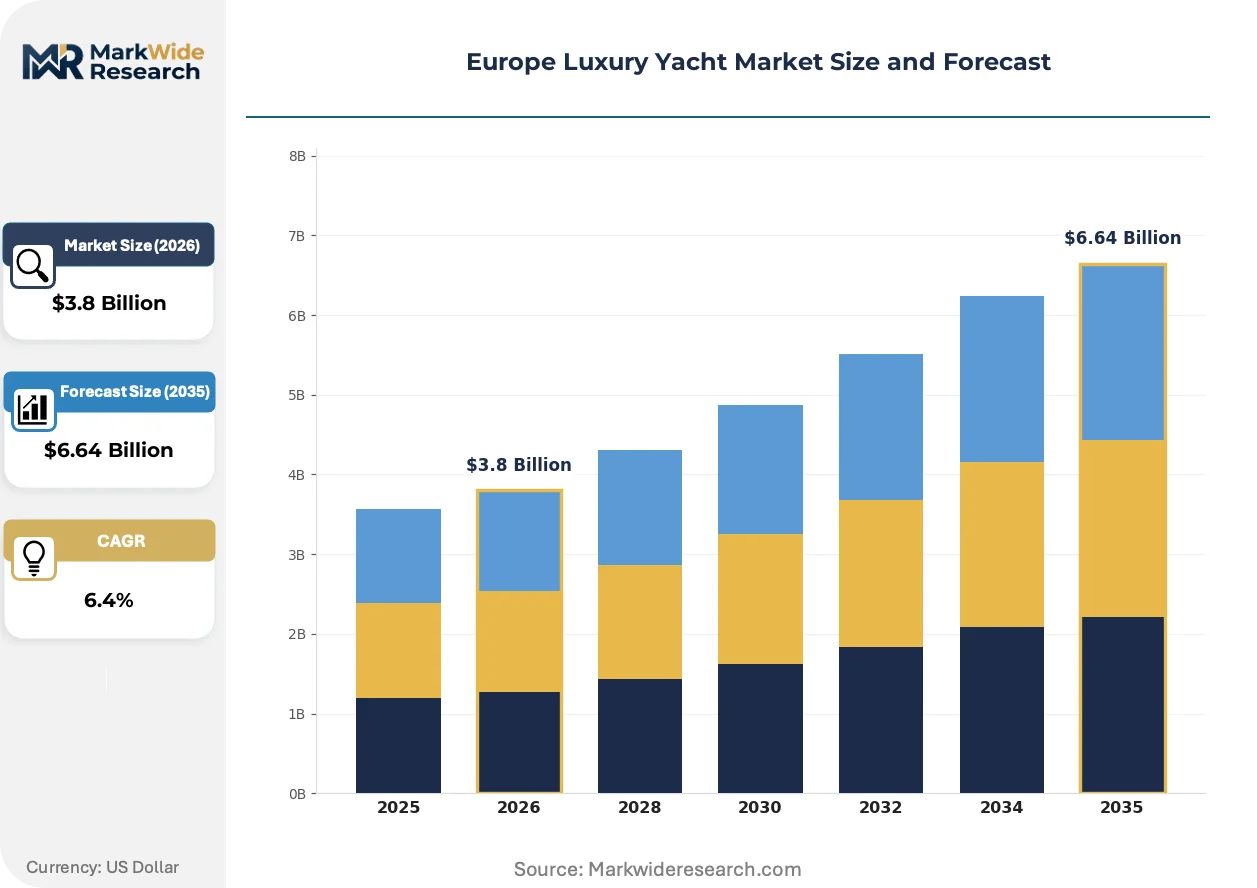
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Yachts, Sailing Yachts, Explorer Yachts, Catamarans End User: Private Owners, Charter Services, Corporate Clients, Luxury Resorts Size: Small (Up to 30 ft), Medium (30 ft to 70 ft), Large (70 ft to 100 ft), Mega Yachts (Over 100 ft) Technology: Hybrid Engines, Navigation Systems, Stabilization Technology, Automation |
| Companies Covered | Azimut Benetti, Fincantieri Yachts, Fr. Lürssen Werft GmbH & Co.KG, Sunseeker, Nobiskrug Yacht GmBH, Ferretti S.p.A., Feadship, Princess Yachts, Sanlorenzo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Yacht Market Strategic Shifts & Innovations
Propulsion electrification and hull material science are converging to redefine performance benchmarks, while regulatory pressure on emissions forces rapid adaptation across Mediterranean yards.
Hybrid-electric drivetrains with lithium-ion storage banks are decentralizing power architecture away from centralized diesel plants toward distributed pod-mounted motors. Charter operators in the 30-50 meter segment are specifying these configurations to meet Monaco port authority noise restrictions. The technology is decentralizing engine room spatial requirements, freeing hull volume for guest accommodation expansion.
The EU Green Deal's maritime provisions are mandating shore-power compatibility and emission-control-area readiness for all new builds over 500 gross tons. Fincantieri Yachts and Ferretti S.p.A. are pre-wiring hulls for cold-ironing infrastructure ahead of 2025 Mediterranean port mandates. Explorer yacht specifications are most affected, with owners demanding extended blue-water range without compromising territorial water compliance.
Commissioning contracts are fragmenting from traditional build-to-spec models toward fractional ownership and managed charter programs. Family offices are purchasing hull shares through specialized yacht management platforms rather than assuming full operational burden. This pattern concentrates in Italy and France, where established charter infrastructure supports revenue-sharing arrangements that offset capital commitment.
Europe Luxury Yacht Market Segmentation
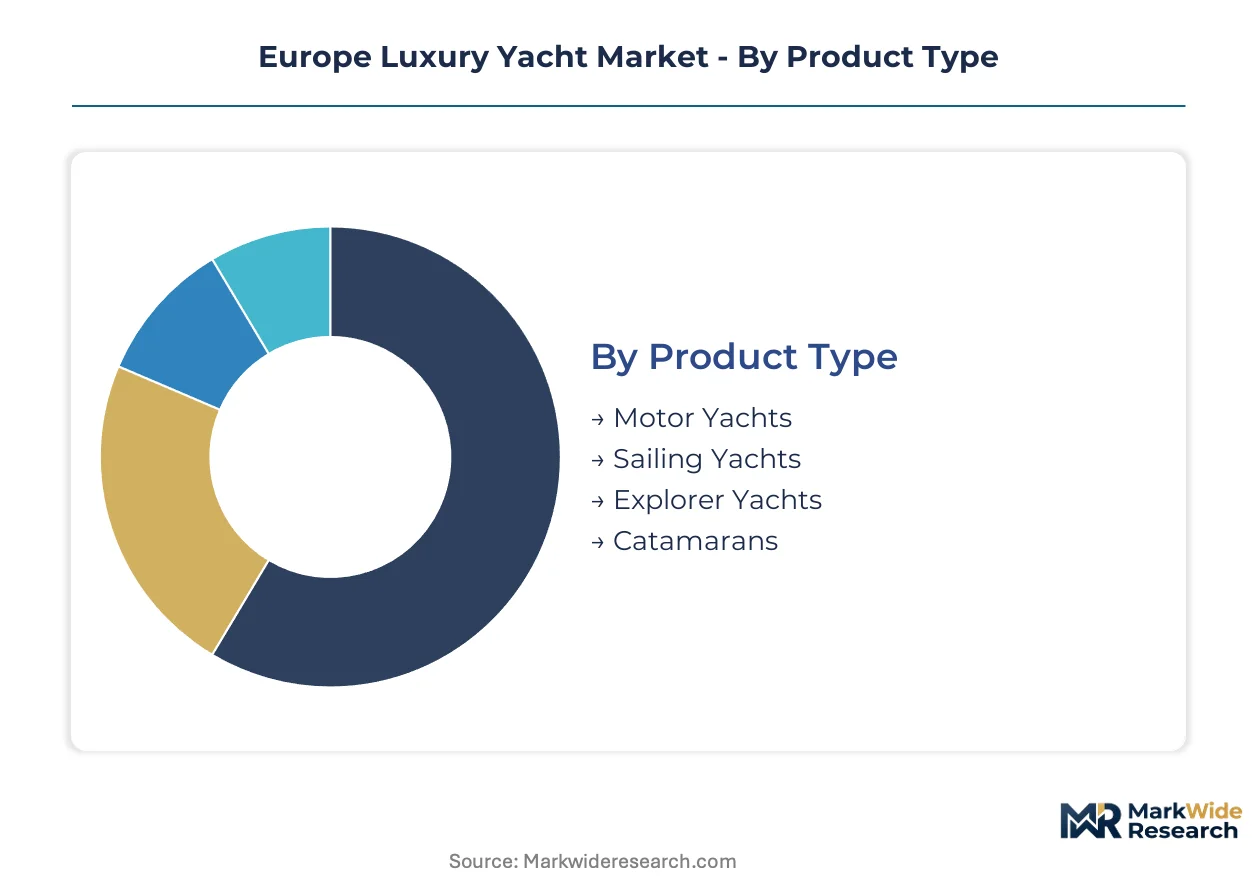
Segmentation in the Europe luxury yacht market reveals how capital deployment, regulatory compliance, and owner preferences fragment across distinct vessel categories. Builders calibrate composite fabrication lines and propulsion architectures to match the technical and experiential demands of each segment.
Product Type:
Capital intensity escalates sharply with hull complexity and propulsion sophistication, with composite-intensive motor platforms demanding the heaviest upfront tooling investment.
- Motor Yachts:Diesel-electric or conventional diesel propulsion dominates this segment, with hulls constructed from advanced composites, steel, or aluminum alloy. Demand concentrates among ultra-high-net-worth individuals commissioning vessels for Mediterranean charter circuits, where Azimut Benetti and Ferretti S.p.A. anchor production. The EU Green Deal's maritime decarbonization timeline is compressing yard investment cycles for hybrid-electric retooling.
- Explorer Yachts:Polar-capable range and expedition-grade hull forms define this category, with ice-class certification enabling Norwegian fjord itineraries above the Arctic Circle. Owners prioritize extended blue-water range without compromising territorial water compliance under IMO carbon intensity indicators.
- Sailing Yachts:Mast and rigging systems add structural complexity beyond motor equivalents, appealing to owner-operators seeking hands-on navigation.
- Catamarans:Twin-hull stability and beam width maximize deck space for charter guest accommodation.
Motor yachts absorb the bulk of installed capacity; explorer yachts are expanding most quickly.
End User:
Procurement patterns diverge sharply between operational models that assume full capital burden versus those that distribute ownership across managed platforms.
- Private Owners:Family offices commission custom builds through direct yard relationships, prioritizing design-to-delivery control and bespoke interior specifications. Italian and French family offices increasingly favor fractional ownership structures through specialized yacht management platforms.
- Charter Services:Fleet operators specify standardized configurations optimized for crew efficiency and maintenance predictability across multiple hulls.
- Corporate Clients:Hospitality and entertainment enterprises acquire vessels for client entertainment and executive retreat programming.
- Luxury Resorts:Integrated coastal properties deploy yachts as extensions of land-based guest experience infrastructure.
Private owners command the premium customization tier; charter services drive volume throughput.
Size:
Hull length thresholds determine regulatory jurisdiction, crew requirements, and port access privileges across Mediterranean mooring infrastructure.
- Small (Up to 30 ft):Owner-operated vessels with minimal crew requirements, constructed from fiberglass composites for cost-efficient production.
- Medium (30 ft to 70 ft):The 30-50 meter charter segment is specifying hybrid-electric configurations to meet Monaco port authority noise restrictions. CE marking timeline compression under revised recreational craft directives most acutely affects this bracket.
- Large (70 ft to 100 ft):Steel and aluminum alloy construction dominates, with Fincantieri Yachts leveraging Trieste shipyard infrastructure for custom builds. EMA environmental guidelines and EU Green Deal maritime provisions mandate shore-power compatibility for this tonnage range.
- Mega Yachts (Over 100 ft):All new builds over 500 gross tons face emission-control-area readiness requirements. F-Gas Regulation phase-down creates aftermarket retrofit demand for CO2-based climate systems across existing fleets.
Large hulls capture the dominant revenue position; mega yachts claim the steepest expansion trajectory.
Technology:
R&D allocation concentrates where regulatory pressure intersects with owner experience differentiation.
- Hybrid Engines:Lithium-ion storage banks and distributed pod-mounted motors decentralize power architecture away from centralized diesel plants. Solid-state battery integration with diesel-electric gensets enables overnight silent anchorage without generator noise.
- Navigation Systems:Computational fluid dynamics integration demands specialized naval architect talent commanding premium compensation.
- Stabilization Technology:Gyroscopic and fin-based systems reduce roll for guest comfort in open-water conditions.
- Automation:Bridge and engineering control consolidation reduces crew headcount requirements for owner-operated vessels.
Hybrid engines absorb concentrated yard investment; automation is climbing the fastest as labor costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy stockpiles in Hamburg and carbon fiber pre-preg shipments through Rotterdam anchor northern European superyacht supply chains. Mediterranean basin demand concentrates around Italian composite fabrication clusters and French Riviera charter infrastructure. Builders calibrate hull production across these nodes to match emission-control timelines and owner commissioning preferences.
Italy
Viareggio and La Spezia host the densest concentration of composite hull fabricators serving the 24-80 meter charter segment. EU Green Deal maritime decarbonization mandates compress yard investment cycles for hybrid-electric retooling before 2030 compliance deadlines. Azimut Benetti and Sanlorenzo anchor production agility across multiple Mediterranean facilities, with Ferretti S.p.A. specializing in flybridge configurations.
France
Cannes and Monaco mooring infrastructure drives demand for emission-compliant hulls under port authority noise restrictions. EMA environmental guidelines and F-Gas Regulation phase-downs elevate certification burdens for onboard climate systems. Chantiers de l'Atlantique and Beneteau Group occupy positions within the large custom and production yacht tiers respectively.
Germany
Fr. Lürssen Werft GmbH & Co.KG and Nobiskrug Yacht GmBH exemplify steel and aluminum specialists serving the mega yacht segment above 80 meters. REACH chemical compliance for antifouling coatings eliminates proven copper-based formulations before biofouling alternatives achieve equivalent performance. Hamburg and Bremen concentrate naval architect talent fluent in computational fluid dynamics.
Netherlands
Feadship anchors the custom superyacht segment through Amsterdam and Kaag Island facilities. CE marking timeline compression under revised recreational craft directives extends certification review periods for hull delivery. Dutch builders pre-wire hulls for cold-ironing infrastructure ahead of 2025 Mediterranean port mandates.
United Kingdom
Sunseeker and Princess Yachts occupy positions within the mid-size motor yacht segment, with Poole and Plymouth anchoring production. IMO carbon intensity indicators reshape buyer specifications toward diesel-electric architectures. British yards face capacity constraints from specialized designer scarcity and extended regulatory review periods.
Europe Luxury Yacht Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue expedition-grade hull specialization and solid-state battery integration. Italian and Dutch yards consolidate around custom composite fabrication, while German builders dominate steel-intensive mega yacht construction. Three archetypes define positioning: vertically integrated design-to-delivery specialists, modular platform producers, and expedition-focused naval architects. Competitive moves concentrate on hybrid propulsion R&D partnerships and Arctic-capable hull certification acquisition.
Within the Italian integrated tier, Azimut Benetti and Sanlorenzo represent design-to-delivery control; Ferretti S.p.A. occupies a position within the flybridge and megayacht specialization vector. German steel specialists Fr. Lürssen Werft GmbH & Co.KG and Nobiskrug Yacht GmBH exemplify large custom build concentration. Dutch custom producer Feadship anchors the premium commissioning segment alongside British mid-size motor yacht fabricators Sunseeker and Princess Yachts.
| Leading Market Players |
|---|
| Azimut Benetti |
| Fincantieri Yachts |
| Fr. Lürssen Werft GmbH & Co.KG |
| Sunseeker |
| Nobiskrug Yacht GmBH |
| Ferretti S.p.A. |
| Feadship |
| Princess Yachts |
| Sanlorenzo |
| Others |
Cost & Logistics Intelligence
EU Green Deal maritime decarbonization mandates gate qualified supply access and premium-tier pricing power, as yards achieving early IMO carbon intensity compliance command preferential mooring privileges in Monaco and Barcelona while non-compliant builders face exclusion from high-value charter circuits.
Pricing Analysis
Extended warranty and post-delivery service bundling separate premium Italian yards from unbundled competitors, with Azimut Benetti and Ferretti S.p.A. folding five-year hybrid system coverage into base contracts while smaller Viareggio fabricators charge separately for genset maintenance. Pricing stratifies across ice-class certified, hybrid-electric, and conventional diesel tiers, with polar-capable hull forms capturing substantial premiums due to Norwegian fjord route access. Cost compression in the 30-50 meter composite segment intensifies as aerospace sector demand for pre-preg carbon fiber squeezes margin. Charter fleet operators exhibit highest price sensitivity due to standardized configuration requirements, while family office private owners prioritize design-to-delivery control over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Italian carbon fiber pre-preg suppliers concentrated around Viareggio and La Spezia, where peak commissioning seasons trigger capacity bottlenecks extending delivery timelines. Raw material flows draw from German titanium alloy stockpiles in Hamburg, Dutch epoxy resin shipments through Rotterdam, and French copper-based antifouling formulations now restricted under REACH compliance. Tariff exposure on Chinese lithium-ion battery cells amplifies cost uncertainty for hybrid-electric drivetrain integration. Distribution runs through Mediterranean charter management platforms in Cannes and Monaco, with northern European yards leveraging direct yard-to-owner commissioning for mega yacht segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating around upstream control over hybrid propulsion R&D and downstream capture of charter revenue streams, as builders race to integrate solid-state battery partnerships and polar-capable hull certification before 2030 compliance deadlines.
For Market Incumbents: Deepen in-house production of lithium-ion storage systems through partnerships with emerging solid-state cell chemistry specialists, insulating margin from Chinese battery tariff exposure. Expand Trieste and Amsterdam facilities to anchor ice-class certification capacity before Norwegian fjord infrastructure matures, preempting German steel specialists from capturing polar expedition demand. For New Entrants and Emerging Players: Launch via fractional ownership platforms targeting Italian and French family offices seeking managed charter exposure without full operational burden. Target the underdeveloped Arctic Circle expedition segment above 70 degrees north, where polar-capable hull scarcity meets rising ultra-high-net-worth demand for differentiated itineraries beyond traditional Côte d'Azur routes. For Investors and Strategic Acquirers: First IMO carbon intensity indicator compliance announcements from Mediterranean flag states are the leading indicator that order book concentration will shift toward hybrid-electric yards, signaling acquisition timing for distressed conventional diesel specialists. Prioritize design-to-delivery control capabilities and EMA environmental guideline alignment as durable moats across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion R&D Partnership | Secures lithium-metal cell chemistry access ahead of F-Gas Regulation phase-down deadlines. |
| Ice-Class Certification Acquisition | Unlocks Norwegian fjord charter routes above Arctic Circle where infrastructure remains underdeveloped. |
| Fractional Ownership Platform Launch | Captures family office capital deployment shifting from full ownership to managed revenue-sharing structures. |
| Cold-Ironing Infrastructure Pre-Wiring | Ensures EU Green Deal shore-power compliance for 500+ gross ton vessels before 2025 Mediterranean port mandates. |
| Naval Architect Talent Acquisition | Addresses computational fluid dynamics specialist scarcity constraining yard expansion in Hamburg and Bremen clusters. |
Research Approach
Document review covered EU maritime regulatory filings, IMO vessel efficiency submissions, and Mediterranean port authority mooring access records, complemented by interviews with Italian composite hull fabricators, German steel yacht specialists, Dutch custom build directors, Monaco charter fleet operators, and family office yacht management advisors. Secondary validation drew from EMA environmental guideline databases, REACH chemical restriction notices, F-Gas Regulation phase-down schedules, and Mediterranean customs trade data. Bottom-up order book analysis triangulated against top-down ultra-high-net-worth wealth distribution estimates across the analysis window.
Historical build data cross-referenced against panel input from naval architects and procurement directors anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include hull material class, propulsion architecture, length tier, and charter versus private ownership structure. CAGRs derived from yard capacity utilization rates, composite input cost trajectories, and regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporated polar expedition route development patterns and lithium-ion battery chemistry advancement curves.
IMO carbon intensity indicator enforcement delays, REACH antifouling formulation approval setbacks, and lithium supply chain disruption are the dominant revision risks to modeled outputs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Teardrop Trailer Market