
 United States RV Rental Market | 2026-2036
United States RV Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United States RV Rental Market Outlook
Luxury motorhome specifications is unwinding the traditional rental market as consumers expect hotel-grade interiors, solar power systems, and smart connectivity in mobile accommodations. Cruise America dominates the branded fleet segment with standardized Class C offerings across hundreds of rental centers. Outdoorsy leverages peer-to-peer network effects to unlock privately owned RV inventory for short-term rentals. El Monte RV specializes in long-haul highway configurations optimized for cross-country itineraries.
United States RV rental denotes the short-term commercial provision of recreational vehicles ranging from compact camper vans to diesel-powered Class A motorhomes exceeding forty feet in length, typically equipped with sleeping quarters, kitchenettes, climate control systems, and onboard waste management for temporary habitation during travel. The primary commercial purpose centers on delivering mobile lodging alternatives to hotels for domestic tourism, outdoor recreation, and remote work mobility. Class B camper vans capture margin pools from solo travelers and adventure seekers prioritizing maneuverability and fuel efficiency over spaciousness. Peer-to-peer networks represent the fastest-growing booking channel as digital platforms displace traditional travel agency intermediation. Families and group travelers sustain demand concentration in Class C motorhomes where sleeping capacity and value intersect.
NHTSA mandates seatbelt configurations and crashworthiness standards for motorhome chassis, while EPA Tier 3 emissions rules constrain diesel powertrain options available to fleet operators. State-level insurance minimums and commercial vehicle registration requirements create operational complexity for peer-to-peer hosts entering the market. Stakeholders must monitor evolving FMCSA commercial driver licensing thresholds as larger RV classifications approach weight thresholds requiring specialized operator credentials.
Market Dynamics
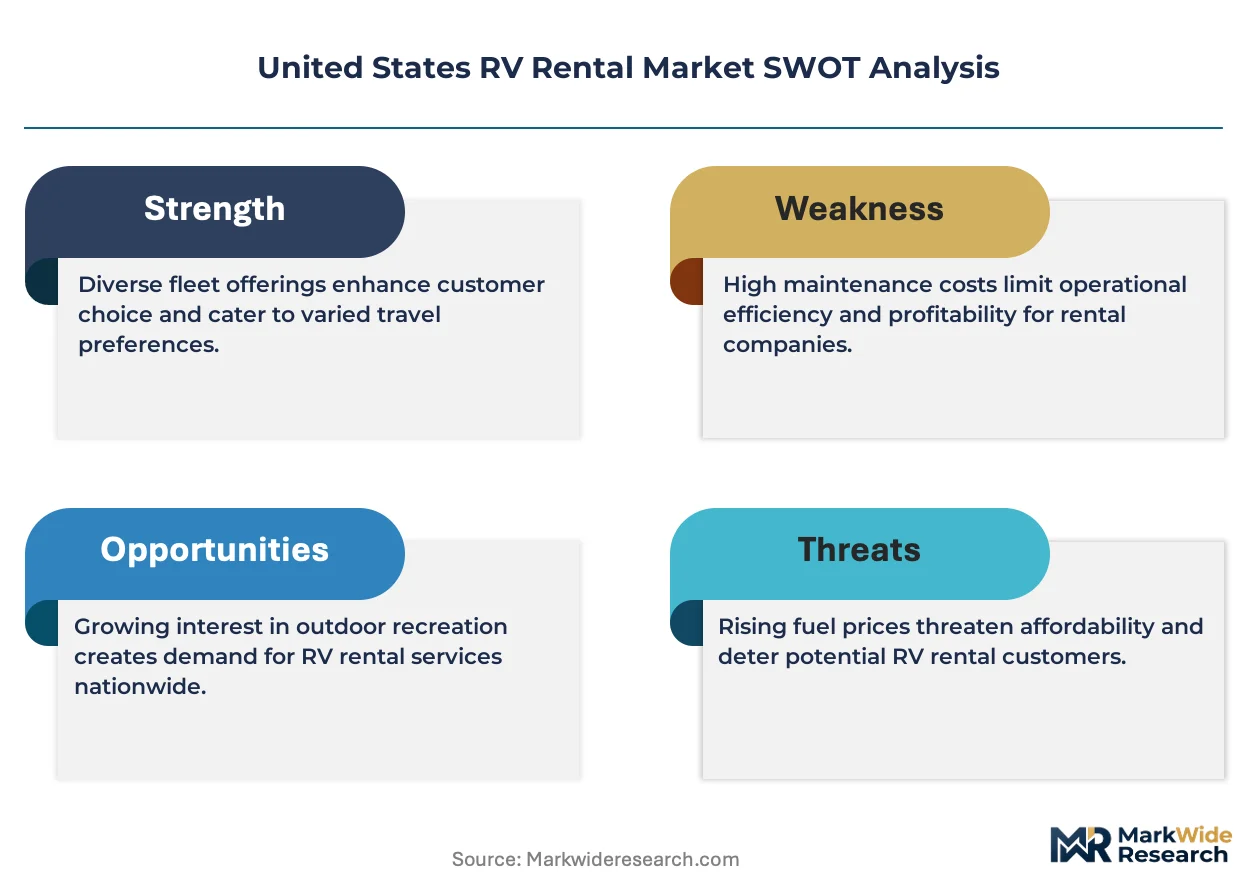
Peer-to-peer digital platforms are compressing traditional fleet ownership economics by unlocking privately held RV inventory for commercial rental use, redistributing supply authority from centralized operators to dispersed asset owners.
Growth Catalysts
- Remote work normalization:Knowledge workers extending leisure trips into multi-week "workations" sustain demand for mobile office configurations with reliable connectivity and dedicated workspace layouts.
- EPA Tier 3 emissions compliance:Cleaner diesel powertrains reduce operating cost volatility for fleet operators while expanding permissible travel zones in urban air quality districts.
- California campground infrastructure:State park system expansions and private KOA network density create pickup-return logistics that enable one-way rental economics.
Market Restraints
- Commercial vehicle insurance minimums:State-level liability thresholds in Texas and Florida impose capital barriers on peer-to-peer hosts entering the market.
- Diesel aftertreatment complexity:DEF system maintenance and SCR component failure rates elevate downtime costs for Class A motorhome operators.
- Seasonal demand asymmetry:Northeast and Upper Midwest markets experience 60-70% utilization variance between peak summer and winter months, compressing annual yield per unit.
Strategic Opportunities
- Texas Hill Country corridor:Underdeveloped between major metro RV rental penetration creates whitespace for hub-and-spoke distribution models anchored in Austin-San Antonio.
- Solar-integrated power systems:Rooftop photovoltaic with lithium battery banks enables boondocking rentals independent of campground hookup infrastructure.
- FMCSA commercial driver licensing thresholds:Anticipated regulatory clarity on Class A motorhome operator requirements will unlock professional driver services as a value-add tier.
Industry Challenges
- Certified RV technician scarcity:ASE-aligned training programs for house-system diagnostics and chassis integration remain concentrated in legacy manufacturing regions, creating service bottlenecks in high-growth rental markets.
- Platform-legacy PMS integration:Peer-to-peer booking engines require API connectivity with established fleet management systems, generating middleware development costs and data synchronization failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States RV Rental Market |
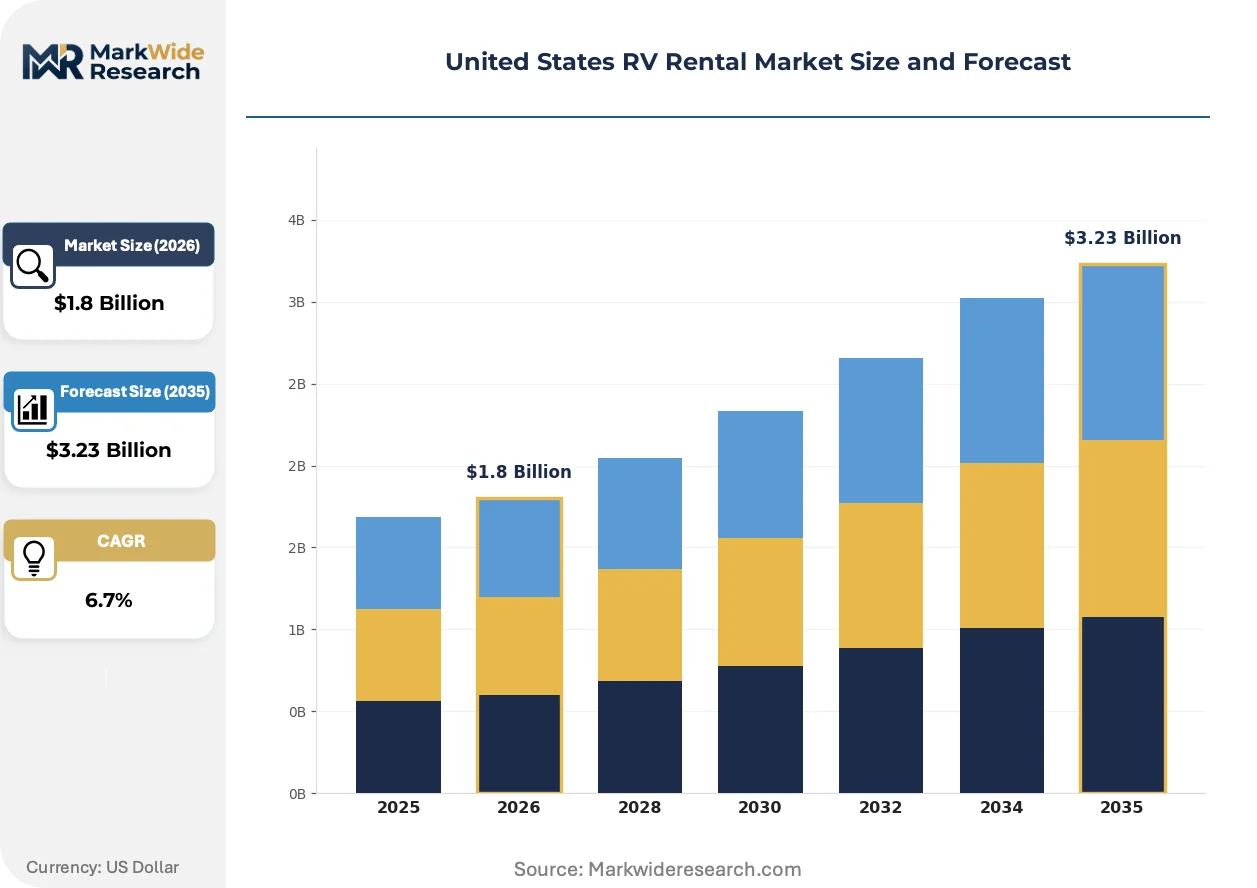
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Class A Motorhomes, Class B Camper Vans, Class C Motorhomes, Truck Campers, Pop-up Campers Customer Type: Solo Travelers, Families, Adventure Seekers, Group Travelers, Corporate Clients Rental Duration: Daily, Weekly, Monthly, Seasonal, Long-term Lease Booking Channel: Online Platforms, Travel Agencies, Direct Rental Offices, Mobile Apps, Peer-to-Peer Networks |
| Companies Covered | El Monte RV, Road Bear RV, Cruise America, Native Campervans, Allstar Coaches, Outdoorsy, RVezy, Moterra Campervans, RVshare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States RV Rental Market Strategic Shifts
Telematics-enabled usage-based pricing is rewiring how rental economics get calculated, shifting revenue models from flat daily rates toward variable structures that capture actual miles driven, generator hours consumed, and real-time demand elasticity.
Cellular-connected vehicle management systems are fragmenting the operational control layer between fleet operators and asset owners. Real-time GPS tracking, remote door lock management, and automated damage documentation now flow through platform dashboards rather than physical handoff protocols. Independent hosts adopting these systems report reduced dispute resolution overhead and faster turnover cycles between bookings.
NHTSA seatbelt anchorage standards for converted van platforms are compressing available chassis supply for Class B camper van conversions. Manufacturers must engineer structural reinforcements that add weight and reduce payload capacity, pushing rental economics toward heavier-duty platforms. California and Florida rental operators face the tightest procurement timelines as compliant chassis allocations concentrate with national fleet purchasers.
Subscription-based access models are displacing traditional nightly rental structures among younger demographic cohorts. Monthly membership fees covering a set number of usage days reduce transaction friction and improve inventory predictability for operators. This pattern concentrates in Pacific Northwest and Colorado markets where outdoor recreation participation rates intersect with tech-sector employment density.
United States RV Rental Market Segmentation
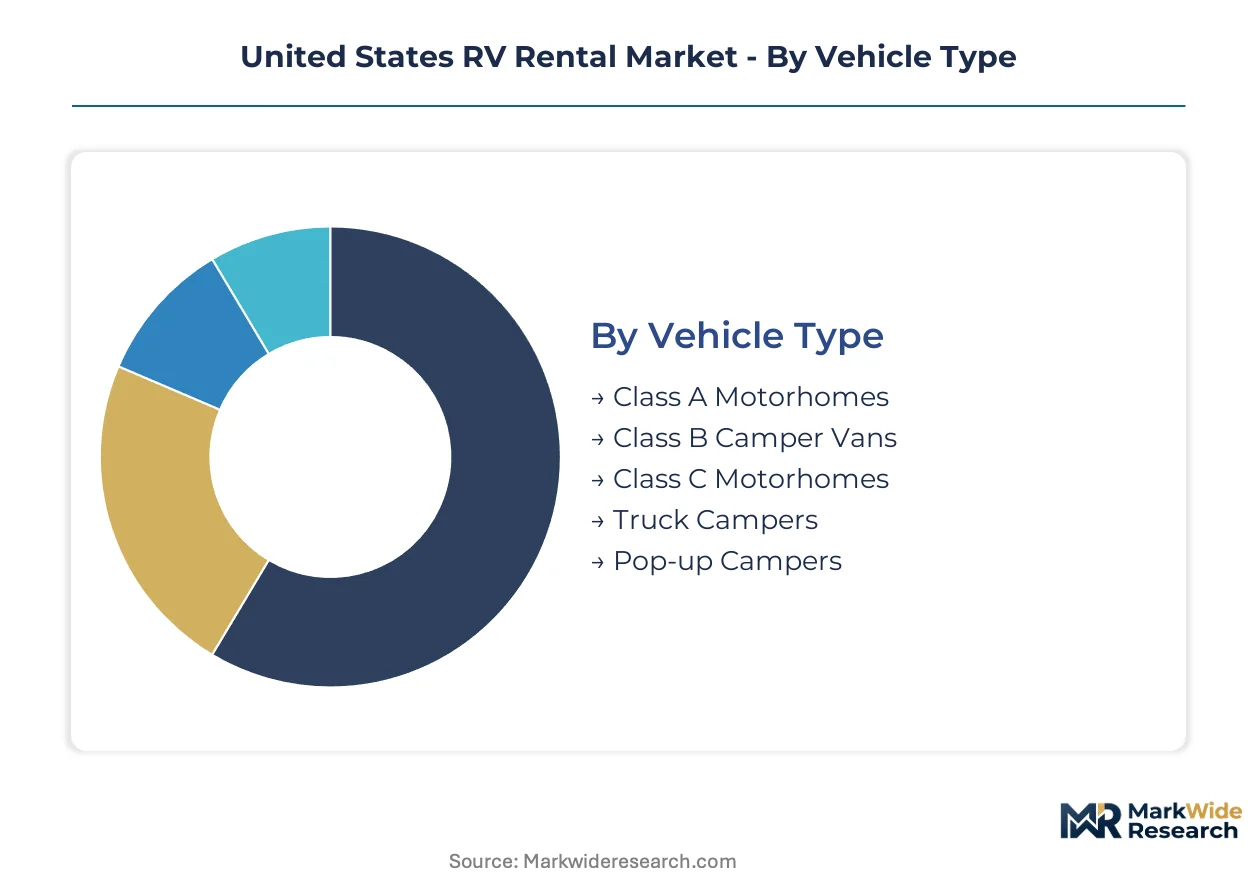
RV rental segmentation reveals distinct operational economics across vehicle configurations and customer profiles. Fleet operators calibrate inventory mix against utilization patterns, seasonal demand variance, and maintenance cost structures. Each segment carries unique insurance, depreciation, and turnover dynamics that shape profitability models.
Vehicle Type:
Class A motorhomes concentrate in cross-country domestic itineraries, while compact configurations serve regional and urban-adjacent markets.
- Class A Motorhomes:Diesel-powered chassis exceeding 35 feet with residential-grade amenities including full-size refrigerators and washer-dryer units. Demand clusters in California-to-Florida snowbird corridors where extended-stay campground infrastructure supports month-long rentals.
- Class B Camper Vans:Compact converted vans on Ford Transit or Mercedes Sprinter platforms prioritizing fuel efficiency and urban maneuverability. Solo travelers and remote workers in Pacific Northwest and Colorado markets drive fastest expansion as boondocking-capable electrical systems reduce campground dependency.
- Class C Motorhomes:Cab-over bunk configurations on Ford E-Series or Mercedes Sprinter cutaways balancing sleeping capacity with drivability. Families represent core demand in Texas Hill Country and Great Lakes regional circuits.
- Truck Campers:Slide-in units mounted on heavy-duty pickup beds enabling off-pavement access to dispersed camping zones. Adventure seekers in Utah and Arizona backcountry drive seasonal uptake.
- Pop-up Campers:Collapsible tent trailers towed by mid-size SUVs offering entry-level price points. First-time renters in Midwest state park systems sustain residual demand despite limited rental fleet penetration.
Class C motorhomes hold the largest share; momentum sits with Class B camper vans.
Customer Type:
Cost tier stratification separates budget-conscious families from premium corporate accounts seeking turnkey mobile event solutions.
- Solo Travelers:Individual renters prioritizing compact vehicle formats and flexible pickup locations. Digital nomad cohorts in Austin and Denver sustain demand for workspace-optimized Class B configurations with cellular boosters and dedicated desk areas.
- Families:Multi-generational groups requiring sleeping capacity above six berths and entertainment systems. Peak summer demand concentrates in Florida KOA networks and California coastal routes.
- Adventure Seekers:Outdoor recreation enthusiasts targeting trailhead proximity and off-grid capability. Mountain bike and climbing communities in Moab and Jackson Hole drive specialized 4x4 camper van demand.
- Group Travelers:Friend cohorts and club organizations splitting costs across multi-vehicle bookings. Bachelor party and festival circuits in Nevada and Tennessee generate concentrated seasonal spikes.
- Corporate Clients:Event marketing teams and mobile healthcare providers requiring branded wrap configurations and guaranteed availability. Film production support in Georgia and Louisiana sustains contract-based fleet relationships.
Families dominate transaction volume; corporate clients deliver highest per-rental yield.
Rental Duration:
Duration-based pricing tiers align with depreciation schedules and opportunity cost calculations for fleet operators managing finite inventory turns.
- Daily:Single-day excursions and local event support with premium per-dieme rates offsetting high turnover overhead. Urban weekenders in Seattle and Portland sustain this tier despite compressed margins.
- Weekly:Seven-day standard packages matching traditional vacation leave patterns. National park circuits including Yellowstone and Grand Canyon anchor consistent weekly booking flows.
- Monthly:Extended-stay configurations with discounted rates capturing snowbird migration and remote work relocation demand. Arizona and Florida operators report 40% of annual revenue from multi-month winter contracts.
- Seasonal:Three-to-six month arrangements common among retiree demographics following temperate weather patterns. Pacific Coast Highway and Atlantic seaboard routes exhibit pronounced seasonal concentration.
- Long-term Lease:Six-plus month corporate and film industry deployments with full maintenance inclusion. Production companies in New Mexico and Georgia leverage this structure for location shooting schedules.
Weekly rentals hold the largest share; monthly arrangements are expanding most quickly.
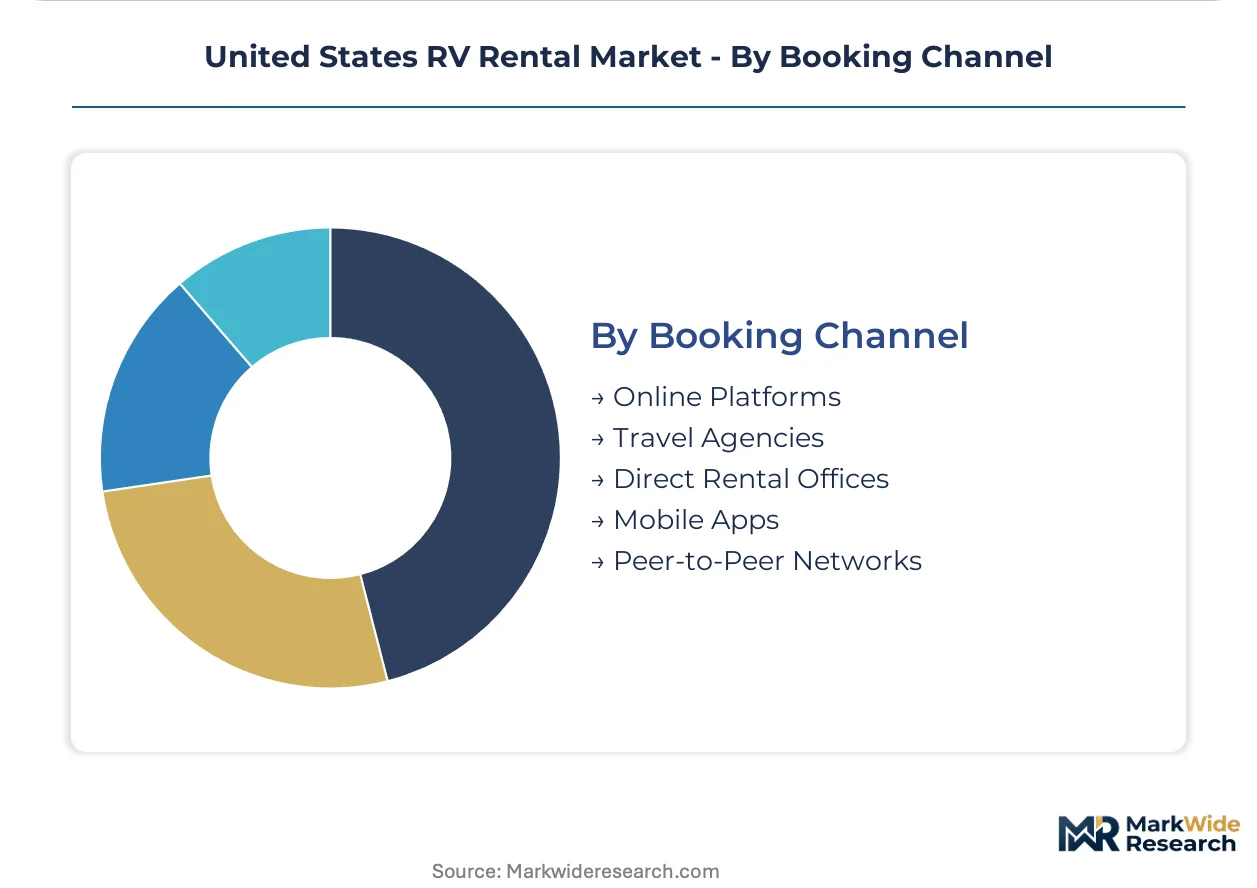
Booking Channel:
Digital intermediation is displacing legacy travel agency relationships while peer-to-peer platforms fragment supply authority.
- Online Platforms:Aggregator websites consolidating fleet inventory from multiple operators with instant confirmation and comparison tools. Outdoorsy and RVshare dominate this channel with nationwide coverage and host onboarding tools.
- Travel Agencies:Traditional intermediaries bundling RV rentals with campground reservations and activity packages. European inbound tour operators in Florida and California sustain residual agency volume.
- Direct Rental Offices:Branded fleet operators including Cruise America and El Monte RV with physical pickup locations and standardized vehicle configurations. Corporate accounts and first-time renters prefer this channel for in-person orientation.
- Mobile Apps:Native smartphone applications with geolocation-based inventory search and digital key handoff. Younger demographics in tech-heavy markets show highest app-native booking rates.
- Peer-to-Peer Networks:Platform-mediated transactions connecting private RV owners with short-term renters. Inventory fragmentation across this channel now exceeds branded fleet supply in Texas and Colorado markets.
Direct rental offices hold the largest share; peer-to-peer networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States RV rental market exhibits pronounced regional variation in supply-demand balance, with coastal states generating outbound rental flows and interior corridors serving as transit corridors rather than destination markets.
California
California anchors national fleet deployment through its concentration of branded rental headquarters and peer-to-peer host density. NHTSA seatbelt anchorage standards for converted van platforms compress available chassis supply, creating procurement bottlenecks for Los Angeles and San Francisco operators. The Pacific Coast Highway corridor sustains seasonal north-south migration patterns that concentrate Class A motorhome demand.
Florida
Florida absorbs inbound snowbird rentals from northeastern and midwestern origins, with KOA network density enabling extended-stay campground economics. State-level commercial vehicle insurance minimums impose capital barriers on peer-to-peer hosts entering the Orlando and Tampa markets. The Panhandle region experiences concentrated spring break demand from group travelers and festival circuits.
Texas
Texas Hill Country corridor exhibits underdeveloped rental penetration between Austin and San Antonio metros, creating whitespace for hub-and-spoke distribution models. EPA Tier 3 emissions compliance expands permissible travel zones in urban air quality districts including Dallas-Fort Worth and Houston. The state's independent energy grid reduces campground electrical dependency for solar-equipped rentals.
Pacific Northwest
Washington and Oregon sustain fastest Class B camper van expansion as remote worker density in Seattle and Portland drives workspace-optimized vehicle demand. Subscription-based access models displace nightly rental structures among tech-sector employment cohorts. The Cascade Range and Olympic Peninsula trailhead proximity supports boondocking-capable electrical system uptake.
Southwest
Arizona and Utah concentrate adventure-seeker demand for off-pavement access to dispersed camping zones in Moab and Sedona. Seasonal utilization variance between summer peak and winter trough reaches sixty to seventy percent in Flagstaff and Salt Lake City markets. Truck camper configurations on heavy-duty pickup beds capture specialized backcountry rental segments.
United States RV Rental Market Competitive Environment
Concentration sits with branded fleet operators maintaining standardized vehicle configurations across physical rental center networks. The market structure fragments between centralized fleet ownership and peer-to-peer platform mediation, creating tiered competitive dynamics. Strategic archetypes include legacy highway rental specialists, peer-to-peer network orchestrators, and adventure-focused van conversion boutiques. Dominant competitive moves encompass fleet standardization for operational efficiency and API integration with booking platform middleware.
Among legacy fleet operators, Cruise America and El Monte RV anchor the branded rental center segment with nationwide coverage and standardized Class C offerings. Outdoorsy occupies a position within the peer-to-peer network tier, unlocking privately owned RV inventory through digital platform mediation. These three entities represent divergent strategic approaches to supply authority—centralized ownership versus dispersed asset aggregation—while collectively defining competitive boundaries for new market entrants.
| Leading Market Players |
|---|
| El Monte RV |
| Road Bear RV |
| Cruise America |
| Native Campervans |
| Allstar Coaches |
| Outdoorsy |
| RVezy |
| Moterra Campervans |
| RVshare |
| Others |
Value Chain & Pricing Dynamics
Fleet-scale utilization rates above seventy percent during peak season create margin buffers that compress per-unit fixed costs and enable aggressive rate competition against fragmented peer-to-peer hosts. This scale concentration shapes both procurement leverage for chassis acquisition and pricing floors that deter marginal entrants from sustaining year-round operations.
Pricing Analysis
Leisure travelers anchor a three-tier pricing structure across premium, standard, and economy levels in the United States RV rental market. Price differentiation rests on vehicle classification tier and seasonal booking window, with Class A diesel motorhomes commanding premiums against compact camper van alternatives. Pricing pressure stems from peer-to-peer platform commission compression and insurance cost pass-through requirements in Texas and Florida. Budget-conscious families exhibit highest price sensitivity, while corporate event clients demonstrate lowest elasticity due to guaranteed availability requirements.
Supply Chain Analysis
Strategic chassis stockpiling dominates over just-in-time procurement as NHTSA seatbelt anchorage compliance creates allocation bottlenecks for converted van platforms. Manufacturing concentration centers on Ford Motor Company chassis production in Michigan, Mercedes-Benz Sprinter assembly in South Carolina, and specialized RV body integration facilities in Indiana and California. Raw material dependencies include aluminum sheet stock for exterior panels, lithium-ion cells for house battery systems, and DEF-grade urea for diesel aftertreatment. Single-source vulnerability sits with Ford E-Series cutaway allocations for Class C motorhome configurations. Distribution runs through branded rental center networks and peer-to-peer platform hubs rather than traditional dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States RV rental market represents an early-cycle expansion opportunity as remote work normalization sustains multi-week booking patterns that permanently elevate annual utilization baselines above pre-pandemic thresholds.
For Market Incumbents: Consolidate fleet standardization around telematics-enabled chassis platforms to reduce per-unit service overhead and accelerate turnover cycles between bookings. Acquire certified RV technician training capacity in Texas Hill Country and Pacific Northwest growth corridors to preempt service bottlenecks. Threats from peer-to-peer network fragmentation require defensive API integration investments that lock corporate accounts into guaranteed availability contracts.
For New Entrants and Emerging Players: Lead with solar-integrated power system configurations that enable boondocking-independent rentals in campground-scarce markets. Target the Austin-San Antonio corridor whitespace with hub-and-spoke logistics anchored in Texas Hill Country destination clusters. Pursue subscription-based access models rather than nightly rate competition to capture tech-sector remote worker cohorts in Denver and Seattle metropolitan areas.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among peer-to-peer platform operators with host onboarding tools and insurance bundling capabilities that generate take-rate stability across seasonal demand troughs. Long-term viability over a five-to-ten year horizon favors asset-light platform models over capital-intensive fleet ownership structures. Acquisition targets should demonstrate regional host density above critical mass thresholds in Colorado or Pacific Northwest markets. The signal to watch is FMCSA regulatory clarity on commercial driver licensing thresholds for Class A motorhome operations, which would unlock professional driver services as a value-add revenue tier.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time GPS tracking and remote door management reduce dispute resolution overhead for peer-to-peer hosts. |
| Solar Power System Deployment | Rooftop photovoltaic with lithium battery banks enables boondocking rentals independent of KOA hookup infrastructure. |
| Hub-and-Spoke Distribution Expansion | Austin-San Antonio corridor anchoring captures whitespace between major metro RV rental penetration zones. |
| Certified Technician Training Investment | ASE-aligned programs for house-system diagnostics alleviate service bottlenecks in high-growth rental markets. |
| Subscription Access Model Launch | Monthly membership fees reduce transaction friction and improve inventory predictability for operators in tech-heavy markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews combined with secondary validation across industry sources. Stakeholder roles included fleet operations directors at branded rental centers, peer-to-peer platform host onboarding managers, campground infrastructure planners at KOA network headquarters, insurance underwriters specializing in commercial vehicle liability, and NHTSA regulatory compliance officers. Secondary data sources encompassed EPA Tier 3 emissions compliance filings, state-level commercial vehicle registration databases, SEC 10-K disclosures from publicly traded chassis manufacturers, and campground utilization statistics from state park systems. Bottom-up fleet inventory counts were triangulated against top-down consumer spending estimates from travel industry surveys.
Across the analysis window, volume and value outputs reflect modeled projections calibrated against historical utilization patterns and seasonal demand variance coefficients. Segmentation dimensions include vehicle classification tier, rental duration category, booking channel type, and customer archetype stratification. CAGRs were derived from regression analysis against macroeconomic indicators including leisure travel expenditure indices and remote work adoption rates. Industry-specific forecast inputs incorporated chassis procurement lead times from Ford and Mercedes-Benz allocation schedules, plus campground infrastructure expansion timelines from state park capital improvement programs.
The analysis sits within stated boundaries; outcomes outside sustained remote work normalization or stable EPA emissions compliance requirements would require recalibration. Forecasts reflect documented assumptions regarding peer-to-peer platform host acquisition rates and branded fleet depreciation schedules. Specific risk factors that could revise projections include NHTSA seatbelt anchorage standard enforcement changes, state-level insurance minimum threshold adjustments, and FMCSA commercial driver licensing threshold determinations. Revision becomes warranted when seasonal utilization variance coefficients exceed historical ranges or chassis allocation disruptions persist beyond normalized procurement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Global Houseboats Market