
 Luxury Van Market | 2026-2036
Luxury Van Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Van Market Analysis
Aluminum-intensive unibody construction is decoupling luxury van curb weights from traditional steel architectures, improving fuel efficiency without sacrificing interior volume. Mercedes-Benz leverages its proprietary modular platform strategy across multiple wheelbase configurations. BMW sustains engineering investment in plug-in hybrid powertrains for its premium van concepts. Ford dominates North American commercial upfit channels with its Super Duty-based conversion architecture.
A luxury van denotes a high-specification vehicle exceeding five meters in length, typically featuring multi-zone climate control, acoustic laminated glass, and ride-height-adjustable air suspension for occupant comfort during extended journeys. Executive vans and conversion vans command the highest margin pools due to bespoke interior fitments and extended production cycles. Electric technology within the propulsion category is attracting capital allocation faster than hybrid alternatives, though all-wheel drive retains primacy in mountainous and cold-climate applications. Corporate customers represent the most stable demand segment, while luxury rentals exhibit the greatest cyclical volatility.
EPA tailpipe standards and Euro 7 emission frameworks are compelling powertrain diversification across manufacturer lineups, with California Air Resources Board zero-emission mandates creating de facto national compliance requirements for US-market entrants. NHTSA safety regulations governing roof crush resistance and electronic stability control shape structural engineering priorities for upfitters. Stakeholders must evaluate battery supply chain localization against tariff exposure when configuring regional assembly strategies.
Market Dynamics
Powertrain electrification investments are restructuring competitive capital allocation across the luxury van segment, with aluminum-intensive unibody construction simultaneously reducing curb weights while preserving interior volume for executive configurations.
Growth Catalysts
- Euro 7 Emission Standards:European regulatory pressure is accelerating manufacturer investment in zero-emission powertrain architectures for executive fleet applications.
- Corporate Fleet Procurement:Sustained order expansion from executive transport buyers is stabilizing demand visibility through extended production cycles.
- Aluminum Unibody Adoption:Advanced materials engineering is improving fuel efficiency metrics without compromising cabin dimensions for luxury upfitters.
Market Restraints
- Battery Supply Chain Concentration:Raw material processing bottlenecks in lithium and cobalt refining are constraining production scaling for electric conversion variants.
- Extended Production Cycles:Bespoke interior fitments for executive configurations create manufacturing throughput limitations relative to standard commercial vans.
- All-Wheel Drive Technical Constraints:Electric drivetrain packaging challenges in cold-climate mountainous applications limit powertrain optionality for certain geographic markets.
Strategic Opportunities
- China Premium Conversion Demand:Underpenetrated luxury rental channels in tier-one Chinese cities present expansion vectors for western upfitter partnerships.
- California ZEV Mandate Spillover:CARB zero-emission requirements are creating de facto national compliance pathways for US-market electric van entrants.
- Acoustic Laminated Glass Integration:Convergence of noise cancellation technology with climate-controlled cabin systems is opening premium tier differentiation.
Industry Challenges
- Upfitter Certification Timelines:NHTSA roof crush resistance and electronic stability control compliance extends time-to-market for new conversion architectures.
- Legacy Platform Integration Complexity:Super Duty-based conversion systems require substantial re-engineering to accommodate battery-electric powertrains without payload compromise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Van Market |
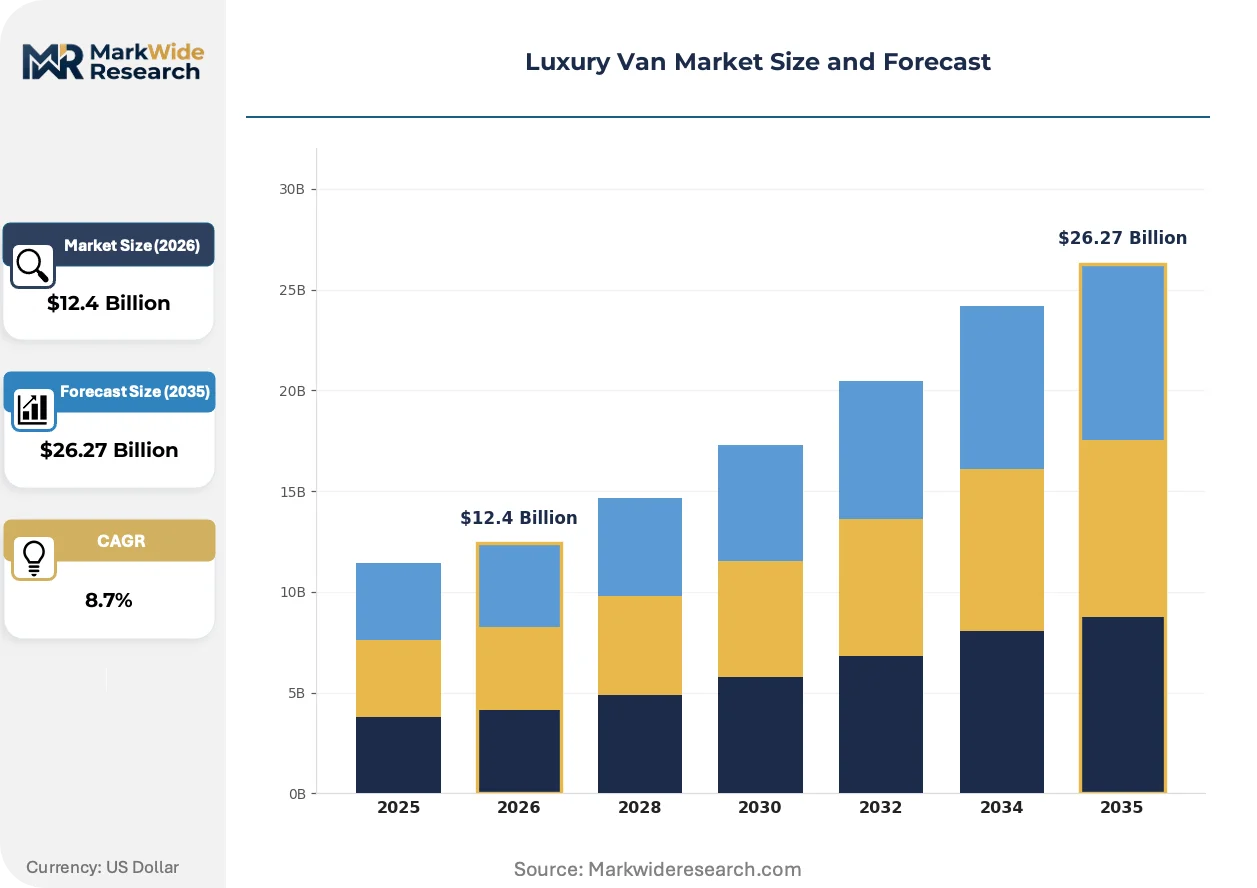
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vans, Cargo Vans, Conversion Vans, Executive Vans Feature: Gourmet Kitchen, Advanced Entertainment System, Premium Seating, Custom Interiors Technology: Hybrid, Electric, Autonomous, All-Wheel Drive End User: Corporate Customers, Travel Agencies, Luxury Rentals, Private Individuals |
| Companies Covered | GMC, BMW, Mercedes-Benz, Chevrolet, Audi, Toyota, Lexus, Mitsubishi, Ford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Van Market Emerging Trajectories
Active noise cancellation systems and modular platform architectures are redefining occupant experience benchmarks, while regulatory fragmentation across emission zones complicates powertrain portfolio planning for multinational manufacturers.
Acoustic laminated glass is expanding into multi-zone climate control cabins as a standard specification rather than optional upgrade. Corporate fleet buyers are mandating these configurations for executive roadshow applications. This technology is expanding into the premium rental channel, compressing differentiation windows for mid-tier conversion specialists.
EPA Tier 3 tailpipe standards are forcing powertrain diversification investments that exceed near-term demand signals for electric variants. Manufacturers are absorbing compliance costs across hybrid and battery-electric lineups simultaneously. The United States market is responding with extended-wheelbase hybrid configurations that preserve range flexibility for interstate executive transport.
Luxury rental channel procurement is consolidating around outcome-based vehicle availability contracts rather than discrete unit purchases. Fleet management intermediaries are displacing direct manufacturer relationships in high-rotation metropolitan markets. This pattern is most visible in Dubai and Singapore, where hospitality-sector buyers prioritize uptime guarantees over capital expenditure control.
Luxury Van Market Segmentation
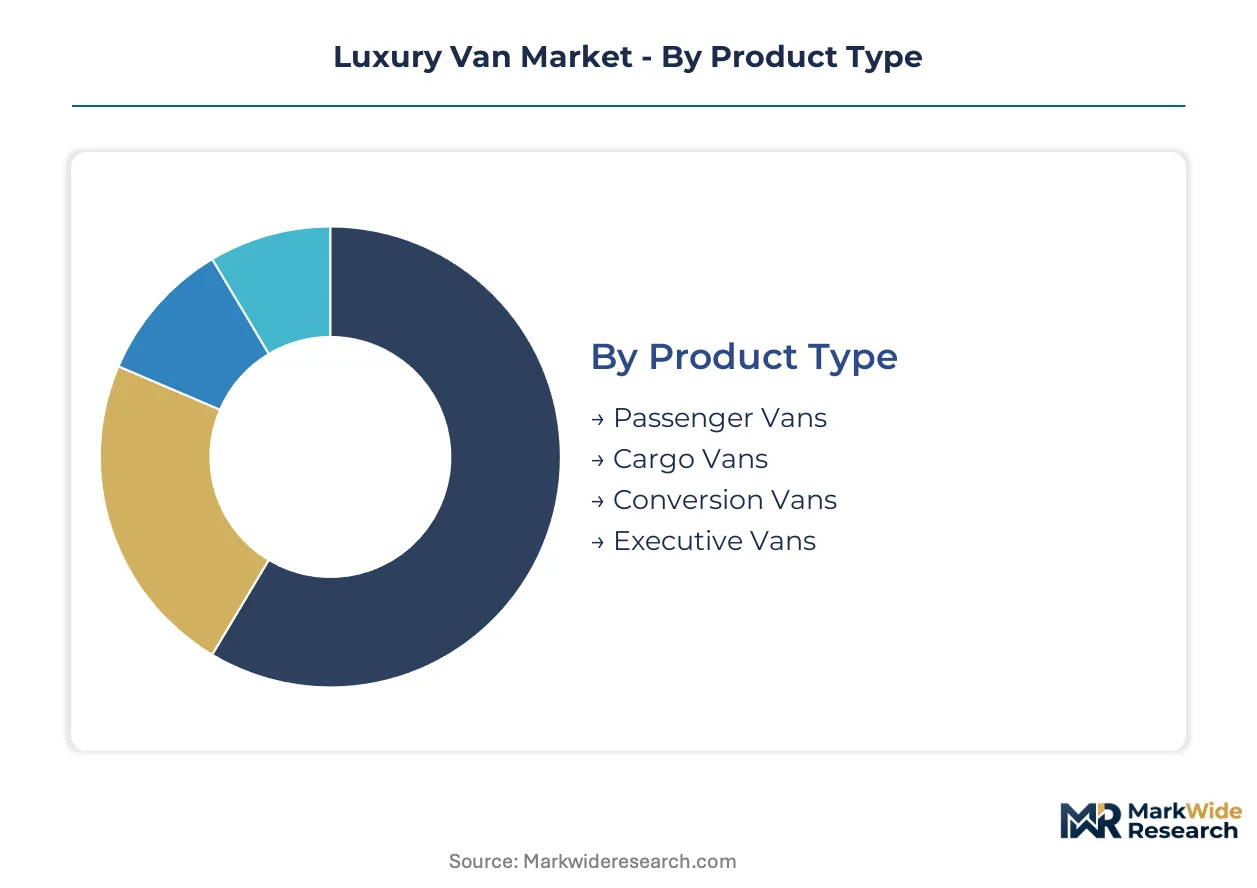
Segmentation in luxury vans reveals how bespoke engineering and regulatory pressure fragment demand across distinct buyer profiles. Each dimension—product architecture, onboard amenities, propulsion systems, and procurement channels—carries divergent margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Integration depth varies sharply: passenger and cargo configurations serve standalone fleet deployment, while executive and conversion variants embed within multi-vehicle hospitality programs requiring coordinated upfit timelines.
- Passenger Vans:Aluminum-intensive unibody architectures accommodate multi-zone climate control and acoustic laminated glass as standard. Fleet buyers in Germany and the United States concentrate orders here for executive roadshow circuits where occupant density meets comfort mandates.
- Executive Vans:Bespoke interior fitments extend production cycles substantially. Corporate procurement in China and tier-one Middle Eastern cities drives specification escalation toward private-jet-equivalent cabin environments.
- Cargo Vans:Payload-optimized configurations prioritize structural reinforcement over occupant amenities. Commercial upfitters in North America favor Super Duty-based architectures for last-mile premium logistics.
- Conversion Vans:Aftermarket specialists integrate ride-height-adjustable air suspension and custom seating. Extended manufacturing timelines limit throughput relative to factory-delivered alternatives.
Passenger vans lead volumes today; executive vans are gaining share fastest.
Feature:
Cost tier stratification separates fleet-standard specifications from owner-operator bespoke commissions, with rental intermediaries occupying a squeezed middle band.
- Premium Seating:Multi-point massage functions and ventilated leather configurations command material cost premiums exceeding standard automotive seating by substantial multiples. Corporate fleet specifications in California and Dubai mandate these for executive retention programs.
- Custom Interiors:Hand-finished wood veneers and ambient lighting systems require artisan labor pools concentrated in Northern Italy and Southern Germany. Lead times stretch commissioning calendars for private individual buyers.
- Gourmet Kitchen:Compact refrigeration and induction cooking modules occupy dedicated chassis zones. Demand concentrates in North American recreational conversion applications rather than executive transport.
- Advanced Entertainment System:4K display arrays and streaming connectivity integrate with acoustic laminated glass for cabin isolation. Rental channel procurement in Singapore specifies these for hospitality-sector contracts.
Premium seating leads volumes today; custom interiors are climbing the fastest.
Technology:
Application context dictates powertrain selection: interstate executive transport favors hybrid range flexibility, while urban hotel shuttle circuits accommodate full-electric duty cycles.
- Electric:Battery-electric architectures face packaging constraints for all-wheel drive variants in mountainous cold-climate applications. CARB zero-emission mandates in California create compliance spillover into national fleet procurement.
- Hybrid:Plug-in configurations preserve range autonomy for extended-wheelbase executive transport across the United States interstate network. BMW sustains dedicated engineering investment for this architecture.
- All-Wheel Drive:Mechanical complexity increases curb weight and reduces efficiency metrics. Demand concentrates in Alpine European markets and Rocky Mountain corridors where traction assurance overrides efficiency priorities.
- Autonomous:SAE Level 2+ driver assistance integrates with highway pilot functions for chauffeur fatigue reduction. Regulatory fragmentation across national type-approval regimes delays deployment timelines.
Hybrid leads volumes today; electric is expanding most quickly.
End User:
Customer type determines contract structure: corporate buyers negotiate multi-year fleet agreements, while rental channels shift toward outcome-based availability contracts.
- Corporate Customers:Extended production cycles align with executive transport procurement calendars. Order visibility stabilizes manufacturer throughput planning across German and US fleet buyers.
- Luxury Rentals:Fleet management intermediaries displace direct manufacturer relationships in high-rotation metropolitan markets. Dubai and Singapore hospitality sectors prioritize uptime guarantees over capital expenditure control.
- Travel Agencies:Group transport specifications balance per-passenger cost with brand differentiation requirements. Seasonal demand volatility compresses margin realization.
- Private Individuals:Bespoke commissioning tolerates extended delivery timelines for unique interior configurations. Wealth concentration in Chinese tier-one cities sustains order flow for Western upfitter partnerships.
Corporate customers lead volumes today; luxury rentals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global luxury van engineering concentration, with German OEMs commanding conversion architecture standards across executive fleet procurement calendars in multiple continents.
United States
Corporate fleet buyers in California and Texas concentrate orders for extended-wheelbase executive transport configurations. EPA Tier 3 tailpipe standards and CARB zero-emission mandates create de facto national compliance pathways for electric van entrants. Detroit-based upfitters leverage Super Duty conversion architectures for premium commercial channels.
Germany
Mercedes-Benz sustains modular platform engineering across multiple wheelbase variants from Stuttgart and Sindelfingen facilities. Euro 7 emission standards accelerate powertrain electrification investments for executive fleet applications. Bavarian automotive clusters supply acoustic laminated glass and air suspension systems to conversion specialists.
China
Wealth concentration in Shanghai and Beijing sustains demand for Western upfitter partnerships in tier-one cities. MIIT new energy vehicle mandates favor battery-electric architectures for urban hotel shuttle circuits. Pearl River Delta manufacturing bases produce premium seating and custom interior components for domestic conversion channels.
United Arab Emirates
Dubai hospitality-sector buyers prioritize uptime guarantees through outcome-based vehicle availability contracts over capital expenditure control. MOHAP vehicle import regulations shape specification compliance for luxury rental fleet procurement. Abu Dhabi sovereign wealth vehicle investments channel capital toward premium mobility service platforms.
Japan
METI carbon neutrality roadmaps redirect manufacturer R&D allocation toward hybrid powertrain preservation for interstate executive transport range flexibility. Osaka-based suppliers concentrate artisan labor pools for hand-finished wood veneer interior components. Tokyo corporate fleet procurement stabilizes order visibility for aluminum-intensive unibody architectures.
Luxury Van Market Vendor Landscape
Platform diversification dominates the current landscape across luxury van manufacturing, with consolidated OEM supply contrasting fragmented conversion specialist tiers. Three strategic archetypes occupy distinct positions: integrated automotive groups controlling proprietary architectures, regional upfitters executing bespoke interior commissions, and fleet management intermediaries displacing direct manufacturer relationships. Capacity expansion in battery-electric lineups and strategic partnerships with acoustic component suppliers constitute the dominant competitive moves reshaping capital allocation.
Among German-based integrated automotive groups, Mercedes-Benz and BMW exemplify platform-control archetypes, with the former leveraging modular architectures across wheelbase variants and the latter sustaining dedicated plug-in hybrid engineering investment. Ford anchors North American commercial upfit channels through scale-driven conversion architecture licensing. These three companies represent divergent strategic postures—proprietary platform control, powertrain specialization, and commercial channel dominance—without implying specific market share positions or operational metrics.
| Leading Market Players |
|---|
| GMC |
| BMW |
| Mercedes-Benz |
| Chevrolet |
| Audi |
| Toyota |
| Lexus |
| Mitsubishi |
| Ford |
| Others |
Supply Flow & Price Mechanics
Aluminum-intensive unibody construction is simultaneously compressing material cost premiums and redistributing supplier power toward specialized extrusion and bonding equipment manufacturers in Germany and Japan. This production-method transition concentrates procurement leverage among Tier 1 systems integrators capable of certifying crash-worthiness for executive configurations.
Pricing Analysis
Input-cost pass-through from lithium carbonate and cobalt sulfate volatility is intensifying pricing pressure on battery-electric conversion variants. Three-tier pricing structure across executive, premium rental, and fleet-standard levels separates bespoke interior commissioning from factory-delivered configurations. Price differentiation rests on certification grade for NHTSA roof crush resistance and acoustic laminated glass integration. Corporate fleet buyers in California exhibit lowest price sensitivity due to CARB compliance mandates, while luxury rental intermediaries in Dubai negotiate hardest on capital expenditure per unit.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai coordinate hub-and-spoke patterns for conversion component logistics. Geographic supply concentration centers on Germany for air suspension systems, China for premium seating manufacturing, and Japan for hand-finished wood veneer components. Raw material dependencies include aluminum sheet from Norwegian smelters, lithium hydroxide from Australian spodumene, and acoustic interlayer films from South Korean chemical producers. Single-source vulnerability in solid-state battery cell prototyping constrains electric architecture scaling. Distribution runs through OEM-certified upfitter networks rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
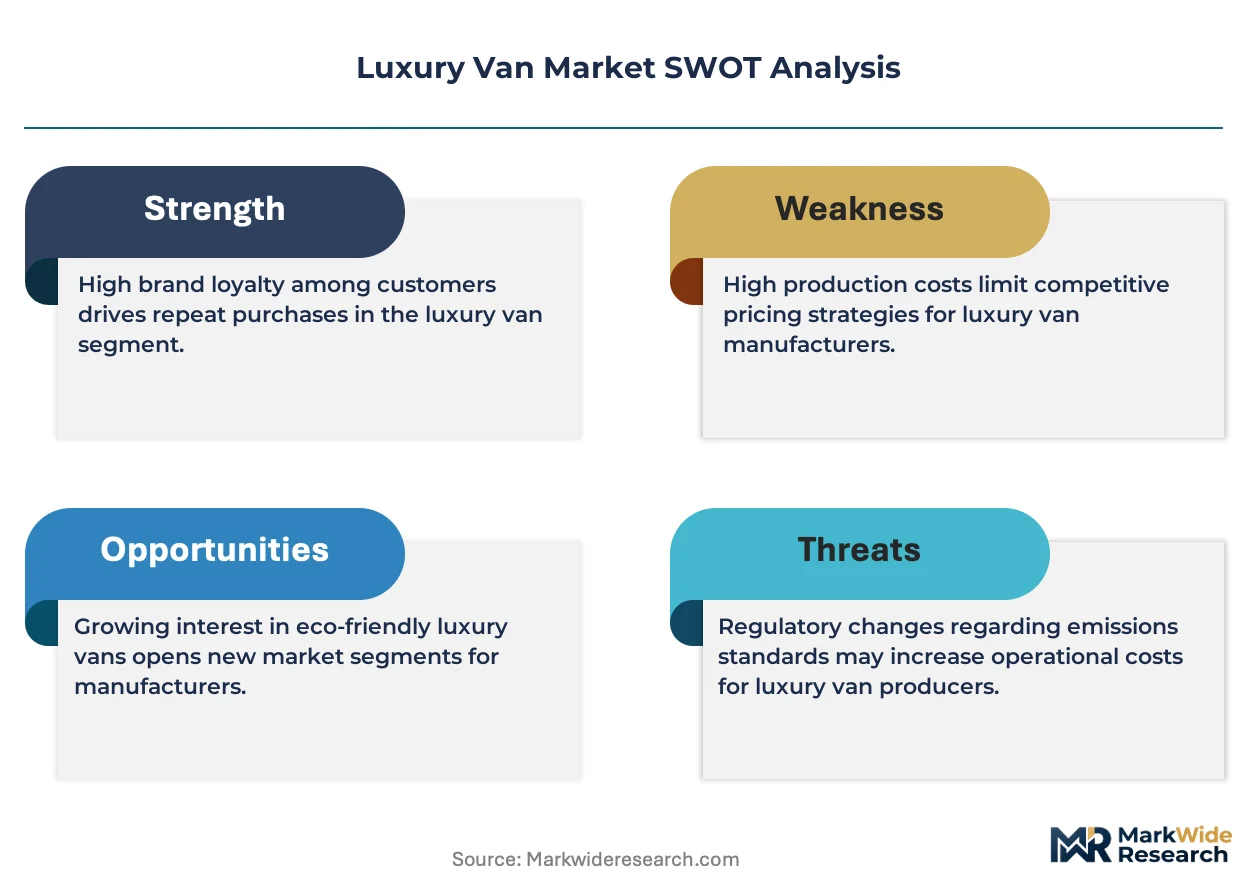
The luxury van market functions as a geographic-arbitrage play where Euro 7 compliance costs in Europe exceed California ZEV mandate investments, creating margin expansion potential for US-based conversion specialists serving interstate executive transport demand.
For Market Incumbents: Extend proprietary modular platform architectures across additional wheelbase variants to capture corporate fleet standardization mandates. Deepen backward integration into acoustic component supply through captive partnerships with Bavarian glass laminators. Battery supply agreement diversification mitigates lithium refining concentration risk in Chinese processing facilities. For New Entrants and Emerging Players: Enter via white-space targeting of tier-two Chinese cities where Western upfitter partnerships remain underdeveloped. Concentrate initial commissioning on executive van configurations for private individual buyers in Shanghai and Beijing. Direct-to-consumer digital configuration platforms bypass legacy dealership networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional conversion specialists with NHTSA certification infrastructure and artisan labor pools in Northern Italy. Long-term viability hinges on electric architecture transition completion within the next product cycle generation. Watch battery-electric order ratios from California corporate fleets as inflection indicator for powertrain portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Mercedes-Benz modular architectures reduce engineering redundancy across executive and cargo configurations. |
| Battery Supply Agreement | Long-term offtake contracts with Korean cell manufacturers secure capacity for electric conversion variants. |
| Software-Defined Vehicle Investment | Over-the-air updates for active noise cancellation systems extend feature lifecycles post-delivery. |
| Geographic Manufacturing Footprint | Pearl River Delta assembly localization circumvents tariff exposure on imported interior components. |
| Charging Infrastructure Partnership | Hotel shuttle circuit electrification in Dubai and Singapore depends on destination charging network density. |
Methodological Framework
Bottom-up corporate fleet procurement modeling reconciled against top-down aluminum extrusion capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 upfitter operations directors, luxury rental fleet managers, and California corporate procurement officers combined with secondary validation against EPA certification filings, NHTSA safety databases, CARB ZEV credit registries, and MIIT new energy vehicle production statistics. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of executive van production cycles and conversion lead times informed the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, onboard amenity tier, propulsion system, and end-user procurement channel. CAGRs derive from regression against fleet replacement calendars and regulatory compliance phase-in schedules. Forecast inputs incorporate Euro 7 implementation timing and CARB mandate spillover elasticity into national fleet procurement.
Inputs from OEM production disclosures and upfitter certification timelines were available through the study window; gaps in private individual buyer commissioning data introduce uncertainty bands around bespoke interior demand projections. Forecasts reflect documented assumptions regarding battery cost decline trajectories and aluminum alloy supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
US Recreational Boating Market