
 North America ATV and UTV Market | 2026-2036
North America ATV and UTV Market Size, Share, and Industry Trends Forecast 2026-2036
North America ATV and UTV Market Analytics
EPA emission standards for off-road spark-ignition engines is restructuring the cost-of-entry calculus for manufacturers serving the United States. Polaris Inc. leverages its domestic manufacturing footprint to navigate certification timelines faster than import-dependent rivals. BRP Inc. sustains competitive intensity through specialized Rotax engine architectures that meet evolving thresholds. American Honda Motor Co. Inc. anchors its position with proven ATV reliability that reduces warranty exposure under stricter compliance regimes.
All-terrain vehicles and utility task vehicles are motorized off-road machines built on tubular steel frames with independent suspension travel typically exceeding 25 centimeters, designed to traverse unpaved surfaces at speeds up to 80 km/h for recreation, agriculture, and industrial transport. Engine capacity stratification shows 500cc and 800cc segments carrying the deepest margin pools as buyers trade up from entry displacement. Side-by-side configurations within the vehicle type dimension are capturing disproportionate growth as agricultural and commercial users prioritize cargo capacity and rollover protection over traditional quad bike formats.
The United States Environmental Protection Agency enforces Tier 4 emission mandates that compel fuel injection and catalytic converter adoption, while Transport Canada coordinates parallel compliance through its off-road vehicle safety regulations. NHTSA rollover stability standards and state-level trail access permitting in Colorado, Utah, and Arizona further constrain product design and channel availability. Stakeholders must monitor how provincial regulators in Ontario and Quebec harmonize with federal Canadian rules to avoid fragmented certification burdens across the border.
Market Dynamics
EPA Tier 4 emission mandates and parallel Transport Canada regulations are forcing simultaneous engine architecture redesigns across the North American supplier base, compressing development cycles while elevating compliance costs for manufacturers without captive fuel-injection expertise.
Growth Catalysts
- Recreational Tourism Clustering:Rocky Mountain corridor operators in Colorado, Utah, and Arizona are expanding guided off-road experience fleets, creating concentrated demand pull for side-by-side configurations with rollover protection structures.
- Texas Dual-Use Convergence:Ranch-scale agriculture and Permian Basin oil-field utility applications overlap in the state, generating sustained replacement cycles for high-displacement utility task vehicles with cargo-rated beds.
- CARB Harmonization Spillover:California Air Resources Board tailpipe rules are being adopted by neighboring states, expanding the addressable market for catalytic converter-equipped powertrains beyond single-state compliance.
Market Restraints
- Emission Hardware Cost Inflation:Fuel injection systems, oxygen sensors, and precious-metal catalytic substrates are elevating bill-of-materials pressure on sub-500cc entry segments where price elasticity is highest.
- Steel Frame Supply Concentration:Tubular chassis fabrication capacity concentrates in Midwestern metalworking corridors, creating geographic vulnerability to regional labor disruptions or freight cost spikes.
- Trail Access Permitting Friction:State-level land management agencies in Arizona and Utah are tightening seasonal access windows and group size limits, constraining recreational utilization rates and replacement demand velocity.
Strategic Opportunities
- Mexico Manufacturing Footprint:Assembly relocation to Baja California and Chihuahua offers tariff-advantaged access to the United States market while sidestepping domestic labor cost escalation.
- Electric Powertrain White Space:Battery-electric architectures remain underdeveloped above 50 horsepower, creating first-mover potential for commercial fleet operators with depot charging infrastructure.
- Agricultural Autonomy Integration:GPS-guided implement control and precision spraying systems are converging with UTV platforms, opening premium pricing for integrated farm management solutions.
Industry Challenges
- Powertrain Calibration Talent Scarcity:EFI mapping and emission control strategy expertise resides with a narrow cohort of engineers, elongating recruitment timelines for Tier 4 compliance programs.
- Dual Certification Burden:Manufacturers must synchronize EPA and Transport Canada homologation timelines, creating launch delays when regulatory interpretation diverges on rollover protection testing protocols.
- Dealer Network Reconfiguration:Traditional powersports retailers lack technical capacity for complex emission system diagnostics, forcing OEMs to subsidize technician training or bypass channels entirely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America ATV and UTV Market |
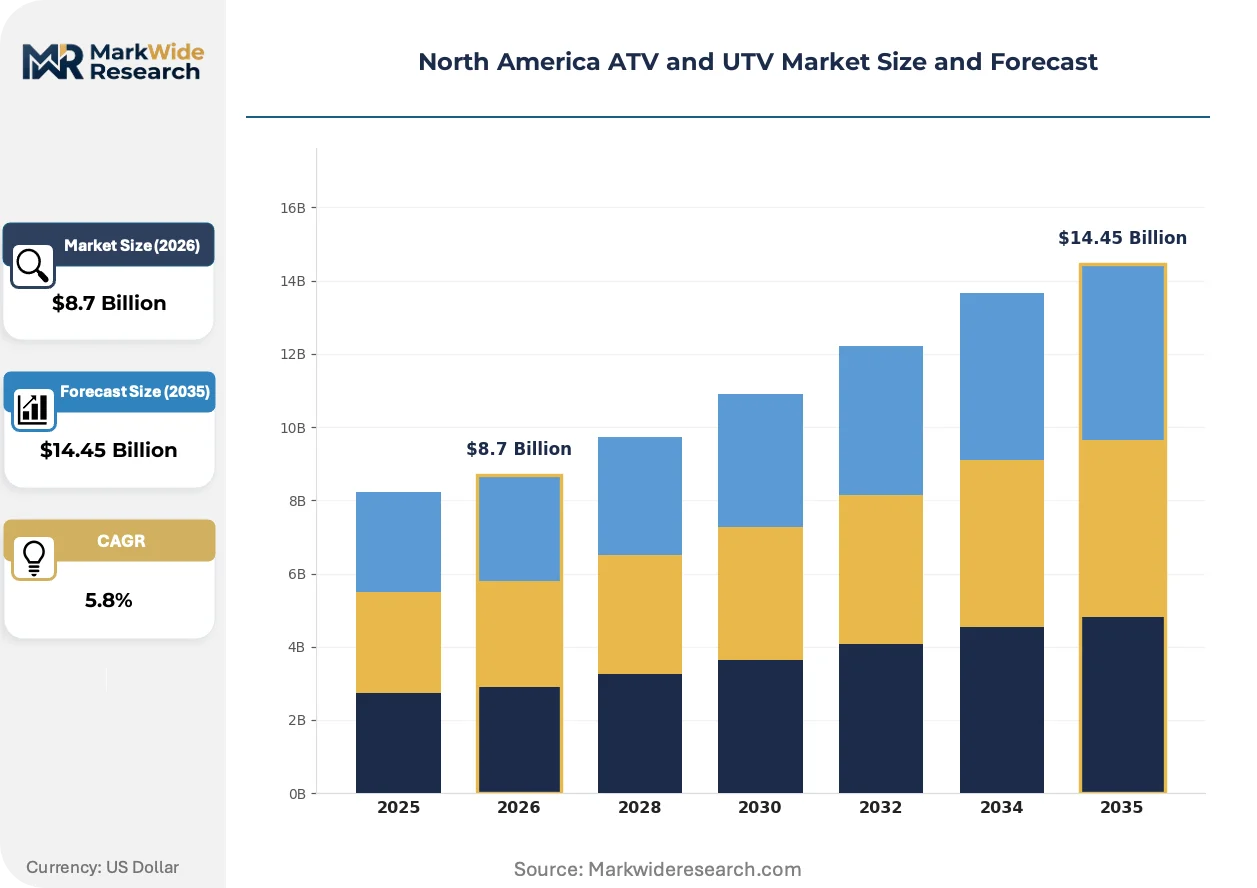
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: All-Terrain Vehicle, Utility Task Vehicle, Side-by-Side, Quad Bike Engine Capacity: 250cc, 500cc, 800cc, 1000cc End User: Recreational Users, Industrial Users, Agricultural Users, Government Agencies Distribution Channel: Online Retail, Dealerships, Direct Sales, Rental Services |
| Companies Covered | Polaris Inc., BRP Inc., American Honda Motor Co. Inc., Yamaha Motor Co. Ltd, Kawasaki Heavy Industries Ltd., Textron Inc., Arctic Cat Inc., Deere & Company, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America ATV and UTV Market Evolving Landscape
Powertrain electrification and precision agriculture integration are restructuring competitive differentiation, while regulatory stringency accelerates consolidation among engineering-constrained suppliers.
Electronic fuel injection systems with closed-loop oxygen feedback are replacing carbureted architectures across all displacement classes. Agricultural cooperatives and commercial fleet operators are adopting these powertrains fastest, prioritizing cold-start reliability and altitude compensation. EFI deployment is converging with telematics integration, enabling remote diagnostics that compress warranty resolution cycles and shift service revenue from dealers to manufacturer-controlled platforms.
Transport Canada's off-road vehicle safety regulations are tightening rollover protection and occupant containment standards ahead of NHTSA alignment. The industrial consequence is accelerated structural redesign for side-by-side architectures, with reinforced cage tubing and integrated seatbelt anchorages becoming mandatory. Quebec and Ontario provincial regulators are harmonizing with federal Canadian rules faster than historical patterns, reducing fragmented certification burdens for suppliers serving the cross-border market.
Ranch operators and oil-field service companies are consolidating fleet procurement under centralized procurement functions with total-cost-of-ownership analytics. Traditional dealer networks are being displaced by direct OEM fleet account teams offering multi-year maintenance contracts and guaranteed uptime clauses. This concentration is most visible in Texas and Alberta, where scale buyers negotiate volume pricing that erodes margin pools for smaller regional distributors.
North America ATV and UTV Market Segmentation
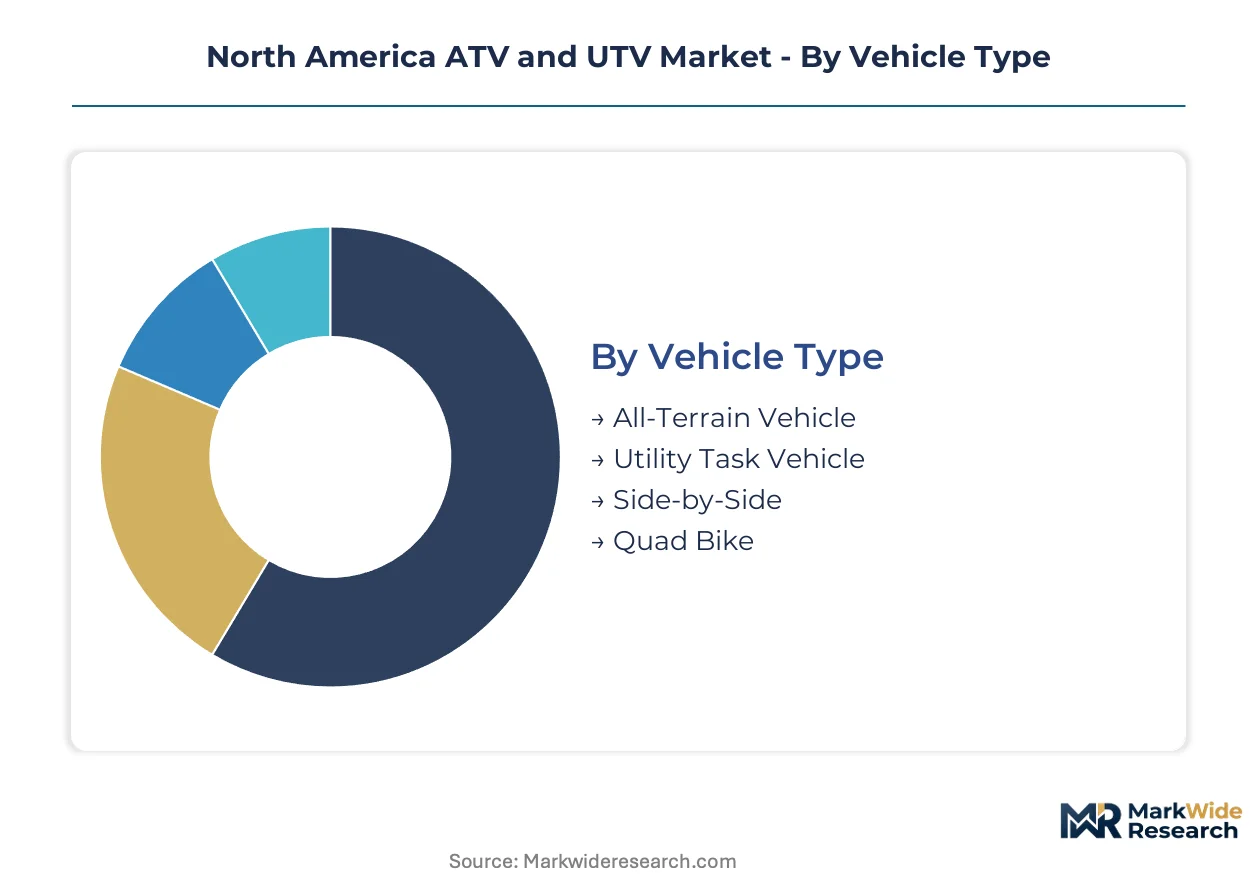
Segmentation in the North America ATV and UTV Market reveals how EPA Tier 4 compliance costs and end-use specialization are fragmenting manufacturing footprints. Supply-side concentration in specific displacement classes and vehicle architectures creates divergent margin structures across the value chain.
Vehicle Type:
Assembly capacity concentrates most heavily around rollover-protected architectures as commercial fleet procurement accelerates.
- All-Terrain Vehicle:Traditional straddle-seated configurations built on tubular steel frames with swing-arm rear suspension. Ranch operators in Texas and Alberta maintain replacement cycles for herd management and fence-line inspection, though recreational trail access restrictions in Arizona and Utah constrain velocity in leisure channels.
- Utility Task Vehicle:Cargo-bed equipped side-by-sides with dual-seat or bench configurations, engineered for payload ratings exceeding 450 kilograms. Permian Basin oil-field service companies and agricultural cooperatives in the Texas Panhandle are consolidating procurement under multi-year fleet contracts, displacing traditional dealer relationships.
- Side-by-Side:Enclosed-cab variants with integrated rollover protection structures meeting Transport Canada safety regulations.
- Quad Bike:Lightweight recreational formats with minimal cargo capacity, facing displacement from side-by-side alternatives in commercial applications.
Today's leader: Utility Task Vehicle. Tomorrow's challenger: Side-by-Side.
Engine Capacity:
Cost tier stratification shows mid-displacement segments absorbing the steepest bill-of-materials pressure from fuel injection hardware mandates.
- 500cc:Single-cylinder and parallel-twin architectures with electronic fuel injection replacing carbureted predecessors. Cold-start reliability at altitude drives adoption among Rocky Mountain recreational tourism operators in Colorado and guided outfitters in Utah.
- 800cc:V-twin and inline-twin configurations delivering torque curves optimized for towing and cargo-hauling. Ranch-scale agriculture in Texas and industrial fleet operators in Alberta negotiate volume pricing that compresses margin pools for regional distributors.
- 250cc:Entry-level single-cylinder powertrains facing the highest price elasticity from emission hardware cost inflation.
- 1000cc:Flagship displacement class with premium pricing for performance-oriented recreational buyers.
Volume concentrates in 500cc and 800cc brackets, with 1000cc climbing fastest as buyers trade up from entry displacement.
End User:
Customer type diversification is forcing OEMs to reconfigure service networks around divergent uptime requirements and procurement sophistication.
- Recreational Users:Individual and family purchasers prioritizing trail access and ride experience over payload specification. Seasonal permitting restrictions in Arizona and Utah are tightening group size limits and access windows, constraining replacement demand velocity in leisure channels.
- Agricultural Users:Ranch operators and farm cooperatives integrating GPS-guided implement control and precision spraying systems with UTV platforms. Centralized procurement functions in Texas and Alberta negotiate total-cost-of-ownership contracts with guaranteed uptime clauses.
- Industrial Users:Oil-field service companies and mining contractors with depot charging infrastructure evaluating battery-electric alternatives above 50 horsepower.
- Government Agencies:Park services and land management departments with standardized fleet specifications and extended replacement cycles.
Maturity favors Agricultural Users. Expansion trajectory runs through Industrial Users.
Distribution Channel:
Margin pressure from emission system complexity is accelerating channel bypass as OEMs build direct technical service capabilities.
- Dealerships:Traditional powersports retailers with geographic concentration in Midwestern and Southwestern corridors. EFI mapping and catalytic converter diagnostics exceed typical technician training levels, forcing OEMs to subsidize certification programs or disintermediate entirely.
- Direct Sales:OEM fleet account teams serving centralized procurement functions with multi-year maintenance contracts. This channel is expanding most quickly in Texas and Alberta where scale buyers negotiate volume pricing.
- Online Retail:Digital configurators with limited technical support capacity for emission system troubleshooting.
- Rental Services:Rocky Mountain corridor operators in Colorado and Utah expanding guided experience fleets with rollover-protected side-by-side configurations.
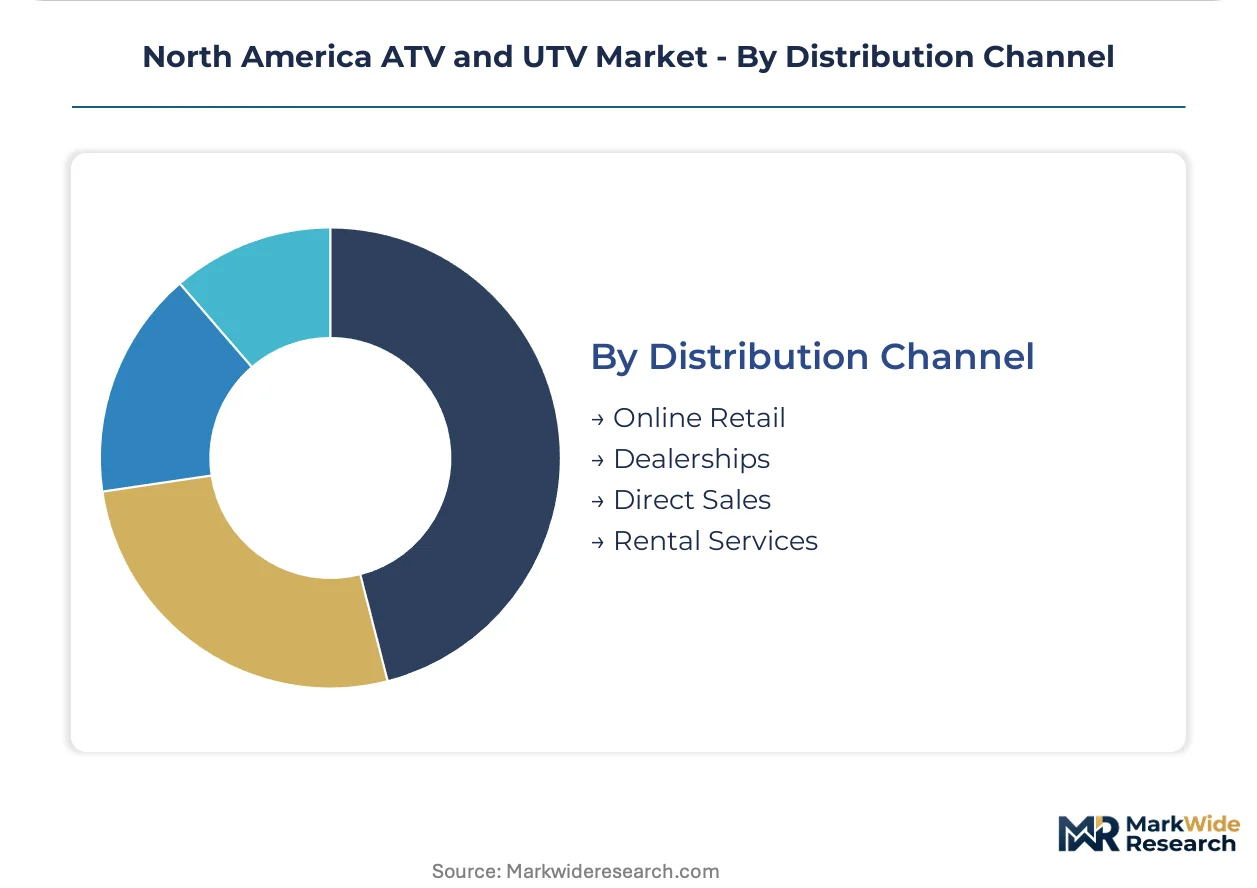
Dealerships retain volume leadership. Direct Sales represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in the Great Lakes industrial corridor anchor North American manufacturing capacity for off-road vehicle powertrains and chassis systems. EPA and Transport Canada regulatory harmonization is compressing certification timelines across the border, while assembly relocation to northern Mexico accelerates under tariff-advantaged trade frameworks.
United States
Texas ranch operators and Permian Basin oil-field service companies sustain replacement cycles for high-displacement utility task vehicles with cargo-rated beds. EPA Tier 4 emission mandates compel fuel injection and catalytic converter adoption across all engine classes. Austin and Dallas-Fort Worth host expanding fleet procurement offices for centralized agricultural and industrial buyers negotiating multi-year maintenance contracts.
Canada
Alberta agricultural cooperatives and Saskatchewan mining contractors drive demand for rollover-protected side-by-side configurations with integrated telematics. Transport Canada coordinates off-road vehicle safety regulations with provincial regulators in Ontario and Quebec to reduce fragmented certification burdens. Calgary and Edmonton concentrate fleet account management teams serving energy sector buyers with depot charging infrastructure for electric powertrain evaluation.
Mexico
Assembly relocation to Baja California and Chihuahua offers tariff-advantaged access to the United States market while sidestepping domestic labor cost escalation. Mexican federal environmental regulations align with EPA emission thresholds through bilateral trade agreement annexes. Ciudad Juárez and Tijuana metalworking corridors supply tubular chassis fabrication capacity for cross-border manufacturing networks.
Colorado
Rocky Mountain recreational tourism operators in Colorado and Utah are expanding guided off-road experience fleets, creating concentrated demand pull for side-by-side configurations. State-level trail access permitting tightens seasonal windows and group size limits, constraining replacement demand velocity in leisure channels. Denver and Colorado Springs host outfitter procurement hubs sourcing rollover-protected vehicles for guided adventure tourism.
North America ATV and UTV Market Competitive Landscape
The competitive structure tilts toward diversified powersports conglomerates with captive engine manufacturing and established fleet account relationships. Market concentration remains moderate with tiered differentiation across premium performance, utility-specialized, and agricultural-integrated segments. Two strategic archetypes dominate: domestic manufacturers leveraging regulatory proximity for faster certification cycles, and diversified industrial conglomerates integrating precision agriculture systems with utility vehicle platforms. Competitive moves center on Mexico manufacturing footprint expansion and direct fleet sales channel development bypassing traditional dealer networks.
Among North American-based powersports specialists, Polaris Inc. and BRP Inc. occupy positions representing the diversified conglomerate archetype with captive powertrain engineering capabilities. American Honda Motor Co. Inc. anchors the reliability-focused tier with proven ATV architectures that reduce warranty exposure under stricter compliance regimes. These three entities exemplify how regulatory proximity and manufacturing scale concentrate competitive positioning in the North American market.
| Leading Market Players |
|---|
| Polaris Inc. |
| BRP Inc. |
| American Honda Motor Co. Inc. |
| Yamaha Motor Co. Ltd |
| Kawasaki Heavy Industries Ltd. |
| Textron Inc. |
| Arctic Cat Inc. |
| Deere & Company |
| Kubota Corporation |
| Others |
Value Network & Pricing Analysis
Captive fuel-injection manufacturing in the Great Lakes industrial corridor anchors both supply security and pricing power for Tier 4-compliant powertrains. OEMs with in-house EFI calibration capabilities command premium positioning while import-dependent rivals absorb certification delays and margin compression.
Pricing Analysis
After-sales service bundling separates fleet contract pricing from transactional retail sales. Three-tier pricing structure across premium, standard, and economy levels tracks engine displacement and rollover protection certification. Cost compression in sub-500cc entry segments intensifies because precious-metal catalytic substrates inflate bill-of-materials pressure. Agricultural cooperatives in Texas exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while individual recreational buyers in Colorado and Utah face highest elasticity.
Supply Chain Analysis
Freight cost spikes from Midwestern metalworking corridors to Southwestern assembly plants elevate landed costs for tubular chassis components. Tubular steel frame fabrication concentrates in Michigan, Ohio, and Indiana, while final assembly draws from Baja California and Chihuahua maquiladora networks. Supply chain risk centers on single-source vulnerability for oxygen sensors and catalytic substrates. Distribution runs through direct OEM fleet account teams displacing traditional powersports dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Mexico manufacturing access offers tariff-advantaged positioning against domestic labor cost escalation and EPA compliance timelines.
For Market Incumbents: Anticipate electric powertrain disruption above 50 horsepower by securing battery supply agreements and depot charging infrastructure partnerships. Defend positioning through backward integration into tubular chassis fabrication and captive EFI mapping expertise. Prioritize certification investment for Transport Canada rollover protection alignment ahead of NHTSA convergence. For New Entrants and Emerging Players: EPA Tier 4 emission mandates in the United States open a window for specialized catalytic converter integration services and EFI calibration consulting. Target agricultural autonomy integration in Texas and Alberta where GPS-guided implement control converges with UTV platforms. Pursue direct fleet sales channel development bypassing dealer technical capacity constraints. For Investors and Strategic Acquirers: Roll-up economics work for regional powersports distributors with established service networks because emission system complexity forces OEM subsidy of technician training. Mid-term viability favors targets with cross-border certification capabilities and Mexico assembly relationships. Monitor electric powertrain adoption rates among Permian Basin oil-field operators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Manufacturing Footprint Expansion | Tariff-advantaged access to United States market sidesteps domestic labor cost escalation. |
| Direct Fleet Sales Channel Development | Bypasses dealer technical capacity gaps for EFI diagnostics and catalytic converter service. |
| Electric Powertrain Platform Investment | First-mover positioning in battery-electric architectures above 50 horsepower for industrial depots. |
| Agricultural Autonomy Integration | GPS-guided implement control opens premium pricing for integrated farm management solutions. |
| Transport Canada Certification Alignment | Harmonized rollover protection standards reduce fragmented homologation burdens across border. |
Research Methodology
Multiple input streams — OEM product planning executives, fleet procurement managers at Texas agricultural cooperatives, powersports dealer principals, and tubular chassis fabricators — were reconciled against regulatory filing databases and vehicle registration records. Secondary validation drew from EPA certification documents, Transport Canada safety regulation updates, SEC 10-K disclosures, and state-level trail access permitting records. Bottom-up unit shipment estimates triangulated with top-down value chain analysis across the projection horizon.
Data-stream reconciliation applied vehicle type, engine capacity, end-user category, and distribution channel segmentation dimensions. CAGRs derived from regression analysis of historical displacement trends and regulatory compliance cost trajectories. Forecast inputs incorporated EFI adoption curves, Mexico assembly relocation patterns, and electric powertrain evaluation timelines among industrial fleet operators.
Revisions become necessary when EPA-Transport Canada regulatory interpretation diverges, steel frame supply disruptions materialize, or electric powertrain performance thresholds shift. Forecasts reflect documented assumptions about emission hardware cost trajectories and dealer network reconfiguration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Recreational Boating Market