
 Towable Tubes Market | 2026-2036
Towable Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Towable Tubes Market Outlook
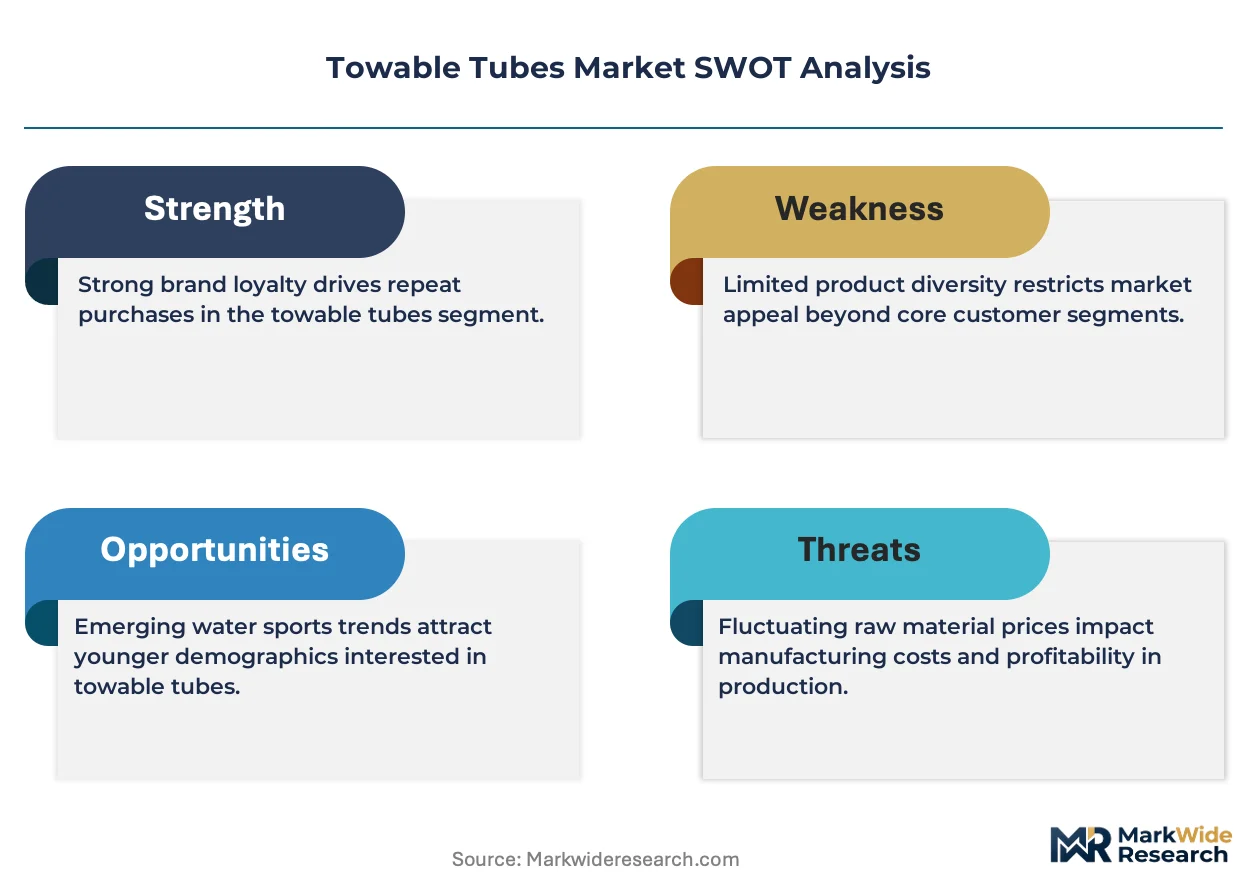
North American manufacturing capacity is reshaping supply availability for towable water sports equipment. O'Brien leverages domestic assembly lines to control lead times for seasonal replenishment. Jobe sustains European design heritage while competing aggressively in North American distribution channels. Airhead anchors its position through value-tier pricing that captures entry-level family buyers.
Towable tubes are inflatable watercraft constructed from heavy-gauge PVC or reinforced nylon bladders with neoprene knuckle guards and tow-point harnesses, designed to be pulled behind motorboats at speeds of 15–35 mph for recreational riding. Deck tubes dominate commercial rental fleets due to rider stability and faster turnover, while banana tubes command premium positioning among water sports enthusiasts seeking high-speed maneuverability. Nylon-skinned models capture margin pools in the replacement segment, whereas TPU formulations represent an emerging material trajectory focused on puncture resistance and extended UV durability.
The Consumer Product Safety Commission governs seam integrity and labeling standards for inflatable towables sold in the United States, while ISO 6185 provides international benchmarks for buoyancy chamber construction and pressure testing. Coast Guard auxiliary guidelines in high-traffic waterways increasingly influence local rental operator purchasing decisions regarding rider capacity and visible coloration requirements. Stakeholders must monitor how state-level watercraft liability frameworks evolve alongside material certification demands.
Market Dynamics
Seasonal replenishment cycles along Florida's inland waterway corridor are compressing lead-time tolerances, forcing manufacturers to reconfigure domestic assembly capacity around just-in-time inventory models.
Growth Catalysts
- Lake destination rental fleet expansion:Recreational operators across Minnesota's 10,000 Lakes region and Wisconsin's Door County are scaling multi-rider tube acquisitions to capture weekend tourism surges.
- Consumer Product Safety Commission seam integrity mandates:Enhanced labeling and construction standards are accelerating replacement demand as legacy inventory cycles out of compliance.
- TPU puncture resistance formulations:Advanced thermoplastic polyurethane blends are extending product lifespans in commercial rental applications, reducing total cost of ownership.
Market Restraints
- Heavy-gauge PVC input cost volatility:Petrochemical feedstock fluctuations are compressing margin pools for value-tier manufacturers dependent on commodity-grade materials.
- Supply concentration in Southeast Asian bladder fabrication:Limited qualified suppliers for reinforced nylon chamber construction create single-source vulnerability during peak seasonal windows.
- Coast Guard auxiliary coloration visibility requirements:Local waterway enforcement variations are fragmenting SKU rationalization efforts across state boundaries.
Strategic Opportunities
- Great Lakes secondary market penetration:Michigan and Ohio lake communities show underdeveloped rental infrastructure relative to Florida saturation levels.
- Direct-to-consumer channel innovation:Brand-owned e-commerce platforms are bypassing traditional marine specialty retail markups, capturing margin previously lost to distribution tiers.
- ISO 6185 buoyancy certification convergence:Harmonized international pressure-testing standards are reducing export friction for domestic manufacturers targeting Canadian and Australian recreational markets.
Industry Challenges
- Skilled neoprene knuckle guard fabrication labor scarcity:Specialized sewing and bonding technicians are concentrated in legacy textile regions, creating hiring bottlenecks for capacity expansion.
- Multi-jurisdictional liability framework navigation:State-level watercraft operator insurance mandates vary unpredictably, complicating fleet standardization for national rental chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Towable Tubes Market |
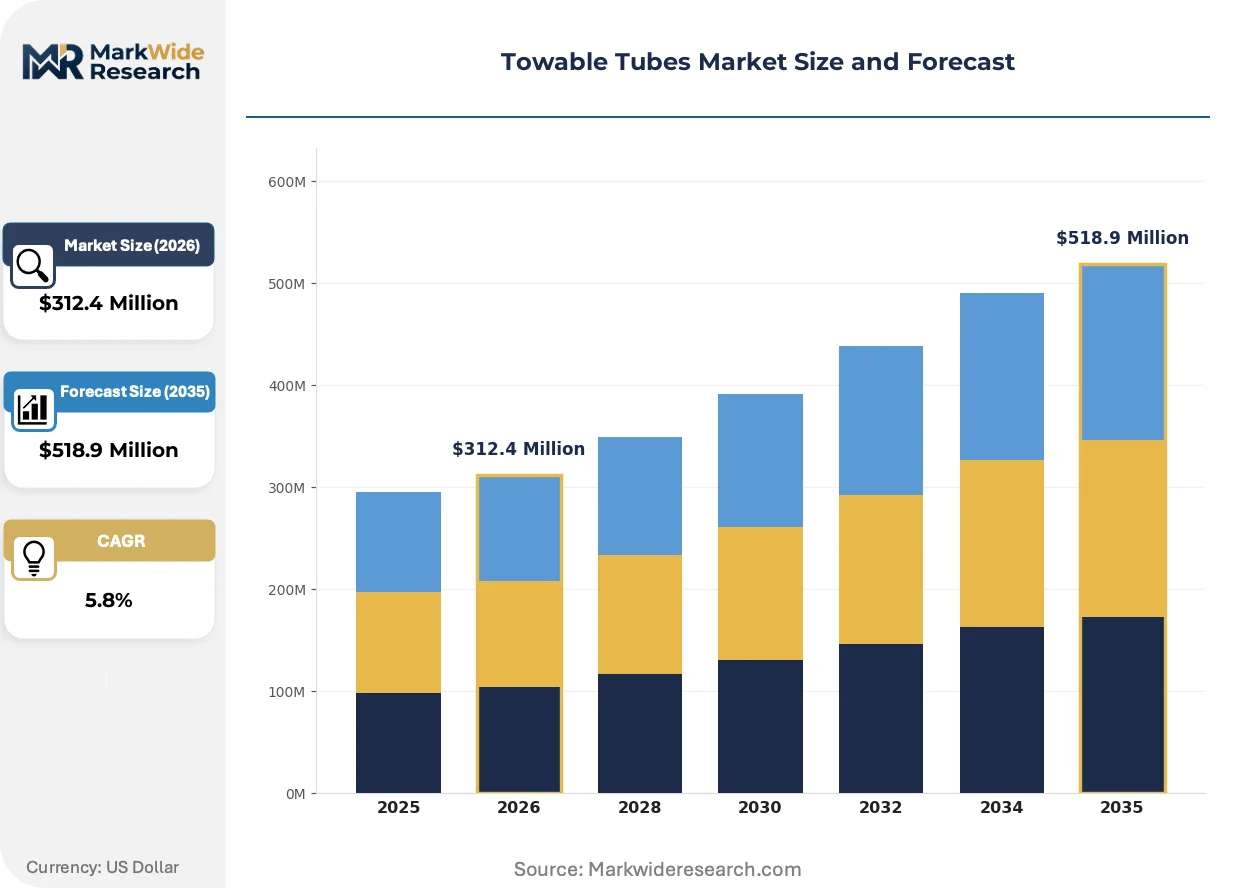
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Tubes, Banana Tubes, Deck Tubes, Sit-in Tubes End User: Families, Water Sports Enthusiasts, Rental Companies, Resorts Material: PVC, Nylon, Neoprene, TPU Capacity: 1 Person, 2 Persons, 3 Persons, 4 Persons |
| Companies Covered | O'Brien, Jobe, WOW Sports, Liquid Shredder, Airhead, RAVE Sports, Connelly, Hyperlite, HO Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Towable Tubes Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to reshape competitive differentiation in towable water sports equipment, with durability and compliance emerging as primary purchase criteria.
Thermoplastic polyurethane formulations are hybridizing traditional PVC-nylon construction paradigms, delivering puncture resistance and UV stability previously unavailable in recreational price tiers. Commercial rental operators in high-usage lake environments are adopting TPU-skinned models at accelerated replacement cycles. This material transition is compressing competitive advantage windows for manufacturers locked into legacy commodity-grade supply contracts.
The Consumer Product Safety Commission's evolving seam integrity testing protocols are forcing redesign of tow-point harness attachment geometries. Manufacturers must now validate load-bearing stitch patterns through third-party certification, adding compliance timeline friction. Deck tube categories face the steepest redesign burden, as their flat-rider configurations concentrate stress at perimeter seam junctions.
Buyer concentration among multi-location rental chains is consolidating procurement authority previously dispersed across independent operators. National fleet managers are unbundling after-sales service from equipment purchase, negotiating direct maintenance partnerships with regional repair networks. This purchasing pattern shift is most visible across Florida's seasonal tourism corridor, where replacement volume justifies dedicated vendor relationship structures.
Towable Tubes Market Segmentation
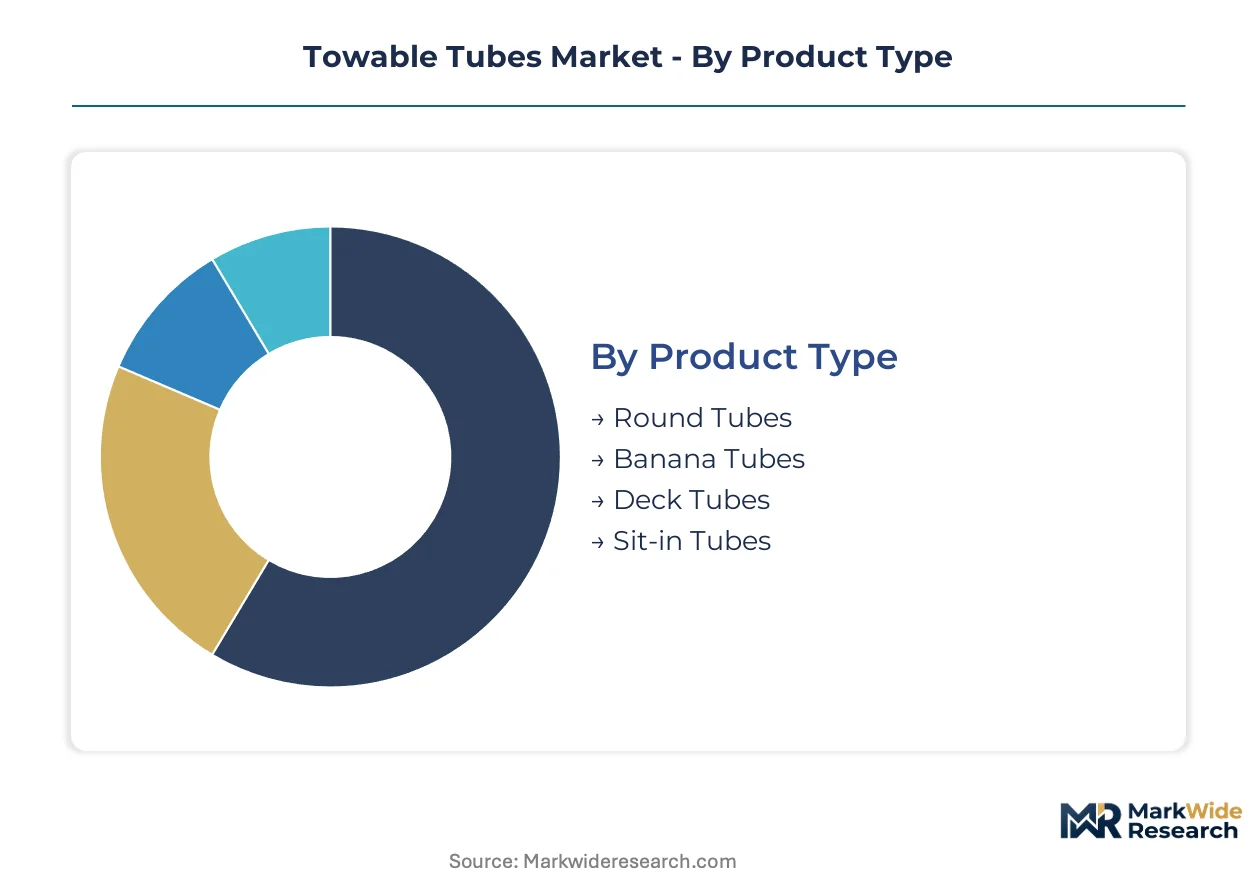
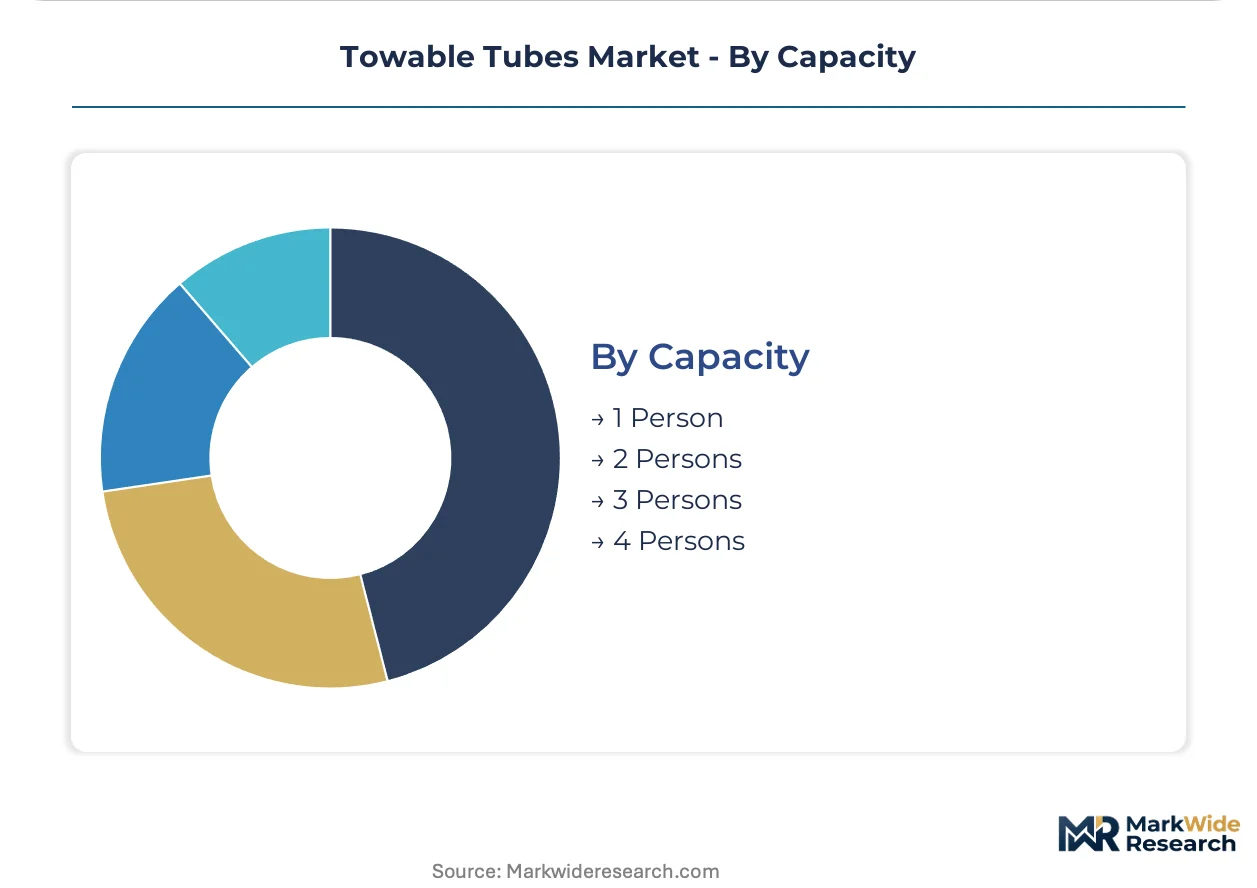
Towable tube procurement patterns diverge sharply across rider configuration, buyer category, and material specification. Understanding these segment boundaries clarifies why manufacturers maintain parallel product architectures rather than unified platforms.
Product Type:
Application context determines which tube geometry commands placement priority in retail and rental channels.
- Round Tubes:Classic circular bladders with central cockpit seating dominate entry-level family purchases due to predictable stability at moderate tow speeds. Demand clusters in Minnesota's lake cabin communities where multi-generational users prioritize forgiving handling over maneuverability.
- Deck Tubes:Flat-rider platforms with EVA foam padding and multiple grab handles accelerate rental fleet turnover through faster rider loading. Florida's inland waterway operators specify deck configurations for commercial durability under high-frequency daily use.
- Banana Tubes:Elongated multi-chamber designs deliver high-speed carving response for experienced riders. Water sports enthusiasts in Wisconsin's Door County drive specification requirements for reinforced tow-point geometry.
- Sit-in Tubes:Enclosed cockpit configurations with backrest support target younger riders and comfort-seeking families. Resort procurement in Michigan lake communities favors these models for liability-conscious guest programming.
Deck tubes hold installed capacity. Banana tubes are rotating up the share rankings.
End User:
Customer type segmentation reveals divergent purchasing rhythms and specification authority structures.
- Rental Companies:Fleet managers negotiate direct vendor relationships for seasonal replenishment, prioritizing seam durability certifications and rapid-warranty response networks. Procurement concentrates in Florida's tourism corridor and Minnesota's lake destination clusters.
- Families:Recreational buyers purchasing through marine specialty retail or direct-to-consumer channels emphasize price accessibility and storage compactness. Weekend cabin owners in Ohio and Wisconsin drive replacement cycles.
- Water Sports Enthusiasts:Performance-oriented riders command premium positioning through specialty retailers, demanding advanced material formulations and high-visibility coloration for crowded waterway safety.
- Resorts:Hospitality operators integrate towable equipment into packaged recreation programming, requiring Coast Guard auxiliary guideline compliance and standardized rider capacity labeling across multi-location portfolios.
Rental companies anchor volume throughput. Resorts are gaining procurement sophistication fastest.
Material:
Cost tier and durability requirements stratify raw material selection across commercial and consumer applications.
- TPU:Thermoplastic polyurethane formulations deliver puncture resistance and extended UV stability previously unavailable in recreational price tiers. Commercial rental operators in high-usage lake environments are adopting TPU-skinned models at accelerated replacement cycles.
- PVC:Heavy-gauge polyvinyl chloride remains the volume workhorse for value-tier family purchases, though petrochemical feedstock volatility compresses margin pools for manufacturers locked into commodity-grade supply contracts.
- Nylon:Reinforced nylon bladder construction with woven skin layers captures margin pools in the replacement segment, particularly among rental operators seeking mid-cycle durability upgrades without full TPU cost exposure.
- Neoprene:Knuckle guard and handle grip applications rely on specialized neoprene fabrication, where skilled sewing and bonding technician scarcity creates hiring bottlenecks for capacity expansion.
PVC holds installed capacity. TPU is rotating up the share rankings.
Capacity:
Rider count specifications fragment inventory requirements across buyer segments with distinct utilization patterns.
- 2 Persons:Dual-rider configurations balance social experience with manageable storage footprint, dominating family purchases and small rental fleet allocations. Wisconsin and Minnesota lake communities show particular concentration.
- 4 Persons:Maximum-capacity deck tubes command premium positioning in commercial rental fleets where per-ride revenue scales with rider count. Florida operators specify these for peak seasonal throughput.
- 1 Person:Solo rider tubes serve performance enthusiasts and specialized training applications, with limited volume outside water sports specialty channels.
- 3 Persons:Mid-capacity options fill niche positioning between standard family and commercial fleet specifications, often specified by resort operators seeking programming flexibility.
2-person configurations hold installed capacity. 4-person models are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bladder fabrication capacity clusters in Southeast Asian contract manufacturers, yet final assembly and distribution networks concentrate in domestic facilities serving seasonal replenishment windows.
United States
Florida's inland waterway corridor drives replacement demand through compressed seasonal tourism cycles. The Consumer Product Safety Commission enforces seam integrity testing protocols that accelerate legacy inventory obsolescence. Minnesota's 10,000 Lakes region and Wisconsin's Door County anchor multi-rider fleet expansion among independent rental operators.
Canada
Ontario's Great Lakes cottage communities sustain steady family replacement purchases through marine specialty retail channels. Transport Canada administers recreational watercraft safety standards that influence visible coloration specifications for commercial operators. British Columbia's Okanagan Valley lake destinations show emerging rental infrastructure development comparable to US saturation levels.
Germany
Engineering-focused water sports enthusiasts in Bavaria and Baden-Württemberg command premium positioning for high-performance banana tube configurations. The country's national product safety regulator enforces CE marking requirements that align with ISO 6185 buoyancy certification benchmarks. Lake Constance and Bavarian lake clusters concentrate specialty retail distribution for TPU-skinned models.
Australia
Queensland and New South Wales coastal tourism operators scale multi-rider deck tube acquisitions for reef-adjacent water sports programming. The Therapeutic Goods Administration (TGA) does not regulate towable equipment, leaving state-level maritime safety authorities to mandate rider capacity labeling. Gold Coast manufacturing subcontractors serve Asia-Pacific export markets with ISO 6185-certified bladder construction.
Brazil
São Paulo and Rio de Janeiro lake communities show underdeveloped rental infrastructure relative to North American penetration rates. The national health surveillance agency (ANVISA) lacks specific inflatable recreational watercraft jurisdiction, deferring to municipal waterway enforcement for operational safety standards. Paraná's Itaipu reservoir region concentrates emerging fleet investment among hospitality operators.
Towable Tubes Market Competitive Environment
Heritage marine brands and value-tier specialists split the market into distinct procurement channels. Rental fleet managers negotiate direct vendor relationships prioritizing warranty response velocity, while family buyers route through marine specialty retail or direct-to-consumer platforms. Three archetypes dominate: legacy water sports houses with domestic assembly control, European design-origin exporters, and price-positioned volume players. Competitive moves center on material formulation licensing and seasonal inventory pre-positioning partnerships with regional distributors.
Within the heritage marine tier, O'Brien anchors domestic assembly capabilities that compress lead times for Florida corridor replenishment. Jobe exemplifies European design-origin positioning while competing aggressively in North American distribution channels. Airhead occupies the value-tier vector, capturing entry-level family buyers through price-accessible PVC configurations. These three fabricators represent the strategic spectrum without exhausting the participant base.
| Leading Market Players |
|---|
| O'Brien |
| Jobe |
| WOW Sports |
| Liquid Shredder |
| Airhead |
| RAVE Sports |
| Connelly |
| Hyperlite |
| HO Sports |
| Others |
Value Chain & Pricing Dynamics
Southeast Asian bladder fabrication clusters in Vietnam and Thailand concentrate reinforced nylon chamber supply, anchoring margin pools in domestic final assembly and seasonal distribution partnerships. TPU formulation licensing premiums and CPSC compliance certification costs stratify pricing power between heritage marine brands and value-tier PVC competitors.
Pricing Analysis
The Consumer Product Safety Commission dictates the pricing tier structure through seam integrity testing mandates that add compliance timeline friction. Three-tier pricing structure across premium TPU, standard nylon-reinforced, and economy PVC levels separates rental fleet specifications from family recreational purchases. Cost compression in commodity-grade PVC tiers intensifies because petrochemical feedstock volatility erodes manufacturer margins. Rental companies show lowest price sensitivity due to total cost of ownership calculations, while weekend cabin owners in Ohio and Wisconsin drive highest price elasticity.
Supply Chain Analysis
Extended payment terms from domestic assembly facilities to Southeast Asian bladder suppliers characterize working capital structures in this industry. Bladder fabrication draws from Vietnam, Thailand, and Indonesia, while neoprene knuckle guard fabrication rests on legacy textile regions in the southeastern United States. Single-source vulnerability during peak seasonal windows creates structural risk when Florida's inland waterway corridor demands simultaneous replenishment. Distribution runs through marine specialty retail, direct-to-consumer platforms, and direct vendor relationships with national rental chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic polyurethane material science disruption is compressing competitive advantage windows for manufacturers locked into legacy PVC supply contracts. CPSC seam integrity protocol evolution accelerates this inflection by forcing redesign investments that favor capitalized incumbents.
For Market Incumbents: Insulate domestic assembly capacity through backward integration into TPU formulation partnerships that secure puncture-resistant material supply. Capture rental fleet procurement consolidation by embedding rapid-warranty response networks directly into national chain vendor relationships. O'Brien's lead-time compression model in Florida corridor replenishment exemplifies this defensive positioning against European design-origin exporters.
For New Entrants and Emerging Players: Michigan and Ohio lake communities show underdeveloped rental infrastructure relative to Florida saturation levels, presenting white-space acquisition targets. Paraná's Itaipu reservoir region in Brazil concentrates emerging hospitality fleet investment with limited qualified supplier presence. Direct-to-consumer channel innovation bypassing marine specialty retail markups offers the most penetrable go-to-market angle for capital-light entry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine recreation platforms seeking exit liquidity through strategic rollup. Five-to-ten year viability hinges on material formulation IP and CPSC certification infrastructure rather than brand heritage alone. Watch TPU adoption velocity among commercial rental operators as the signal indicating whether premium material transitions sustain margin expansion or compress toward commodity pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| TPU Material Licensing Agreement | Secures puncture-resistant formulations for Florida rental fleet specifications ahead of competitors. |
| Direct-to-Consumer Platform Launch | Bypasses marine specialty retail markups to capture margin previously lost to distribution tiers. |
| CPSC Certification Pre-Positioning | Accelerates seam integrity validation timelines before peak seasonal replenishment windows. |
| Regional Repair Network Partnership | Unbundles after-sales service from equipment purchase for national rental chain procurement. |
| Great Lakes Distribution Expansion | Targets Michigan and Ohio lake communities with underdeveloped rental infrastructure. |
Study Parameters
Cross-validation between primary interviews with rental fleet managers, marine specialty retail buyers, and neoprene fabrication technicians anchors the qualitative findings. Secondary validation draws from CPSC enforcement bulletins, ISO 6185 certification registries, and U.S. Coast Guard auxiliary guideline updates. Customs records tracking heavy-gauge PVC and TPU resin imports, alongside SEC filings from marine recreation parent companies, provide demand-side triangulation. Bottom-up channel checks across Minnesota's 10,000 Lakes region and Wisconsin's Door County converge with top-down market sizing across product type, end user, material, and capacity segments.
Calibration against historical replacement cycle patterns and seasonal tourism correlation indices shapes the analytical framework across the projection horizon. Segmentation dimensions include tube geometry, buyer category archetype, material formulation tier, and rider capacity specification. CAGRs derive from installed base turnover rates, regulatory obsolescence acceleration, and material substitution elasticity. Forecast inputs incorporate Florida inland waterway corridor replenishment velocity and Great Lakes secondary market penetration trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by TPU-specialized new entrants or rapid CPSC protocol tightening would shift outcomes. Macroeconomic deviation in petrochemical feedstock costs, state-level watercraft liability framework fragmentation, or breakthrough material science disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
North America Hovercraft Market