
 Global Truck Camper Market | 2026-2036
Global Truck Camper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Truck Camper Market Outlook
The EPA's updated emissions thresholds for light-duty truck chassis is recalibrating the cost-of-entry calculus for camper manufacturers dependent on domestic pickup platforms. Host Industries leverages vertical integration across its Indiana manufacturing campus to sustain margin control amid chassis scarcity. Lance Camper anchors its competitive position through fiberglass-dominant product lines that navigate stricter weight compliance. Soaring Eagle Campers specializes in compact hard-sided configurations that occupy the entry-premium tier.
A truck camper constitutes a demountable recreational living module engineered for mounting within the bed of a full-size or mid-size pickup truck, typically constructed with aluminum framing, fiberglass shells, or composite sandwich panels to achieve payload limits between 1,500 and 6,000 pounds while providing sleeping quarters, galley facilities, and wet-bath amenities. Its primary commercial purpose centers on converting existing truck assets into mobile lodging platforms without requiring dedicated tow vehicles or separate registration. Hard-Sided Campers dominate installed base value due to superior insulation and four-season usability, while Composite material adoption accelerates fastest as manufacturers pursue weight reduction without structural compromise. The Compact size tier captures disproportionate interest from Adventure Travelers seeking backcountry access on modified off-road chassis.
The National Highway Traffic Safety Administration enforces occupant protection standards that shape camper structural design, while the EU's F-Gas Regulation constrains refrigeration system specifications for export-bound units. The US Forest Service's expanded dispersed camping policies in western states amplify addressable demand for self-contained units. Stakeholders must monitor chassis manufacturer electrification timelines, as battery-electric pickup payload reductions threaten conventional camper weight assumptions.
Market Dynamics
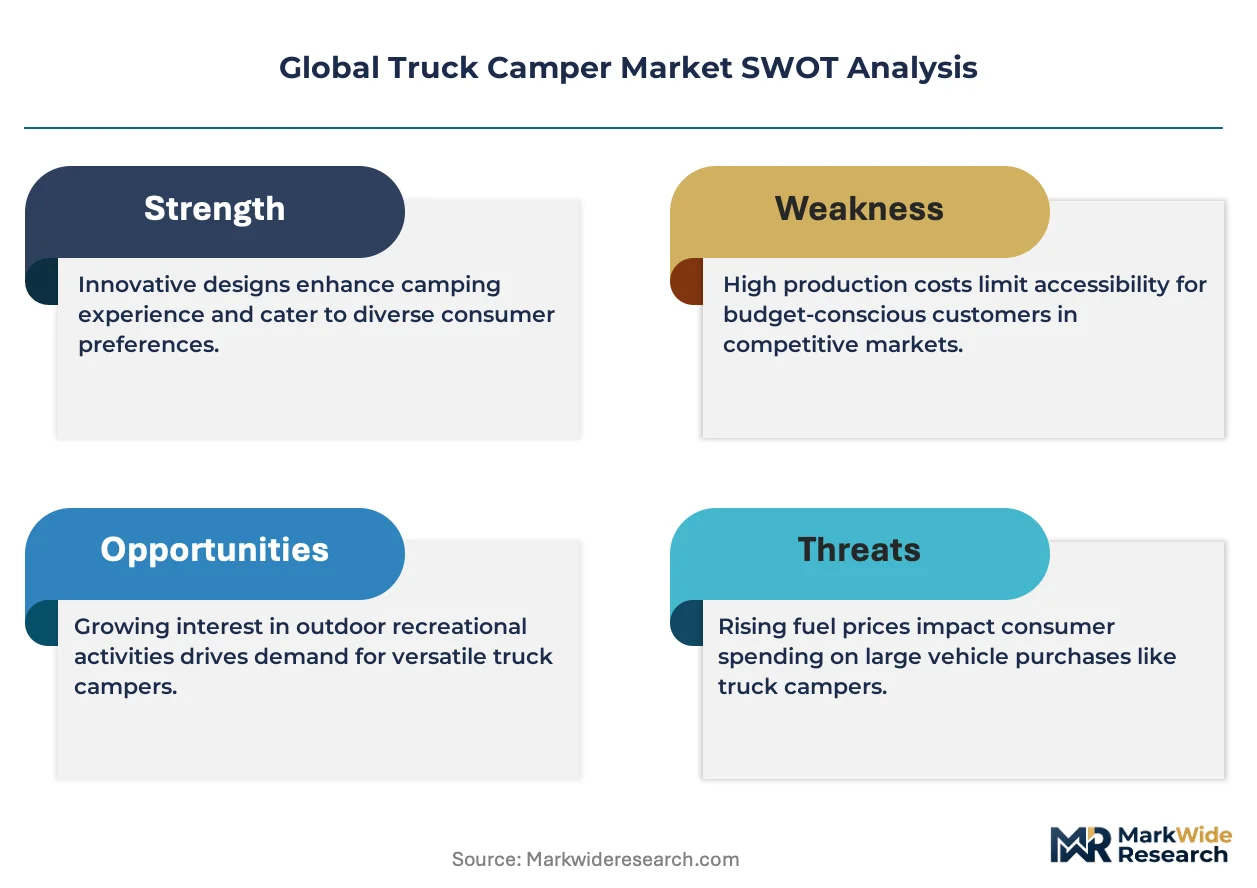
Chassis electrification timelines at Ford, GM, and Stellantis are compressing payload capacity assumptions that governed camper design for decades, forcing manufacturers to recalibrate material specifications and sleeping configurations simultaneously.
Growth Catalysts
- EU Green Deal material mandates:Carbon footprint disclosure requirements for imported recreational vehicles are accelerating composite panel adoption among European-bound manufacturers, creating compliance-driven upgrade cycles.
- Dispersed camping policy liberalization:The US Forest Service's expanded backcountry access protocols in western states are amplifying demand for self-contained, off-grid capable units with integrated solar and water systems.
- Adventure Traveler segment expansion:Post-pandemic mobility preferences among remote workers are converting pickup trucks into dual-use assets for weekday commuting and weekend recreation.
Market Restraints
- Chassis supply concentration:Dependence on three domestic pickup manufacturers creates allocation vulnerability during semiconductor shortage periods or production retooling for electric platforms.
- Aluminum-lithium composite pricing volatility:Lightweight structural material costs fluctuate with aerospace sector demand, compressing margin predictability for mid-tier producers.
- Payload compliance fragmentation:Divergent state-level enforcement of GVWR regulations creates interstate commerce friction for rental fleet operators and cross-country buyers.
Strategic Opportunities
- Australian overland export channel:Established pickup culture and remote touring infrastructure create addressable demand for four-season hard-sided configurations with enhanced dust sealing.
- Battery-electric chassis adaptation:Frunk-integrated power take-off systems in Ford F-150 Lightning and Rivian R1T platforms enable all-electric HVAC and cooking without auxiliary generators.
- Modular interior systems:Swappable bed-galley-wet-bath configurations allow single-shell platforms to address both weekend warrior and extended expedition use cases.
Industry Challenges
- Composite technician scarcity:Fiberglass and carbon-fiber layup expertise concentrates in marine and aerospace sectors, constraining workforce expansion for camper shell production.
- Multi-jurisdiction certification timelines:Separate NHTSA crashworthiness validation, EPA emissions compliance for onboard generators, and state RV safety inspections extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Truck Camper Market |
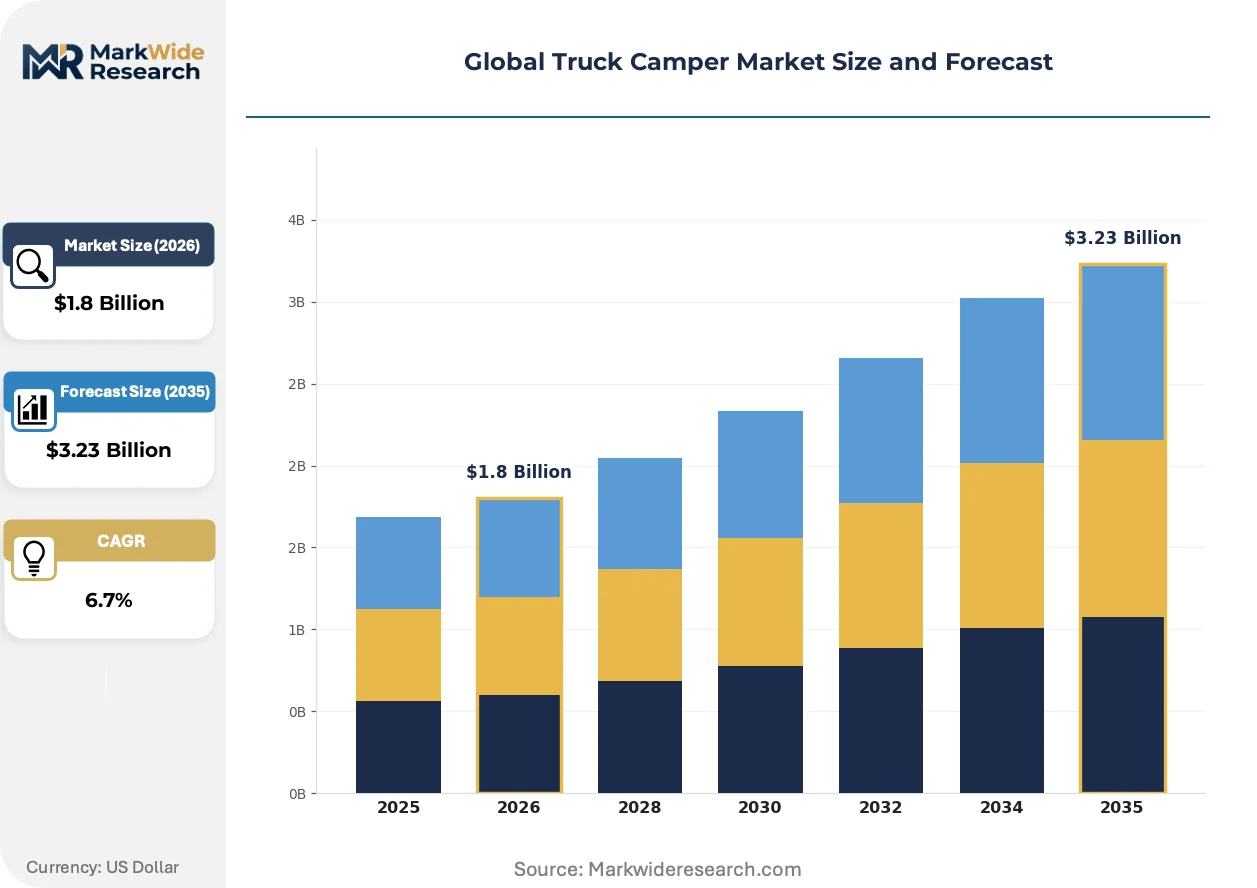
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard-Sided Campers, Soft-Sided Campers, Hybrid Campers, Custom Campers End User: Recreational Users, Commercial Users, Adventure Travelers, Seasonal Campers Size: Compact, Standard, Large, Extra Large Material: Aluminium, Fiberglass, Wood, Composite |
| Companies Covered | Supertramp Campers, Soaring Eagle Campers, Host Industries, 27 North, Tune Campers, nuCamp, Kingstar, Total Composites, Lance Camper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Truck Camper Market Strategic Shifts
Powertrain electrification is forcing simultaneous innovation across three vectors: structural weight reduction, onboard energy management, and manufacturing process adaptation. Each vector carries distinct competitive implications for incumbent and emerging producers.
Structural honeycomb composite panels are decentralizing manufacturing location decisions by enabling regional fabrication without heavy metalworking infrastructure. Adventure Traveler buyers in Colorado, Utah, and Idaho are specifying these configurations at accelerating rates. The technology is decentralizing production from traditional Midwest metalworking clusters to distributed composite shops near western recreation corridors.
REACH chemical restriction expansions are eliminating legacy adhesive and coating formulations from EU-bound product lines. German and French import channels now require full material substance documentation across supply tiers. Hard-sided camper manufacturers serving Scandinavian markets are reformulating shell lamination processes to maintain CE marking eligibility.
Direct-to-consumer configuration platforms are compressing traditional dealer intermediary roles in North American distribution. Western US buyers increasingly specify shell materials, interior layouts, and off-road packages through manufacturer websites before chassis delivery. This channel shift concentrates in states with dispersed camping infrastructure and high pickup ownership density.
Global Truck Camper Market Segmentation
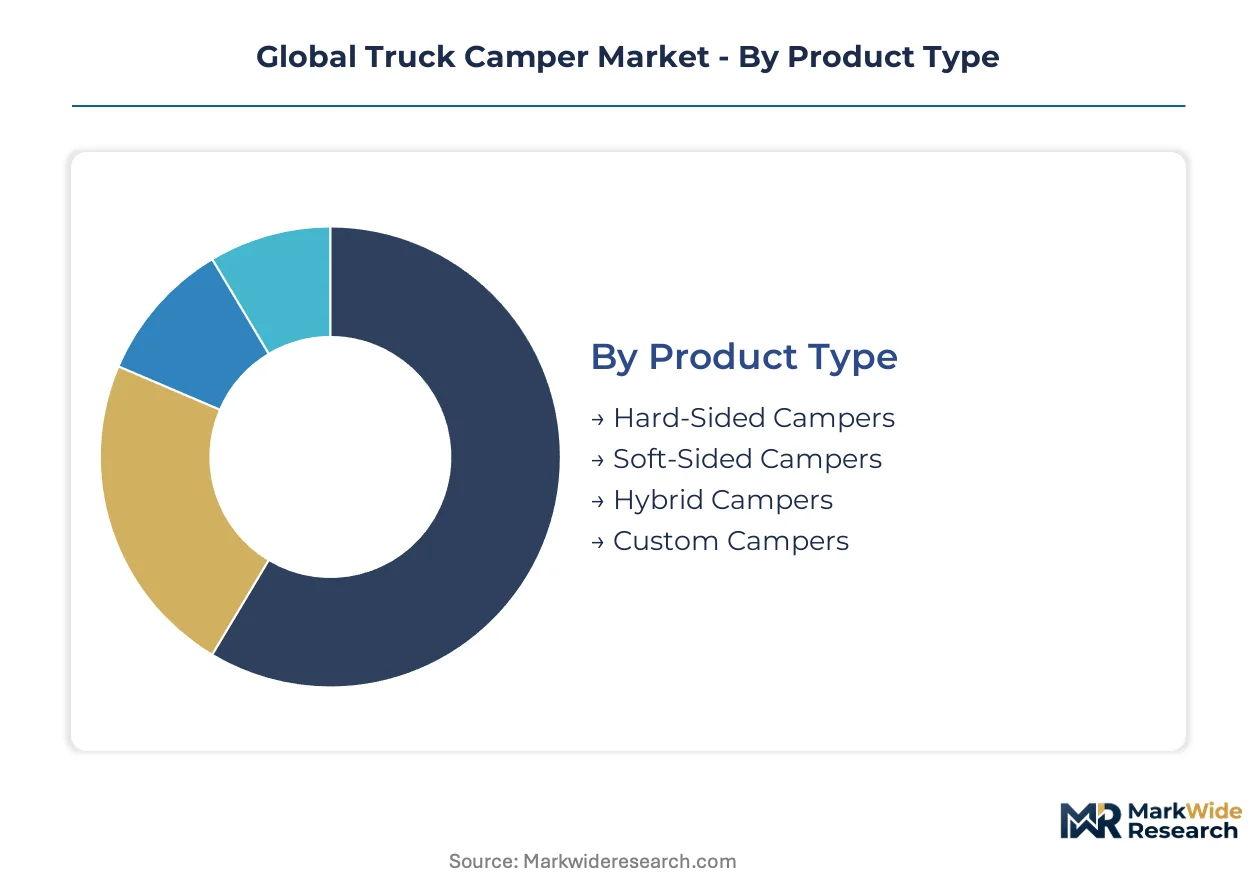
Truck camper segmentation reflects divergent buyer priorities across durability, mobility, and compliance requirements. Product architecture, user profile, dimensional constraints, and material selection each create distinct competitive arenas with separate margin profiles and regulatory exposure.
Product Type:
Customization intensity spans from mass-produced hard shells to bespoke expedition builds, with standardization economies concentrating in high-volume configurations.
- Hard-Sided Campers:Rigid fiberglass or aluminum exoskeletons deliver thermal insulation and weather resistance for four-season operation. Demand clusters among dispersed camping enthusiasts in Colorado, Utah, and Idaho where NHTSA occupant protection standards shape structural reinforcement requirements.
- Soft-Sided Campers:Collapsible fabric walls reduce travel height and weight for garage storage compatibility. Pop-up mechanisms appeal to urban buyers in California and Texas converting daily-driver pickups into weekend platforms without parking penalties.
- Hybrid Campers:Hard lower shells with fabric upper sections balance weather protection and weight reduction.
- Custom Campers:Bespoke fabrication for expedition-grade specifications with reinforced mounting systems.
Most installed capacity flows through Hard-Sided Campers. Expansion is steepest in Hybrid Campers.
End User:
Commercial logic separates fleet procurement from individual purchase cycles, with application durability dictating warranty and service infrastructure requirements.
- Recreational Users:Weekend and vacation-oriented buyers seeking dual-use asset conversion of existing pickup trucks. This segment concentrates in the United States where dispersed camping policy liberalization by the US Forest Service amplifies demand for self-contained units.
- Adventure Travelers:Remote workers and extended expedition planners requiring off-grid power and water autonomy. Buyers in western states specify compact configurations for modified off-road chassis access to backcountry terrain.
- Commercial Users:Utility fleets and mobile service operations deploying campers as field accommodation.
- Seasonal Campers:Snowbird and hunting-season buyers with predictable annual usage patterns.
Recreational Users anchor current revenue concentration. Adventure Travelers are climbing the fastest as post-pandemic mobility preferences solidify.
Size:
Payload compliance and chassis compatibility create hard boundaries that segment buyers by truck class ownership and intended terrain access.
- Compact:Sub-1,500-pound dry weights enabling half-ton pickup compatibility and technical trail access. Australian overland export channels favor these configurations for remote touring infrastructure.
- Standard:Three-quarter-ton optimized dimensions balancing living space and GVWR headroom.
- Large:Full-size truck beds with expanded galley and wet-bath amenities.
- Extra Large:One-ton dually configurations maximizing interior volume for extended occupancy.
Standard dimensions dominate production volume. Compact units are gaining share fastest through adventure traveler specification.
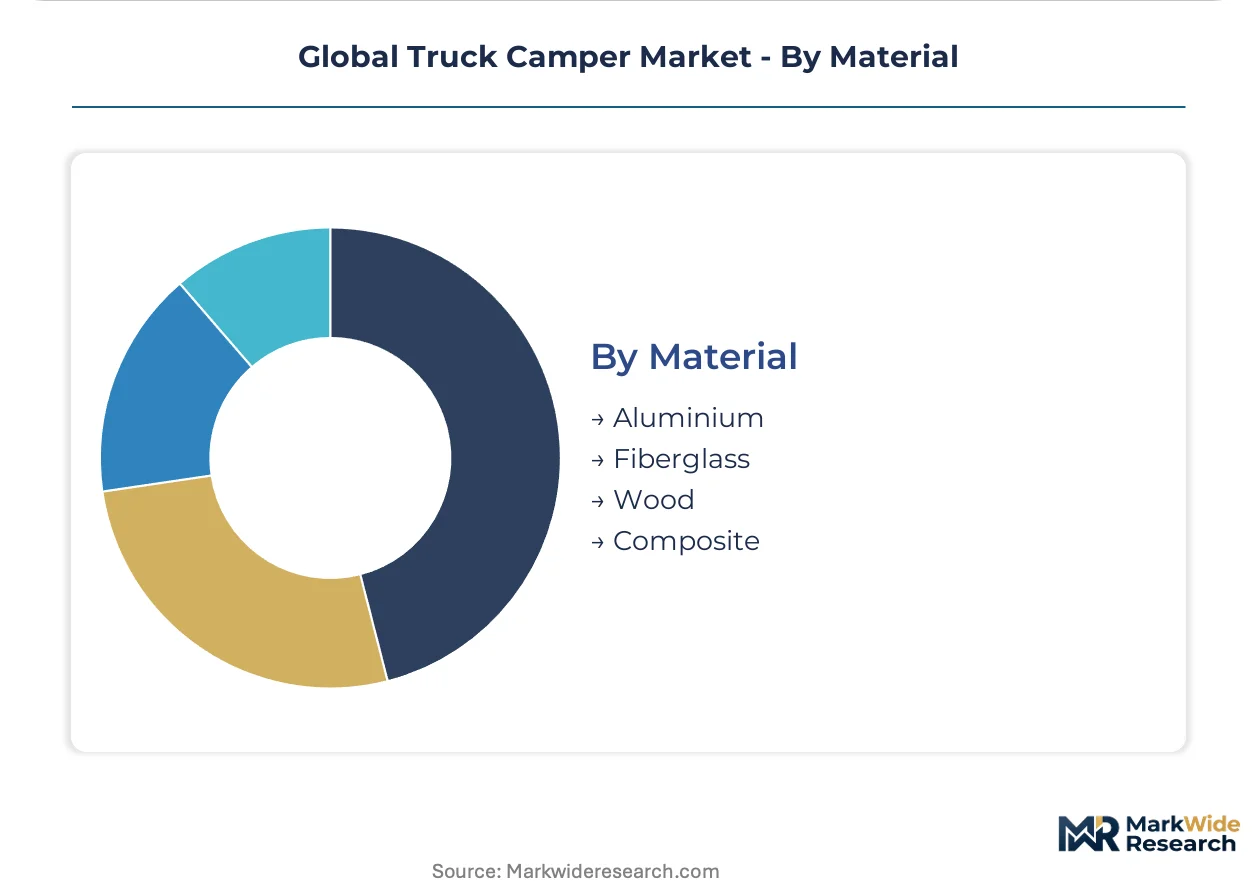
Material:
Weight-versus-durability tradeoffs intersect with EU regulatory compliance to reshape supplier qualification and fabrication location decisions.
- Composite:Honeycomb sandwich panels combining fiberglass skins with structural cores achieve maximum strength-to-weight ratios. EU Green Deal carbon footprint disclosure requirements for imported recreational vehicles accelerate adoption among European-bound manufacturers.
- Fiberglass:Gel-coated shells dominate hard-sided production with proven weather sealing and repairability.
- Aluminium:Extruded framing and sheet construction offers corrosion resistance and recyclability.
- Wood:Traditional framing persists in entry-tier and restoration segments.
Fiberglass commands the largest installed base. Composite fabrication is expanding most quickly as electrified chassis payload reductions force material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Truck camper manufacturing originated in post-war North America, where pickup truck proliferation and dispersed recreation infrastructure created the first scalable market. Production techniques migrated to Australia and Europe as overland touring cultures matured, with each region developing distinct regulatory and material specifications.
United States
Dispersed camping policy liberalization by the US Forest Service in western states amplifies demand for self-contained, off-grid capable units. NHTSA occupant protection standards shape structural reinforcement requirements for all domestic-bound production. Manufacturing clusters concentrate in Indiana and the Pacific Northwest, where Host Industries maintains vertical integration across its Indiana campus to control margins amid chassis scarcity.
Germany
REACH chemical restrictions and EU Green Deal carbon footprint disclosure requirements are eliminating legacy adhesive formulations from camper shells bound for Scandinavian markets. KBA vehicle type approval processes govern pickup platform modifications for overland configurations. Industrial activity clusters in Baden-Württemberg, where composite panel suppliers serve both automotive and recreational vehicle sectors with shared technical expertise.
Australia
Established pickup culture and remote touring infrastructure create sustained demand for four-season hard-sided configurations with enhanced dust sealing. The country's national vehicle safety regulator enforces ADR compliance for imported and domestically manufactured camper modules. Fabrication concentrates in Queensland and Western Australia, where proximity to mining and agricultural fleets supports dual-use commercial-recreational production.
Canada
Extended wilderness access seasons and dispersed crown land camping policies sustain demand for insulated, four-season configurations. Transport Canada CMVSS standards align with US NHTSA thresholds, enabling cross-border product harmonization. Manufacturing activity centers in Ontario and British Columbia, where proximity to US supply chains and Rocky Mountain recreation corridors supports regional distribution.
Global Truck Camper Market Competitive Environment
The competitive structure tilts toward vertically integrated regional specialists rather than consolidated multinational players. Mid-tier fabricators dominate volume production, with premium-tier specialists capturing disproportionate margin through material differentiation and bespoke configuration. Two strategic archetypes prevail: Indiana-based metalworking-heritage producers with captive chassis relationships, and western composite specialists serving adventure traveler specifications. Dominant competitive moves include backward integration into shell lamination processes and direct-to-consumer configuration platforms that compress traditional dealer intermediaries.
Within the vertically integrated tier, Host Industries anchors Indiana-based production with campus-scale manufacturing control. Lance Camper occupies a position exemplifying fiberglass-dominant product architecture for weight compliance navigation. Soaring Eagle Campers represents the compact hard-sided specialization targeting entry-premium tier buyers. These three fabricators illustrate the geographic and material stratification governing competitive positioning across North American supply.
| Leading Market Players |
|---|
| Supertramp Campers |
| Soaring Eagle Campers |
| Host Industries |
| 27 North |
| Tune Campers |
| nuCamp |
| Kingstar |
| Total Composites |
| Lance Camper |
| Others |
Value Chain & Pricing Dynamics
Aluminum-lithium composite sheet pricing volatility cascades through camper shell fabrication tiers, compressing margin headroom for mid-tier producers while premium fiberglass-dominant lines absorb cost spikes through specification premiums. Raw material cost passthrough mechanics separate captive-supply incumbents from contract-dependent fabricators across Indiana and Pacific Northwest production clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with differentiation anchored in material certification grade and after-sales service bundling. Price differentiation intensifies as EU Green Deal compliance costs concentrate in European-bound configurations, while domestic buyers face compressed negotiation leverage amid chassis allocation scarcity. Adventure Traveler segments exhibit lowest price sensitivity due to expedition-grade specification requirements, whereas entry-tier recreational buyers concentrate purchasing power on compact hard-sided units.
Supply Chain Analysis
Refurbishment flows for composite shell delamination and frame fatigue create secondary material recovery channels that extend component lifecycle economics. Manufacturing concentration centers on the United States, Germany, and Australia, with raw material dependencies spanning aerospace-grade aluminum-lithium alloys, fiberglass roving, and structural adhesive formulations. Single-source vulnerability concentrates in chassis platform supply from Ford, GM, and Stellantis production networks. Distribution runs through direct-to-consumer configuration platforms and traditional dealer intermediaries, with channel mix shifting toward manufacturer-controlled digital specification tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite material substitution and direct-to-consumer channel compression present dual margin-expansion pathways as chassis electrification timelines force weight reduction premiums.
For Market Incumbents: Anchor competitive position through backward integration into fiberglass lamination processes and captive chassis allocation agreements with domestic pickup manufacturers. Composite technician scarcity from marine and aerospace sector competition threatens workforce scaling for shell production expansion. Defend against emerging western composite specialists by consolidating dealer network control in dispersed camping corridor states. For New Entrants and Emerging Players: Begin with compact hard-sided configurations targeting Australian overland export channels, where established pickup culture and remote touring infrastructure create addressable white space. The entry-premium tier offers lowest incumbent saturation relative to specification complexity. Pursue direct-to-consumer configuration platforms to bypass traditional dealer margin extraction. For Investors and Strategic Acquirers: Roll-up economics work for regional composite specialists because fabrication decentralization enables distributed production near western recreation corridors without heavy metalworking infrastructure. Target acquisition archetypes include Baden-Württemberg-based panel suppliers with shared automotive technical expertise and Queensland fabricators serving mining fleet dual-use demand. Monitor battery-electric pickup payload specifications as inflection signal for conventional camper weight assumption obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Substitution | EU Green Deal carbon disclosure requirements accelerate honeycomb panel adoption among European-bound manufacturers. |
| Direct-to-Consumer Platform Launch | Western US buyers increasingly specify shell configurations through manufacturer websites before chassis delivery. |
| Backward Integration into Lamination | Captive fiberglass shell production insulates margin control from aerospace sector material demand spikes. |
| Australian Export Channel Development | Remote touring infrastructure and dust-sealing specifications create differentiated demand for four-season hard-sided units. |
| Battery-Electric Chassis Adaptation | Frunk-integrated power take-off in Ford F-150 Lightning and Rivian R1T enables all-electric HVAC without generators. |
Study Parameters
Coverage spans North America, Europe, and Australia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged camper manufacturing executives, composite material procurement leads, chassis platform engineers at domestic pickup OEMs, and dispersed camping policy administrators at the US Forest Service. Secondary sources incorporated NHTSA occupant protection filings, EU F-Gas Regulation documentation, KBA vehicle type approval records, and ADR compliance frameworks. Bottom-up production volume triangulation against top-down consumer expenditure patterns anchored value estimates.
Granularity-level modeling addressed product type, end user archetype, size tier, and material composition across the projection horizon. CAGRs derived from segment-level demand elasticity analysis against chassis availability constraints and regulatory compliance cost passthrough assumptions. Forecast inputs incorporated electrified pickup payload reduction timelines and REACH chemical restriction expansion schedules for adhesive formulation reformulation.
Several conditions sit outside the modeled scope, including semiconductor shortage recurrence severity, tariff rate modifications on aluminum-lithium composite imports, and state-level GVWR enforcement harmonization outcomes. Forecasts reflect assumptions regarding chassis manufacturer production allocation continuity and composite technician workforce expansion feasibility. Practitioners should monitor battery-electric pickup market penetration rates and EU carbon border adjustment mechanism implementation timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market