
 US Recreational Boating Market | 2026-2036
US Recreational Boating Market Size, Share, and Industry Trends Forecast 2026-2036
US Recreational Boating Market Analysis
Subscription-based boat clubs and fractional ownership models are tilting competitive dynamics toward asset-light operators that lower entry barriers for recreational users. Brunswick Corporation leverages its integrated parts-and-accessories network to sustain aftermarket revenue streams alongside new vessel sales. Yamaha Motor Corporation anchors its position through vertical control over outboard engine manufacturing and proprietary marine propulsion systems. Malibu Boats specializes in performance tow boats, dominating the watersport participant segment with purpose-built hull designs.
US recreational boating encompasses powered and unpowered vessels designed for leisure navigation, watersport towing, and coastal cruising, typically constructed from fiberglass-reinforced polymer, aluminum alloy, or marine-grade composite laminates with beam widths ranging from six to fourteen feet for trailered craft. The primary commercial purpose centers on delivering accessible leisure marine experiences to private owners and charter clients across inland waterways, coastal zones, and Great Lakes navigation corridors. Motorboats lead volume across the boat type dimension, while personal watercraft generates outsized margin contribution through lower production complexity and rapid replacement cycles. Charter services within the ownership structure dimension are expanding fastest as urban consumers near coastal metros prioritize access over equity.
The US Coast Guard enforces federal safety equipment mandates and vessel construction standards that dictate hull integrity testing and onboard fire suppression requirements for all commercially sold craft. The EPA regulates marine engine emissions under Clean Air Act Title II, compelling manufacturers to certify outboard and sterndrive powerplants to increasingly stringent hydrocarbon and nitrogen oxide limits. The National Marine Manufacturers Association coordinates industry compliance lobbying while state-level registration fees in Florida, Texas, and California shape regional demand elasticity. Stakeholders must monitor evolving electrification mandates and infrastructure subsidy programs that could reallocate competitive advantage between internal combustion incumbents and emerging electric propulsion entrants.
Market Dynamics
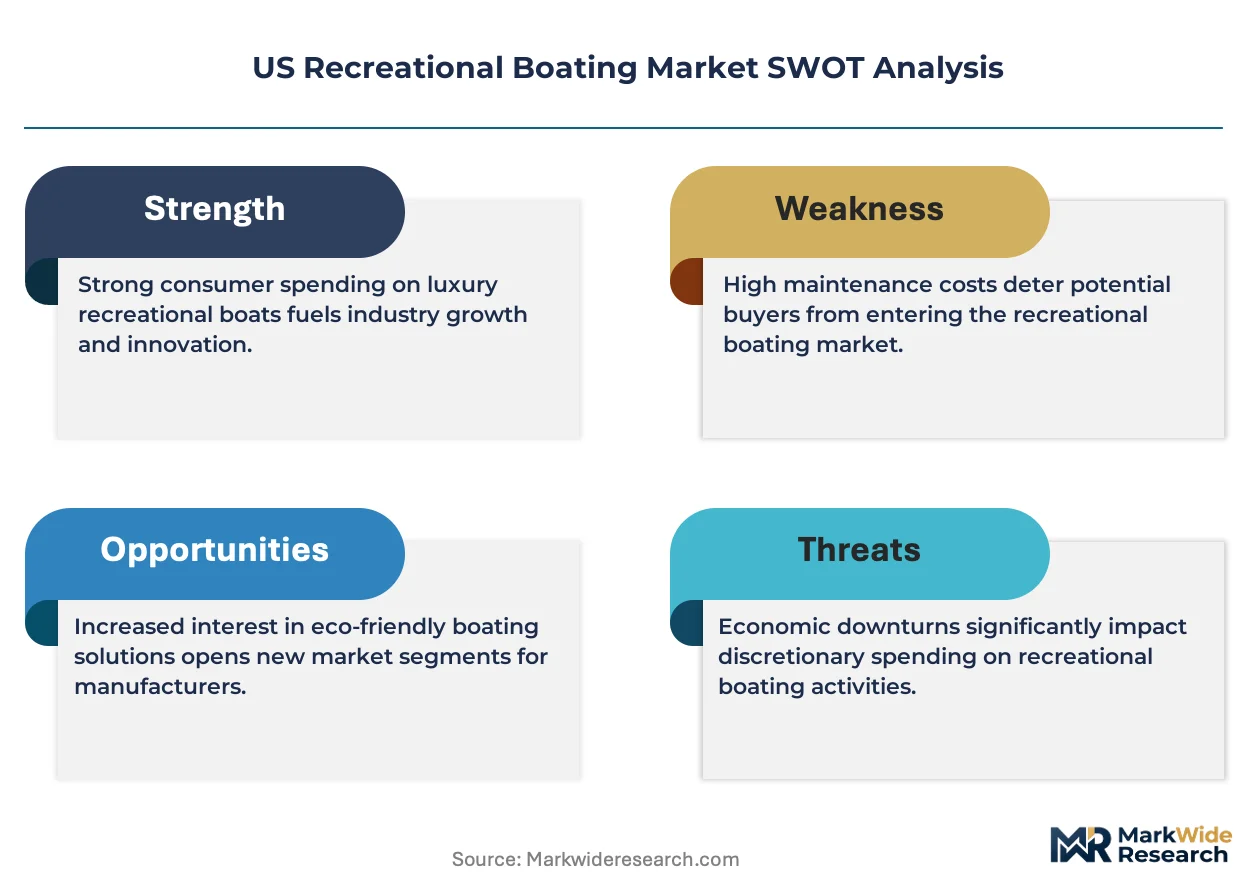
Electrification mandates and EPA emissions compliance are restructuring competitive advantage across propulsion systems, while subscription-based access models redistribute ownership economics toward asset-light platforms.
Growth Catalysts
- EPA Clean Air Act Title II:Stringent hydrocarbon and nitrogen oxide limits for outboard engines are accelerating manufacturer investment in cleaner propulsion architectures and certified powerplant redesigns.
- Florida's year-round boating season:Sustained vessel turnover in coastal Sun Belt states drives marina infrastructure expansion and supports higher replacement cycle frequency for motorized craft.
- Marine-grade lithium-ion battery systems:Energy density improvements in nautical battery packs are enabling viable electric range for inland day cruisers and pontoon configurations.
Market Restraints
- Aluminum alloy input volatility:Hull fabrication costs fluctuate with commodity pricing for marine-grade aluminum sheet and extrusion stock, compressing margin predictability for mid-market builders.
- Great Lakes seasonal contraction:Hibernation months in northern freshwater corridors restrict annual utilization rates and dampen new vessel demand elasticity in Michigan, Wisconsin, and Minnesota.
- Coastal mooring scarcity:Limited slip availability in high-density Florida and California harbors constrains fleet expansion for private owners regardless of acquisition capacity.
Strategic Opportunities
- Texas Gulf Coast underpenetration:Second-home development and retiree migration into Corpus Christi and Galveston corridors present whitespace for dealership network expansion and service infrastructure.
- Fractional ownership platforms:Urban coastal consumers in Seattle and Boston are prioritizing hourly access over equity, opening channel innovation for membership-based fleet operators.
- Infrastructure subsidy programs:Federal and state electrification grants for dockside charging installations could reallocate advantage toward early electric propulsion entrants with compatible vessel portfolios.
Industry Challenges
- Marine technician certification gaps:Shortage of ASE-certified outboard specialists and fiberglass repair craftsmen extends service wait times and erodes customer retention for dealership networks.
- Emissions compliance timeline compression:EPA certification cycles for redesigned powerplants strain R&D bandwidth, forcing simultaneous engineering of internal combustion refinement and electric platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Recreational Boating Market |
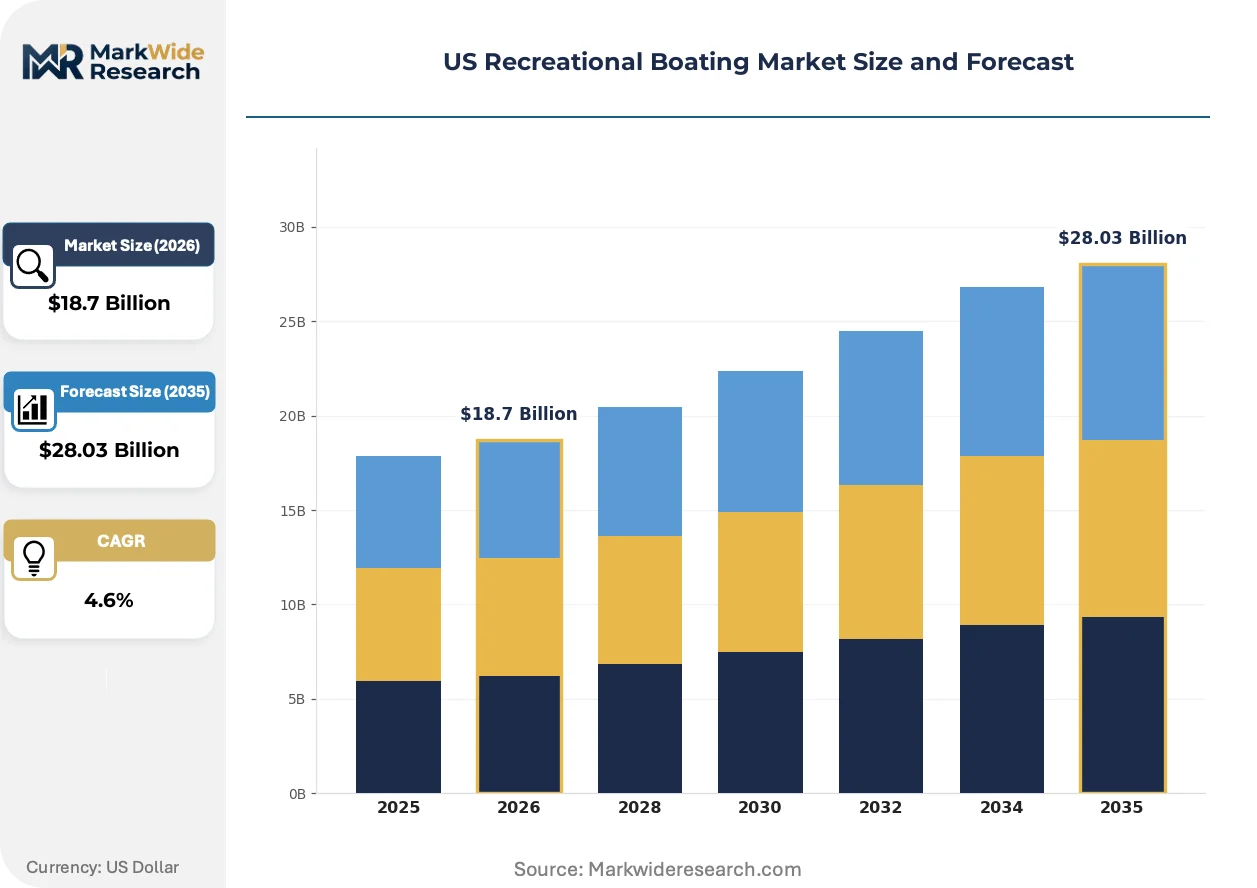
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Motorboats, Sailboats, Personal Watercraft, Yachts Ownership Structure: Private Ownership, Charter Services, Rental Agencies, Cooperatives Usage Frequency: Daily, Weekly, Monthly, Seasonal End User Segment: Families, Fishing Enthusiasts, Adventure Seekers, Watersport Participants |
| Companies Covered | Brunswick Corporation, Yamaha Motor Corporation, Groupe Beneteau, Malibu Boats, MasterCraft, Marine Products Corporation, Polaris Inc, Azimut Benetti Group, White River Marine Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Recreational Boating Market Emerging Trajectories
Propulsion electrification and digital hull design are compressing development cycles while access-based consumption models restructure how recreational marine experiences reach end users.
Integrated electric outboard systems from Mercury Marine and Torqeedo are collapsing the performance gap between fossil-fuel and battery-powered propulsion for sub-25-foot vessels. First-time buyers in freshwater lake communities are adopting these configurations at accelerating rates. The technology is collapsing residual value risk for traditional gasoline engine inventories and forcing dealership service departments toward electrical system competency.
EPA's updated marine engine emissions standards under Clean Air Act Title II are mandating evaporative emission controls and exhaust after-treatment for sterndrive powerplants. Manufacturers must certify to hydrocarbon limits that approach automotive Tier 3 equivalents. Sterndrive-equipped day cruisers face the steepest compliance cost escalation, prompting portfolio shifts toward outboard configurations that isolate engine emissions from hull certification.
Boat club memberships and fractional ownership platforms are displacing traditional dealer-financed retail in coastal metropolitan markets. Urban consumers within 50 miles of Seattle, Miami, and San Diego marinas increasingly prefer hourly access to diversified fleets over single-vessel equity. This consumption-pattern shift concentrates fleet purchasing power with platform operators and fragments individual buyer decision-making authority.
US Recreational Boating Market Segmentation
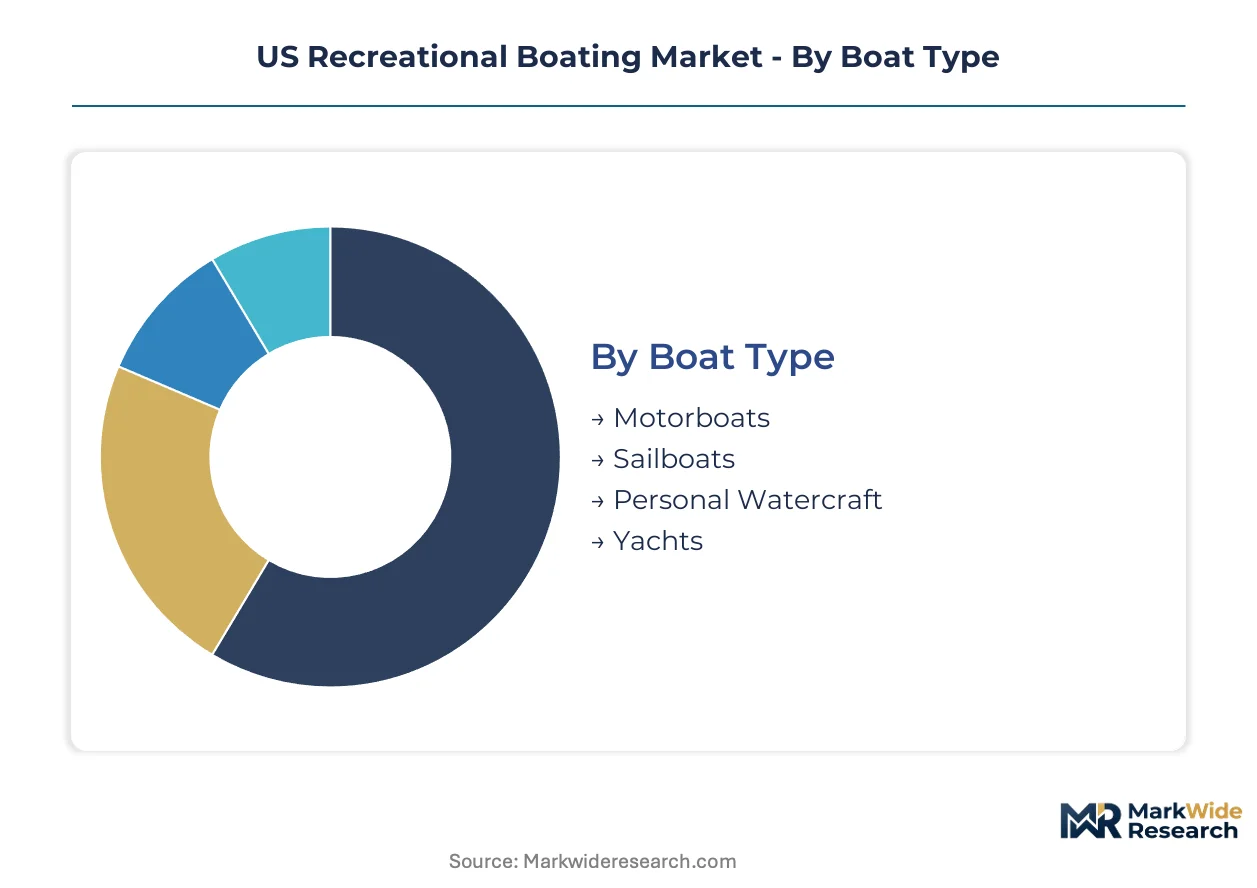
Segmentation in recreational boating reveals distinct demand profiles that shape vessel specifications, distribution channel requirements, and aftermarket service intensity. Understanding these divisions enables targeted product positioning across propulsion configurations, hull materials, and financing structures.
Boat Type:
Volume concentration across hull configurations tracks closely with propulsion technology maturity and price elasticity among first-time buyers.
- Motorboats:Fiberglass-reinforced polymer and marine-grade aluminum hulls with beam widths from six to fourteen feet dominate trailerable craft production. Demand concentrates in Florida's year-round boating corridors and Texas Gulf Coast second-home developments, driven by family cruising and fishing applications that favor outboard powerplant reliability.
- Personal Watercraft:Compact composite hulls with jet-pump propulsion systems enable rapid acceleration and watersport towing capability. Florida and California coastal metros sustain replacement cycle frequency through high hourly utilization rates and saltwater corrosion exposure that compresses asset lifespans.
- Sailboats:Displacement hulls with mast-stepped rigging and auxiliary diesel or electric propulsion serve coastal cruising and racing enthusiasts.
- Yachts:Large-displacement vessels exceeding forty feet in length with enclosed cabin configurations and multiple staterooms target high-net-worth ownership segments.
Motorboats hold installed capacity. Personal Watercraft is rotating up the share rankings.
Ownership Structure:
Access economics are tilting procurement authority from individual equity holders toward fleet operators and platform intermediaries.
- Private Ownership:Single-vessel equity positions with dealer financing and marine insurance requirements dominate traditional retail channels. Michigan and Wisconsin seasonal contraction patterns dampen utilization rates and extend replacement cycles for privately held craft in northern freshwater corridors.
- Charter Services:Commercial operators maintain diversified fleets with professional crew and scheduled maintenance protocols. Coastal metropolitan markets within fifty miles of Seattle, Miami, and San Diego marinas are expanding fastest as urban consumers prioritize hourly access over capital commitment.
- Rental Agencies:Short-term hourly and daily vessel access with standardized safety equipment and orientation protocols serves tourist corridors.
- Cooperatives:Member-governed shared ownership structures with rotating reservation systems and collective maintenance funds.
Private Ownership holds installed capacity. Charter Services is expanding most quickly.
Usage Frequency:
Utilization intensity determines service revenue potential, insurance pricing tiers, and residual value depreciation curves.
- Seasonal:Hibernation-month storage and spring commissioning cycles characterize Great Lakes and northern Atlantic operations. Minnesota and Wisconsin owners face compressed annual utilization that constrains accessory spending and dampens new vessel demand elasticity.
- Weekly:Regular weekend operation with trailer launch or slip-based storage supports consistent fuel, maintenance, and upgrade expenditures. Florida's year-round boating season sustains this pattern with higher replacement cycle frequency for motorized craft.
- Daily:Continuous operation with professional maintenance protocols typical of commercial fleet and high-enthusiast segments.
- Monthly:Occasional leisure operation with extended storage intervals and deferred maintenance accumulation.
Seasonal holds installed capacity. Weekly is climbing the fastest.
End User Segment:
Activity-specific requirements drive divergent hull design priorities, propulsion power specifications, and electronics package configurations.
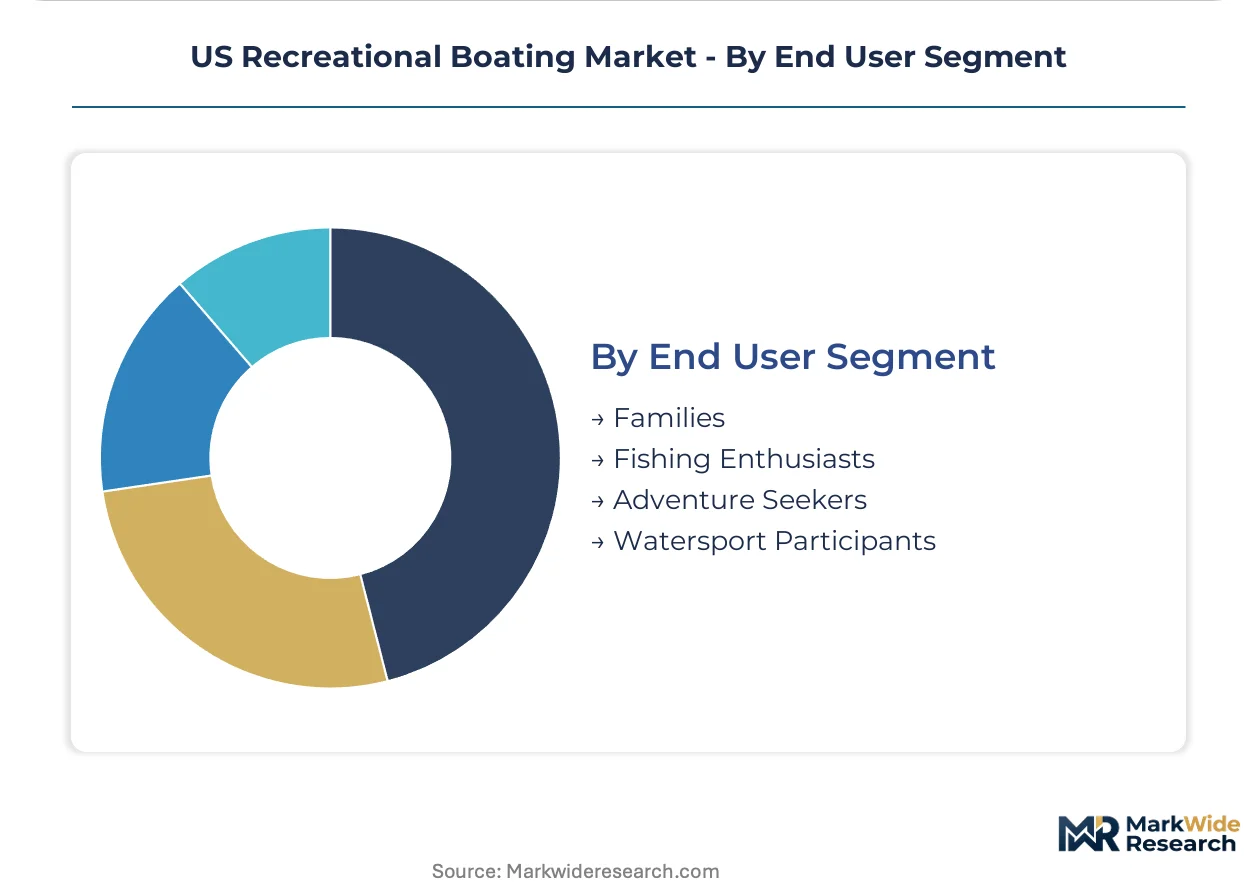
- Families:Pontoon boats and day cruisers with enclosed head compartments, swim platforms, and stability-optimized hull geometries dominate procurement. Coastal Sun Belt states with year-round operation sustain demand for family-oriented configurations that prioritize passenger capacity over speed performance.
- Watersport Participants:Purpose-built tow boats with ballast systems, wake-shaping hull designs, and high-torque inboard engines serve wakeboarding and waterskiing enthusiasts. Malibu Boats and similar specialists anchor positioning through vertical control over hull engineering and proprietary propulsion integration.
- Fishing Enthusiasts:Center-console and walkaround hulls with livewell systems, rod storage, and sonar electronics integration.
- Adventure Seekers:Rigid inflatable and shallow-draft vessels for coastal exploration and remote waterway access.
Families hold installed capacity. Watersport Participants is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in recreational boating favor domestic production, with US yards supplying the majority of coastal demand while specialty components and luxury European imports fill premium niches. Regional performance diverges sharply between Sun Belt states with year-round operation and northern corridors constrained by seasonal hibernation patterns.
Florida
Year-round subtropical climate sustains the nation's highest vessel turnover rates and marina infrastructure density. The Florida Fish and Wildlife Conservation Commission administers vessel registration fees and boating safety education mandates that shape demand elasticity. Miami-Fort Lauderdale-West Palm Beach corridor concentrates dealership networks, yacht brokerage services, and marine propulsion system distributors serving both domestic and Caribbean export markets.
Texas
Gulf Coast second-home development and retiree migration into Corpus Christi and Galveston corridors drive whitespace expansion for dealership networks. Texas Parks and Wildlife Department manages waterway access permits and vessel titling protocols that influence ownership transaction costs. Houston-Galveston metropolitan cluster anchors fiberglass hull fabrication and aluminum fishing boat manufacturing for regional distribution.
California
Coastal mooring scarcity in high-density harbors constrains fleet expansion despite substantial household acquisition capacity. California Air Resources Board enforces marine engine emission standards that exceed federal EPA baselines and accelerate electric propulsion adoption timelines. San Diego-Los Angeles-Long Beach corridor hosts specialized yacht refit facilities and marine electronics integration services for Pacific cruising routes.
Michigan
Great Lakes seasonal contraction restricts annual utilization rates and dampens new vessel demand elasticity relative to Sun Belt comparators. Michigan Department of Natural Resources oversees watercraft registration and aquatic invasive species inspection programs at public launch facilities. Detroit-Muskegon-Grand Rapids triangle maintains legacy concentration in sterndrive engine manufacturing and fiberglass hull lamination for freshwater fishing configurations.
New York
Seasonal operation patterns and high slip costs in Long Island Sound and Hudson River corridors compress replacement cycle frequency. New York State Department of Motor Vehicles coordinates vessel registration with county-level property tax assessments on dockside improvements. Montauk-Newport coastal cluster sustains deep-draft sailboat and motor yacht brokerage activity serving Northeast seasonal cruising grounds.
US Recreational Boating Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with proprietary propulsion and hull technologies that determine downstream assembly economics. The vendor base organizes around three functional tiers: diversified marine conglomerates with integrated parts networks, specialized hull fabricators focused on discrete activity segments, and emerging electric propulsion entrants capitalizing on infrastructure subsidy windows. Strategic differentiation centers on backward integration into engine manufacturing, captive distribution through owned dealership networks, and portfolio diversification across boat type and price tier.
Among diversified platform operators, Brunswick Corporation and Yamaha Motor Corporation exemplify contrasting integration strategies. Brunswick anchors positioning through captive parts-and-accessories distribution and multi-brand hull portfolios spanning family cruising to performance watersport applications. Yamaha Motor Corporation represents vertical control over outboard engine manufacturing and proprietary marine propulsion system supply. Malibu Boats occupies a specialist position within performance tow boat architecture, exemplifying focused hull engineering for wake-shaping and watersport towing applications.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Yamaha Motor Corporation |
| Groupe Beneteau |
| Malibu Boats |
| MasterCraft |
| Marine Products Corporation |
| Polaris Inc |
| Azimut Benetti Group |
| White River Marine Group |
| Others |
Supply Flow & Price Mechanics
Marine-grade aluminum sheet and extrusion stock concentration in domestic smelter networks and Canadian primary metal flows directly determines margin capture for mid-market hull fabricators. Pricing power pools with vertically integrated builders commanding captive parts distribution, while commodity-exposed assemblers face compressed predictability.
Pricing Analysis
First-time family buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the US recreational boating market. Price differentiation separates Mercury Marine and Yamaha outboard configurations from entry-level powerplant alternatives, with brand premium and EPA certification tier as primary drivers. Cost compression in aluminum-intensive hull fabrication is intensifying because of commodity volatility and tariff exposure on Canadian metal imports. Charter fleet operators demonstrate lowest price sensitivity due to hourly-revenue model economics, while individual seasonal owners in Great Lakes corridors exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk architecture for marine-grade aluminum inputs. Hull fabrication draws from domestic fiberglass laminators, Mexican component assembly operations, and Chinese electronics integration specialists. Single-source vulnerability concentrates in lithium-ion battery cell supply for emerging electric propulsion configurations. Distribution runs through Brunswick's captive parts-and-accessories network, independent dealership channels, and direct-to-fleet procurement for boat club operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based access platforms and fractional ownership models present a substitution threat that traditional equity-sale incumbents must navigate through defensive portfolio repositioning.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into electric propulsion R&D and securing exclusive marina infrastructure partnerships in Florida and Texas Gulf Coast corridors. Captive control over certified service networks addresses the marine technician shortage that threatens customer retention. Priority investment in lithium-compatible hull platforms responds to EPA emissions compliance timelines compressing internal combustion powerplant viability. For New Entrants and Emerging Players: Electric-native day cruiser configurations for Texas second-home developments and Corpus Christi retiree migration corridors represent the most penetrable entry point against legacy internal combustion incumbents. Mid-market pontoon specifications with dockside charging compatibility target whitespace between premium yacht brokerage and economy fishing boat segments. Go-to-market execution through boat club fleet procurement channels bypasses fragmented individual buyer decision authority. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric propulsion platform development, favoring acquisition of specialist battery system integrators over greenfield R&D buildout. Long-term viability across the analysis window hinges on regulatory subsidy capture and charging infrastructure deployment pace. Target acquisition archetype: electric outboard technology holders with EPA certification pathway progress and compatible vessel portfolio partnerships. Signal to watch: Florida and California dockside electrification grant award velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Platform Development | EPA Clean Air Act Title II compliance deadlines are accelerating certified powerplant redesign investment requirements. |
| Marina Infrastructure Partnership | Dockside charging installation access in Florida and California harbors secures fleet operator procurement preference. |
| Fractional Ownership Platform Launch | Urban coastal consumers in Seattle and Miami increasingly prioritize hourly access over single-vessel equity positions. |
| Technician Certification Program Expansion | ASE-certified outboard specialist scarcity extends service wait times and erodes dealership network customer retention. |
| Aluminum Supply Agreement Restructuring | Commodity volatility in marine-grade sheet and extrusion stock compresses margin predictability for mid-market builders. |
Methodological Framework
A standing panel of marine propulsion engineers, dealership operations managers, marina infrastructure developers, and boat club fleet procurement directors provided ongoing calibration throughout this study. Primary interview findings triangulated against secondary validation from EPA certification filings, National Marine Manufacturers Association production surveys, US Coast Guard vessel registration databases, and state-level registration fee records. Bottom-up hull fabrication cost modeling and top-down consumer expenditure analysis converged on segment-level demand estimates.
Scenario-bracketing around EPA compliance timeline acceleration, electrification subsidy program expansion, and aluminum tariff regime shifts structured analytical framework development across the projection horizon. Segmentation dimensions modeled encompass boat type, ownership structure, usage frequency, and end-user activity profile alongside regional climate utilization patterns. CAGRs derived from replacement cycle frequency analysis, demographic migration flow projections, and propulsion technology adoption curve benchmarking. Industry-specific forecast inputs incorporated marina slip availability constraints and marine technician labor pool growth trajectories.
Practitioners should monitor EPA enforcement discretion on evaporative emission controls, lithium battery cell import tariff adjustments, and Great Lakes water level variability for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Motorhome Market