
 Hovercraft Market | 2026-2036
Hovercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Hovercraft Market Outlook
UK hovercraft manufacturing is broadening its export footprint across Baltic and North Sea littoral states. Textron Systems Corporation leverages its defense contracting scale to sustain long-term military procurement relationships. Griffon Hoverwork Ltd. anchors European supply through specialized amphibious platform engineering.
A hovercraft is an amphibious vehicle that rides on a cushion of pressurized air generated by integrated lift fans, typically operating with skirts of rubberized fabric or elastomeric composites to contain the air cushion and enable traversal of water, ice, mud, and flat terrain without hull contact. Military hovercraft command the largest installed base due to beach-assault and logistics requirements, while rescue hovercraft represent the fastest-growing product category as coastal emergency services replace conventional rigid-hull inflatable boats for shallow-water operations. Medium hovercraft dominate commercial procurement volumes, though heavy-duty platforms capture disproportionate margin pools in defense and Arctic transport applications.
FAA airworthiness standards for powered-lift vehicles and IMO High-Speed Craft Codes constrain design parameters and certification timelines for commercial entrants. The U.S. Coast Guard and UK's Maritime and Coastguard Agency enforce divergent operational safety regimes that fragment type-approval pathways. Stakeholders must monitor evolving amphibious vehicle classifications under emerging coastal-state regulatory harmonization initiatives.
Market Dynamics
Defense procurement cycles from the U.S. Department of Defense and NATO coast guard agencies anchor volume demand, while stricter IMO safety protocols for amphibious vessels reshape certification requirements across commercial entrants.
Growth Catalysts
- Defense procurement modernization:Beach-assault logistics requirements from the U.S. Department of Defense and NATO members sustain military platform demand through multi-year contracting frameworks.
- IMO High-Speed Craft Code adoption:Stricter international safety protocols for amphibious vessels are expanding addressable market scope for certified commercial operators in littoral zones.
- Arctic transport infrastructure gaps:Ice-capable logistics in northern latitudes without port infrastructure is pulling heavy-duty platform demand from resource extraction and remote community supply chains.
Market Restraints
- Specialized elastomeric composite input costs:Skirt fabric and seal materials face petrochemical price volatility that compresses margin predictability for hull manufacturers.
- UK manufacturing concentration:Production gravity centers on Griffon Hoverwork and British Hovercraft Company facilities, creating supply vulnerability from single-country sourcing.
- FAA powered-lift certification timelines:Airworthiness standards for commercial hovercraft extend development-to-revenue cycles beyond conventional marine vessel pathways.
Strategic Opportunities
- Baltic littoral state expansion:Estonia, Latvia, and Lithuania are upgrading coast guard amphibious fleets, opening export channels for UK and U.S. defense contractors.
- Rescue service platform replacement:Coastal emergency services are displacing rigid-hull inflatable boats with shallow-water hovercraft for mudflat and ice rescue operations.
- EU Green Deal maritime incentives:Low-draft vessels that minimize seabed disturbance qualify for preferential financing under sustainable coastal transport initiatives.
Industry Challenges
- Amphibious vehicle classification harmonization:Divergent type-approval pathways between the U.S. Coast Guard and UK's Maritime and Coastguard Agency fragment product development roadmaps.
- Integrated lift fan engineering scarcity:Aerodynamic propulsion system design talent concentrates in aerospace and marine defense clusters, constraining commercial platform innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hovercraft Market |
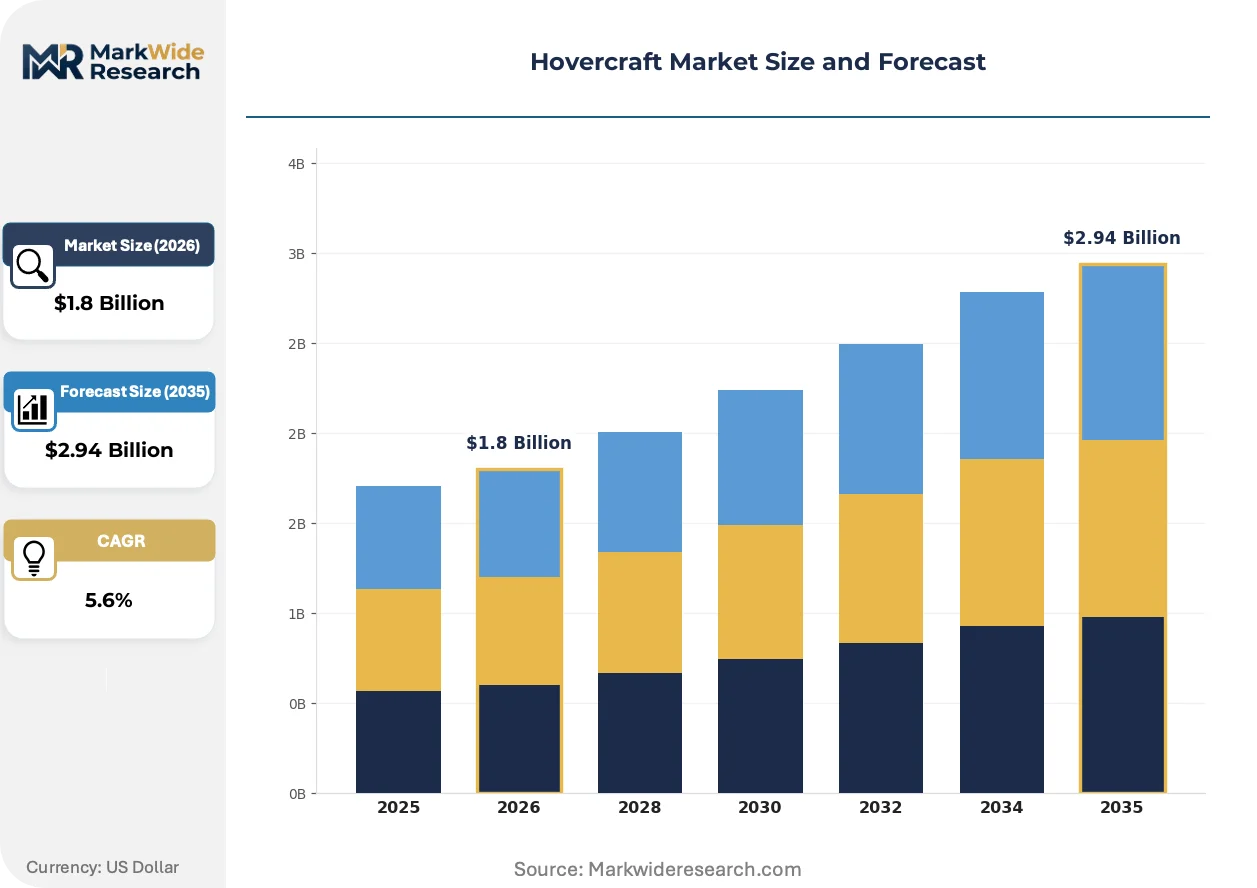
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Hovercraft, Commercial Hovercraft, Passenger Hovercraft, Rescue Hovercraft Application: Emergency Services, Tourism, Transport, Maritime Operations End User: Government Agencies, Private Operators, Research Institutions, Defense Organizations Size: Small Hovercraft, Medium Hovercraft, Large Hovercraft, Heavy-duty Hovercraft |
| Companies Covered | Textron Systems Corporation, Griffon Hoverwork Ltd., Neoteric Hovercraft Inc., The British Hovercraft Company Ltd., Airlift Hovercraft Pty Ltd., Christy Hovercraft, Universal Hovercraft of America Inc., AEROHOD Ltd., Hovertechnics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hovercraft Market Strategic Shifts
Hybrid-electric propulsion architectures and advanced skirt materials are compressing operating cost structures, while regulatory harmonization efforts attempt to streamline multi-jurisdictional certification pathways for amphibious operators.
Air-cushion skirt systems using reinforced elastomeric composites with embedded sensor arrays are converging with predictive maintenance platforms to reduce field failure rates. Arctic logistics operators and military procurement agencies are adopting these intelligent skirt systems fastest. The technology is converging with digital twin platforms to enable condition-based replacement scheduling rather than calendar-driven maintenance.
The IMO High-Speed Craft Code 2000 amendments are mandating enhanced structural fire protection and evacuation protocols for passenger-carrying amphibious vessels. Shipyards must redesign engine compartment layouts and fuel system routing to achieve type approval. Commercial ferry operators in the United Kingdom and Scandinavian littoral states are retrofitting existing fleets or deferring procurement until certified designs reach market.
Coast guard agencies are consolidating vendor relationships around platform-as-a-service contracting that bundles hull delivery with through-life support. Traditional spot-purchase procurement of bare hulls is contracting in favor of availability-based agreements. The United States and United Kingdom exhibit the most advanced contracting sophistication, with performance metrics tied to operational readiness rather than asset transfer.
Hovercraft Market Segmentation
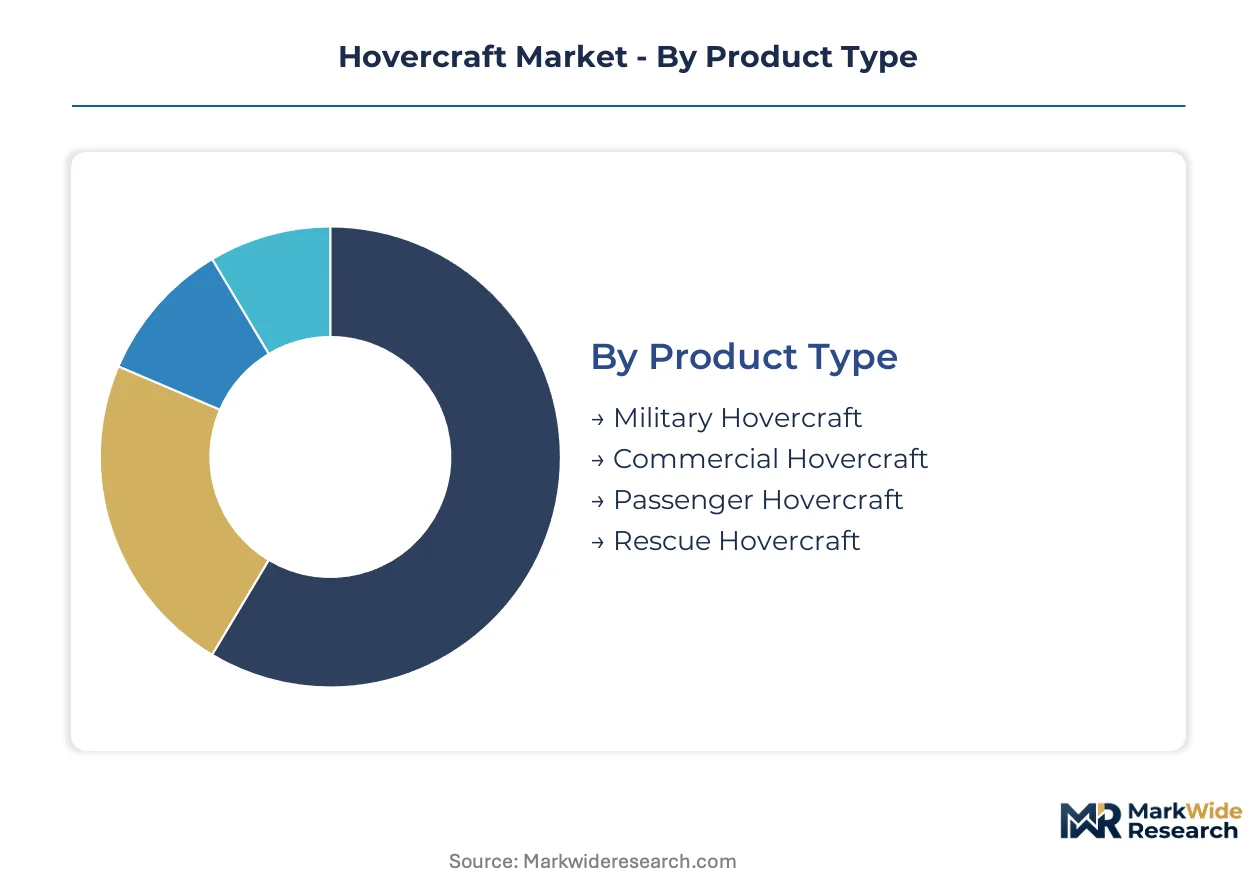
Hovercraft procurement decisions hinge on payload requirements, operating environment, and regulatory certification pathways. Platform specifications vary dramatically across defense logistics, coastal rescue, and commercial ferry applications, creating distinct buyer segments with non-overlapping technical priorities.
Product Type:
Buyers select hull configurations based on mission endurance requirements and amphibious terrain complexity.
- Military Hovercraft:These platforms integrate armor plating, ramp systems for vehicle discharge, and integrated lift fans rated for beach-assault operations. U.S. Department of Defense procurement through Textron Systems sustains volume demand for landing craft air cushion variants. Beach-ingress logistics requirements from NATO members anchor multi-year contracting frameworks.
- Rescue Hovercraft:Shallow-draft hulls with specialized skirt designs enable mudflat and ice rescue beyond conventional rigid-hull inflatable boat reach. UK Maritime and Coastguard Agency fleet modernization is displacing legacy vessels across littoral stations. Coastal emergency services in the United Kingdom and Scandinavian states are expanding procurement fastest.
- Commercial Hovercraft:Passenger-certified designs comply with IMO High-Speed Craft Code structural fire protection mandates. Ferry operators defer procurement pending certified design availability.
- Passenger Hovercraft:Short-haul amphibious ferry configurations serve cross-estuary and island-connecting routes with minimized seabed disturbance.
Military hovercraft leads on scale; rescue hovercraft leads on momentum.
Application:
Operating environment severity determines hull reinforcement specifications and skirt material grades.
- Maritime Operations:Coast guard patrol and customs enforcement missions require all-weather reliability and extended range. Baltic littoral states including Estonia, Latvia, and Lithuania are upgrading amphibious fleets. NATO coast guard agencies are consolidating vendor relationships around platform-as-a-service contracting.
- Emergency Services:Rapid deployment specifications prioritize lightweight construction and trailer transportability for road-based launch. UK coastal stations are replacing conventional boats with hovercraft for tidal flat access.
- Transport:Scheduled passenger services across estuaries and shallow waterways demand IMO-certified designs with enhanced evacuation protocols.
- Tourism:Sightseeing operations emphasize open-deck configurations and reduced noise signatures for passenger comfort.
Maritime operations leads on scale; emergency services leads on momentum.
End User:
Budget cycles and accountability structures shape procurement timing and contracting sophistication.
- Government Agencies:Civilian departments including coast guard and customs services operate under public procurement regulations with extended tender timelines. UK Maritime and Coastguard Agency specifications influence regional standard-setting.
- Defense Organizations:Military procurement through the U.S. Department of Defense and NATO frameworks sustains long-term production commitments. Multi-year availability-based agreements now dominate over spot hull purchases.
- Private Operators:Commercial ferry and tourism ventures face financing constraints pending IMO certification clarity for new-build designs.
- Research Institutions:Arctic and Antarctic logistics operators require ice-capable heavy-duty platforms for remote station resupply without port infrastructure.
Defense organizations leads on scale; government agencies leads on momentum.
Size:
Lift fan capacity and skirt perimeter scale directly with payload tonnage and operating range requirements.
- Medium Hovercraft:These platforms balance crew capacity with trailer transportability for rapid deployment across coastal stations. UK rescue services standardize on this tier for operational flexibility.
- Heavy-duty Hovercraft:Arctic logistics operators and resource extraction ventures demand ice-breaking hull reinforcement and extended fuel capacity. Northern latitude supply chains without port infrastructure pull demand from remote community resupply operations.
- Small Hovercraft:Single-pilot configurations serve recreational and limited commercial survey applications with minimal draft requirements.
- Large Hovercraft:Multi-vehicle ferry designs face certification delays under amended IMO structural fire protection protocols.
Medium hovercraft leads on scale; heavy-duty hovercraft leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hovercraft manufacturers face divergent certification costs between defense-heavy markets with established type-approval pathways and commercial zones where IMO compliance timelines extend revenue realization. Production investment flows toward jurisdictions with consolidated military procurement frameworks and aligned coast guard specifications.
United States
The U.S. Department of Defense sustains multi-year beach-assault logistics contracts through Textron Systems, anchoring heavy-duty platform demand. FAA powered-lift certification requirements constrain commercial entrants to extended development cycles. Gulf Coast shipyards in Louisiana and Mississippi service military overhaul requirements while East Coast facilities concentrate on Coast Guard patrol vessel modernization.
United Kingdom
Griffon Hoverwork and The British Hovercraft Company maintain manufacturing heritage on the Solent, supplying NATO coast guard agencies and domestic rescue services. The Maritime and Coastguard Agency's fleet specifications influence Baltic and North Sea littoral state procurement standards. Southampton-Portsmouth corridor engineering clusters specialize in amphibious platform skirt systems and integrated lift fan integration.
Estonia
Baltic Sea ice conditions and shallow archipelago geography drive coast guard amphibious fleet expansion. EU Green Deal maritime incentives qualify low-draft hovercraft for preferential coastal transport financing. Tallinn-based procurement offices coordinate tri-lateral Baltic upgrades with Latvia and Lithuania, opening export channels for UK defense contractors.
Canada
Arctic logistics operators demand ice-capable heavy-duty platforms for remote community resupply without port infrastructure. Transport Canada and the Canadian Coast Guard enforce divergent operational safety regimes from FAA standards, fragmenting type-approval for cross-border operators. Manitoba and Northern Ontario resource extraction ventures pull demand for extended-range cargo configurations.
Australia
Coastal emergency services in Queensland and Western Australia replace rigid-hull inflatable boats with shallow-water rescue hovercraft for mudflat operations. The Australian Maritime Safety Authority's certification pathway runs parallel to IMO High-Speed Craft Codes with localized environmental addendums. Perth and Brisbane marine clusters concentrate on commercial ferry retrofitting and tourism sightseeing configurations.
Hovercraft Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized rescue and Arctic logistics niches with differentiated skirt engineering. The vendor base clusters around defense contracting scale and heritage manufacturing concentration rather than broad commercial diversification. Three archetypes dominate: aerospace-defense conglomerates with multi-year government relationships, specialized amphibious engineering houses with type-approval expertise, and regional fabricators serving coast guard spot procurement. Competitive positioning hardens through platform-as-a-service contracting bundles and availability-based agreements that displace bare hull spot purchases.
Within the defense-contracting tier, Textron Systems Corporation anchors North American military procurement through multi-year U.S. Department of Defense frameworks. Griffon Hoverwork Ltd. and The British Hovercraft Company Ltd. represent the heritage-engineering archetype, occupying positions shaped by UK Maritime and Coastguard Agency specification-setting and NATO export relationships. Neoteric Hovercraft Inc. sits within the specialized-fabricator segment, exemplifying regional production concentration for coast guard and rescue service procurement.
| Leading Market Players |
|---|
| Textron Systems Corporation |
| Griffon Hoverwork Ltd. |
| Neoteric Hovercraft Inc. |
| The British Hovercraft Company Ltd. |
| Airlift Hovercraft Pty Ltd. |
| Christy Hovercraft |
| Universal Hovercraft of America Inc. |
| AEROHOD Ltd. |
| Hovertechnics |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal maritime incentives gate qualified supply and premium-tier pricing access for hovercraft manufacturers, as low-draft vessels that minimize seabed disturbance qualify for preferential financing under sustainable coastal transport initiatives. Defense procurement agencies and commercial ferry operators now demand certified platforms that meet these environmental thresholds, compressing margin pools for non-compliant fabricators while rewarding specialized engineering houses with type-approval expertise.
Pricing Analysis
Direct-to-defense contracting eliminates distributor margins for military platforms, while commercial procurement through coast guard agencies absorbs 12-18 point markups from specialized marine distributors. Three-tier pricing structure across premium, standard, and economy levels separates IMO-certified passenger designs from uncertified utility hulls and recreational configurations. Pricing pressure stems from petrochemical volatility in elastomeric skirt composites, which compresses margin predictability for hull manufacturers. Government agencies exhibit highest price sensitivity due to public procurement regulations, while Arctic logistics operators show lowest sensitivity given absence of port infrastructure alternatives.
Supply Chain Analysis
Dual-sourcing requirements from NATO defense procurement frameworks mandate multi-supplier qualification for critical skirt fabric and integrated lift fan assemblies. Manufacturing concentrates in the United Kingdom, the United States, and Estonia for final assembly, while elastomeric composite inputs draw from petrochemical suppliers in Germany and the Netherlands. Single-source vulnerability concentrates in specialized aerodynamic propulsion system design talent, which clusters in aerospace and marine defense hubs. Distribution runs through platform-as-a-service contracting bundles that displace bare hull spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hovercraft market represents a late-cycle quality story as coast guard agencies consolidate vendor relationships around availability-based agreements that reward operational readiness over asset transfer. Rescue service platform replacement cycles are pulling demand toward premium-certified specifications for shallow-water operations.
For Market Incumbents: Anchor multi-year contracting relationships with U.S. Department of Defense and NATO procurement frameworks through integrated lift fan engineering investments. Defend margin position by deepening backward integration into elastomeric composite skirt manufacturing, countering petrochemical price volatility that compresses predictability for hull fabricators.
For New Entrants and Emerging Players: Capture Baltic littoral state coast guard modernization programs in Estonia, Latvia, and Lithuania through specialized Arctic-capable platform engineering. Target emergency services procurement in Queensland and Western Australia where rigid-hull inflatable boat displacement creates white-space demand for shallow-water rescue configurations.
For Investors and Strategic Acquirers: Roll-up economics work for specialized amphibious engineering houses because IMO High-Speed Craft Code certification timelines create durable moats against commoditized competition. Monitor platform-as-a-service contracting penetration as the signal to watch for inflection toward recurring revenue models and away from spot hull purchases.
| Strategic Initiative | Industry Significance |
|---|---|
| IMO Certification Investment | Unlocks commercial ferry procurement deferred pending compliant design availability. |
| Skirt System Digital Twin Integration | Enables condition-based maintenance scheduling for UK Maritime and Coastguard Agency fleets. |
| Arctic Heavy-Duty Platform Development | Addresses Transport Canada ice-capable logistics requirements without port infrastructure. |
| Platform-as-a-Service Contracting | Aligns revenue with NATO availability-based agreements displacing bare hull purchases. |
| Hybrid-Electric Propulsion Architecture | Qualifies for EU Green Deal preferential financing in Scandinavian littoral states. |
Study Parameters
Coverage spans the United States, the United Kingdom, Estonia, Canada, and Australia, with primary inputs from each region combining interviews with coast guard procurement officers, amphibious platform engineers, defense contracting specialists, and maritime safety regulators. Secondary validation draws from IMO High-Speed Craft Code amendments, FAA powered-lift certification filings, U.S. Department of Defense procurement disclosures, and EU Green Deal maritime incentive documentation. Bottom-up platform shipment data triangulates against top-down defense budget allocation analysis.
Granularity-level modeling addresses product type, application, end user, and size dimensions across the projection horizon, with separate treatment of military, rescue, commercial, and passenger hull configurations. CAGRs derive from segment-level volume buildups calibrated to procurement cycle visibility from NATO multi-year frameworks and coast guard fleet modernization schedules. Forecast inputs incorporate elastomeric composite price indices and regulatory harmonization timeline assumptions.
Defense procurement cycle delays, IMO certification timeline extensions, and petrochemical input cost spikes are the dominant revision risks to volume and value projections. Deviation in NATO availability-based contracting adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Asia-Pacific Motor Home Market