
 Impact-Modified PCR Plastics for Automotive Interiors Market | 2026-2036
Impact-Modified PCR Plastics for Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Impact-Modified PCR Plastics for Automotive Interiors Market Insights
Tier-1 parts manufacturers are redrawing material specifications faster than interior trim shops, pressuring compounders to certify impact-modified PCR grades for dashboard panels and center consoles. BASF leverages its European compounding network to supply OEM-validated ABS blends with controlled melt flow indices. Dow anchors North American supply through proprietary compatibilizer technology that preserves Izod impact strength above 20 kJ/m² at PCR loadings exceeding 30 percent. Covestro differentiates via polycarbonate-based formulations targeting premium seat back applications where surface aesthetics must match virgin-grade benchmarks.
Impact-modified PCR plastics for automotive interiors comprise thermoplastic resins—primarily ABS blends, polypropylene, and polycarbonate—reinforced with elastomeric impact modifiers and filled with post-consumer recycled feedstock processed to specified particle size and contamination limits, delivering notched Izod impact resistance above 15 kJ/m² while meeting OEM fogging and odor requirements for cabin environments. Polypropylene dominates volume consumption across injection-molded door panels and roof liners due to its cost position and established recycling streams, though polycarbonate grades command margin pools in center consoles and armrests where heat resistance and surface finish justify premium positioning. Dashboard panels represent the fastest-growing application segment as OEMs pursue visible sustainability credentials in the primary occupant sightline.
The EU End-of-Life Vehicles Directive and REACH compliance obligations enforced by ECHA are tightening permissible substance limits and mandating recycled content disclosures for automotive interior materials sold in Europe. EPA guidelines under the Toxic Substances Control Act govern recycled feedstock approval for US automotive applications, while China's MIIT and SAMR administer GB standards for interior air quality that PCR compounds must satisfy. Stakeholders must monitor how diverging regional compliance timelines for recycled content mandates reshape qualification costs and supplier eligibility across manufacturing footprints.
Market Dynamics
OEM sustainability mandates are compressing qualification timelines for impact-modified PCR grades, forcing compounders to validate odor and fogging performance in parallel with mechanical property certification rather than sequentially.
Growth Catalysts
- EU End-of-Life Vehicles Directive:Binding recycled content thresholds for automotive plastics sold in Germany and France are pulling dashboard-grade ABS compounds through Tier-1 supplier qualification pipelines faster than historical replacement cycles.
- Polypropylene recycling infrastructure:Established mechanical recycling streams for door panel and roof liner feedstock are lowering input cost volatility versus virgin resin, enabling volume commitments from cost-sensitive interior trim shops.
- Premium cabin visibility:Center console and armrest applications where passengers directly contact surfaces are commanding validated PCR grades that demonstrate tactile equivalence to virgin polycarbonate, opening margin pools for certified compounders.
Market Restraints
- Post-consumer feedstock contamination:Inconsistent paint and adhesive residue in shredded automotive plastic waste streams requires additional washing and elutriation steps that add 15-25% to compounding costs versus virgin resin processing.
- Izod impact strength degradation:PCR loadings above 30% in ABS blends without compatibilizer modification fall below OEM specifications of 20 kJ/m² for dashboard substrate applications, limiting substitution rates in structural interior components.
- REACH substance restrictions:ECHA enforcement of SVHC disclosure obligations for recycled content creates documentation burdens that disqualify smaller compounders lacking in-house regulatory affairs capabilities from European OEM supply chains.
Strategic Opportunities
- Seat back structural foams:Polycarbonate-based PCR formulations with glass fiber reinforcement are penetrating premium electric vehicle platforms where reduced cabin weight supports range extension targets without sacrificing occupant protection.
- Closed-loop OEM takeback programs:Volkswagen and BMW pilot programs for end-of-life vehicle plastic recovery are creating captive feedstock streams that bypass commodity recycled resin markets entirely.
- Biomass-toughened compatibilizers:Dow and BASF R&D pipelines are integrating bio-based elastomeric modifiers that improve PCR dispersion while satisfying EU Green Deal carbon intensity benchmarks for scope 3 emissions reporting.
Industry Challenges
- Odor panel certification timelines:OEM fogging and VOC testing protocols require 12-18 month validation cycles that mismatch annual model year refresh schedules, forcing compounders to maintain parallel development tracks for multiple vehicle platforms simultaneously.
- Melt flow index variance:Batch-to-batch inconsistency in post-consumer polypropylene feedstock forces injection molders to requalify processing parameters, generating scrap rates of 8-12% during production ramp-up phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact-Modified PCR Plastics for Automotive Interiors Market |
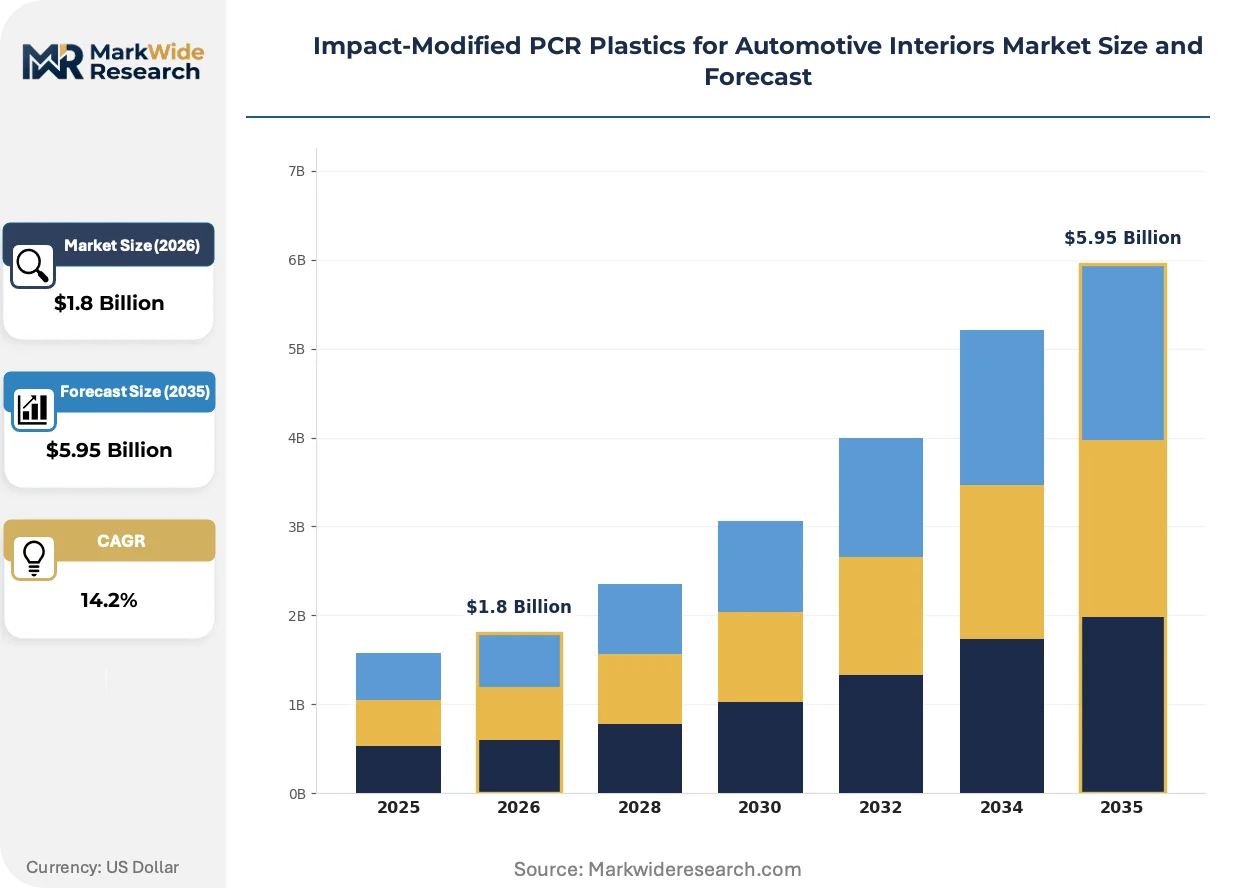
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS Blend, Polypropylene, Polycarbonate, Polystyrene, Acrylic, Nylon Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming, Compression Molding Application: Dashboard Panels, Door Panels, Center Consoles, Seat Backs, Roof Liners, Armrests End User: OEM Suppliers, Tier-1 Parts Manufacturers, Interior Trim Shops, Aftermarket Modifiers |
| Companies Covered | BASF, Dow, Covestro, Sabic, ExxonMobil, INEOS Styrolution, LyondellBasell, Avient, Novares, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact-Modified PCR Plastics for Automotive Interiors Market Trends and Innovations
Material science advances and regulatory disclosure requirements are converging to redefine how recycled content gets specified, tested, and priced across automotive interior supply tiers.
Reactive compatibilizer technology is decomposing the historical trade-off between PCR loading rates and impact resistance in ABS blends. Tier-1 suppliers in Germany are specifying grades with 40% post-consumer content for non-structural trim pieces, confident that maleic anhydride grafting chemistry preserves notched Izod values above 18 kJ/m². This is decomposing the premium pricing structure that previously separated virgin-grade from recycled-grade compounds, compressing margin pools for undifferentiated compounders.
REACH Article 33 disclosure obligations enforced by ECHA now mandate recycled content traceability down to the polymer batch level for automotive interior materials. Compounders must maintain chain-of-custody documentation linking specific shredded bumper or dashboard sources to finished pellet lots. Dashboard panel manufacturers face the steepest compliance costs, as these visible components attract regulatory scrutiny and consumer attention simultaneously.
Fleet procurement managers at leasing companies are inserting sustainability clauses into vehicle acquisition contracts that specify minimum recycled interior content percentages. This bypasses traditional OEM-Tier-1 negotiations and pushes specification authority downstream to operators with three- to four-year replacement cycles. The shift is most pronounced in Germany's corporate fleet market, where CO₂ reporting obligations under the CSRD extend to scope 3 emissions from leased assets.
Impact-Modified PCR Plastics for Automotive Interiors Market Segmentation
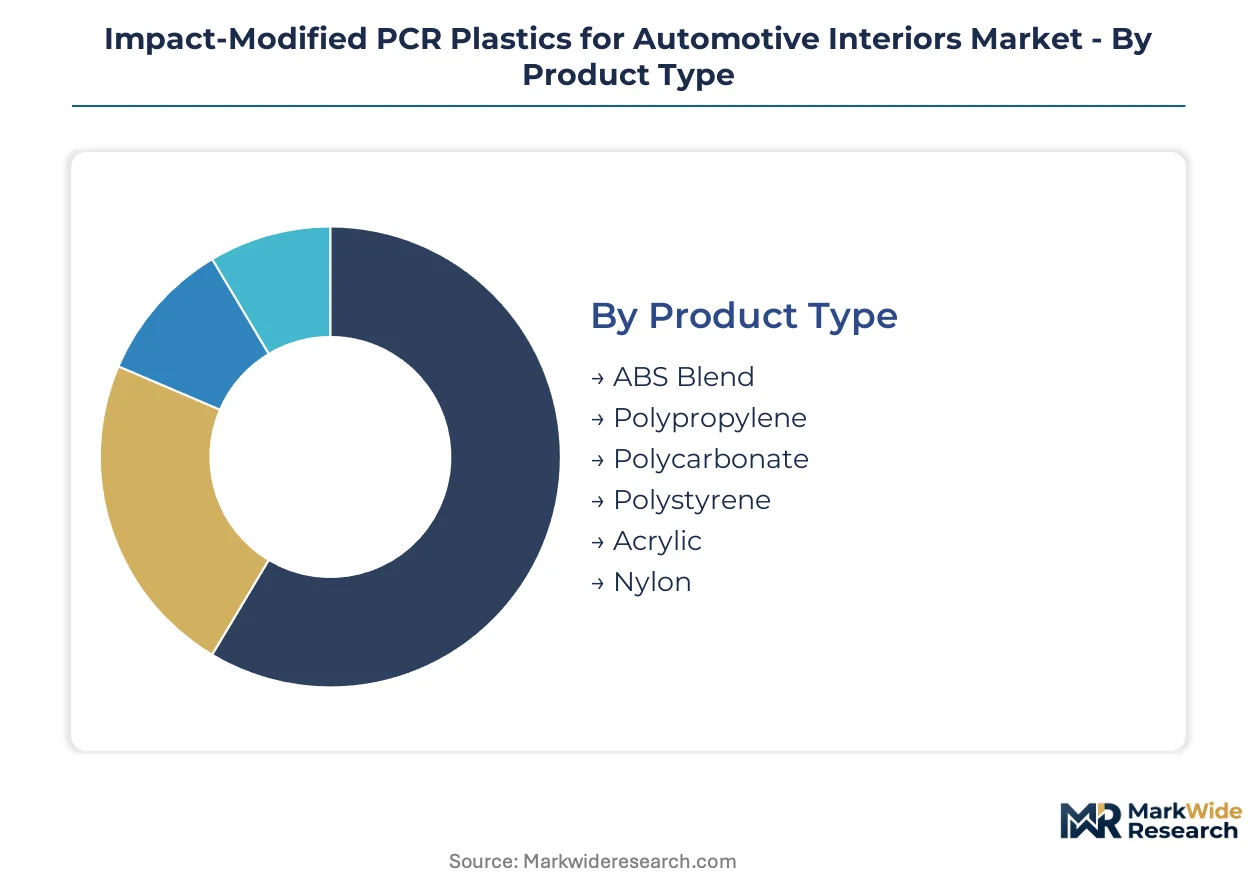
Impact-modified PCR plastics serve distinct performance tiers across automotive interior applications, with resin selection and processing technology determining qualification pathways for OEM supply chains. Specification divergence between structural and cosmetic components creates segmented demand pools that compounders must address through tailored formulation portfolios.
Product Type:
REACH Article 33 disclosure obligations enforced by ECHA create divergent compliance burdens across resin chemistries, with polycarbonate and ABS blends attracting the steepest traceability requirements due to their concentration in visible cabin components.
- ABS Blend:Elastomer-modified acrylonitrile-butadiene-styrene formulations deliver notched Izod impact resistance above 20 kJ/m² for dashboard substrates. Volkswagen and BMW suppliers in Germany are pulling certified grades through qualification pipelines fastest due to binding recycled content mandates under the EU End-of-Life Vehicles Directive.
- Polypropylene:Copolymer and homopolymer grades dominate volume consumption across door panels and roof liners, leveraging established mechanical recycling infrastructure that lowers feedstock cost volatility versus virgin resin. Injection molders in Germany's automotive corridor favor these grades for cost-sensitive applications where surface aesthetics are secondary to functional performance.
- Polycarbonate:High-clarity formulations command premium positioning in center consoles and armrests where tactile equivalence to virgin material is mandatory.
- Polystyrene:Lower-impact grades serve non-structural trim pieces with reduced mechanical requirements.
- Acrylic:Surface-capable grades target decorative applications requiring UV stability and gloss retention.
- Nylon:Glass-reinforced variants penetrate seat back structural applications demanding elevated heat resistance.
Polypropylene handles the majority of throughput; ABS Blend is expanding most quickly on share as dashboard visibility drives specification urgency.
Technology:
Processing method selection correlates directly with part geometry complexity and production scale, with injection molding commanding the broadest qualification across Tier-1 supplier networks.
- Injection Molding:Dominant process for dashboard panels and center consoles requiring tight dimensional tolerance and complex geometries. Melt flow index variance in post-consumer polypropylene feedstock forces molders to requalify parameters, generating scrap rates of 8-12% during production ramp-up phases.
- Extrusion:Primary method for continuous profile production in door panel substrates and roof liner sheets. Dow's proprietary compatibilizer technology preserves impact strength at PCR loadings exceeding 30 percent, enabling volume commitments for extruded components.
- Blow Molding:Hollow-part formation for ducting and conduit applications with moderate structural demands.
- Thermoforming:Sheet-based shaping for large-area trim components where material efficiency priorities dominate.
- Compression Molding:Batch processing for low-volume specialty parts and prototype validation.
Injection Molding captures the greatest equipment investment; Extrusion is climbing the fastest as sheet and profile applications multiply.
Application:
Passenger sightline visibility determines specification stringency, with primary occupant-facing components commanding the longest qualification timelines and highest certification costs.
- Dashboard Panels:Fastest-growing application segment as OEMs pursue visible sustainability credentials in the primary occupant sightline. Odor panel certification protocols require 12-18 month validation cycles that mismatch annual model year refresh schedules.
- Door Panels:High-volume consumption anchor supported by established polypropylene recycling streams and cost-efficient injection molding infrastructure. Interior trim shops in Germany's manufacturing corridor rely on these grades for fleet procurement contracts specifying minimum recycled content.
- Center Consoles:Premium surface applications where polycarbonate-based PCR formulations must demonstrate tactile equivalence to virgin material.
- Seat Backs:Structural foam applications in electric vehicle platforms where reduced cabin weight supports range extension targets.
- Roof Liners:Large-format components prioritizing acoustic dampening and material efficiency over surface finish.
- Armrests:High-touch surfaces requiring validated grades that satisfy OEM fogging and VOC requirements.
Door Panels anchor volume throughput; Dashboard Panels are gaining share fastest as sustainability visibility priorities intensify.
End User:
Supply tier position determines technical capability requirements and regulatory exposure, with OEM suppliers facing the most stringent chain-of-custody documentation obligations.
- OEM Suppliers:Direct manufacturer relationships require batch-level recycled content traceability under REACH Article 33. Volkswagen and BMW pilot programs for end-of-life vehicle plastic recovery are creating captive feedstock streams that bypass commodity recycled resin markets.
- Tier-1 Parts Manufacturers:Intermediate processors redrawing material specifications faster than interior trim shops, pressuring compounders to certify impact-modified PCR grades for dashboard panels and center consoles in parallel development tracks.
- Interior Trim Shops:Cost-sensitive processors favoring polypropylene grades with established recycling infrastructure and lower input cost volatility.
- Aftermarket Modifiers:Fragmented demand pool with reduced regulatory exposure and shorter qualification cycles.
Tier-1 Parts Manufacturers handle the majority of specification authority; OEM Suppliers are expanding their share fastest as direct procurement relationships consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals handle recycled polymer feedstock shipments that supply compounders across northern Germany's automotive corridor. Rail links connect these facilities to injection molding clusters in Wolfsburg, Stuttgart, and Munich, enabling just-in-time delivery of certified PCR grades to Volkswagen and BMW supplier networks.
Germany
Volkswagen's Zwickau electric vehicle plant sources dashboard-grade ABS compounds with validated PCR content for ID series production. The EU End-of-Life Vehicles Directive mandates minimum recycled content thresholds that Tier-1 suppliers in Lower Saxony must satisfy by 2027. BASF's Ludwigshafen compounding network supplies OEM-validated blends with controlled melt flow indices to Stuttgart's premium manufacturer ecosystem.
United States
Detroit's automotive manufacturing base consumes impact-modified polypropylene for door panel applications across Ford and General Motors supplier networks. EPA guidelines under the Toxic Substances Control Act govern recycled feedstock approval timelines that compounders must navigate for interior trim qualification. Dow's Midland, Michigan operations anchor North American supply through proprietary compatibilizer technology preserving impact strength at elevated PCR loadings.
China
SAIC Motor's Shanghai manufacturing complex specifies PCR-enhanced polycarbonate for center console applications in Roewe and MG electric vehicle lines. MIIT and SAMR administer GB standards for interior air quality that PCR compounds must satisfy before cabin installation approval. The Yangtze River Delta's injection molding cluster processes volume orders for domestic OEMs pursuing visible sustainability credentials in premium EV segments.
France
Renault's Flins facility integrates recycled-content polypropylene into Scenic E-Tech interior components under binding extended producer responsibility frameworks. ANSM and environmental regulators enforce substance disclosure obligations that compounders must document at the polymer batch level. The Auvergne-Rhône-Alpes region hosts compounders supplying Stellantis manufacturing sites with certified grades meeting REACH Article 33 traceability requirements.
Japan
Toyota's Tsutsumi plant evaluates polycarbonate-based PCR formulations for next-generation Prius center console applications. METI's carbon neutrality roadmaps pressure suppliers to demonstrate scope 3 emissions reductions through recycled content adoption. The Nagoya automotive corridor's Tier-1 network maintains parallel qualification tracks for multiple vehicle platforms to accommodate 12-18 month odor panel certification cycles.
Impact-Modified PCR Plastics for Automotive Interiors Market Competitive Landscape
Listed leaders compete with private specialists across formulation certification and OEM validation timelines. The supplier base concentrates around integrated petrochemical groups with captive compounding networks and independent compounders serving regional automotive clusters. Three archetypes dominate: diversified chemical conglomerates with European compounding infrastructure, North American resin producers leveraging compatibilizer technology, and specialty compounders focused on premium polycarbonate grades. Capacity expansion and strategic technology licensing represent the primary competitive moves as qualification pipelines compress.
Within the diversified chemical tier, BASF and Dow exemplify scale-driven positioning through established OEM validation relationships. Covestro occupies a distinct premium-tier position anchored in polycarbonate-based formulations. These three represent contrasting strategic postures: European network coverage, proprietary additive technology, and high-performance specialty grades respectively.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Covestro |
| Sabic |
| ExxonMobil |
| INEOS Styrolution |
| LyondellBasell |
| Avient |
| Novares |
| Others |
Pricing and Supply Chain Analysis
Post-consumer ABS feedstock displacing virgin resin in dashboard substrates simultaneously concentrates procurement leverage in Germany's automotive corridor and compresses margin pools for undifferentiated compounders lacking OEM validation relationships. The substitution dynamic reshapes supply geography toward captive recycling streams and forces pricing stratification across certification tiers.
Pricing Analysis
Volume-discount tiering structures separate OEM-validated grades from commodity recycled compounds. Pricing stratifies across premium, standard, and economy tiers based on REACH Article 33 traceability documentation and melt flow index consistency. Cost compression in standard-grade polypropylene is intensifying because established mechanical recycling infrastructure lowers input volatility. Fleet procurement managers demonstrate highest price sensitivity, while premium electric vehicle platforms absorb certification premiums for polycarbonate-based formulations.
Supply Chain Analysis
Inventory lead-times stretch 12-18 months for odor panel certification cycles that mismatch annual model year schedules. Supply concentrates in Germany, China, and the United States, with feedstock drawing from shredded automotive plastic waste streams and proprietary compatibilizer additives. Single-source vulnerability persists in maleic anhydride grafting chemistry for reactive compatibilizers. Distribution runs through Tier-1 supplier networks to OEM manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent compounders face substitution defense against bio-based interior materials and aluminum trim alternatives that threaten PCR plastic specification share in premium cabin applications.
For Market Incumbents: Compound certification capabilities across multiple OEM qualification pipelines simultaneously to compress validation timelines. Deepen backward integration into closed-loop takeback programs that bypass commodity recycled resin markets. BASF and Dow demonstrate how proprietary compatibilizer technology preserves specification authority against emerging entrants lacking R&D scale.
For New Entrants and Emerging Players: Differentiate on localized feedstock aggregation for regional automotive clusters underserved by integrated petrochemical groups. Target France's Auvergne-Rhône-Alpes manufacturing corridor where Stellantis suppliers seek qualified secondary sources. Pursue direct compounding partnerships with Tier-1 interior trim shops rather than OEM validation pathways.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compounders with validated REACH documentation and captive recycling infrastructure. Five-to-ten year viability hinges on scope 3 emissions reporting compliance under EU Green Deal frameworks. Monitor Volkswagen and BMW pilot program expansion as inflection signal for closed-loop feedstock economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captive feedstock streams bypass volatile commodity PCR markets and secure margin control. |
| Long-term Supply Agreement | Tier-1 suppliers lock volume commitments from compounders with validated odor panel certifications. |
| Joint Venture | OEM-compounder partnerships accelerate closed-loop end-of-life vehicle plastic recovery programs. |
| Green Manufacturing Transition | Bio-based elastomeric modifiers satisfy EU Green Deal carbon intensity benchmarks for scope 3 reporting. |
| Capacity Expansion | European compounding networks add Ludwigshafen and northern Germany lines to serve Volkswagen supplier demand. |
Research Methodology
The analysis maps ABS blend, polypropylene, and polycarbonate formulation tiers, each validated through compounder technical directors, Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distributor operations. Primary interviews with BASF, Dow, and Covestro R&D heads combined with secondary validation from ECHA substance restriction databases, EU End-of-Life Vehicles Directive filings, and automotive production registries. Bottom-up resin consumption estimates triangulated against top-down OEM sustainability target disclosures.
Consistency checks validated volume and value outputs against IHS Markit vehicle production data, ACC automotive plastics demand reports, and customs trade flows for recycled polymer feedstock. The projection horizon spans resin chemistry, application visibility tier, processing technology, and regional manufacturing cluster segmentation. CAGRs derived from regression analysis of historical substitution rates and regulatory mandate implementation timelines, incorporating electric vehicle platform ramp schedules and REACH compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated bio-based material substitution would require recalibration. Forecasts reflect assumptions about odor panel certification standardization and closed-loop feedstock scale economics. Specific risk factors include divergent regional compliance timelines and feedstock contamination variance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market