
 Motorized Quadricycle Market | 2026-2036
Motorized Quadricycle Market Size, Share, and Industry Trends Forecast 2026-2036
Motorized Quadricycle Market Analysis
Powertrain electrification is fragmenting the motorized quadricycle technology stack into distinct battery-electric, hybrid, and combustion-engine architectures. Renault Group leverages its European micro-mobility heritage to anchor production in France. Bajaj Auto Ltd. dominates cost-efficient gasoline quadricycle exports across emerging markets. Ligier Group specializes in premium electric variants for urban fleet operators seeking reduced operating costs.
A motorized quadricycle is a four-wheeled motor vehicle with unladen mass capped at 450 kg for electric variants or 550 kg for combustion-engine models, maximum design speed between 25 km/h and 90 km/h depending on classification, and primary commercial purpose spanning restricted-access urban transport, light commercial duty, and recreational mobility. Electric battery technology captures expanding margin pools as municipal zero-emission zones proliferate across European cities. Conventional engine segments retain volume leadership in price-sensitive South Asian and African markets where charging infrastructure remains sparse. Delivery services application channels are accelerating fastest as e-commerce logistics operators substitute quadricycles for full-size vans in dense urban cores.
The EU L6e-L7e framework administered by national type-approval authorities shapes product design specifications and market access across member states. France's national automotive regulator enforces stringent crash-safety standards that filter out low-cost imports. India's Automotive Research Association deploys CMVR rules that govern quadricycle construction and usage parameters for domestic manufacturers. Stakeholders must monitor how divergent speed-limit and safety-test regimes between European and Indian regulatory spheres affect platform standardization strategies and export economics.
Market Dynamics
The motorized quadricycle sector is undergoing a fundamental restructuring as battery-electric powertrains displace combustion architectures across European urban logistics fleets, compressing platform development cycles and forcing supplier recalibration toward electrified component ecosystems.
Growth Catalysts
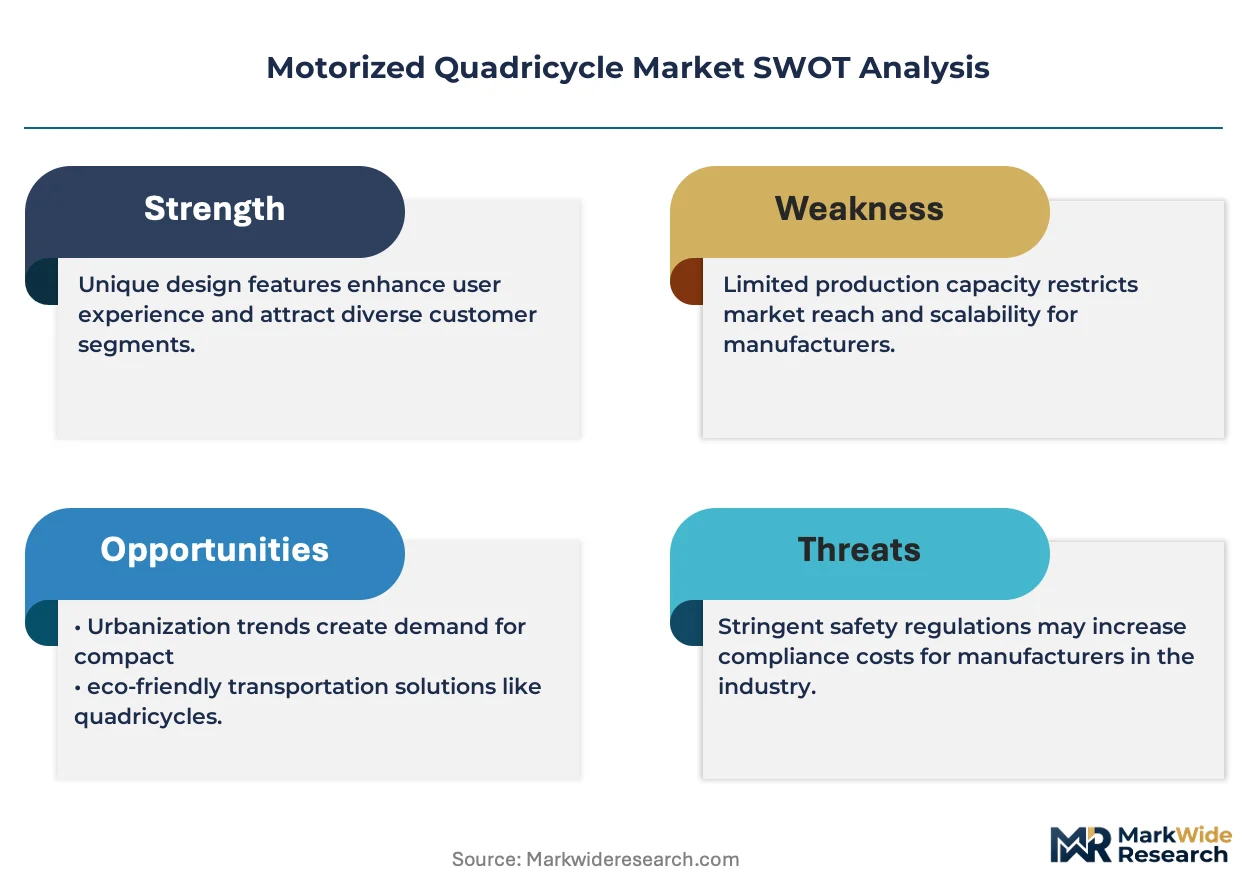
- EU L6e-L7e Classification:The European type-approval framework reduces homologation costs for lightweight four-wheelers, enabling faster market entry for electric variants targeting last-mile delivery operators in France, Italy, and Spain.
- Urban Zero-Emission Zones:Municipal mandates in Paris, Madrid, and Milan restrict internal combustion vehicle access to city centers, redirecting fleet procurement toward battery-electric quadricycles for parcel and food distribution services.
- Battery Cost Curves:Lithium-ion cell economics improve accessibility of electric powertrains for commercial buyers, narrowing total-cost-of-ownership gaps against gasoline alternatives in high-utilization delivery applications.
Market Restraints
- Lithium Supply Concentration:Raw material processing for battery cells clusters in Chinese refining capacity, exposing European assemblers to input volatility and geopolitical supply disruptions.
- Speed-Limit Divergence:India's CMVR rules cap quadricycle performance at 50 km/h, preventing platform standardization with EU L7e vehicles rated to 90 km/h and fragmenting engineering investments.
- Charging Infrastructure Gaps:Sparse public charging networks in African and South Asian markets preserve demand for gasoline quadricycles despite operating cost penalties.
Strategic Opportunities
- Cold-Chain Logistics:Refrigerated electric quadricycles address pharmaceutical and fresh-food delivery requirements in dense European urban cores where full-size vans face access restrictions.
- Subscription Fleet Models:Logistics-as-a-service platforms in Germany and the Netherlands bundle vehicle access, maintenance, and insurance, reducing capital barriers for small delivery operators.
- India's PLI Scheme:Production-linked incentives for advanced automotive technology attract battery and electric powertrain investments, positioning domestic manufacturing for cost-competitive export supply.
Industry Challenges
- Homologation Timeline Compression:Divergent crash-test protocols between France's national automotive regulator and Indian CMVR authorities extend certification cycles for multi-market platforms.
- Powertrain Integration Complexity:Battery thermal management and electric motor calibration demand skill sets scarce among traditional small-vehicle engineering teams in European manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorized Quadricycle Market |
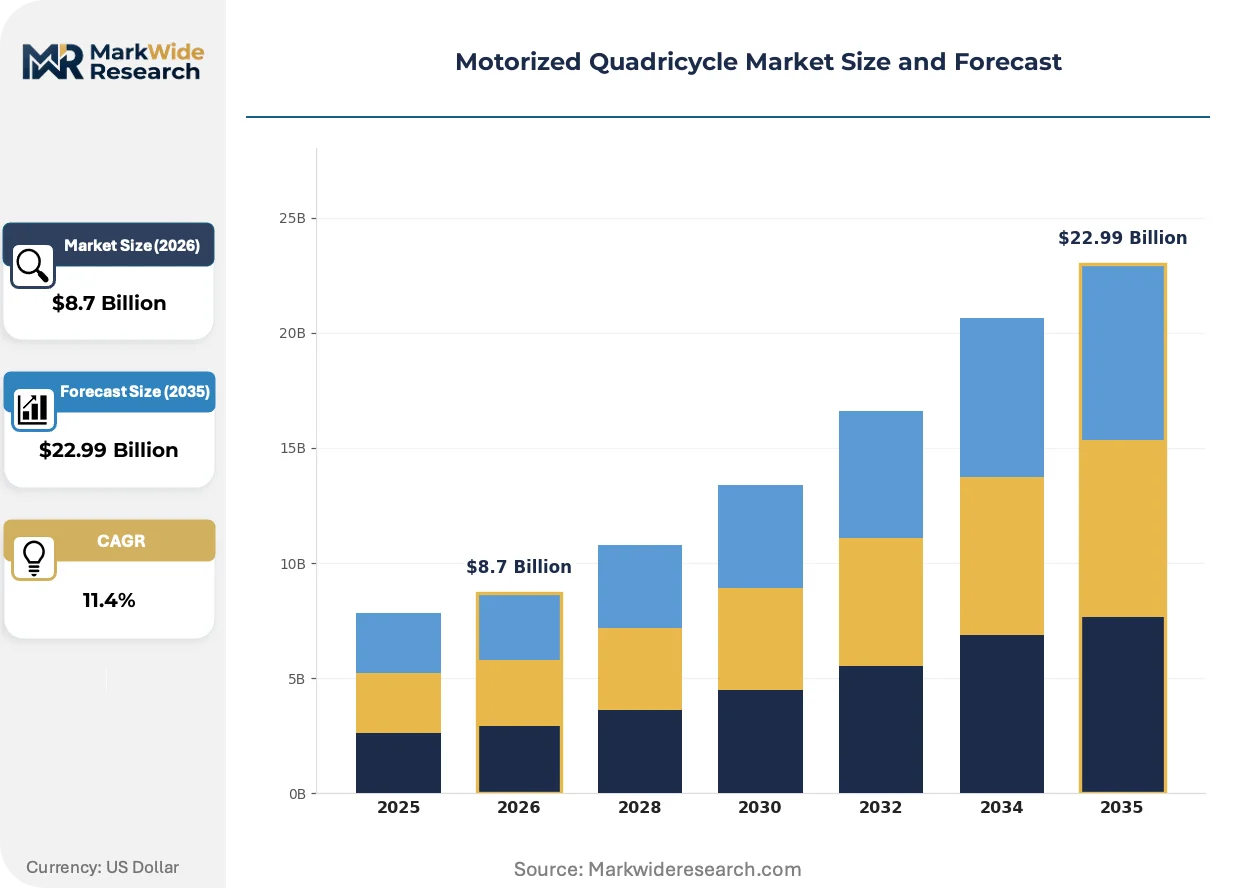
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Quadricycles, Gasoline Quadricycles, Hybrid Quadricycles, Off-Road Quadricycles End User: Recreational Users, Delivery Services, Emergency Services, Commercial Fleets Technology: Conventional Engine, Electric Battery, Hybrid Powertrain, Autonomous Features Application: Urban Transport, Leisure Activities, Waste Management, Military Use |
| Companies Covered | Renault Group, Polaris Inc., Bajaj Auto Ltd., Ligier Group, Aixam, Stellantis, Mahindra & Mahindra, Textron Inc., Micro Mobility Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorized Quadricycle Market Emerging Trajectories
Powertrain electrification is collapsing traditional technology boundaries in the motorized quadricycle sector, compressing development timelines and forcing convergence between automotive and consumer electronics supply chains.
Modular battery-swapping architectures are collapsing range-anxiety barriers for commercial fleet operators. Urban delivery services in Barcelona and Lyon adopt hot-swappable pack systems that eliminate dwell time at charging stations. This technology is collapsing the operational penalty that previously constrained electric quadricycle deployment against refuelable gasoline alternatives.
France's national automotive regulator enforces crash-safety standards exceeding baseline EU L6e-L7e requirements, filtering out low-cost import competition. Manufacturers targeting the French market must engineer reinforced passenger compartments and advanced restraint systems. Premium electric variants for fleet operators absorb these compliance costs through reduced operating expenditure claims.
Leasing structures displace outright purchase in European commercial channels. Small logistics operators in Milan and Amsterdam prefer bundled service contracts covering vehicles, maintenance, and energy costs. This shift concentrates fleet procurement decisions among platform aggregators rather than individual owner-drivers, altering manufacturer salesforce deployment and aftermarket revenue capture.
Motorized Quadricycle Market Segmentation
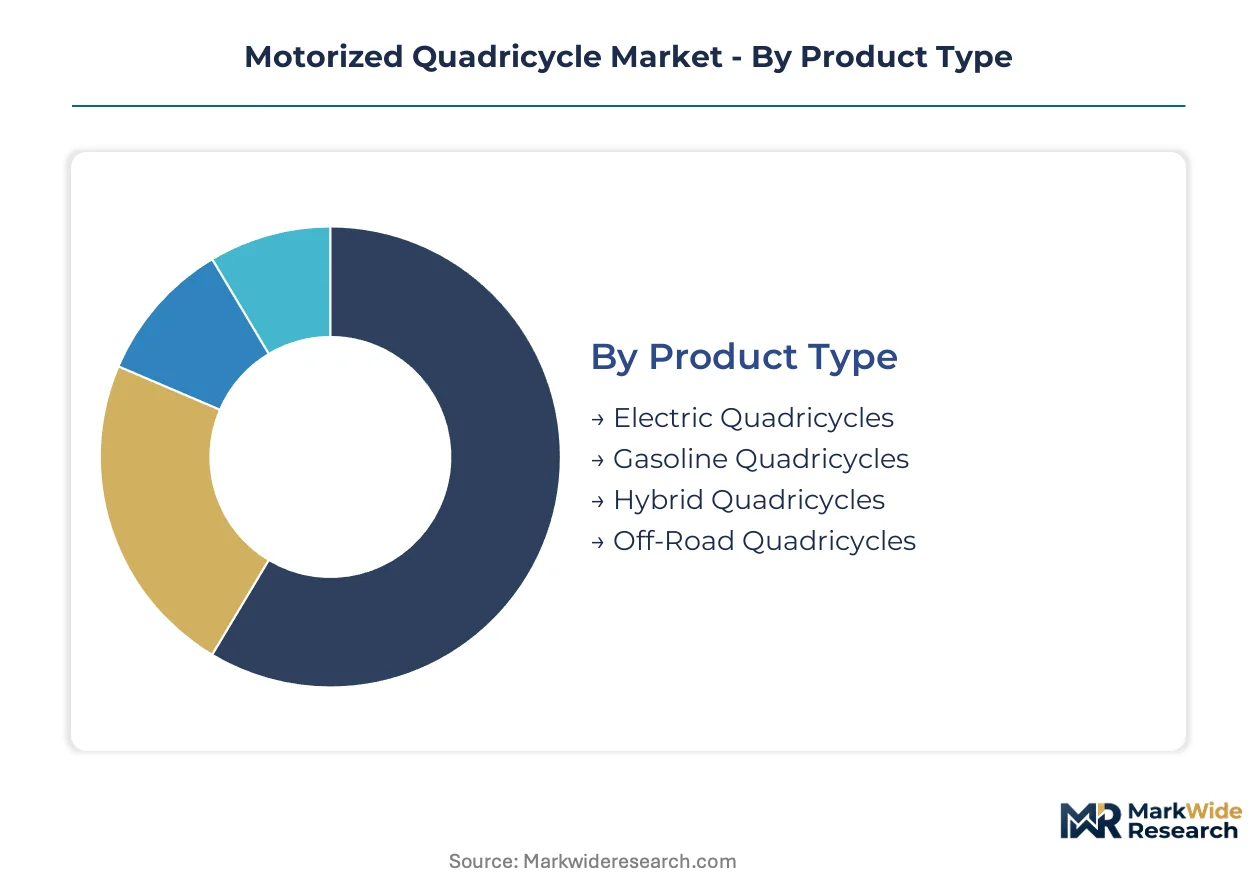
Segmentation in motorized quadricycles reveals how powertrain choices and use-case specialization drive divergent margin structures. Product type and end-user alignment determine whether manufacturers compete on acquisition cost or total-cost-of-ownership economics.
Product Type:
Mature combustion platforms coexist with emerging electric architectures, each commanding distinct customer bases and regulatory pathways.
- Electric Quadricycles:Battery-powered platforms with lithium-ion cell packs and regenerative braking systems. Demand concentrates in French and Spanish urban delivery fleets where municipal zero-emission zones restrict combustion access. Battery cost curves are narrowing ownership gaps against gasoline alternatives.
- Gasoline Quadricycles:Internal combustion engines optimized for low-displacement efficiency and minimal maintenance. Volume leadership persists in Indian and African markets where charging infrastructure remains sparse and fuel distribution networks dominate.
- Hybrid Quadricycles:Dual-mode powertrains combining small combustion engines with electric assist motors. Fleet operators in Italian cities value the operational flexibility during extended delivery routes.
- Off-Road Quadricycles:Reinforced suspension and higher ground clearance for unpaved terrain. Agricultural and recreational buyers in rural Spain and southern France drive niche procurement.
Gasoline quadricycles retain volume leadership; electric variants hold the steepest expansion curve.
End User:
Customer type segmentation separates capital-constrained individual buyers from fleet operators optimizing utilization rates.
- Recreational Users:Individual consumers purchasing for leisure mobility and tourism applications. Coastal regions in France and Italy sustain seasonal demand patterns.
- Delivery Services:Parcel, food, and pharmaceutical logistics operators replacing full-size vans in dense urban cores. Barcelona and Amsterdam fleets are standardizing on compact electric platforms for last-mile efficiency.
- Emergency Services:Municipal first responders requiring narrow-access vehicle capability. Parisian fire departments deploy specialized quadricycles for historic district navigation.
- Commercial Fleets:Corporate pool vehicles and facility management operators. German industrial campuses favor subscription-based procurement models.
Delivery services are climbing the fastest; recreational users anchor baseline demand stability.
Technology:
Technology segmentation tracks how electrification is fragmenting engineering competencies across supplier ecosystems.
- Conventional Engine:Carbureted or fuel-injected gasoline powertrains with mechanical transmission systems. Bajaj Auto's Indian manufacturing base exports cost-optimized units across South Asia and Africa.
- Electric Battery:Lithium-ion cell architectures with battery management systems and thermal regulation. Renault Group's French production clusters target EU L6e-L7e compliance.
- Hybrid Powertrain:Integrated motor-generator systems with dual-fuel capability. Limited deployment in Italian fleet trials.
- Autonomous Features:Sensor-equipped platforms with lane-keeping and collision-avoidance capabilities. Early-stage testing in Dutch logistics corridors.
Conventional engines dominate unit shipments; electric battery platforms gain share fastest.
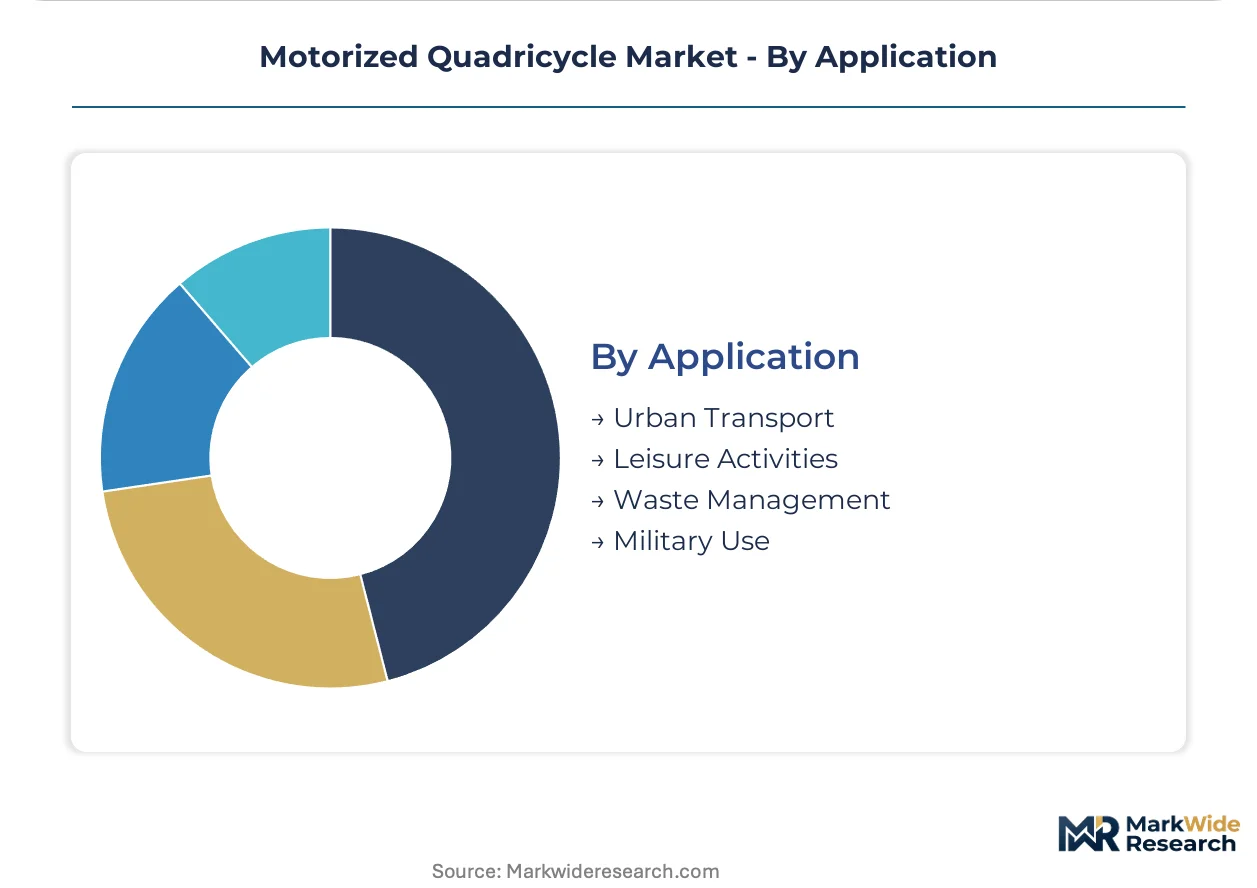
Application:
Application segmentation maps how vehicle specifications align with access restrictions and duty cycles.
- Urban Transport:Street-legal platforms for personal mobility and shared fleet services. Madrid's micro-mobility permits favor compact four-wheelers over two-wheeled alternatives.
- Leisure Activities:Tourism rental fleets and recreational trail access. French alpine regions sustain seasonal tourism procurement.
- Waste Management:Compact refuse collection in pedestrianized city centers. Milan's sanitation department trials electric variants for historic district coverage.
- Military Use:Light logistics and base transport for defense applications. Limited procurement through European defense procurement frameworks.
Urban transport commands the largest installed base; waste management applications show the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet buyers in France, Italy, and Spain drive European demand for low-speed electric quadricycles, while price-sensitive operators in India and South Asia sustain gasoline-powered procurement. Regulatory frameworks diverge sharply between EU L6e-L7e classifications and India's CMVR rules, fragmenting platform standardization.
France
Parisian delivery operators and municipal fleets anchor electric quadricycle adoption as the city tightens combustion-vehicle access restrictions. France's national automotive regulator enforces crash-safety standards exceeding baseline EU requirements, filtering import competition. Manufacturing clusters in Flins and Maubeuge concentrate Renault Group's electric micro-mobility production.
Italy
Milanese logistics providers and historic-district service operators procure compact electric platforms for last-mile efficiency. The Ministry of Infrastructure and Transport aligns national type-approval with EU L6e-L7e frameworks while permitting regional urban access restrictions. Industrial concentration in Piedmont sustains Ligier Group's premium electric variant assembly.
Spain
Barcelona's parcel and food delivery fleets standardize on battery-electric quadricycles for dense urban core operations. Municipal zero-emission zones in Madrid and Barcelona redirect procurement from gasoline alternatives. Manufacturing activity clusters in Catalonia and the Basque Country around component supply for European assemblers.
India
Cost-conscious commercial operators and rural mobility buyers sustain gasoline quadricycle volume leadership. The Automotive Research Association deploys CMVR rules capping vehicle speed at 50 km/h, preventing platform sharing with EU-rated models. Production concentrates in Maharashtra and Gujarat, with Bajaj Auto's Pune facilities exporting across South Asian and African markets.
Germany
Subscription-based fleet operators and industrial campus managers in Berlin and Hamburg favor bundled service contracts over outright purchase. The Kraftfahrt-Bundesamt administers EU-aligned type-approval while municipal authorities experiment with micro-mobility permits for compact four-wheelers. Logistics-as-a-service platforms in the Netherlands and Germany concentrate procurement decisions among aggregator networks.
Motorized Quadricycle Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement networks. The vendor base splits between European electric-platform developers and emerging-market gasoline specialists, with limited cross-regional overlap. Three archetypes dominate: integrated automotive groups with micro-mobility heritage, dedicated quadricycle specialists, and diversified two-wheeler manufacturers extending into four-wheeled products. Competitive moves concentrate on geographic expansion through distribution partnerships and powertrain diversification across electric and combustion architectures.
Within the integrated automotive tier, Renault Group and Stellantis occupy positions shaped by European electrification mandates and fleet-channel relationships. Among dedicated specialists, Ligier Group and Aixam exemplify premium-electric positioning for regulated urban markets. Bajaj Auto Ltd. represents the cost-optimized gasoline archetype, with manufacturing scale supporting emerging-market penetration where charging infrastructure remains undeveloped.
| Leading Market Players |
|---|
| Renault Group |
| Polaris Inc. |
| Bajaj Auto Ltd. |
| Ligier Group |
| Aixam |
| Stellantis |
| Mahindra & Mahindra |
| Textron Inc. |
| Micro Mobility Systems |
| Others |
Supply Flow & Price Mechanics
Underutilized battery cell capacity in Chinese refining clusters is pressuring European assemblers to renegotiate lithium supply contracts while compressing margins on electric quadricycle platforms destined for French and Spanish fleet operators.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium carbonate benchmarks dominate procurement between European OEMs and Asian cell suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Renault Group's fleet-optimized L7e variants from Ligier's premium electric offerings and Bajaj Auto's gasoline-powered economy exports. Cost compression in the economy tier is intensifying because Indian CMVR compliance costs are rising while African buyers resist price increases. Delivery services in Barcelona and Milan show the least price sensitivity due to total-cost-of-ownership advantages in high-utilization routes.
Supply Chain Analysis
Upstream feedstock concentration in Chilean lithium brine operations, Australian spodumene mines, and Chinese cathode processing facilities creates dependency bottlenecks for European electric quadricycle assemblers. Battery management systems and thermal regulation components draw from South Korean and Japanese electronics suppliers. Single-source vulnerability in Chinese lithium hydroxide refining exposes production schedules to geopolitical disruption. Distribution runs through Renault Group's Flins assembly hub for Western European fleet channels and Bajaj Auto's Pune export corridors for South Asian and African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This motorized quadricycle market functions as a defensive-moat story where regulatory entrenchment through EU L6e-L7e homologation creates durable barriers against low-cost import competition.
For Market Incumbents: Build certification moats by exceeding baseline EU crash-safety standards enforced by France's national automotive regulator. Secure backward integration into battery pack assembly near Maubeuge to reduce exposure to Chinese lithium volatility. Channel control through subscription fleet partnerships in Germany and the Netherlands limits price discovery for emerging entrants. For New Entrants and Emerging Players: Cold-chain logistics configurations for pharmaceutical delivery in dense European urban cores represent the most penetrable entry point where incumbent coverage remains thin. India's PLI scheme for advanced automotive technology offers manufacturing cost advantages for export-oriented electric platforms. Go-to-market execution through logistics-as-a-service aggregators in Amsterdam and Berlin bypasses direct competition with established OEM salesforces. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet subscription operators bundling vehicles, maintenance, and energy costs. Long-term viability across the projection horizon favors acquisition targets with proven EU type-approval track records and established relationships with municipal procurement authorities in Paris, Madrid, and Milan. Battery-swapping infrastructure deployment rates in Barcelona and Lyon signal platform scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with Korean cell manufacturers secure lithium-ion capacity for L7e platform ramp. |
| Platform Standardization | Modular architectures spanning EU L6e-L7e classifications reduce homologation costs across multiple speed-rated variants. |
| Charging Infrastructure Partnership | Collaboration with municipal authorities in Paris and Madrid accelerates fleet deployment in zero-emission zones. |
| Geographic Manufacturing Footprint | Production placement in Maharashtra leverages India's PLI incentives for cost-competitive export supply. |
| Software-Defined Vehicle Investment | Over-the-air update capability for battery management systems extends platform lifecycle in commercial fleet applications. |
Methodological Framework
A standing panel of fleet procurement managers at European logistics operators, homologation engineers at national type-approval authorities, lithium supply contract negotiators, and aftermarket service directors provided ongoing calibration. Primary interviews combined with secondary validation against EU vehicle registration databases, IHS Markit production data, and national automotive regulator filing records. Bottom-up triangulation across segment-level demand estimates and top-down reconciliation with macroeconomic indicators anchored volume projections.
Scenario-bracketing around battery cost curve trajectories and regulatory enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include powertrain architecture, end-use application, vehicle speed classification, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating fleet replacement cycles, municipal zero-emission zone expansion schedules, and charging infrastructure buildout assumptions. Industry-specific inputs encompassed lithium carbonate price volatility bands and EU L6e-L7e homologation timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in euro-zone industrial activity indices and Chinese export policy stance would shift the trajectory. Forecasts reflect documented assumptions regarding battery chemistry cost reductions and municipal access restriction enforcement. Cross-checking against European Alternative Fuels Observatory deployment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Segway Market
Recreational Vehicles
RV Leisure Battery Market