
 Electric Van Market | 2026-2036
Electric Van Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Van Market Intelligence
Modular vehicle platforms that bundle scalable battery packs with configurable cargo bays is hardening buyer preferences for adaptable commercial fleets. Ford leverages its established commercial vehicle dominance to electrify its Transit line. Renault differentiates with a focus on compact, city-centric electric vans for European markets. Meanwhile, BYD competes on battery technology and integrated supply chains to expand its global footprint from its base in China.
An electric van is a commercial vehicle propelled by one or more electric motors, drawing energy from a rechargeable battery pack, typically with capacities ranging from 40 kWh to over 100 kWh. These vehicles are designed for transporting goods or passengers, primarily for commercial operations within urban and last-mile logistics networks. The Last Mile Delivery application segment commands the largest share, driven by e-commerce growth. While Lithium-ion is the prevailing Battery Technology, research into Solid State batteries aims to address range and charging limitations.
Regulatory frameworks like the EU Green Deal and emissions standards set by the US EPA are compelling fleet operators to decarbonize. In parallel, China's dual carbon goals provide significant state-level support and mandates for commercial EV adoption. Stakeholder success now depends on accurately modeling total cost of ownership and securing access to scalable charging infrastructure.
Market Dynamics
The central dynamic shaping the electric van market is the direct tension between stringent government decarbonization mandates, such as the EU Green Deal, and the practical constraints of deploying scalable, high-speed charging infrastructure for commercial operations.
Growth Catalysts
- Regulatory Mandates:Policies like the EU Green Deal and China's dual carbon goals are compelling fleet operators to transition from internal combustion engines, creating guaranteed demand.
- Battery Technology Advancement:Continuous improvements in Lithium-ion battery energy density and cost reduction per kWh expand vehicle range and payload capacity, addressing key operational barriers.
- E-Commerce Expansion:Sustained growth in online retail drives demand for last-mile delivery, a segment where electric vans offer a clear operational advantage.
Market Restraints
- High Upfront Investment:The initial purchase price of an electric van and depot charging infrastructure remains a significant barrier for small and medium-sized enterprises.
- Charging Infrastructure Gaps:Insufficient public fast-charging for commercial vehicles creates operational risks, limiting routes and increasing vehicle downtime.
- Battery Mineral Dependency:Supply chains for raw materials like lithium are geographically concentrated, exposing manufacturers to price volatility and geopolitical risk.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Services:Enabling fleets to sell power back to the grid creates new revenue streams for operators and supports grid stability.
- Emerging Market Penetration:Urbanizing regions in Southeast Asia and Latin America present white space for adoption as e-commerce networks mature.
- Solid State Battery Integration:Future solid state batteries promise to solve range and charging limitations, unlocking a new performance tier for commercial EVs.
Industry Challenges
- Specialized Technician Shortage:A deficit of mechanics trained in high-voltage systems complicates maintenance and increases vehicle downtime, impacting fleet operational efficiency.
- Software Integration Complexity:Integrating EV fleet management software with existing logistics and ERP systems presents a significant IT challenge for many operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Van Market |
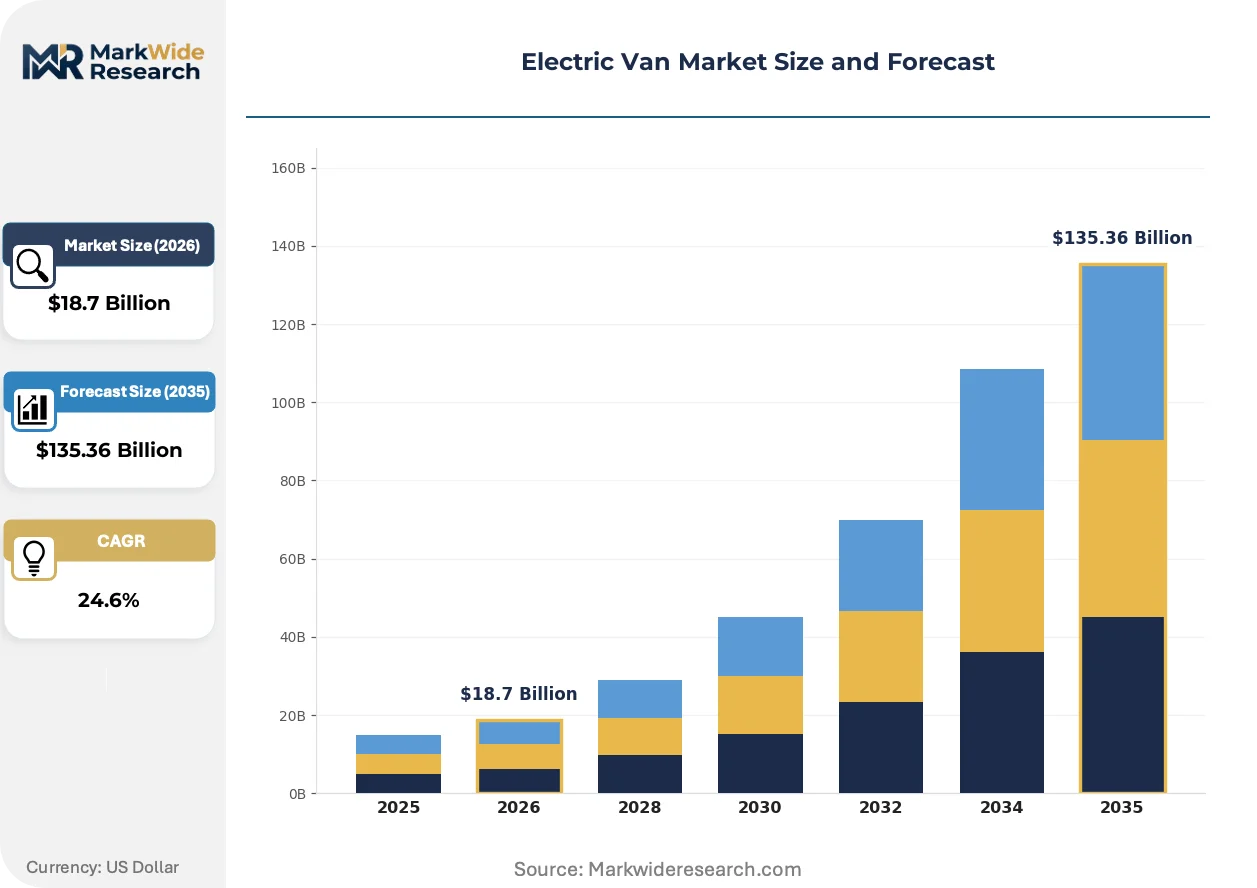
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Commercial, Medium Duty, Heavy Duty, Passenger, Cargo Battery Technology: Lithium-ion, Solid State, Lead Acid, Nickel-Metal Hydride, Zinc-Air Application: Last Mile Delivery, Logistics, Shuttle Services, Mobile Workshops, Courier Services End User: Fleet Operators, Delivery Companies, Service Providers, Vehicle Leasing Firms |
| Companies Covered | Opel, Vauxhall, Ford, Nissan, Geely, Mercedes-Benz, Renault, BYD, Kia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Van Market Strategic Shifts & Innovations
Integration of modular vehicle engineering with data-centric fleet management software is fundamentally altering the value proposition of commercial vehicles. This shift moves the focus from hardware sales to integrated, service-based mobility solutions for logistics operators.
Modular vehicle platforms, or "skateboards," combine scalable battery packs with integrated electric drive units. Commercial fleet operators are quickly adopting these architectures for their inherent design flexibility across different cargo and vocational applications. This trend is consolidating vehicle development around a few core platforms, compressing time-to-market for new specialized van models.
The US Environmental Protection Agency's (EPA) stringent emissions standards for commercial vehicles impose significant financial disincentives for operating older, diesel-powered fleets. This regulatory pressure directly accelerates the procurement cycle for zero-emission alternatives. Last-mile delivery and municipal service fleets are responding by prioritizing electric van acquisitions to meet compliance deadlines and avoid penalties.
Buyer evaluation is shifting from focusing on upfront vehicle purchase price to relying on sophisticated Total Cost of Ownership (TCO) models. This change displaces transactional sales with consultative approaches that bundle the vehicle with energy, charging, and maintenance services. The TCO-driven procurement pattern is most visible among large logistics firms in North America and Europe.
Electric Van Market Segmentation
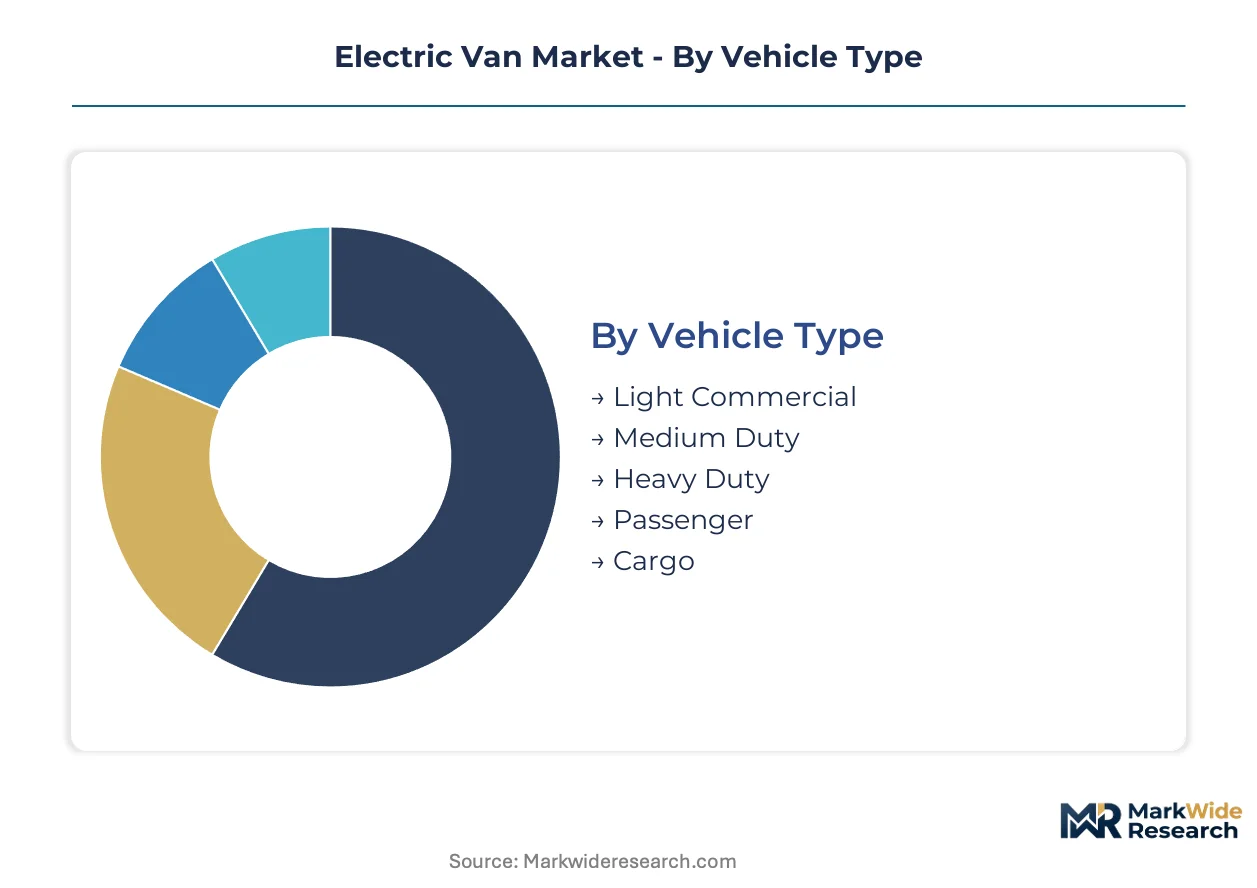
Understanding the distinct segments within the electric van market is essential for stakeholders to align product development and market strategies. This segmentation highlights the diverse operational requirements and technological preferences driving purchasing decisions across various commercial applications.
Vehicle Type:
The technical specifications and load-carrying capabilities of electric vans define their suitability for specific commercial tasks.
- Light Commercial:These vehicles typically have a gross vehicle weight rating (GVWR) under 3.5 tons, designed for urban deliveries and smaller payloads. Demand for light commercial electric vans is concentrating in European cities due to stringent emissions zones and last-mile delivery growth.
- Cargo:Built with dedicated cargo space and often higher payload capacities, these vans primarily transport goods rather than passengers. This type sees significant demand from e-commerce fulfillment centers in China, driven by national policies supporting EV adoption.
- Medium Duty:Electric vans in this category range from 3.5 to 7.5 tons GVWR, offering increased payload and range for regional distribution.
- Heavy Duty:These larger electric vans exceed 7.5 tons GVWR, serving more demanding logistics operations and specialized vocational applications.
- Passenger:Configured for transporting people, these electric vans are utilized for shuttle services, ride-sharing, and corporate transport.
Light Commercial leads on scale; Cargo leads on momentum.
Battery Technology:
Performance characteristics and energy storage density are key differentiators influencing battery technology choices for electric vans.
- Lithium-ion:This prevailing battery chemistry offers high energy density and a long cycle life, supporting typical electric van ranges of 40 kWh to over 100 kWh. Global logistics firms in North America prioritize Lithium-ion for its proven reliability and energy efficiency.
- Solid State:This emerging technology promises higher energy density, faster charging times, and enhanced safety, addressing current range and charging limitations. Research into Solid State batteries is attracting significant investment from automotive manufacturers in Japan and Germany.
- Lead Acid:Primarily used in ancillary systems or for very short-range, low-power applications due to lower energy density and shorter lifespan.
- Nickel-Metal Hydride:Offers a balance of energy density and cost, but generally superseded by Lithium-ion for primary propulsion in new electric van designs.
- Zinc-Air:A battery type with high theoretical energy density, but currently facing challenges in practical commercialization for vehicle applications.
Lithium-ion dominates current deployments; Solid State batteries are positioned for future disruption.
Application:
Operational requirements and delivery patterns dictate the specific applications where electric vans demonstrate optimal value.
- Last Mile Delivery:This segment involves the final leg of goods transportation from a hub to the customer, often in urban areas. The growth of e-commerce directly drives demand for electric vans in last-mile delivery networks across the United States.
- Logistics:Encompasses broader freight movement and supply chain operations, including hub-to-hub transfers and regional distribution. Large logistics firms in Europe are integrating electric vans to meet decarbonization targets.
- Shuttle Services:Involves transporting passengers on fixed routes or on-demand, commonly for airports, hotels, or corporate campuses.
- Mobile Workshops:Electric vans equipped with tools and equipment for on-site service and maintenance professionals.
- Courier Services:Focused on time-sensitive parcel and document delivery, often within dense urban environments.
Last Mile Delivery commands the largest share; Logistics is expanding its operational scope.
End User:
The organizational structure and scale of operations define the purchasing power and fleet management needs of various end-user groups.
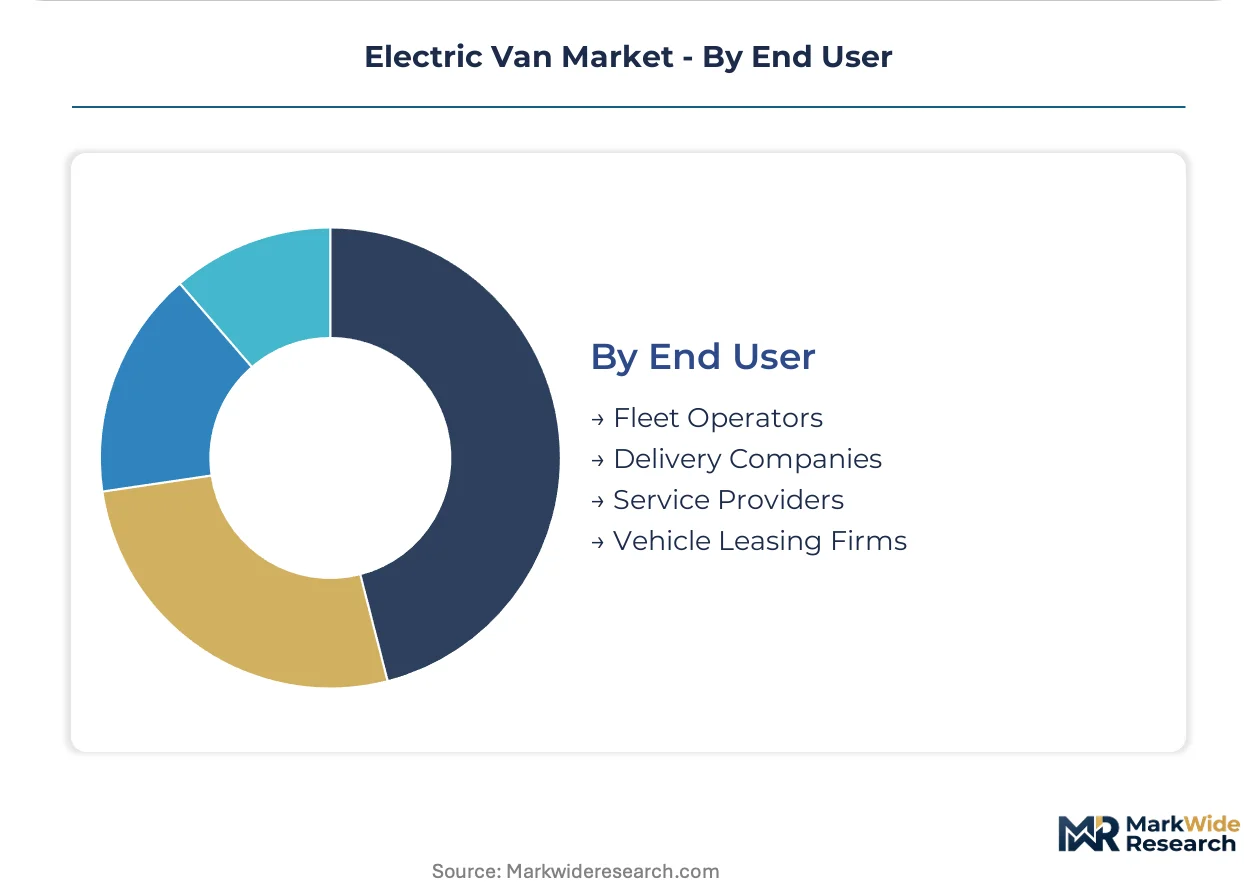
- Fleet Operators:Companies managing a large number of vehicles for various commercial purposes, prioritizing total cost of ownership and operational efficiency. Large fleet operators in Germany are adopting electric vans to comply with EU Green Deal mandates.
- Delivery Companies:Businesses specifically focused on package and goods delivery, seeking reliable vehicles for high-frequency routes. Major delivery companies in the United Kingdom are electrifying their fleets to reduce emissions in urban centers.
- Service Providers:Organizations offering specialized services, such as plumbing, electrical work, or telecommunications, utilizing vans as mobile workstations.
- Vehicle Leasing Firms:Companies that lease commercial vehicles to other businesses, offering flexible fleet solutions without upfront capital expenditure.
Fleet Operators represent the largest purchasing volume; Delivery Companies show the most consistent acquisition patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric van market first scaled significantly in regions prioritizing urban logistics electrification. Early adoption was driven by stringent emissions regulations and expanding e-commerce demand. These foundational developments shaped global manufacturing and deployment strategies for commercial electric vehicles.
China
E-commerce growth in China fuels robust demand for electric vans, particularly for urban delivery and last-mile logistics. China's dual carbon goals provide significant state-level support and mandates for commercial EV adoption. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta actively produce electric vans for domestic and export markets, consolidating supply.
Germany
German fleet operators are adopting electric vans to meet stringent decarbonization targets and enhance operational efficiency. The EU Green Deal and national incentives compel a rapid transition from internal combustion engines across commercial fleets. Large logistics firms in North Rhine-Westphalia and Bavaria are actively integrating electric vans into their last-mile delivery networks.
United States
American e-commerce expansion drives significant demand for electric vans, particularly for last-mile delivery within urban centers. The US EPA's stringent emissions standards accelerate procurement cycles for zero-emission alternatives across various fleet types. California leads in electric van adoption, supported by state incentives and the development of scalable charging infrastructure.
France
French cities are increasingly adopting electric vans for urban deliveries, driven by stringent emissions zones and evolving consumer preferences. The EU Green Deal provides a strong regulatory impetus for fleet conversion within France, impacting both public and private operators. Renault differentiates its compact, city-centric electric vans for European markets from its manufacturing base, serving dense urban environments.
Electric Van Market Key Industry Players
Premium-margin players sit above commodity-margin players across the electric van market, differentiated by technological sophistication and brand reputation. The market exhibits a tiered structure, with established automotive OEMs competing with specialized EV startups. Strategic archetypes include traditional vehicle manufacturers electrifying existing lines, pure-play EV innovators, and integrated battery-to-vehicle producers. Companies pursue strategic partnerships for charging infrastructure and engage in vertical integration to secure critical battery mineral supply chains.
Within the established automotive OEM archetype, Ford leverages its extensive commercial vehicle dominance to electrify its Transit line, catering to diverse commercial needs with scalable platforms. Renault differentiates its offerings with a strategic focus on compact, city-centric electric vans, specifically designed for European markets and optimized for dense urban logistics. Meanwhile, BYD represents the integrated battery-to-vehicle producer archetype, expanding its global footprint from its base in China by controlling its entire supply chain and advanced battery technology.
| Leading Market Players |
|---|
| Opel |
| Vauxhall |
| Ford |
| Nissan |
| Geely |
| Mercedes-Benz |
| Renault |
| BYD |
| Kia |
Cost & Logistics Intelligence
Lithium-ion battery cost reduction fundamentally reshapes the electric van market's cost economics and supply concentration. This transition drives down vehicle prices while intensifying reliance on specific raw material supply chains.
Pricing Analysis
A hybrid pricing model, combining transactional vehicle sales with service subscriptions, dominates the electric van market. Price differentiation stems from comprehensive Total Cost of Ownership (TCO) models, after-sales service bundles, and OEM brand reputation. Pricing pressure stems from intense competition among established automotive OEMs and pure-play EV innovators. Small and medium-sized enterprises exhibit the highest price sensitivity, while large logistics firms prioritize integrated TCO solutions.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by OEMs to mitigate supply chain risks. Geographic supply concentration for battery raw materials centers on China, Australia, and the Democratic Republic of Congo. The market depends on lithium, cobalt, and nickel for battery production, exposing manufacturers to commodity price volatility. Distribution runs through established OEM-led direct sales channels and specialized commercial vehicle dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric van market represents a stable compounder, driven by stringent government decarbonization mandates. This sustained regulatory impetus ensures consistent demand and encourages long-term investment across the value chain.
For Market Incumbents:Hedge against battery mineral price volatility by securing long-term supply agreements and exploring alternative chemistries. Invest in modular vehicle platforms to accelerate new model development and reduce per-variant costs. Counter pure-play EV innovators by leveraging established service networks and Total Cost of Ownership (TCO) expertise. Strengthen charging infrastructure partnerships to offer integrated solutions for fleet operators.
For New Entrants and Emerging Players:Begin with underserved niche segments, such as specialized vocational applications or specific urban last-mile delivery routes. Focus on superior software integration and fleet management solutions to differentiate from traditional OEMs. Target emerging markets in Southeast Asia with lower upfront cost models and adaptable vehicle designs. Emphasize Vehicle-to-Grid (V2G) capabilities to create new revenue streams for operators.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized component suppliers and charging infrastructure providers supporting the electric van ecosystem. Long-term viability hinges on companies offering integrated fleet management software and energy services rather than just hardware. Identify acquisition targets with proven modular platform technology or strong intellectual property in battery management systems. The signal to watch is commercialization breakthroughs in solid-state battery technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates engineering efforts across diverse vehicle models, compressing time-to-market for new specialized vans. |
| Battery Supply Agreement | Secures critical raw material access and mitigates price volatility for core vehicle components. |
| Software-Defined Vehicle Investment | Enhances fleet management capabilities and enables over-the-air updates for improved operational efficiency. |
| Geographic Manufacturing Footprint | Reduces logistics costs and localizes production to serve key regional markets like China and Europe. |
| Charging Infrastructure Partnership | Provides integrated energy solutions, addressing a critical pain point for commercial fleet operators. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and publicly available reports — were reconciled to build a robust market perspective. Primary data collection involved conversations with fleet managers, OEM product leads, charging solution providers, and logistics executives. Secondary validation drew from US EPA filings, EU Green Deal documents, and industry association reports. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Cross-referencing historical market data with expert panel input formed the basis of the forecast framework across the analysis window. Segmentation dimensions modeled included vehicle type, battery technology, application, end-user, and regional adoption patterns. Compound Annual Growth Rates were derived using a regression analysis of market drivers. Key forecast inputs included electric vehicle adoption rates and battery manufacturing cost trends.
Several conditions sit outside the modeled scope, including micro-mobility solutions and heavy-duty electric trucks over 7.5 tons GVWR. Forecasts reflect assumptions regarding stable geopolitical conditions and consistent raw material supply. Deviation in key regulatory frameworks or battery mineral availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
North America Electric Bus Market