
 Mountain Bike Suspension Market | 2026-2036
Mountain Bike Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Mountain Bike Suspension Market Insights
Subscription-based leasing programs for premium suspension forks is reconfiguring competitive entry barriers, allowing smaller teams to access pro-tier equipment without capital outlay. Fox Factory leverages in-house damper manufacturing to sustain margin control across price tiers. SRAM anchors its position through proprietary charger damper technology that dominates OEM spec sheets on enduro bikes. DT Swiss competes via precision-machined air spring systems that occupy the lightweight cross-country niche.
Mountain bike suspension comprises telescoping fork assemblies and rear shock units that manage terrain-induced impacts through hydraulic damping and spring media, typically operating within 100-200mm of travel depending on discipline. The primary commercial purpose centers on maintaining tire contact, rider control, and frame protection across irregular surfaces. Air suspension leads unit volume due to weight advantages in cross-country and trail categories, while coil suspension retains structural margin pools in downhill and freeride segments where consistency under sustained loads outweighs mass penalties. Adjustable damping technology is displacing fixed-configuration units as riders demand on-trail tunability without tools.
FDA oversight applies to suspension components marketed with biometric monitoring integrations, while ISO 4210 bicycle safety standards govern structural fatigue testing protocols that manufacturers must satisfy for European market access. The EU Green Deal's extended producer responsibility frameworks are forcing packaging and end-of-life recycling redesigns across component suppliers. Stakeholders must monitor how evolving trail access policies in priority riding destinations reshape replacement demand patterns and aftermarket service requirements.
Market Dynamics
Adjustable on-trail damping technology is collapsing the traditional aftermarket tuning ecosystem as riders demand instantaneous configuration changes without workshop intervention. This shift compresses service revenue pools while elevating firmware and sensor integration as competitive differentiators across price tiers.
Growth Catalysts
- Trail Infrastructure Investment:Germany's Black Forest region demonstrates how concentrated public spending on purpose-built bike parks accelerates equipment replacement cycles and lifts premium suspension attachment rates among recreational riders.
- Biometric Integration Mandates:FDA oversight of suspension components with health monitoring capabilities is creating certification-driven demand for sensor-integrated forks and shocks in the US fitness and medical-rehabilitation segments.
- Extended Producer Responsibility:The EU Green Deal's end-of-life recycling frameworks are forcing packaging redesigns and material traceability investments that favor larger suppliers with compliance infrastructure.
Market Restraints
- Aluminum and Magnesium Price Volatility:Raw material input swings compress margin predictability for precision-machined air spring manufacturers dependent on aerospace-grade alloy supplies.
- OEM Concentration Risk:Bicycle brand consolidation in Taiwan and mainland China creates dependency on a narrowing pool of frame manufacturers for factory-fit suspension volumes.
- Coil Suspension Substitution Ceiling:Weight penalties prevent coil spring technology from penetrating cross-country and marathon racing segments where mass thresholds are non-negotiable.
Strategic Opportunities
- Subscription Leasing Models:Equipment-as-a-service programs for elite suspension forks unlock pro-tier access for privateer racing teams without capital outlay, reconfiguring competitive entry barriers.
- China Certification Arbitrage:GB standards elevation creates first-mover advantage for suppliers achieving early compliance against domestic competitors struggling with testing protocol investments.
- Sensor-Driven Predictive Maintenance:Convergence of telemetry hardware and cloud analytics enables remote diagnostics that unbundle traditional dealer service relationships.
Industry Challenges
- Damper Tuning Expertise Scarcity:Hydraulic engineering talent pools concentrate at legacy motorsport suppliers, constraining expansion for suspension specialists seeking in-house damping development.
- ISO 4210 Fatigue Testing Bottlenecks:European market access requires extended validation timelines that delay product launches and tie up capital in certification inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mountain Bike Suspension Market |
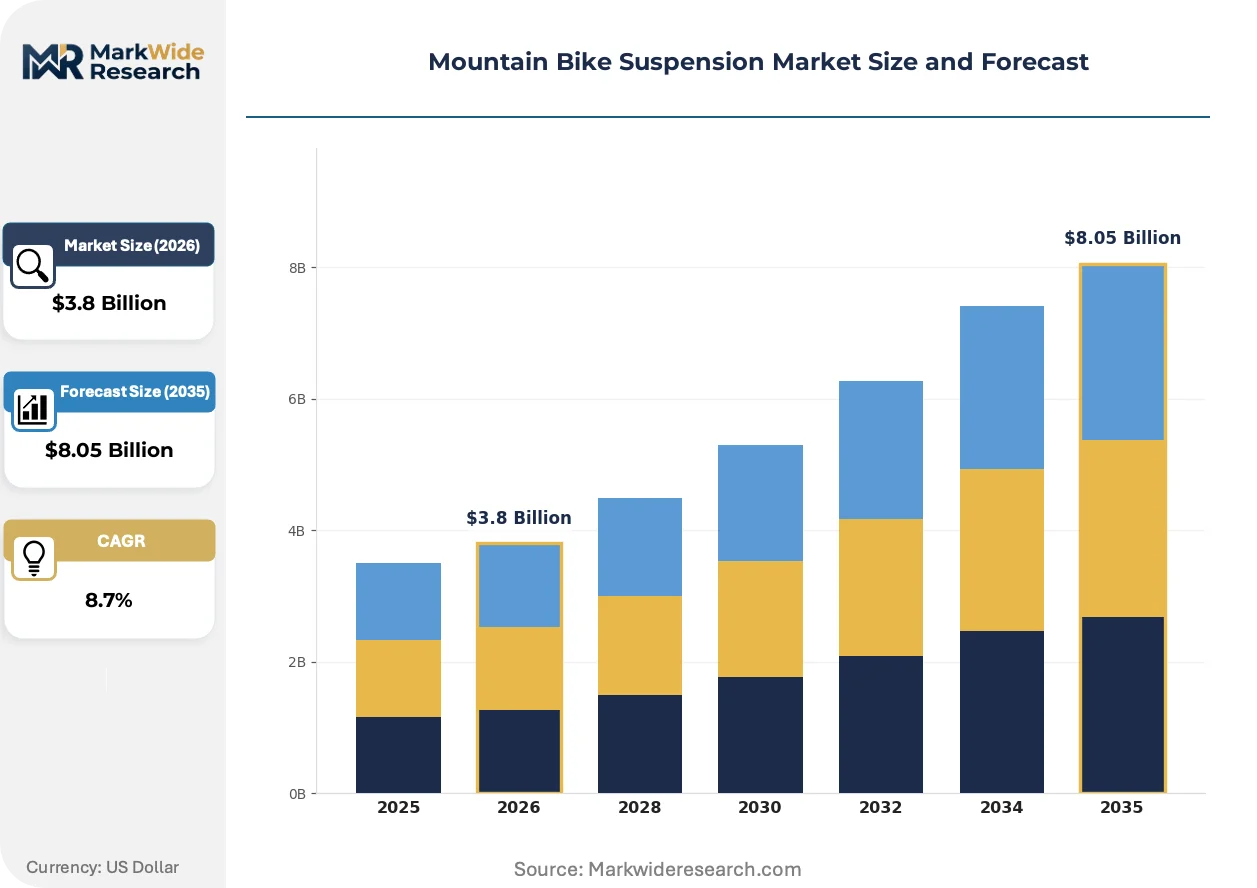
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Air Suspension, Coil Suspension, Hybrid Suspension, Electric Suspension End User: Professional Cyclists, Recreational Riders, Sports Teams, Rental Services Technology: Remote Lockout, Adjustable Damping, Internal Compression, Internal Rebound Application: Cross Country, Downhill, Trail Riding, Freeride |
| Companies Covered | Fox Factory, SRAM, SR Suntour, DT Swiss, Öhlins, Cane Creek Cycling, Manitou, DVO Suspension, Hayes Performance Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mountain Bike Suspension Market Trends and Innovations
Wireless electronic adjustment systems are collapsing the mechanical cable architecture that has defined suspension control for three decades. This transformation elevates firmware capabilities over hardware heritage and redistributes value toward semiconductor and battery supply chains.
Electronic damping adjustment via handlebar-mounted controllers is collapsing the competitive relevance of tool-dependent external adjusters. Enduro and trail riders are adopting these systems fastest, with OEM spec sheets now prioritizing Bluetooth connectivity and app integration over traditional dial counts. The technology is collapsing aftermarket tuning service demand while compressing differentiation windows between product generations.
REACH substance restrictions and RoHS compliance expansions are forcing reformulation of hydraulic fluids and anodizing chemistries used in European-market suspension production. Manufacturers must qualify alternative compounds that maintain thermal stability across operating temperatures without legacy additive packages. Downhill and freeride segments face the steepest reformulation costs due to higher fluid volumes and extreme duty cycles.
Riders are consolidating purchase decisions around complete bike specifications rather than component-level suspension upgrades, shifting influence toward frame manufacturers and away from standalone fork and shock brands. This behavior compresses aftermarket sales velocity and elevates OEM partnership terms as the decisive competitive variable. The pattern is most pronounced in Germany and Austria, where dealer networks emphasize configured packages over build-it-yourself assembly.
Mountain Bike Suspension Market Segmentation
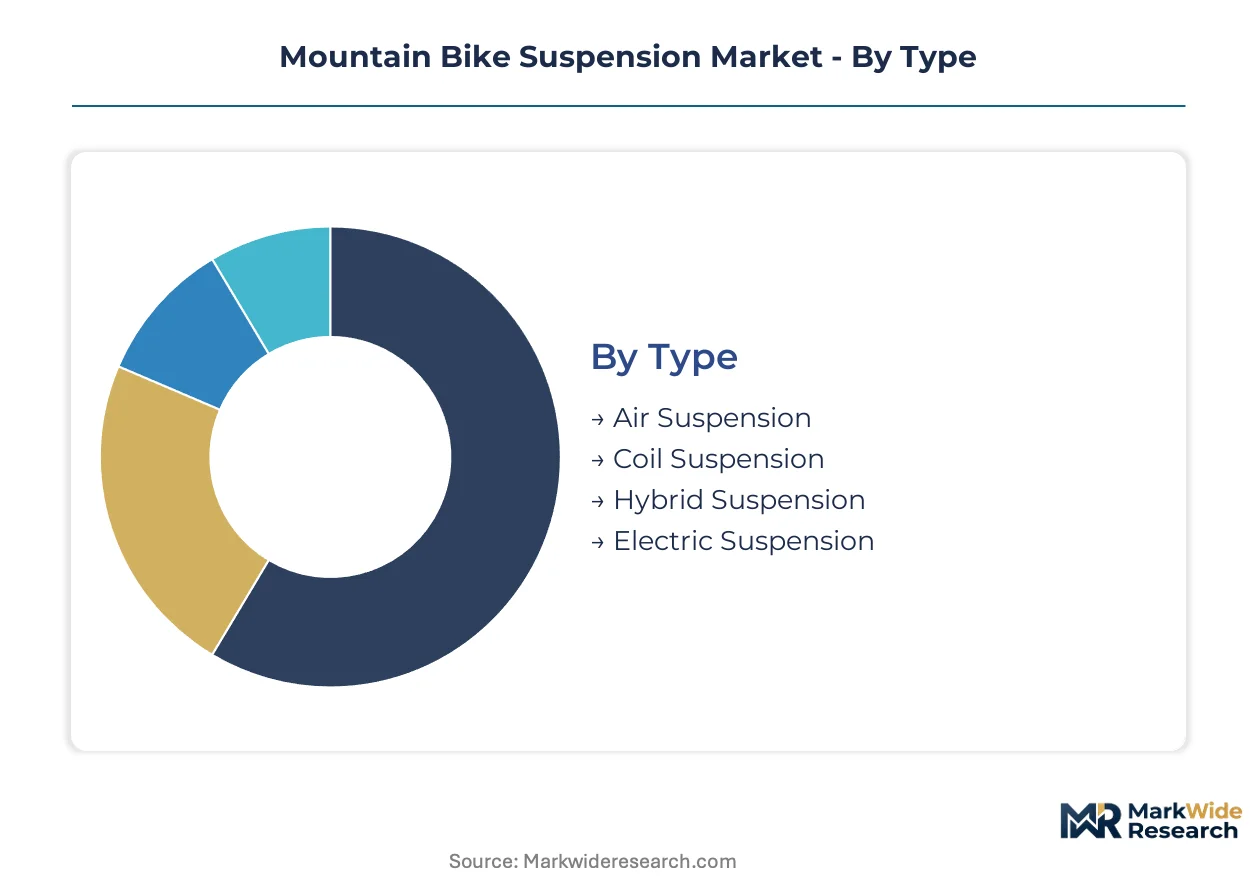
Mountain bike suspension segmentation reflects discipline-specific performance thresholds that dictate spring media, damping architecture, and adjustability requirements. Manufacturers configure product portfolios around these technical boundaries to capture replacement cycles and OEM specification slots.
Type:
Use-case spectrum spans gram-conscious marathon racing to gravity-fed park laps where consistency trumps mass.
- Air Suspension:Pressurized nitrogen or air springs deliver tunable spring rates through volume spacers and pressure adjustments. Cross-country and trail riders in Germany's Black Forest region favor this architecture for its weight advantages on extended climbs.
- Coil Suspension:Steel or titanium coil springs provide linear, heat-resistant performance under sustained impacts. Downhill and freeride segments retain this technology despite mass penalties, as coil predictability preserves control through extended park laps.
- Hybrid Suspension:Dual-chamber designs combine air spring efficiency with coil-like bottom-out resistance. Enduro riders seeking tunability without full coil mass drive niche adoption.
- Electric Suspension:Servo-actuated damping and automated compression adjustment respond to terrain telemetry. FDA oversight applies to units with biometric monitoring, creating certification barriers for US fitness applications.
Established volume favors Air Suspension; emerging adoption favors Electric Suspension.
End User:
Cost tier stratification separates capital-constrained privateers from institutional procurement with predictable replacement budgets.
- Professional Cyclists:Factory teams and elite privateers demand pro-tier dampers with rapid service turnaround and telemetry integration. Subscription leasing programs unlock access without capital outlay for smaller racing programs.
- Recreational Riders:Weekend enthusiasts prioritize reliability and dealer support over marginal performance gains. Germany's trail infrastructure investment accelerates equipment replacement among this cohort.
- Sports Teams:Collegiate and national federation programs procure through institutional tenders with multi-year service contracts. Volume purchasing shifts influence toward OEM partnership terms.
- Rental Services:Bike park and resort operators prioritize durability and rapid turnaround over weight or adjustability. High-hour usage compresses replacement cycles despite lower per-unit margins.
Procurement concentration sits with Recreational Riders; fastest margin expansion tracks Professional Cyclists.
Technology:
Maturity gradient separates decades-old mechanical architectures from firmware-dependent electronic systems.
- Remote Lockout:Handlebar-actuated hydraulic valves suspend compression damping for efficient pedaling. Marathon and cross-country applications favor this proven, cable-actuated simplicity.
- Adjustable Damping:Tool-free external adjusters modify compression and rebound circuits mid-ride. Enduro adoption is climbing the fastest as riders demand terrain-specific tuning without workshop visits.
- Internal Compression:Damper cartridges with shim-stack or port-orifice architectures manage oil flow rates. Precision machining requirements concentrate supply among legacy motorsport suppliers.
- Internal Rebound:Piston-controlled return speed regulation prevents packing through successive impacts. Integration with electronic damping systems is displacing standalone mechanical units.
Mechanical systems retain service revenue; electronic integration commands specification premiums.
Application:
Volume distribution correlates with trail access infrastructure and competitive calendar density.
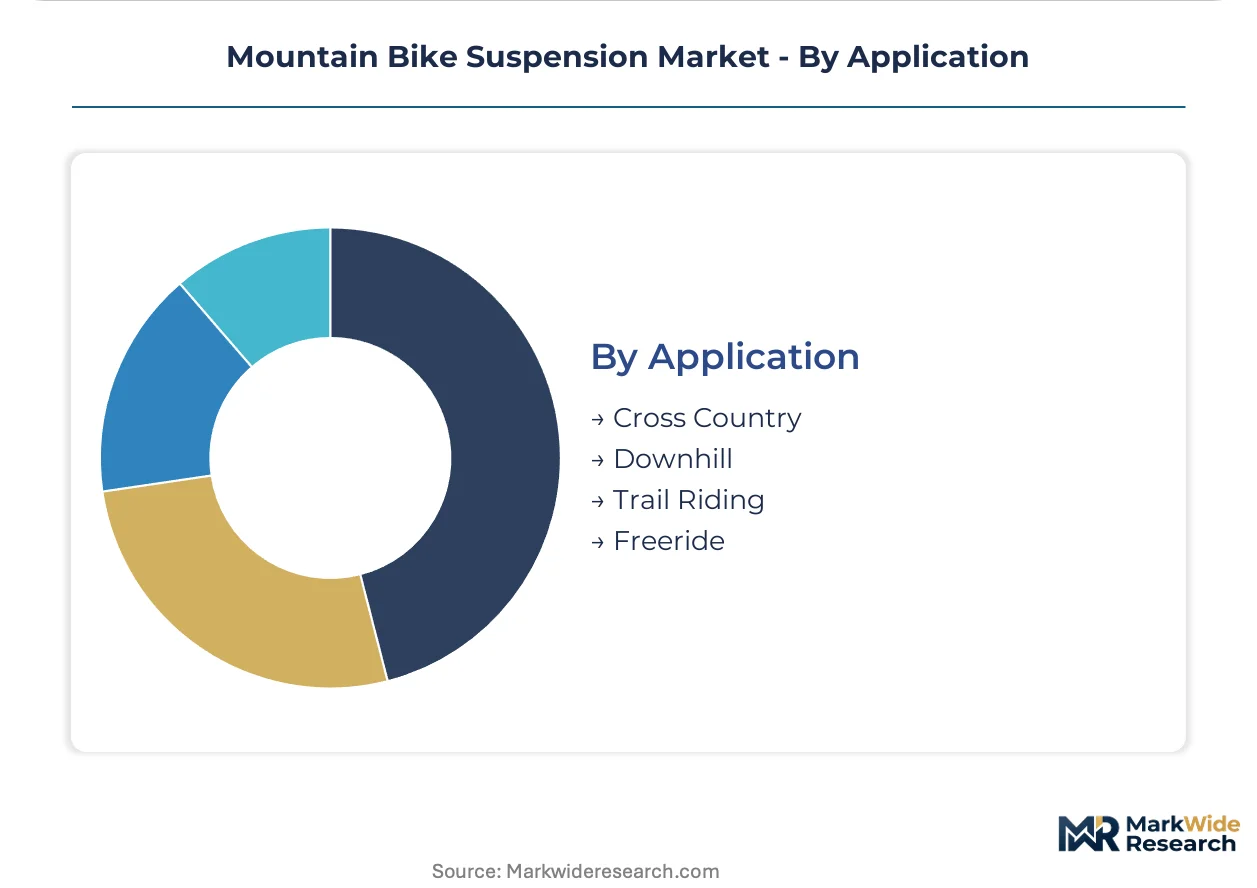
- Cross Country:100-120mm travel forks prioritize efficiency and low mass over impact absorption. Olympic and World Cup racing calendars sustain replacement demand among elite programs.
- Downhill:200mm dual-crown forks and coil shocks manage sustained high-speed impacts. Bike park construction in Austria and Switzerland sustains equipment turnover.
- Trail Riding:130-150mm travel balances climbing efficiency with descending capability. This segment captures the broadest recreational rider base across European markets.
- Freeride:Slopestyle and big-mountain disciplines demand maximum durability with moderate travel. Smaller participant pools limit volume despite premium pricing.
Trail Riding commands unit volume; Downhill sustains margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Black Forest trail infrastructure investment is accelerating equipment replacement cycles and elevating premium suspension attachment rates among recreational riders. National cycling promotion programs in Austria and Switzerland sustain comparable demand patterns through dedicated bike park construction. France's Auvergne-Rhône-Alpes region channels public funds toward purpose-built gravity infrastructure.
Germany
Black Forest municipalities deploy public capital toward trail networks and bike parks at accelerating rates. KBA vehicle safety frameworks extend testing protocols to high-performance bicycle components entering German distribution. Stuttgart's precision engineering cluster hosts damper machining specialists supplying motorsport-derived technology to suspension manufacturers.
United States
FDA oversight applies to suspension forks integrating biometric health monitoring for fitness and medical-rehabilitation applications. Colorado and Utah trail access policies reshape replacement demand through seasonal riding permit structures. Pacific Northwest fabrication clusters concentrate aluminum machining capacity serving aerospace and bicycle component markets simultaneously.
China
GB standards elevation for bicycle component safety is forcing certification investments that favor established suppliers over emerging competitors. MIIT industrial policy channels subsidies toward high-end sporting goods manufacturing in coastal provinces. Shenzhen and Dongguan electronics corridors supply sensor hardware for emerging electronic suspension architectures.
Switzerland
Swissmedic medical device frameworks intersect with suspension products marketed for therapeutic cycling applications. Alpine cantons maintain dense lift-served bike park infrastructure that sustains high-hour equipment usage. Jura region precision manufacturing maintains heritage in micro-hydraulic component production for watchmaking and cycling applications.
Austria
Tirol and Salzburg provinces concentrate gravity trail investment that drives coil suspension demand despite mass penalties. National tourism promotion programs classify bike parks as strategic economic development infrastructure. Graz industrial zone hosts aluminum forging operations supplying fork crown and chassis components to European assembly plants.
Mountain Bike Suspension Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by damper technology sourcing and OEM specification capture. Market structure concentrates around three archetypes: vertically integrated damper manufacturers, precision air spring specialists, and regional volume suppliers serving price-sensitive segments. Competitive moves center on strategic OEM partnership negotiations and firmware development capabilities for electronic adjustment systems.
Within the integrated-manufacturing tier, Fox Factory and SRAM occupy positions that exemplify in-house damper production strategies. Fox Factory leverages captive damper manufacturing to sustain margin control across price tiers. SRAM anchors its market presence through proprietary charger damper technology that dominates OEM specification on enduro platforms. DT Swiss represents the precision-machined air spring archetype, competing via lightweight cross-country architectures.
| Leading Market Players |
|---|
| Fox Factory |
| SRAM |
| SR Suntour |
| DT Swiss |
| Öhlins |
| Cane Creek Cycling |
| Manitou |
| DVO Suspension |
| Hayes Performance Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwanese precision-machining facilities is pressuring component suppliers to absorb margin compression while OEMs consolidate procurement leverage, creating asymmetric pricing power that favors frame manufacturers over standalone suspension brands.
Pricing Analysis
Certification level (ISO 4210/CE/FDA-grade) creates the primary spread between premium and economy tiers, with European-market units commanding substantial premiums due to extended fatigue-testing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects damper technology sourcing, with in-house hydraulic development supporting the top tier. Cost compression in the standard tier is intensifying because OEMs are consolidating specification decisions around complete bike packages. Recreational riders exhibit highest price sensitivity, while professional racing programs prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms from European OEMs are squeezing working capital for precision-machining suppliers in Taiwan, forcing supply-chain finance facility adoption among mid-tier damper manufacturers. Manufacturing concentrates in Taiwan, mainland China, and Switzerland, with Jura-region micro-hydraulic specialists feeding premium European assembly. Aerospace-grade aluminum and magnesium alloys, precision-machined damper cartridges, and sensor hardware from Shenzhen electronics corridors constitute critical inputs. Single-source vulnerability around damper machining expertise constrains capacity expansion. Distribution runs through OEM factory-fit channels and aftermarket dealer networks, with direct-to-consumer growth compressing traditional retail margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic suspension adoption sits at early-cycle expansion, with wireless adjustment technology penetration in enduro and trail segments creating sustained replacement demand across the analysis window.
For Market Incumbents: Build firmware development moats through app-integrated telemetry systems that lock riders into proprietary adjustment ecosystems. Consolidate damper machining capacity in Stuttgart's precision engineering cluster to secure hydraulic engineering talent pools against motorsport competitors. Defensive patenting around electronic damping algorithms protects against emerging semiconductor suppliers entering the category. Certification investment in FDA-grade biometric monitoring creates regulatory barriers for challenger brands. For New Entrants and Emerging Players: Build out subscription leasing infrastructure targeting privateer racing teams excluded from pro-tier equipment access by capital constraints. Target China's domestic replacement market where GB standards elevation disadvantages local competitors lacking testing protocol investments. Develop sensor-driven predictive maintenance platforms that unbundle traditional dealer service relationships. Partner with Shenzhen hardware corridors for rapid electronic suspension prototyping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with subscription leasing programs and telemetry-enabled service contracts, offering superior cash flow quality versus transactional component sales. Acquisition candidates with in-house damper manufacturing and European certification infrastructure present durable competitive positioning across the projection horizon. Monitor trail access policy shifts in Germany's Black Forest and Austria's Tirol as demand inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Damper Manufacturing | Captive hydraulic production insulates margin control against motorsport supplier concentration. |
| Electronic Suspension Platform Launch | Wireless adjustment systems displace mechanical cable architectures and compress generational differentiation windows. |
| Subscription Leasing Program Expansion | Equipment-as-a-service unlocks pro-tier access for capital-constrained privateer racing teams. |
| China GB Standards Early Compliance | First-mover certification against domestic competitors struggling with testing protocol investments. |
| Sensor-Driven Predictive Maintenance Development | Telemetry hardware and cloud analytics unbundle traditional dealer service relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and OEM specification databases to establish baseline market sizing. Interviews with suspension product managers, frame manufacturer procurement leads, damper machining specialists, and bike park operators supplied operational validation. SEC 10-K disclosures, ISO certification registries, and EU Green Deal implementation documents provided secondary triangulation. Bottom-up unit volume estimates and top-down value reconstructions were cross-referenced for convergence.
Forecast inputs span spring media type, damping technology maturity, end-user procurement tier, and application discipline across the modeling period. Segmentation dimensions include suspension architecture, adjustability mechanism, rider category, and regional trail infrastructure development. CAGRs derive from replacement cycle analysis, OEM specification trend extrapolation, and penetration modeling for electronic adjustment systems. Raw material input cost trajectories and regulatory compliance burden projections inform margin trajectory assumptions.
Practitioners should monitor aluminum and magnesium price volatility, OEM consolidation patterns in Taiwan and mainland China, and trail access policy evolution in priority riding destinations for early signals. Forecasts reflect assumptions around sustained infrastructure investment in Germany's Black Forest region and continued FDA oversight expansion for biometric-integrated products. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
300cc Motorcycle Market