
 Automotive Aluminium Extrusion Market | 2026-2036
Automotive Aluminium Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aluminium Extrusion Market Analysis
A shortage of certified aluminium extrusion die engineers is reorganizing how automotive suppliers scale capacity. Novelis Inc. leverages its closed-loop recycling network to secure primary billet supply. Constellium SE anchors European OEM relationships through dedicated structural component lines. Norsk Hydro ASA sustains Nordic energy-cost advantages in smelting and extrusion.
Automotive aluminium extrusion shapes aluminium alloy billets—typically 6xxx series with magnesium and silicon—through heated dies into profiles with tolerances near 0.15 mm, serving primarily to reduce vehicle mass while maintaining crashworthiness. Structural Components command the largest volume share as OEMs substitute extruded profiles for stamped steel in body-in-white assemblies. Thermal Management applications within the Application dimension represent the fastest-expanding margin pool, driven by battery enclosure cooling circuits and heat exchanger manifolds.
The EPA regulates fleet fuel economy thresholds that directly incentivize lightweighting via aluminium substitution. ECHA administers REACH compliance for surface treatments and alloying additives used in extruded automotive parts. China's MIIT enforces new energy vehicle production quotas that amplify aluminium demand for battery tray architectures. Stakeholders must monitor evolving alloy certification requirements across these jurisdictions to maintain qualification status with tier-1 suppliers.
Market Dynamics
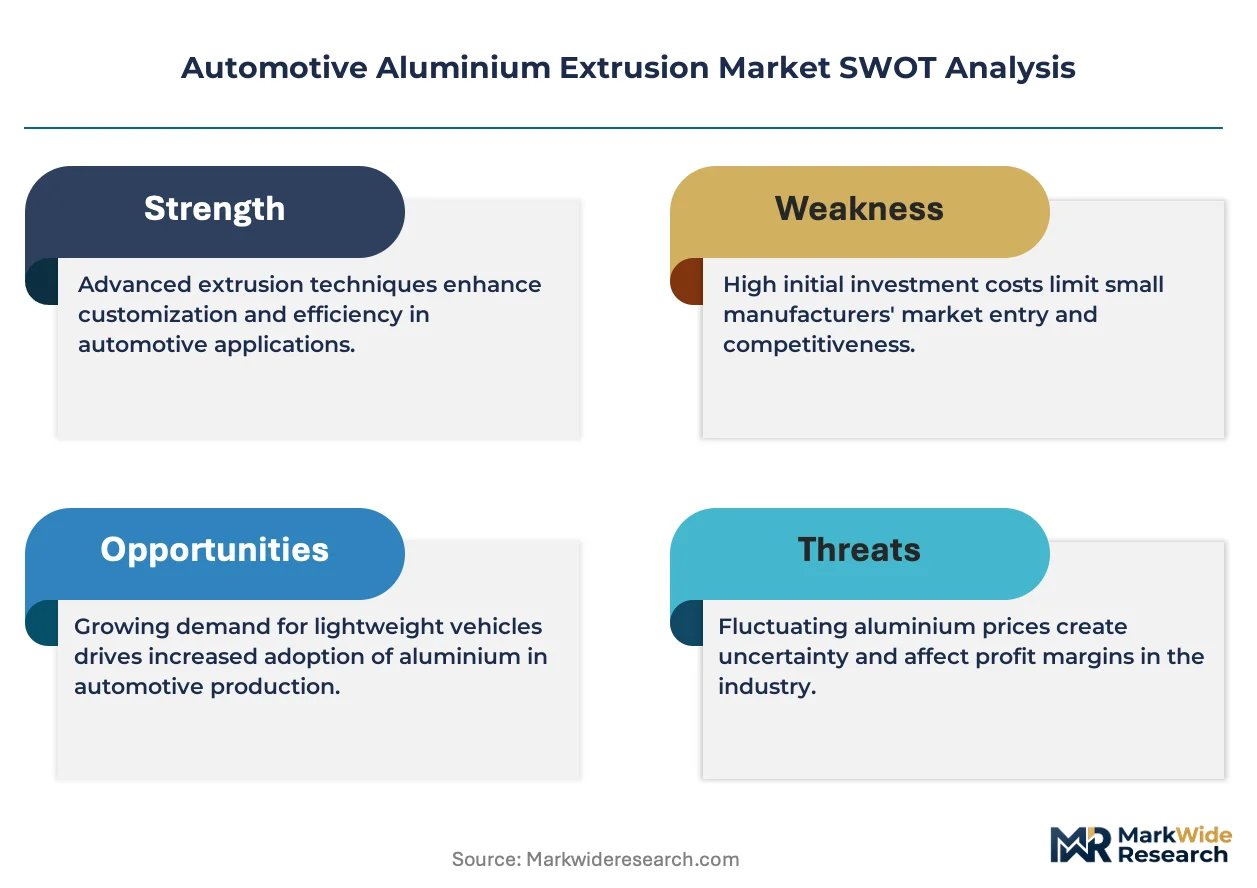
Electric vehicle platform architectures are forcing a wholesale redesign of body-in-white material strategies, with aluminium extrusion displacing stamped steel in structural nodes previously reserved for high-strength alloys. OEM engineering teams now specify hollow multi-chamber profiles for battery enclosure rails, creating capacity bottlenecks at qualified extruders.
Growth Catalysts
- EU Green Deal carbon border adjustments:European automakers accelerate aluminium substitution to avoid embodied carbon tariffs on steel imports, favoring low-carbon extruded profiles from Nordic smelters.
- MIIT new energy vehicle quotas:China's production mandates for battery electric vehicles drive demand for aluminium-intensive battery tray architectures and thermal management circuits.
- Hydro-powered smelting:Norwegian and Icelandic extrusion feedstock commands premium positioning as OEMs scope Scope 3 emissions reduction pathways.
Market Restraints
- Primary aluminium price volatility:LME benchmark swings compress extrusion margins and deter long-term supply contracts between tier-1 suppliers and OEMs.
- Certified die engineering scarcity:Germany and Japan concentrate the limited pool of engineers capable of designing complex hollow profiles for crash-critical applications.
- Steel industry cost competition:Advanced high-strength steel grades from South Korean mills retain cost advantage in non-structural body panels.
Strategic Opportunities
- India automotive manufacturing:Domestic OEMs and multinational joint ventures localize aluminium-intensive platforms, creating greenfield demand for extrusion capacity near Chennai and Pune.
- Solid-state battery thermal interfaces:Next-generation cell architectures require precision-extruded cooling plates with integrated micro-channels.
- Closed-loop recycling infrastructure:EU end-of-life vehicle directives incentivize scrap collection networks that feed dedicated automotive alloy remelting streams.
Industry Challenges
- Alloy qualification timelines:OEM-specific crash simulation protocols extend new 6xxx series certification cycles to 18-24 months, freezing supplier R&D roadmaps.
- Die refurbishment lead times:Wear on hardened steel tooling for complex hollow profiles stretches replacement cycles, constraining production flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aluminium Extrusion Market |
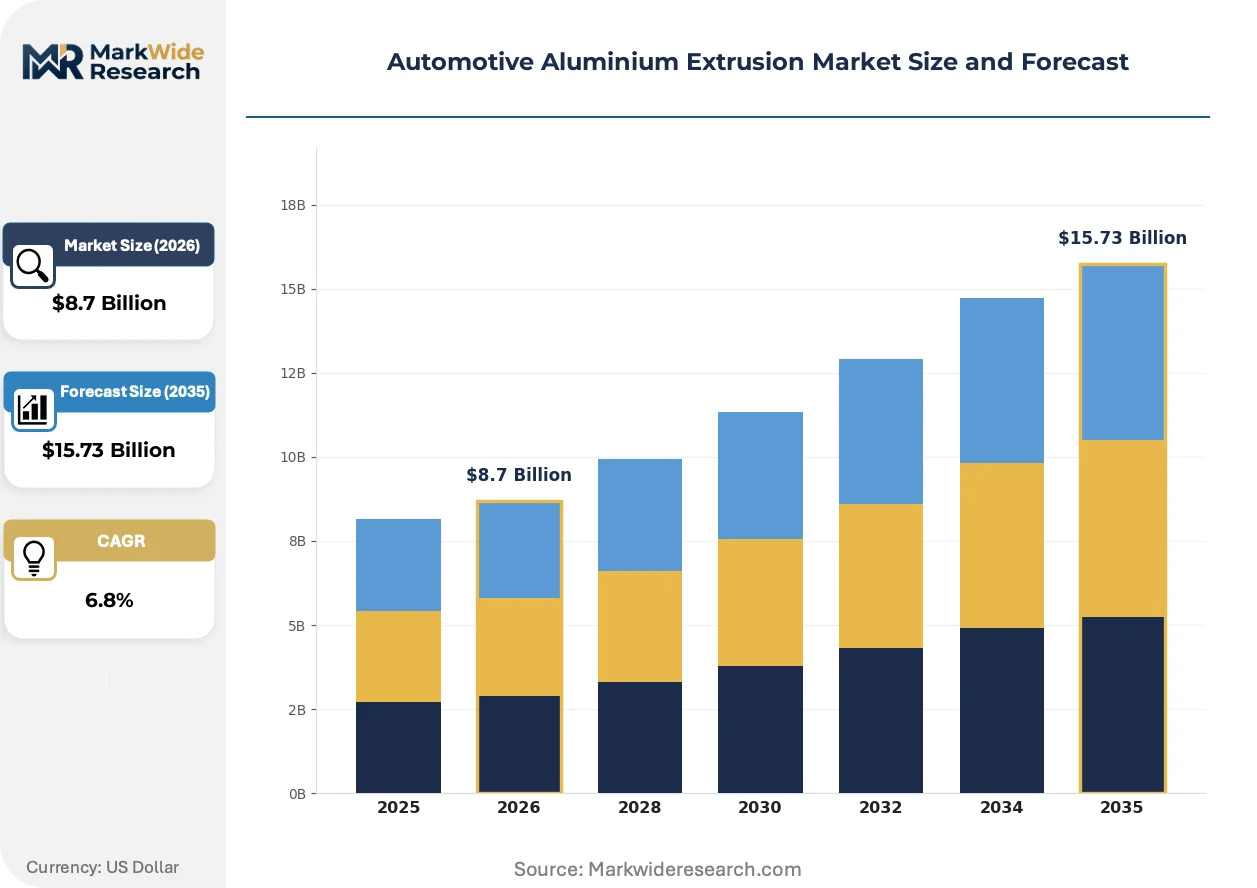
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Components, Body Panels, Heat Exchangers, Chassis Parts End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Extrusion, Die Casting, 3D Printing, Machining Application: Lightweight Structures, Thermal Management, Crash Management, Aesthetic Features |
| Companies Covered | Novelis Inc., Constellium SE, Norsk Hydro ASA, Kaiser Aluminum Corporation, UACJ Corporation, Hindalco Industries Ltd., Bonnell Aluminum, Arconic Corporation, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aluminium Extrusion Market Emerging Trajectories
Extrusion process control systems and alloy formulation science are converging to enable thinner-wall profiles with maintained structural integrity, compressing the traditional mass-efficiency frontier between aluminium and advanced composites.
Direct-chill casting combined with inline quenching is fragmenting the conventional billet supply chain. Tier-1 suppliers in Germany and the United States adopt integrated casting-extrusion cells to reduce thermal cycling losses. This consolidation of process steps compresses lead times for prototype development while raising capital barriers for mid-scale competitors.
REACH authorization requirements for hexavalent chromium surface treatments are forcing conversion to trivalent passivation chemistries across European supply chains. Tier-2 surface treatment houses in Italy and Spain face compliance-driven consolidation. Battery enclosure suppliers serving Swedish and German OEMs now specify REACH-compliant pre-treatment as a qualification gate.
Fleet procurement teams at leasing companies and ride-hailing operators are consolidating specification authority previously held by individual OEM brand divisions. This buyer concentration favors standardized extrusion profiles across multiple vehicle platforms. The shift is most visible in North American commercial van and last-mile delivery segments, where total cost of ownership calculations override brand-specific engineering preferences.
Automotive Aluminium Extrusion Market Segmentation
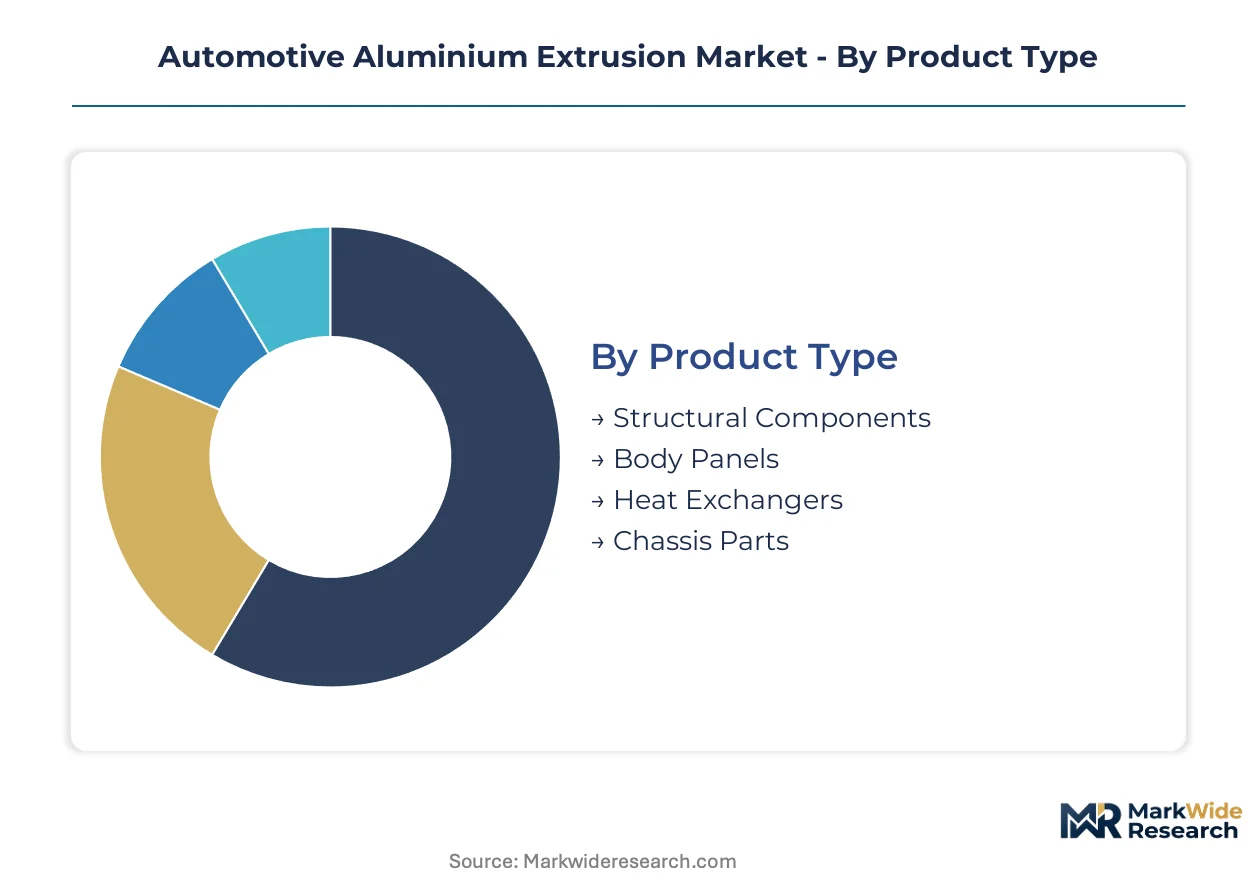
Automotive aluminium extrusion segments channel through distinct procurement pathways. OEM engineering teams specify structural profiles directly for body-in-white programs, while tier-1 suppliers source thermal management components through consolidated vendor pools. Understanding these channel dynamics illuminates where margin pools concentrate and where supplier qualification barriers protect incumbent positions.
Product Type:
Structural Components flow primarily through direct OEM contracts with multi-year qualification cycles. Body Panels and Heat Exchangers move through tier-1 supplier networks with shorter procurement horizons. Chassis Parts split between captive in-house production and external extrusion houses depending on vehicle platform architecture.
- Structural Components:Hollow multi-chamber 6xxx series profiles with wall thicknesses down to 1.2 mm serve crash-critical nodes and battery enclosure rails. Demand concentrates at German and Chinese OEMs electrifying platform architectures, constrained by certified die engineering scarcity that limits qualified supplier expansion.
- Heat Exchangers:Micro-channel extrusions with internal fin structures optimize coolant flow for battery thermal circuits. Procurement is accelerating at Swedish and South Korean battery enclosure suppliers as cell energy densities climb and thermal runaway protocols tighten.
- Body Panels:Thin-walled 5xxx series sheets and extruded frames substitute for stamped steel in hood and door assemblies.
- Chassis Parts:Solid and hollow profiles for suspension links, cross-members, and subframe components.
Structural Components dominate installed base. Heat Exchangers are where expansion concentrates.
End User:
Cost tier stratification separates segments. OEMs and Vehicle Assemblers absorb qualification costs and long development cycles for proprietary profiles. Tier-1 Suppliers and Aftermarket Providers compete on scale economies and inventory velocity for standardized geometries.
- OEMs:In-house aluminium engineering teams at Volkswagen, BYD, and Ford specify bespoke extrusion profiles with exclusive die ownership. These organizations control architecture-level material decisions and capture scope 3 emissions reductions through primary aluminium sourcing contracts.
- Tier-1 Suppliers:Magna, Benteler, and Gestamp operate dedicated extrusion lines feeding multiple OEM platforms from shared die libraries. Their procurement aggregates volume across customers to justify complex hollow profile capacity investments that individual OEMs cannot sustain alone.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities executing OEM-directed specifications.
- Aftermarket Providers:Distributors and remanufacturers serving collision repair and performance modification channels.
OEMs anchor premium pricing through specification authority. Tier-1 Suppliers concentrate volume expansion.
Technology:
Application requirements dictate technology selection. Crash-critical structural nodes demand extrusion integrity. Complex geometries with internal features favor die casting. Prototyping and low-volume customization increasingly adopt additive methods.
- Extrusion:Direct and indirect extrusion of 6xxx and 7xxx series billets produces continuous profiles with grain structure aligned to load paths. Structural Components and Thermal Management applications depend on this method for hollow multi-chamber geometries impossible to form through other means.
- Die Casting:High-pressure injection of molten aluminium into hardened steel molds generates complex three-dimensional shapes with integrated features. This technology serves node consolidation strategies in EV platform engineering where multiple stamped steel parts merge into single castings.
- 3D Printing:Laser powder bed fusion and wire-arc additive manufacturing enable topology-optimized brackets and prototyping iterations without die lead times.
- Machining:CNC milling and drilling of extruded blanks or solid stock for precision interfaces and tolerance refinement.
Extrusion commands structural application share. Die Casting is climbing fastest in node consolidation.
Application:
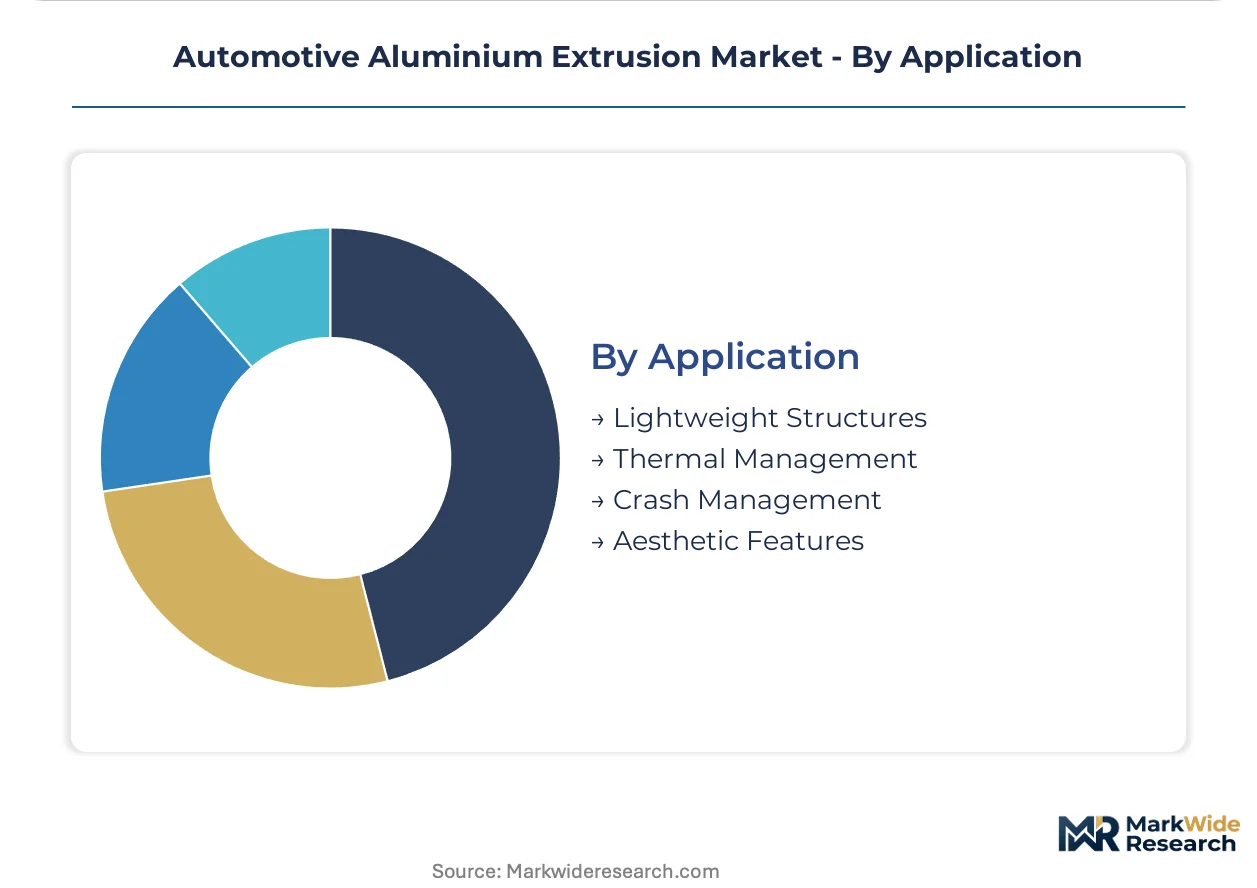
Customer type separates segments by procurement behavior. Fleet operators and leasing companies standardize specifications across Lightweight Structures and Thermal Management for total cost of ownership optimization. Luxury OEMs differentiate through Aesthetic Features with custom finishes and visible aluminium architectures.
- Thermal Management:Battery enclosure cooling plates, heat exchanger manifolds, and motor housing jackets require precision-extruded channels with tight dimensional tolerances for coolant sealing. This application is expanding most quickly at Chinese and European OEMs scaling electric vehicle production and facing MIIT quotas and EU Green Deal carbon accounting.
- Lightweight Structures:Body-in-white extrusions, space frame nodes, and closure reinforcements reduce mass while maintaining stiffness targets. German OEMs lead specification intensity here, driven by fleet CO2 compliance and NHTSA fuel economy thresholds in their US export markets.
- Crash Management:Specially engineered crushable extrusions and load-path directing profiles for frontal and side impact absorption.
- Aesthetic Features:Visible trim, roof rails, and architectural exterior elements with surface finish requirements.
Lightweight Structures dominate current volume. Thermal Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Chinese automakers prioritize battery enclosure architectures, while German OEMs emphasize body-in-white structural substitution. The United States concentrates thermal management procurement through tier-1 supplier networks.
China
MIIT new energy vehicle quotas compel domestic OEMs to electrify platform architectures rapidly. The regulator enforces annual production minimums for battery electric vehicles that amplify aluminium demand for tray assemblies and cooling circuits. Manufacturing clusters around Shanghai and Shenzhen host dedicated extrusion lines feeding BYD and CATL supplier ecosystems.
Germany
Fleet CO2 compliance deadlines drive Volkswagen, BMW, and Mercedes-Benz to substitute extruded profiles for stamped steel in crash-critical nodes. The KBA enforces type-approval protocols that extend alloy qualification timelines to 18-24 months. Industrial concentration in Bavaria and Baden-Württemberg sustains Europe's deepest pool of certified die engineers for hollow multi-chamber profiles.
United States
EPA fuel economy thresholds incentivize lightweighting across Detroit Three pickup and SUV platforms. NHTSA crashworthiness standards shape specification requirements for extruded structural reinforcements. Manufacturing corridors in Michigan and Ohio anchor extrusion capacity serving Ford, GM, and Stellantis assembly networks.
Japan
METI carbon neutrality roadmaps push Toyota and Honda toward aluminium-intensive architectures for hybrid and battery electric platforms. JIS alloy certification protocols maintain stringent material traceability requirements. Industrial clusters in Aichi Prefecture and the Kansai region concentrate precision extrusion capacity for thermal management components.
South Korea
Hyundai Motor Group and Kia Corporation accelerate EV platform rollout under government green growth initiatives. The MFDS oversees surface treatment compliance for automotive components exported to European markets. Gyeonggi-do and Ulsan metropolitan areas host integrated casting-extrusion cells serving battery enclosure and motor housing programs.
Automotive Aluminium Extrusion Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier. The upper tier commands primary billet supply and closed-loop recycling infrastructure, while mid-scale extruders compete on die complexity and regional proximity to OEM assembly plants. Three archetypes dominate: Nordic hydro-powered smelters with Scope 3 advantages, European structural component specialists with dedicated OEM lines, and Asian diversified metals conglomerates with backward integration into bauxite refining. Competitive moves center on captive recycling network expansion and qualification for hollow multi-chamber battery enclosure profiles.
Within the integrated smelter-extruder tier, Norsk Hydro ASA exemplifies Nordic energy-cost positioning through hydro-powered primary production. Constellium SE anchors European OEM relationships through dedicated structural component manufacturing. Novelis Inc. occupies a position emphasizing closed-loop recycling networks that secure primary billet supply against price volatility. These three represent distinct geographic and strategic archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Novelis Inc. |
| Constellium SE |
| Norsk Hydro ASA |
| Kaiser Aluminum Corporation |
| UACJ Corporation |
| Hindalco Industries Ltd. |
| Bonnell Aluminum |
| Arconic Corporation |
| Alcoa Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Nordic smelters and German OEMs lock in primary billet supply against LME volatility while anchoring price visibility for multi-year platform programs. These contracts concentrate purchasing power at integrated extruders capable of guaranteeing Scope 3 emissions thresholds under EU carbon border adjustments.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement for structural components, with spot market exposure limited to secondary alloy feedstock and prototype volumes. Price differentiation rests on certification grade for crash-critical applications and volume scale for standardized thermal management profiles. Cost compression in battery enclosure extrusions is intensifying because Chinese OEMs aggregate demand across multiple platform architectures. Tier-1 suppliers exhibit highest price sensitivity due to margin pressure from consolidated OEM procurement teams, while captive in-house extrusion at Volkswagen and BYD insulates premium pricing for proprietary hollow profiles.
Supply Chain Analysis
Die refurbishment lead times stretching sixteen to twenty weeks constrain production flexibility at extruders serving just-in-time battery enclosure programs. Primary supply concentrates in Norway, Iceland, and Canada for hydro-powered smelting, with Germany and China hosting the bulk of precision extrusion capacity. Raw material dependencies draw from bauxite refining in Guinea and Australia, primary smelting energy costs, and hardened steel tooling from Japanese specialty mills. Single-source vulnerability sits with the limited pool of certified die engineers in Germany and Japan capable of designing complex hollow profiles. Distribution runs through tier-1 supplier consolidation points near OEM assembly clusters in Bavaria, Michigan, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive aluminium extrusion demand follows cyclical recovery patterns tied to electric vehicle platform rollout cadence, with MIIT quotas and EU fleet CO2 deadlines creating synchronized capacity investment windows.
For Market Incumbents: Consolidate die engineering capabilities through selective acquisition of specialized tool-and-die houses in Stuttgart and Nagoya to secure scarce hollow profile design capacity. Lock in long-term primary aluminium supply contracts with Nordic hydro-powered smelters before carbon border adjustments tighten feedstock qualification. Vertical integration into closed-loop scrap collection networks protects margin position against secondary alloy price volatility.
For New Entrants and Emerging Players: Lead with dedicated extrusion capacity for solid-state battery thermal interface plates, where precision micro-channel requirements and absence of established supplier relationships create penetrable white space. Target Indian automotive manufacturing clusters near Chennai and Pune, where domestic OEM localization lacks qualified extrusion partners for aluminium-intensive platforms. Pursue joint development agreements with battery enclosure specialists rather than direct OEM qualification to compress entry timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale extruders with certified hollow multi-chamber capacity and existing relationships with German or Chinese OEM platform engineering teams. Over a five-to-ten year horizon, structural demand for battery enclosure architectures supports viability independent of near-term primary aluminium price cycles. Monitor alloy qualification timeline compression at KBA and MIIT as the signal indicating supplier bottleneck relief and competitive entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Network Expansion | Novelis and Constellium are securing primary billet supply against LME volatility through captive scrap remelting infrastructure. |
| Hollow Multi-Chamber Profile Qualification | Certification for crash-critical battery enclosure rails protects incumbent positions at Norsk Hydro and Kaiser Aluminum. |
| Integrated Casting-Extrusion Cell Investment | Tier-1 suppliers in Germany and the United States compress prototype lead times through thermal cycling loss reduction. |
| REACH-Compliant Surface Treatment Conversion | Tier-2 houses in Italy and Spain face consolidation pressure as Swedish OEMs mandate trivalent passivation chemistry. |
| Die Engineering Capability Acquisition | Scarcity of certified engineers for complex hollow profiles is driving targeted tool-and-die house purchases in Stuttgart. |
Methodological Framework
A standing panel of OEM platform engineers, tier-1 supplier procurement directors, extrusion plant managers, and die design specialists provided ongoing calibration against operational realities. Primary interview data combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed aluminium producers, and customs trade records for billet and profile movements. Bottom-up segment sizing triangulated against top-down industry association estimates from European Aluminium and the Aluminum Association.
Consistency checks validated volume and value outputs against external benchmarks including smelter capacity utilization reports and OEM lightweighting disclosure filings. Segmentation modeling spanned vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs derived from regression analysis of historical platform material intensity trends and forward-looking EV penetration scenarios. Industry-specific inputs incorporated MIIT quota enforcement patterns and KBA type-approval timeline data.
Underlying assumptions cover sustained EV platform rollout cadence and stable alloy certification protocols, with deviation risk concentrated in primary aluminium price volatility and die engineering capacity constraints. Forecasts reflect these assumptions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Air Compressor Market