
 North America Youth ATV and UTV Market | 2026-2036
North America Youth ATV and UTV Market Size, Share, and Industry Trends Forecast 2026-2036
North America Youth ATV and UTV Market Analysis
CPSC youth ATV safety certification is rotating the competitive landscape by disqualifying uncertified manufacturers from retail channels. Polaris Industries sustains broad dealership coverage across the United States and Canada. Yamaha Motor Co. Ltd. dominates youth engine displacement categories below 150cc. BRP Inc. specializes in premium UTV platforms with integrated parental control systems.
Youth ATV and UTV equipment comprises gasoline-powered, four-wheeled recreational vehicles with engine displacements restricted by federal safety standards, designed for operators under sixteen years of age and governed by speed limiters and tethered emergency stops. The primary commercial purpose centers on supervised outdoor recreation, introductory motorsport training, and property utility tasks on farms and rural estates. ATV product type occupies the largest volume share due to lower price points and broader trail access permissions. UTV configurations command margin premiums through multi-passenger seating and cargo utility. Family Use end user segment leads growth as parents seek structured alternatives to unstructured screen time.
CPSC, EPA, and Transport Canada collectively shape product compliance through emissions thresholds, youth safety standards, and import certification requirements. State-level OHV registration programs in Texas, Arizona, and Utah further constrain market access for non-compliant manufacturers. Stakeholders must monitor evolving engine displacement restrictions and electrification pilot programs as regulatory bodies balance youth access with environmental targets.
Market Dynamics
CPSC youth ATV safety certification is compressing the manufacturer base by disqualifying uncertified producers from retail channels. State-level OHV registration programs in Texas, Arizona, and Utah further constrain market access, forcing suppliers to absorb compliance costs or exit.
Growth Catalysts
- Parental demand for supervised recreation:Family Use buyers prioritize structured outdoor alternatives to screen-based entertainment. Rural property owners in Texas and Florida seek utility-task vehicles for estate maintenance.
- CPSC certification requirements:Federal safety standards for youth operators under sixteen create barrier-to-entry advantages for compliant manufacturers. Retailers now require proof of certification before shelf placement.
- Trail network expansion:Southeastern states are extending year-round OHV trail access. Georgia and Alabama have opened new youth-designated riding corridors since 2023.
Market Restraints
- Steel and aluminum input volatility:Chassis and roll-cage fabrication depends on commodity metals subject to tariff and energy-cost fluctuations. Margins compress when raw material prices spike without pricing power.
- Engine supply concentration:Small-displacement gasoline powertrains for sub-150cc categories concentrate among Japanese and Taiwanese suppliers. North American assemblers face single-source risk on critical drivetrain components.
- Electrification cost gap:Battery-electric youth platforms carry 40-60% manufacturing cost premiums versus gasoline equivalents. EPA emissions thresholds do not yet mandate zero-emission conversion for this vehicle class.
Strategic Opportunities
- Canadian provincial expansion:Alberta and British Columbia trail networks remain underdeveloped relative to U.S. southeastern density. Provincial OHV permit programs are relaxing youth access age restrictions.
- Parental control system integration:GPS geofencing and remote speed-limiting technologies converge with smartphone platforms. Premium UTV configurations can bundle subscription-based monitoring services.
- Farm and estate utility pivot:Rural property owners beyond traditional recreation buyers represent untapped demand. Youth-sized equipment with cargo capacity addresses property maintenance tasks.
Industry Challenges
- Powertrain engineering talent scarcity:Small-displacement engine calibration and emissions compliance require specialized skill sets. Manufacturers compete with automotive and powersports sectors for the same technical labor pool.
- CPSC certification timeline compression:Third-party testing and documentation requirements extend product development cycles. New entrants face 12-18 month delays before retail channel eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Youth ATV and UTV Market |
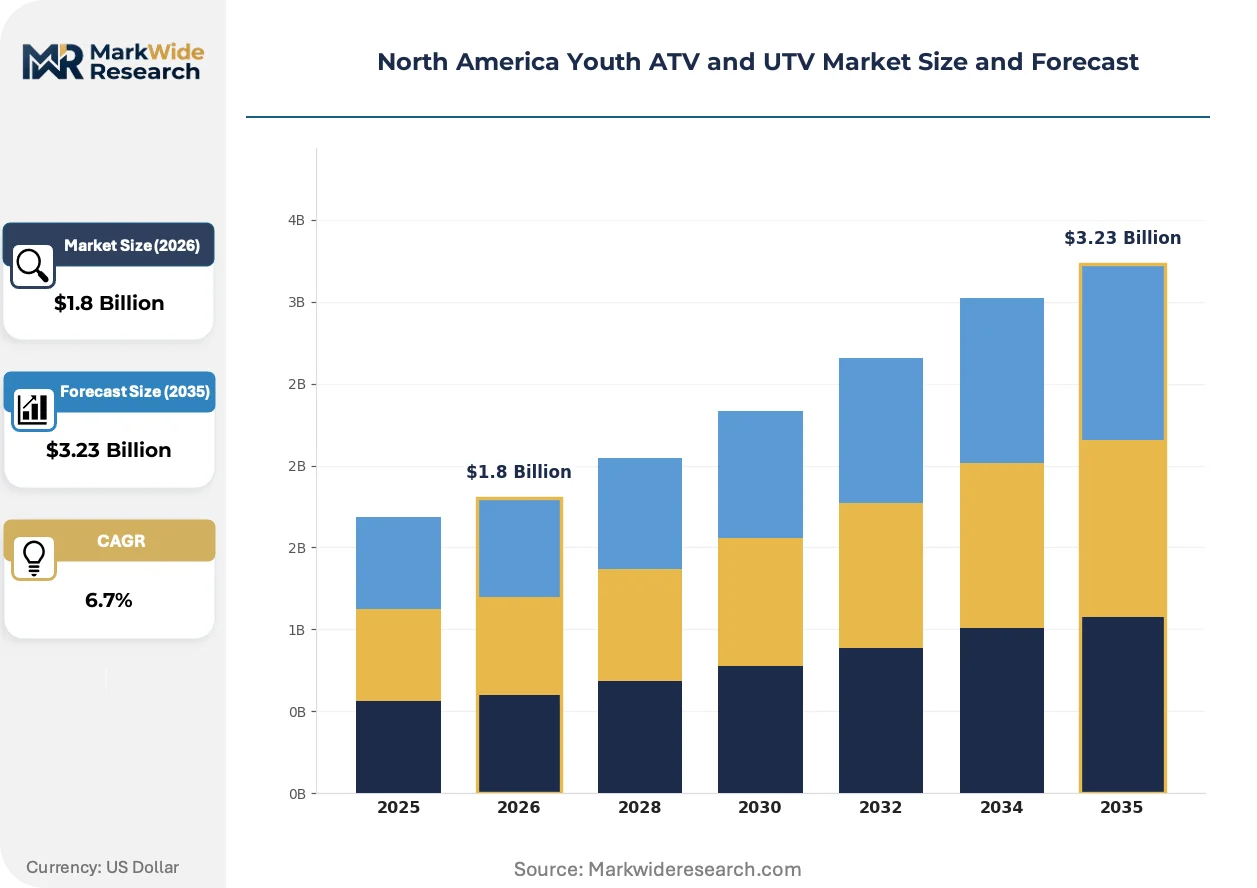
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
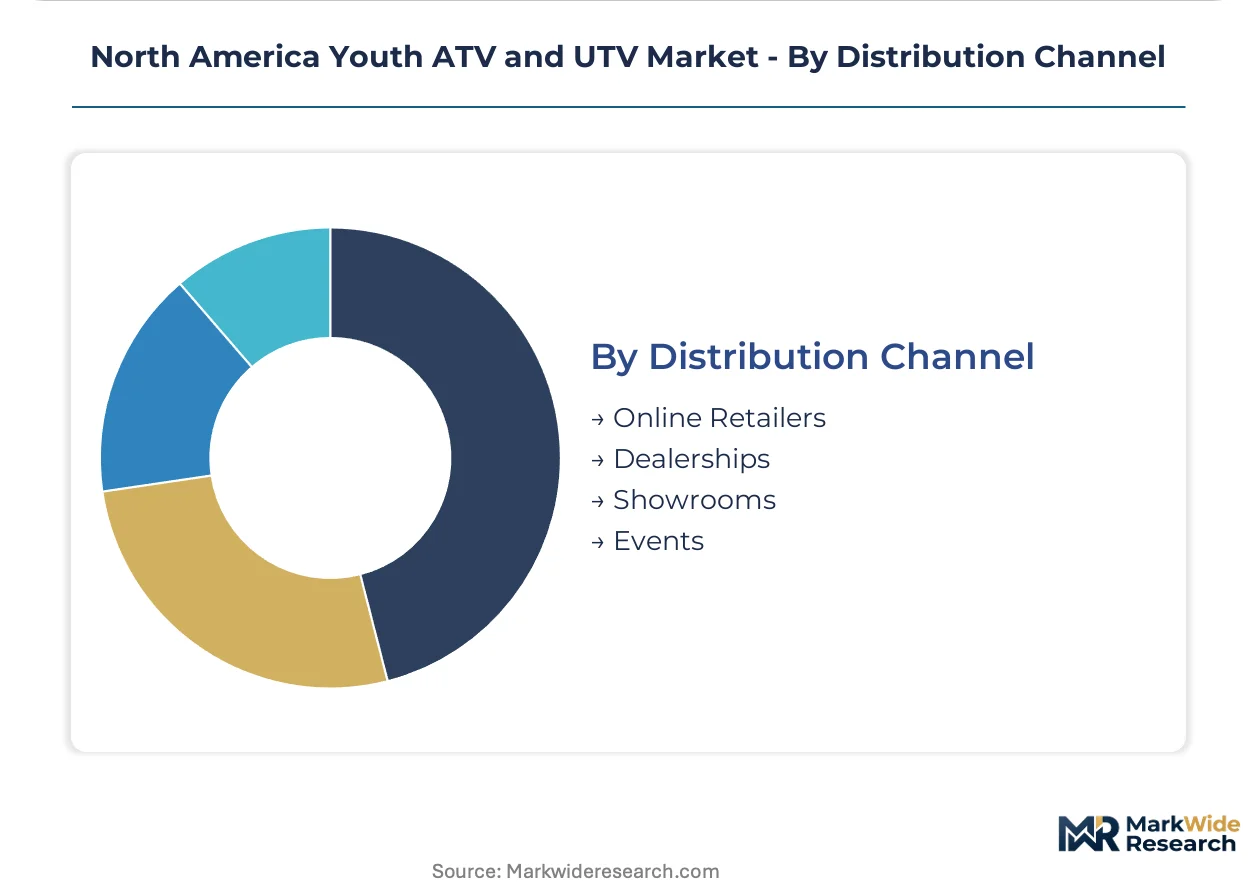
| Segmentation | Product Type: ATV, UTV, Dirt Bike, Go-Kart End User: Recreational Riders, Competitive Racers, Rental Companies, Family Use Engine Capacity: 50cc, 100cc, 200cc, 250cc Distribution Channel: Online Retailers, Dealerships, Showrooms, Events |
| Companies Covered | Yamaha Motor Co. Ltd., Kawasaki Heavy Industries Ltd., Polaris Industries Inc., Kubota Corporation, Textron Inc., BRP Inc., Arctic Cat Inc., CFMOTO, American Honda Motor Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Youth ATV and UTV Market Emerging Trajectories
Electrification pilots and connected-safety systems are restructuring product development priorities. Manufacturers must balance parental control demands against cost constraints while navigating tightening federal and state-level compliance frameworks.
Brushless DC motor and lithium iron phosphate battery packs are miniaturizing powertrain footprints for sub-90cc equivalent performance. Family Use segment buyers in Florida and Georgia are adopting electric youth ATVs at triple-digit annual rates despite price premiums. This technology is miniaturizing component packaging enough to preserve vehicle dimensions while eliminating exhaust emissions and reducing maintenance intervals.
EPA Phase 3 evaporative emissions standards for small spark-ignition engines are tightening permeation limits on fuel tanks and lines. Carburetor-equipped youth models face redesign or discontinuation as manufacturers migrate to electronic fuel injection. The sub-150cc ATV category bears the highest compliance burden, with Texas and California dealers reporting inventory mix shifts toward EFI-equipped 2024 model year units.
Direct-to-consumer configuration tools are displacing traditional dealership inventory selection. Parents in Arizona and Utah now specify safety features, color, and accessory bundles online before pickup at certified delivery points. This channel shift concentrates in states with streamlined OHV registration processes, reducing dealer carrying costs while extending manufacturer working capital cycles.
North America Youth ATV and UTV Market Segmentation
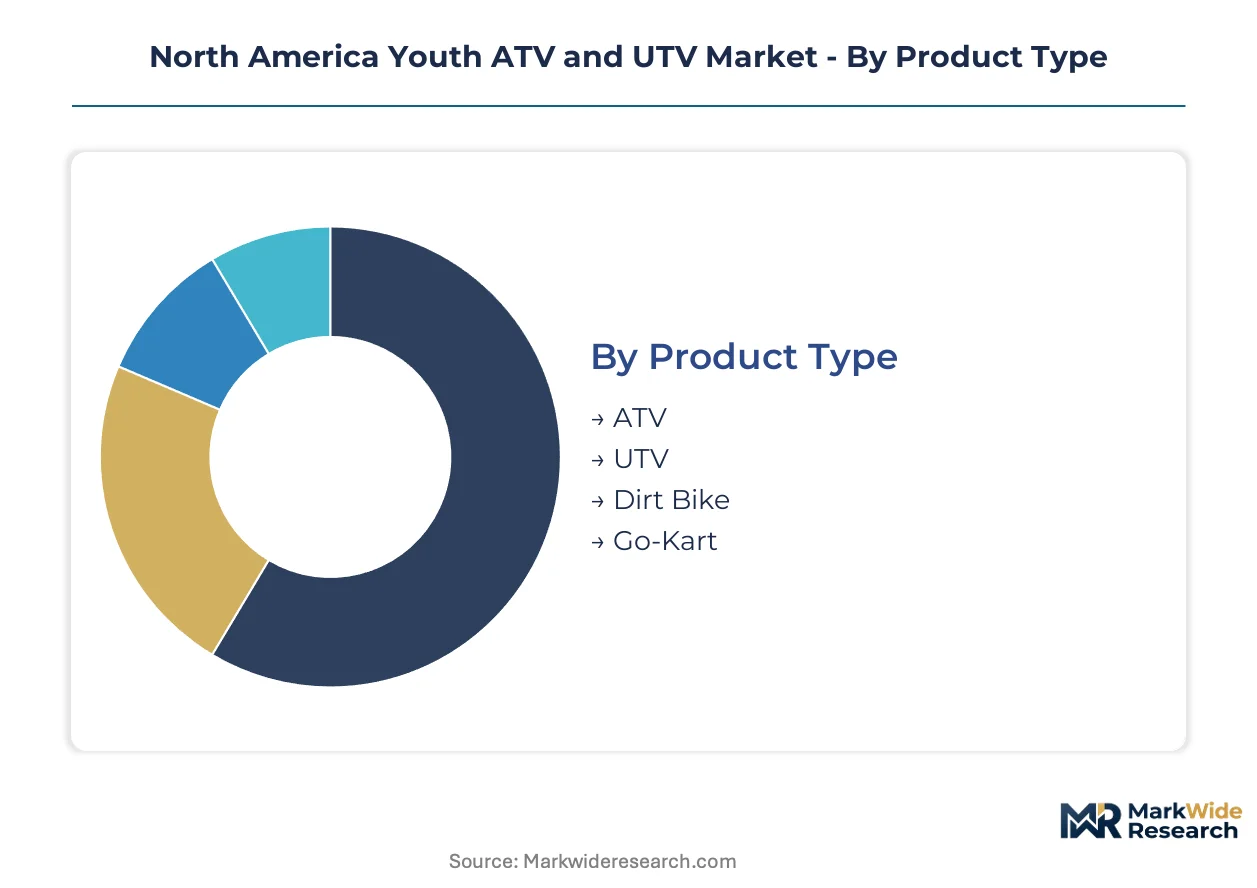
North America Youth ATV and UTV Market segmentation reveals how CPSC certification requirements and state-level trail access rules reshape channel economics. Manufacturers must align product configurations with specific buyer risk profiles and registration compliance burdens.
Product Type:
Dealerships dominate certified gasoline-powered segments, while direct-to-consumer channels capture electric alternatives in states with streamlined OHV registration.
- ATV:Four-wheeled platforms with speed limiters and tethered emergency stops constitute the volume foundation. Texas and Florida dealerships report highest turnover for sub-150cc units used in supervised recreational and light utility tasks on rural properties.
- UTV:Multi-passenger side-by-sides command premium positioning through integrated parental control systems and cargo capacity. Family Use buyers in Georgia and Alabama prioritize these configurations for structured outdoor recreation alternatives to screen-based entertainment.
- Dirt Bike:Two-wheeled youth motorcycles concentrate in competitive racing circuits and specialized training facilities.
- Go-Kart:Closed-course recreational vehicles serve commercial entertainment centers and private estate tracks.
By volume, ATV leads. By growth pace, UTV is ahead.
End User:
Cost tier stratification separates premium parental-control bundles from entry-level recreational configurations.
- Family Use:Parents seeking structured outdoor alternatives drive fastest-expanding demand. GPS geofencing and remote speed-limiting technologies converge with smartphone platforms for subscription-based monitoring services in premium UTV configurations.
- Recreational Riders:Individual youth operators and peer-group riding activities concentrate in southeastern states with year-round trail access.
- Competitive Racers:Sanctioned youth motorsport programs require specialized equipment meeting organizational technical specifications.
- Rental Companies:Commercial fleet operators in Arizona and Utah demand durable platforms with simplified maintenance protocols.
Family Use captures margin premiums. Recreational Riders maintain volume concentration.
Engine Capacity:
Supply concentration among Japanese and Taiwanese component manufacturers shapes availability across displacement categories.
- 50cc:Entry-level youth platforms face CPSC age-grade restrictions. Texas dealers report inventory concentration for introductory riders.
- 100cc:Intermediate displacement bridges supervised training and independent operation.
- 200cc:Performance-oriented configurations serve competitive racing and experienced recreational users.
- 250cc:Upper displacement threshold for youth certification concentrates in utility-task applications on farms and rural estates.
By certification volume, 50cc leads. By utility application expansion, 250cc climbs fastest.
Distribution Channel:
Geography determines channel viability, with state OHV registration complexity filtering online-direct from dealership-dependent segments.
- Dealerships:Certified delivery points dominate CPSC-compliant gasoline-powered sales. Polaris Industries sustains broad coverage across the United States and Canada for youth-certified inventory.
- Online Retailers:Direct-to-consumer configuration tools displace traditional inventory selection in Arizona and Utah, where streamlined registration processes enable pre-specified safety features and accessory bundles.
- Showrooms:Physical demonstration facilities concentrate in southeastern trail-network corridors.
- Events:Temporary retail presence at sanctioned competitions and outdoor recreation expositions.
Dealerships anchor certified product flow. Online Retailers gain share fastest in registration-streamlined states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level OHV registration programs and CPSC certification requirements are redrawing competitive boundaries across North America. Provincial trail access permits in Canada are relaxing age restrictions, while U.S. southeastern states extend year-round riding infrastructure.
United States
Texas, Arizona, and Utah operate streamlined OHV registration systems that accelerate direct-to-consumer channel penetration. EPA Phase 3 evaporative emissions standards force carburetor-equipped youth models toward electronic fuel injection redesigns. Georgia and Alabama have opened new youth-designated riding corridors since 2023, concentrating dealership inventory turnover in the Southeast.
Canada
Alberta and British Columbia trail networks remain underdeveloped relative to U.S. southeastern density, creating expansion headroom. Transport Canada import certification requirements parallel CPSC safety standards, filtering non-compliant manufacturers from retail channels. Provincial OHV permit programs in these western provinces are relaxing youth access age restrictions, stimulating Family Use segment demand.
Mexico
Northern border states concentrate assembly operations serving cross-border supply chains into Texas and Arizona. Mexican environmental regulators apply evolving small-engine emissions thresholds that manufacturers must monitor for future alignment. Monterrey-based industrial clusters support component fabrication for North American youth vehicle platforms.
North America Youth ATV and UTV Market Vendor Landscape
Player mix skews toward diversified powersports conglomerates with established CPSC certification infrastructure. The manufacturer base compresses as federal safety standards disqualify uncertified producers from retail shelf placement. Three strategic archetypes dominate: full-line powersports houses with youth-certified portfolios, agricultural equipment diversifiers leveraging utility-task positioning, and emerging electric specialists piloting brushless powertrains. Competitive moves concentrate on parental control system integration and electrification pilot programs rather than capacity expansion.
Within the full-line powersports tier, Yamaha Motor Co. Ltd. and Polaris Industries Inc. occupy positions defined by engine displacement specialization and dealership coverage breadth respectively. BRP Inc. exemplifies the premium UTV archetype through integrated safety system bundling. These three anchors demonstrate how CPSC compliance infrastructure and parental control technology convergence separate sustainable competitors from market exiters.
| Leading Market Players |
|---|
| Yamaha Motor Co. Ltd. |
| Kawasaki Heavy Industries Ltd. |
| Polaris Industries Inc. |
| Kubota Corporation |
| Textron Inc. |
| BRP Inc. |
| Arctic Cat Inc. |
| CFMOTO |
| American Honda Motor Co. Inc. |
| Others |
Supply Flow & Price Mechanics
Minimum efficient scale in CPSC-certified gasoline engine production concentrates manufacturing among Japanese and Taiwanese suppliers, creating cost floors that electric entrants must undercut through battery pack miniaturization rather than volume leverage. This scale asymmetry shapes price discipline across displacement categories while compressing margins for North American assemblers lacking captive engine supply.
Pricing Analysis
CPSC certification tier creates the primary price spread between entry-level and premium configurations, with EFI-equipped 2024 model year units commanding substantial premiums over carburetor-discontinued inventory. Three-tier pricing structure separates parental-control UTV bundles from standard ATV platforms and economy-grade introductory units. Cost compression in the 50cc entry tier intensifies because steel and aluminum input volatility erodes assembler margins without pricing power. Family Use buyers demonstrate lowest price sensitivity when GPS geofencing and remote speed-limiting technologies are bundled, while Recreational Riders in the Southeast maintain volume concentration at standard tier price points.
Supply Chain Analysis
Strait of Malacca transit underwrites critical lithium iron phosphate cell shipments from Chinese suppliers to North American electric youth vehicle assemblers. Powertrain fabrication draws from Japanese precision casting, Taiwanese electronics integration, and Mexican chassis welding clusters. Single-source vulnerability concentrates in sub-150cc engine supply, where Yamaha and Kawasaki component divisions anchor availability. Distribution runs through certified dealership networks in Texas and Florida, with direct-to-consumer channels penetrating Arizona and Utah where OHV registration streamlining permits pre-configured online specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification pilots and EPA Phase 3 evaporative emissions standards are restructuring product development priorities faster than incumbent certification cycles can absorb, creating asymmetric opportunity for battery-native entrants with brushless powertrain expertise.
For Market Incumbents: Shield certified gasoline portfolio share by accelerating EFI migration ahead of carburetor discontinuation deadlines, while capturing parental control technology through smartphone-integrated subscription bundles that electric specialists cannot replicate without dealership service infrastructure. Absorb steel and aluminum volatility through backward integration into roll-cage fabrication or long-term offtake agreements with Mexican metalworking clusters. Prioritize CPSC certification timeline compression to maintain retail channel exclusivity against uncertified competitors. For New Entrants and Emerging Players: CPSC fast-track certification programs in streamlined registration states create the most penetrable entry corridor, targeting Arizona and Utah direct-to-consumer channels with brushless DC configurations that bypass Japanese engine supply concentration. White-space demand concentrates in Canadian provincial expansion, where Alberta and British Columbia trail network underdevelopment and relaxing age restrictions stimulate Family Use adoption ahead of incumbent dealership coverage buildout. Lead with farm and estate utility positioning rather than recreational trail access, accessing rural property owners through agricultural equipment distributors rather than powersports retail. For Investors and Strategic Acquirers: Electric powertrain engineering boutiques with brushless motor calibration capabilities and lithium iron phosphate pack integration expertise represent the highest-conviction acquisition archetype for long-term viability across the five-to-ten year technology transition window. Battery-electric youth platform manufacturing cost premiums will compress as cell supply scales, but CPSC certification infrastructure and parental control software integration create durable moats for consolidated targets. Monitor EPA emissions threshold acceleration and provincial OHV permit relaxation velocity as inflection indicators for timing strategic deployment.| Strategic Initiative | Industry Significance |
|---|---|
| CPSC Certification Fast-Track | Accelerates retail channel eligibility against 12-18 month standard timelines for uncertified competitors. |
| Parental Control System Integration | Bundles GPS geofencing and remote speed-limiting with smartphone platforms for subscription revenue streams. |
| Canadian Provincial Expansion | Captures Alberta and British Columbia trail network development ahead of incumbent dealership density buildout. |
| Electric Powertrain Miniaturization | Preserves vehicle dimensions while eliminating exhaust emissions and reducing maintenance intervals for Family Use buyers. |
| Farm and Estate Utility Pivot | Accesses rural property owners through agricultural equipment distributors beyond traditional powersports retail channels. |
Methodological Framework
Initial hypotheses were tested against primary input from powersports product managers, CPSC compliance officers, state OHV program administrators, and dealership operations directors, then refined against secondary validation from EPA emissions filings, Transport Canada import certification databases, and state-level vehicle registration statistics. Bottom-up unit shipment estimates by displacement category and end-use segment were cross-checked against top-down market value reconstructions derived from manufacturer revenue disclosures and dealer inventory turnover metrics.
Variance decomposition across the projection horizon isolates volume growth from price-mix effects and segment-shift dynamics, with analytical framework approach modeling product type, engine capacity tier, end-use application, and distribution channel complexity as independent dimensions. CAGRs were synthesized from segment-level growth rates weighted by base-year value shares, incorporating electrification pilot adoption curves and provincial permit relaxation schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable CPSC certification requirements and commodity metal price assumptions; material deviation in regulatory acceleration or tariff regime shifts would warrant model refresh. Practitioners should keep alternative scenarios live as EPA Phase 3 enforcement timing and battery-electric cost compression trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Automotive Trailer Market