
 Fracture Fixation Products Market | 2026-2036
Fracture Fixation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fracture Fixation Products Market Analysis
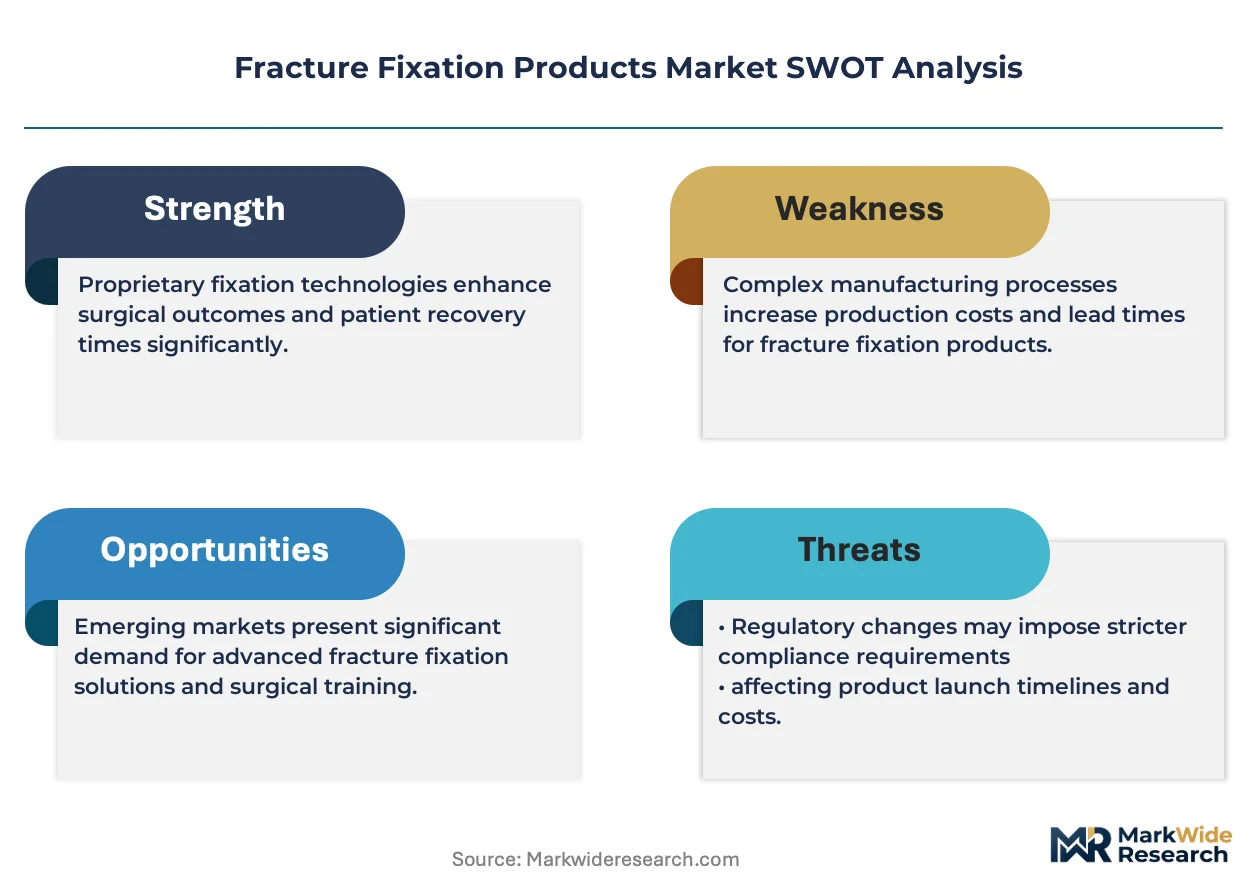
Buyer concentration among hospital networks and integrated delivery systems is recalibrating procurement dynamics across the fracture fixation landscape. Stryker Corporation leverages its trauma platform breadth to sustain contracted supply relationships with major health systems. Zimmer Biomet Holdings Inc. anchors its position through specialized extremity fixation portfolios that dominate ambulatory surgery center channels. DePuy Synthes competes on manufacturing scale across stainless steel and titanium trauma portfolios.
Fracture fixation products encompass metallic and polymeric implants engineered to stabilize bone fragments through mechanical rigidity, with titanium alloys offering strength-to-weight ratios near 110 GPa elastic modulus and bioabsorbable polymers degrading via hydrolysis over 12-24 months. These devices restore anatomical alignment and permit early mobilization in trauma and reconstructive orthopedic procedures. Plates and screws occupy mature, high-volume positions where pricing pressure concentrates, while 3D printing technology is displacing conventional machining in patient-specific anatomic contouring. Minimally invasive surgical approaches are expanding fastest among technology segments as surgeons seek reduced soft-tissue disruption and shorter recovery intervals.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence burdens for manufacturers seeking market access. ISO 5832 material standards and ASTM F138 specifications govern metallic implant biocompatibility and mechanical performance thresholds. Stakeholders must monitor regulatory divergence between FDA and notified body interpretations as MDR implementation tightens post-market surveillance obligations.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins across fracture fixation portfolios, forcing manufacturers to defend position through outcome guarantees and inventory management partnerships rather than product differentiation alone.
Growth Catalysts
- Aging Demographics:Expanding geriatric populations in Germany, Japan, and the United States sustain surgical volumes for osteoporotic fracture repair. Hip and wrist fixation procedures correlate directly with population aging curves.
- FDA 510(k) Pathway Efficiency:Streamlined clearance mechanisms for predicate-based trauma devices accelerate product iteration cycles. Manufacturers leverage substantial equivalence claims to reduce time-to-market for incremental plate and screw innovations.
- Bioabsorbable Polymer Maturation:Hydrolytic degradation profiles now achieve 18-24 month structural integrity windows. Poly-L-lactic acid and polyglycolic acid copolymers eliminate secondary removal surgeries in pediatric and ankle fracture applications.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Chinese smelters control roughly 60% of global titanium sponge feedstock. Western manufacturers face input cost volatility and dual-use export control complications.
- EU MDR Technical Documentation Burden:Clinical evidence requirements for Class III implantable devices have extended approval timelines. Notified body capacity constraints create 12-18 month certification queues.
- Non-Operative Management Resurgence:External fixation and casting protocols for distal radius and clavicle fractures reduce surgical intervention rates. Conservative treatment algorithms challenge volume assumptions in ambulatory settings.
Strategic Opportunities
- India Orthopedic Infrastructure Buildout:Government medical device parks in Andhra Pradesh and Gujarat offer tax holidays and subsidized land. Domestic manufacturing incentives under PLI schemes attract trauma implant assembly operations.
- 3D Printing-Enabled Patient-Specific Plates:Electron beam melting and selective laser sintering converge with preoperative planning software. Complex pelvic and acetabular reconstructions command premium positioning through anatomic fit superiority.
- Ambulatory Surgery Center Penetration:Medicare reimbursement shifts favor same-day discharge for selected extremity procedures. Specialized fixation systems designed for ASC workflow efficiency capture volume migration from inpatient settings.
Industry Challenges
- Biocompatibility Testing Capacity Bottlenecks:ISO 10993 cytotoxicity and sensitization studies face laboratory queue constraints. Extended preclinical timelines compress commercialization windows for novel surface coatings.
- Surgeon Training Standardization:Minimally invasive plate osteosynthesis techniques require cadaveric lab proficiency verification. Fellowship program curriculum heterogeneity limits technique adoption consistency across health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fracture Fixation Products Market |
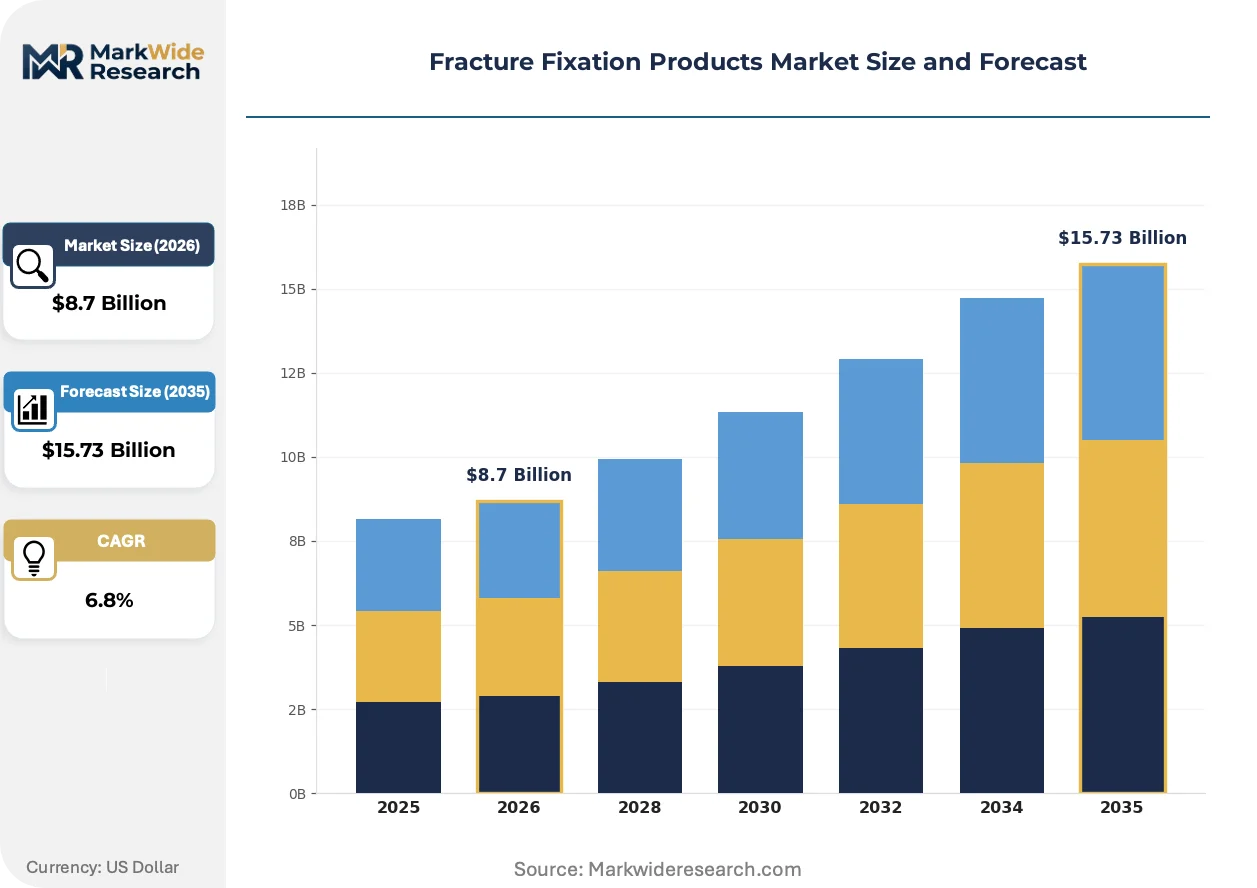
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Rods, Nails Material: Stainless Steel, Titanium, Bioabsorbable Polymers, Composite Materials End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Emergency Departments Technology: Minimally Invasive, Open Surgery, 3D Printing, Image-Guided Surgery |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings Inc., DePuy Synthes, Smith & Nephew plc, Medtronic plc, Orthofix Medical Inc., Arthrex Inc., Globus Medical Inc., Acumed LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fracture Fixation Products Market Emerging Trajectories
Digital surgical planning and additive manufacturing are converging to displace conventional trauma implant production, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for biomechanical performance claims.
Patient-specific 3D-printed titanium plates are expanding into complex periarticular fracture reconstruction. Academic medical centers in the United States and university hospitals in Germany now commission additive-manufactured implants for 15-20% of pelvic trauma cases. This technology is expanding into community hospital settings as printing service bureaus reduce capital barriers and turnaround times compress below 72 hours.
EU MDR post-market clinical follow-up obligations now mandate systematic implant retrieval analysis and registry data submission. Manufacturers must maintain traceability systems linking specific device lots to patient outcomes across 10-15 year lifecycles. Small and mid-cap trauma specialists face disproportionate compliance cost burdens relative to diversified orthopedic conglomerates with established surveillance infrastructure.
Integrated delivery networks in the United States now contract for trauma implant categories through centralized value analysis committees. Surgeons retain preference input, but procurement teams negotiate standardized pricing across health system footprints. This concentration is most visible in the Southeast and Midwest, where Catholic health initiatives and for-profit chains have consolidated purchasing for 40-60 hospital networks under single master agreements.
Fracture Fixation Products Market Segmentation
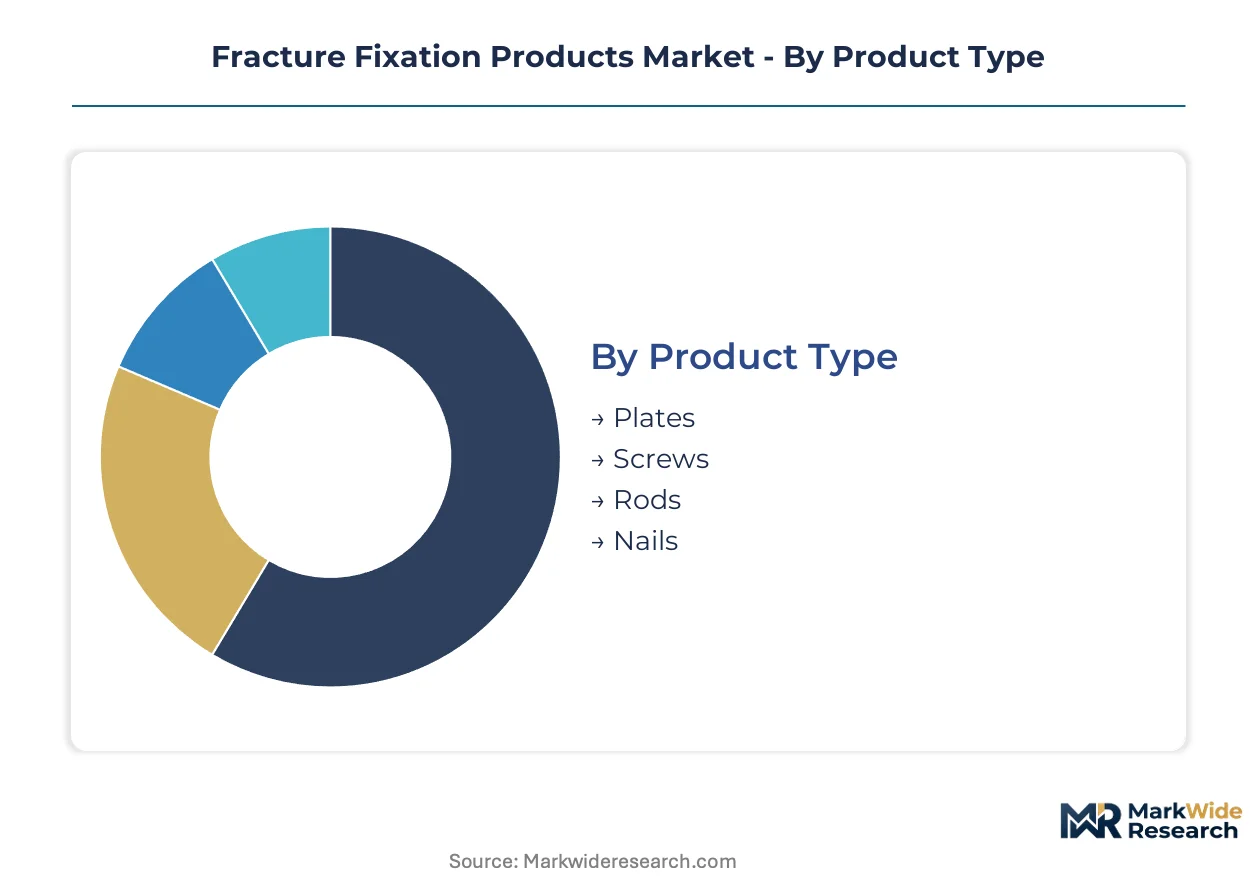
Segmentation in fracture fixation reveals distinct procurement patterns across implant categories. Material selection and surgical approach determine reimbursement pathways and inventory turnover velocity for hospital networks.
Product Type:
Standalone plates and screws dominate high-volume trauma procedures, while intramedullary devices embed into complex long-bone reconstruction workflows.
- Plates:Metallic and polymeric plates span locking compression, limited contact dynamic compression, and reconstruction geometries. Demand clusters in United States academic trauma centers where pelvic and periarticular fracture volumes sustain specialized inventory. Pricing pressure from group purchasing organizations compresses margin on standard small-fragment sets.
- Screws:Cortical, cancellous, and locking screw configurations deliver fragment stabilization across fracture patterns. Germany's orthopedic hospitals maintain the densest per-capita screw consumption in Europe, driven by AO Foundation technique standardization and fellowship training density.
- Rods:Intramullary rods stabilize femoral and tibial shaft fractures through load-sharing mechanics. These devices integrate into minimally invasive surgical suites requiring fluoroscopy-compatible operating tables.
- Nails:Interlocking nails address comminuted long-bone fractures with rotational stability. China manufactures the majority of stainless steel trauma nails for domestic hospital procurement.
Volume placements concentrate in Plates; the faster expansion belongs to Nails as intramedullary techniques displace plate fixation in diaphyseal trauma.
Material:
Cost stratification separates premium titanium from economy stainless steel tiers, with bioabsorbable polymers occupying a narrow specialty niche.
- Stainless Steel:ASTM F138-compliant austenitic stainless delivers cost-efficient fixation for temporary or resource-constrained settings. Indian government hospitals under CDSCO procurement guidelines specify 316L grade for bulk trauma implant purchases.
- Titanium:Ti-6Al-4V ELI and commercially pure titanium offer modulus matching closer to cortical bone. United States trauma centers specify titanium for osteoporotic patient populations where stress shielding risks complicate healing.
- Bioabsorbable Polymers:Poly-L-lactic acid and polyglycolic acid copolymers hydrolyze over 18-24 months. Pediatric ankle fracture applications in Japan's university hospitals drive adoption where secondary removal surgery avoidance carries premium value.
- Composite Materials:Carbon fiber-reinforced polymers and PEEK-based constructs address radiolucency requirements in tumor reconstruction. These materials embed into patient-specific 3D-printed workflows for complex pelvic oncology cases.
Stainless Steel captures the highest placement volumes; Titanium claims the steepest expansion trajectory as aging demographics elevate osteoporotic fracture repair demand.
End User:
Customer type determines packaging, sterilization, and instrumentation bundling requirements across the procurement spectrum.
- Hospitals:Level I trauma centers and community hospitals constitute the dominant consumption node. Integrated delivery networks in the United States negotiate master agreements covering plate, screw, and nail categories across 40-60 facility footprints.
- Orthopedic Clinics:Ambulatory surgery centers and specialty clinics drive demand for streamlined instrument sets and single-use sterile packaging. Medicare reimbursement shifts toward same-day discharge accelerate extremity fixation volume migration to these settings.
- Rehabilitation Centers:Post-acute facilities manage external fixation device adjustments and hardware removal scheduling. These centers coordinate with implanting surgeons for staged care protocols.
- Emergency Departments:EDs initiate provisional stabilization with external fixation and temporary spanning constructs. Rural emergency departments in Germany maintain limited inventory for damage-control orthopedics prior to referral.
Hospitals absorb the dominant placement share; Orthopedic Clinics are climbing the fastest as volume shifts toward ambulatory surgical settings.
Technology:
Surgical approach maturity separates established open techniques from emerging image-guided and additive manufacturing modalities.
- Minimally Invasive:Percutaneous plate osteosynthesis and intramedullary nailing reduce soft-tissue disruption. Fellowship-trained surgeons at United States academic centers drive technique adoption through cadaveric lab certification programs.
- Open Surgery:Direct reduction and plate application remain standard for articular fracture reconstruction. These procedures require extensive surgical exposure and carry higher infection risk profiles.
- 3D Printing:Electron beam melting produces patient-specific titanium plates from preoperative CT segmentation. Germany's university hospitals now commission additive-manufactured pelvic implants for 15-20% of complex acetabular fracture cases.
- Image-Guided Surgery:Intraoperative CT and navigation systems enable percutaneous screw placement in spinal and pelvic trauma. Capital equipment requirements limit deployment to tertiary referral centers.
Open Surgery retains the highest procedure volume; 3D Printing gains share fastest as printing service bureaus compress turnaround below 72 hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fracture fixation products concentrates in health systems with dense trauma center networks and aging patient populations. Surgical volumes track directly with road injury incidence and osteoporosis prevalence curves. Regulatory frameworks in major economies now mandate extended post-market surveillance, reshaping manufacturer compliance investments.
United States
Level I trauma centers in Houston, Baltimore, and Los Angeles sustain high-volume pelvic and periarticular fracture repair. FDA 510(k) pathway efficiencies accelerate predicate-based clearances for incremental plate designs. The Southeast and Midwest host integrated delivery networks consolidating procurement across 40-60 hospital footprints under single master agreements.
Germany
University hospitals in Berlin, Hamburg, and Munich drive adoption of patient-specific 3D-printed titanium implants for complex acetabular reconstruction. EU MDR technical documentation requirements extend certification timelines through notified body capacity constraints. The AO Foundation's headquarters in Davos, Switzerland, anchors German-speaking fellowship training density.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces supply stainless steel trauma nails for hospital procurement under centralized tendering. NMPA regulatory harmonization with international standards accelerates import substitution for premium titanium portfolios. Shanghai and Beijing academic centers pioneer robotic-assisted intramedullary nailing techniques.
India
Government medical device parks in Andhra Pradesh and Gujarat attract trauma implant assembly through PLI scheme subsidies and tax holidays. CDSCO procurement guidelines specify 316L stainless steel for bulk public hospital purchases. Maharashtra's private hospital networks in Mumbai and Pune drive premium titanium adoption for osteoporotic hip fracture repair.
Japan
University hospitals in Tokyo and Osaka prioritize bioabsorbable polymer fixation for pediatric ankle fractures to eliminate secondary removal surgeries. PMDA post-market surveillance requirements align with global ISO 14155 clinical investigation standards. The Kansai region's aging demographic sustains wrist and hip fixation procedure volumes.
Fracture Fixation Products Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and bioabsorbable material niches. The vendor base stratifies across diversified orthopedic conglomerates with full trauma portfolios and mid-cap specialists concentrating on extremity or pelvic sub-segments. Three archetypes dominate: scale-driven manufacturers defending contracted supply relationships, technology licensors monetizing surface coating and 3D printing IP, and regional assemblers capturing price-sensitive public hospital procurement. Competitive moves center on manufacturing partnerships in India and China, plus patient-specific implant service bureau acquisitions.
Among US-based diversified orthopedic manufacturers, Stryker Corporation, Zimmer Biomet Holdings Inc., and DePuy Synthes exemplify scale-driven archetypes with integrated trauma platforms. These entities anchor contracted supply positions through health system master agreements and inventory management partnerships. Their geographic footprint spans domestic manufacturing and Asian assembly partnerships, positioning them to navigate titanium sponge supply volatility and dual-use export control complications.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| DePuy Synthes |
| Smith & Nephew plc |
| Medtronic plc |
| Orthofix Medical Inc. |
| Arthrex Inc. |
| Globus Medical Inc. |
| Acumed LLC |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing adoption in patient-specific titanium plate production simultaneously compresses per-unit tooling costs and fragments supplier concentration away from centralized forging operations toward distributed printing service bureaus. This technology shift feeds back into procurement dynamics as hospital networks negotiate print-on-demand contracts that bypass traditional inventory carrying costs while exposing them to titanium powder supply volatility.
Pricing Analysis
High-volume plates and screws trade on razor-thin margins while patient-specific 3D-printed constructs command premium positioning. Pricing stratifies across premium titanium alloys for osteoporotic populations, standard stainless steel for trauma centers, and economy-grade imports for public hospital tenders. Cost compression in standard fixation sets intensifies as group purchasing organizations consolidate contract awards across integrated delivery networks. Ambulatory surgery centers exhibit the sharpest price sensitivity due to Medicare reimbursement compression, whereas academic trauma centers prioritize anatomic fit and outcomes over unit cost.
Supply Chain Analysis
Titanium sponge feedstock rests on Russian and Chinese smelters controlling the majority of global primary metal output. Western manufacturers source Ti-6Al-4V ELI billet from Japanese and US specialty alloy producers while bioabsorbable polymer resin feeds from European and Chinese chemical suppliers. Single-source vulnerability in titanium sponge concentrates geographic risk exposure for FDA-registered device manufacturers facing dual-use export control complications. Distribution runs through manufacturer-direct sales forces serving hospital networks, supplemented by specialized orthopedic distributors for ambulatory surgery center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium sponge capacity constraints prop pricing power for Western alloy producers, creating a supply-constrained market structure where feedstock security determines competitive viability more than device innovation alone.
For Market Incumbents: Cement contracted supply positions through multi-year titanium sponge offtake agreements with Japanese and US alloy producers. Deepen backward integration into electron beam melting service bureaus to capture patient-specific plate margins before specialty 3D printing firms consolidate. Threat exposure from Chinese domestic manufacturers under NMPA harmonization demands defensive patent portfolio investments in surface coating technologies. For New Entrants and Emerging Players: Enter via bioabsorbable polymer ankle fixation systems for pediatric applications in Japanese university hospitals where secondary surgery avoidance carries premium pricing tolerance. White-space availability concentrates in Indian government medical device parks offering PLI scheme subsidies for trauma implant assembly. Go-to-market execution requires CDSCO registration pathway navigation paired with state tendering office relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking additive manufacturing capabilities. Long-term viability favors mid-cap specialists with secured titanium feedstock and FDA 510(k) clearance infrastructure over pure-play 3D printing service bureaus lacking regulatory dossier depth. Watch NMPA import substitution acceleration as inflection signal for Chinese domestic manufacturer valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Titanium Sponge Supply Agreement | Long-term offtake contracts with Japanese alloy producers insulate Western manufacturers from export control disruption. |
| 3D Printing Service Bureau Acquisition | Patient-specific plate capabilities compress turnaround below 72 hours for pelvic trauma reconstruction cases. |
| EU MDR Technical Documentation Investment | Notified body certification queues create 12-18 month barriers for undercapitalized competitors lacking surveillance infrastructure. |
| India PLI Scheme Manufacturing Entry | Andhra Pradesh medical device parks offer tax holidays attracting trauma implant assembly for price-sensitive public tenders. |
| Ambulatory Surgery Center Workflow Design | Streamlined instrument sets capture Medicare reimbursement shift toward same-day discharge for extremity procedures. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR notified body certification records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with orthopedic trauma surgeons, hospital GPO contracts managers, biomedical engineers, and titanium alloy procurement leads at device manufacturers informed demand dynamics and supply chain vulnerability assessment. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Historical trendline analysis of surgical procedure volumes, implant unit shipments, and material cost indices anchored the forecast framework. Segmentation modeling spanned product type, material grade, end-user facility tier, and surgical approach technology across the projection horizon. CAGRs derived from regression analysis against aging demographic curves, road injury incidence data, and regulatory approval velocity metrics. Titanium sponge price volatility and notified body capacity constraints fed into scenario-weighted outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under titanium sponge supply disruption or accelerated EU MDR enforcement. Forecasts reflect assumptions regarding procedural shift toward minimally invasive techniques and ambulatory migration. Titanium export control expansion, NMPA harmonization pace, and bioabsorbable polymer degradation profile advances warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pleural Catheters Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Sensor Based Smart Catheters Market