
 India Contraceptive Devices Market | 2026-2036
India Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Contraceptive Devices Market Foresight
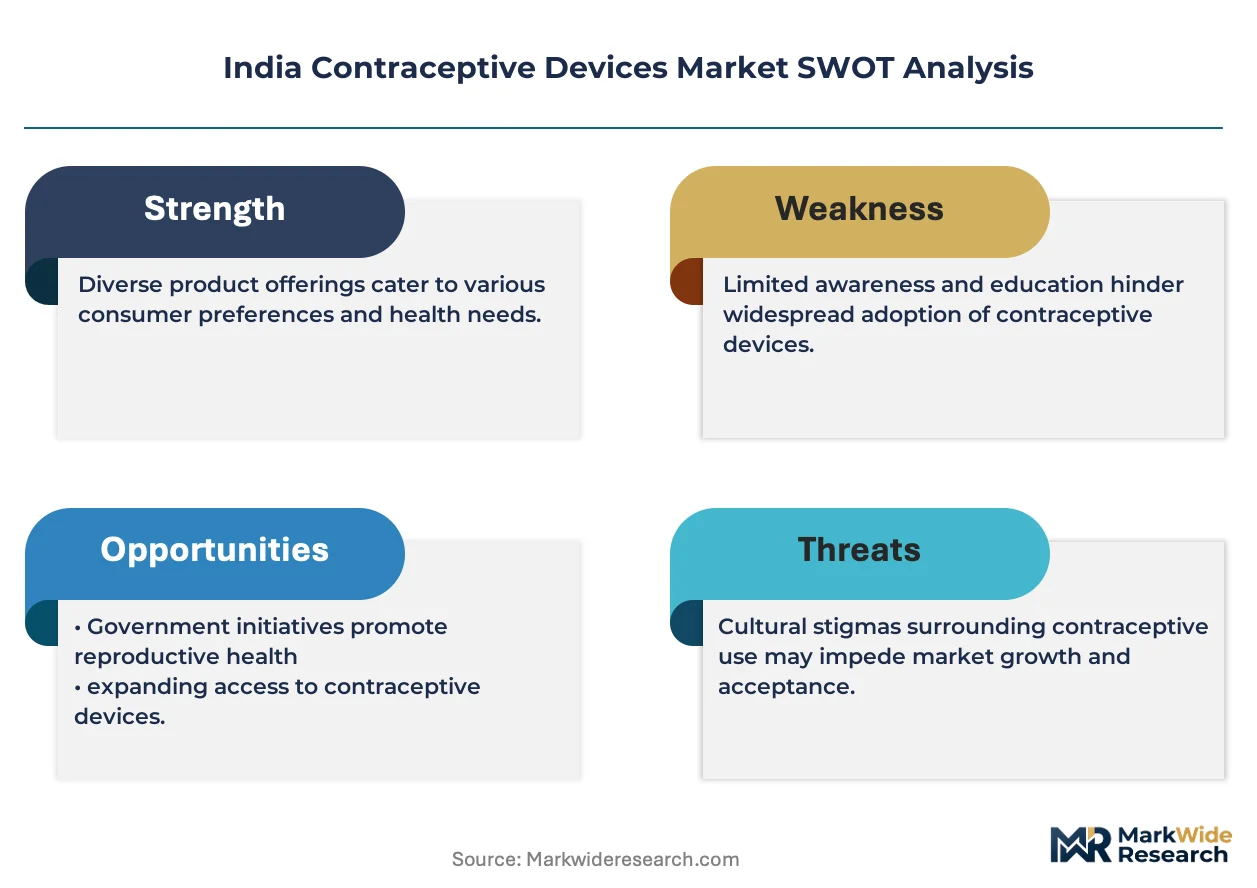
Microfinance-linked distribution and pay-per-use clinic models is fragmenting capital requirements across India's contraceptive devices landscape, enabling smaller regional entrants to challenge established supply chains. Bayer AG leverages its hormonal IUD technology leadership to sustain premium positioning in tertiary hospital procurement. Lupin Pharmaceuticals Ltd anchors its competitive stance through backward integration into active pharmaceutical ingredient production for oral contraceptives. Church & Dwight Co Inc competes via mass-market condom brands with extensive rural reach through general trade channels.
Contraceptive devices encompass physical and pharmaceutical products engineered to prevent pregnancy through barrier methods, hormonal regulation, or intrauterine mechanical action, with specifications ranging from latex tensile strength in male condoms to levonorgestrel release rates in hormonal IUDs measured in micrograms per day. These products serve India's public health infrastructure, private clinical practice, and direct-to-consumer retail channels for fertility management and family planning outcomes. Condoms dominate volume throughput across pharmacy and general trade distribution channels due to low unit cost and minimal clinical intervention requirements. IUDs capture concentrated margin pools through insertion procedure fees and multi-year efficacy cycles that reduce replacement frequency. Online retail represents the fastest-growing distribution channel as telemedicine platforms and e-pharmacy regulations mature, though hospital and clinic channels retain preference for implant and IUD administration.
CDSCO's Medical Device Rules classify contraceptive products across risk-based categories that determine import licensing, clinical evaluation requirements, and post-market surveillance obligations for domestic and foreign manufacturers. BIS standards for latex condoms and the National Family Planning Program's procurement specifications shape product formulation, packaging, and pricing accessible to government channel distribution. India's PLI scheme for medical devices creates manufacturing cost advantages for domestic producers of condoms and disposable contraceptive supplies. Stakeholders must monitor CDSCO's evolving risk classification for hormonal implants and the central government's Essential Medicines List revisions that determine public sector contraceptive procurement priorities.
Market Dynamics
CDSCO's Medical Device Rules are compressing product registration timelines while tightening post-market surveillance obligations, forcing domestic and foreign manufacturers to reconfigure quality management systems and clinical documentation practices for hormonal implants and barrier contraceptives alike.
Growth Catalysts
- National Family Planning Program procurement expansion:Government hospitals and primary health centers are scaling long-acting reversible contraceptive purchases, creating predictable volume commitments for domestic suppliers.
- PLI scheme for medical devices:Manufacturing cost advantages are accruing to domestic condom and disposable supply producers, narrowing price gaps with imported alternatives.
- Telemedicine platform maturation:E-pharmacy regulations are enabling direct-to-consumer channels for oral contraceptives and condoms, bypassing traditional pharmacy distribution in Maharashtra and Karnataka urban clusters.
Market Restraints
- Latex input cost volatility:Natural rubber price fluctuations are squeezing margin structures for domestic condom manufacturers dependent on Kerala and Tamil Nadu rubber belt supply.
- Import licensing concentration:CDSCO's risk-based classification system creates bottlenecks for hormonal implant market entry, privileging established multinational dossiers over new applicants.
- Copper IUD substitution pressure:Non-hormonal mechanical devices face preference erosion as levonorgestrel-releasing systems demonstrate superior bleeding control in tertiary hospital settings.
Strategic Opportunities
- Rural Bihar and Uttar Pradesh underpenetration:General trade channel expansion for condoms remains below saturation in northern plains districts, offering volume growth for mass-market brands.
- Pay-per-use clinic models:Microfinance-linked distribution is fragmenting capital requirements, enabling regional entrants to challenge established supply chains through asset-light service delivery.
- Backward integration into API production:Domestic pharmaceutical manufacturers are capturing margin pools previously ceded to Chinese and European active pharmaceutical ingredient suppliers for oral contraceptive formulations.
Industry Challenges
- CDSCO clinical evaluation timeline compression:Accelerated device approval pathways demand simultaneous quality system upgrades and dossier preparation, straining regulatory affairs capacity at mid-tier manufacturers.
- Insertion procedure skill scarcity:IUD and implant administration training gaps persist in primary health centers, limiting product uptake despite procurement availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Contraceptive Devices Market |
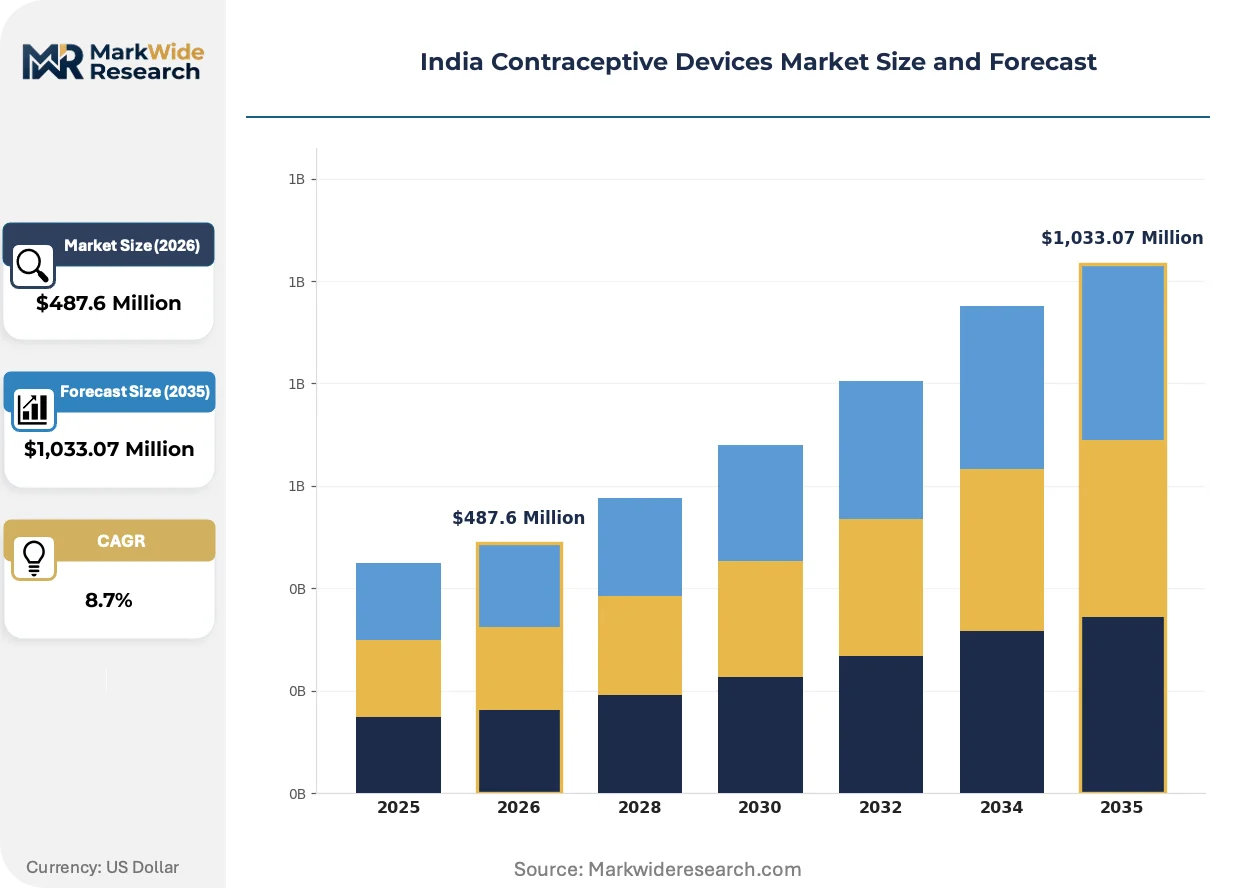
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Condoms, IUDs, Pills, Implants Distribution Channel: Pharmacies, Hospitals, Clinics, Online Retail End User: Individuals, Couples, Healthcare Providers, NGOs Usage Frequency: Daily, Monthly, As Needed, On-Demand |
| Companies Covered | AbbVie Inc, Church & Dwight Co Inc, Bayer AG, Lupin Pharmaceuticals Ltd, Johnson & Johnson, Merck & Co Inc, Reckitt Benckiser Group plc, Cupid Limited, CooperSurgical Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Contraceptive Devices Market Shifts & Advancements
Hormonal delivery mechanisms and digital distribution infrastructure are converging to reshape competitive positioning across India's contraceptive devices landscape, with implications for manufacturing scale, channel economics, and clinical service integration.
Biodegradable polymer technology for subdermal implants is collapsing the distinction between short-acting and long-acting hormonal methods, enabling three-year efficacy cycles with simplified removal procedures. Tertiary hospital gynecology departments in Chennai and Bengaluru are piloting these systems ahead of broader CDSCO registration. The technology is collapsing replacement frequency expectations and associated clinic visit revenue models.
CDSCO's 2023 amendment to Medical Device Rules for in-vitro diagnostic and implantable categories is extending clinical investigation requirements to next-generation hormonal IUDs with modified release profiles. Domestic manufacturers must now generate India-specific safety and efficacy data rather than relying solely on foreign regulatory approvals. Tamil Nadu-based contract research organizations are capturing expanded pharmacovigilance service contracts from multinational sponsors seeking accelerated market entry.
Urban clinic networks in Maharashtra are unbundling contraceptive counseling from product dispensing, creating separate revenue streams for teleconsultation services and in-clinic procedure fees. Pharmacy chains are responding with staffed consultation corners in Mumbai and Pune outlets. This bifurcation is most visible in metropolitan markets where digital health platform subscriptions now outpace traditional over-the-counter purchase frequency for oral contraceptives.
India Contraceptive Devices Market Segmentation
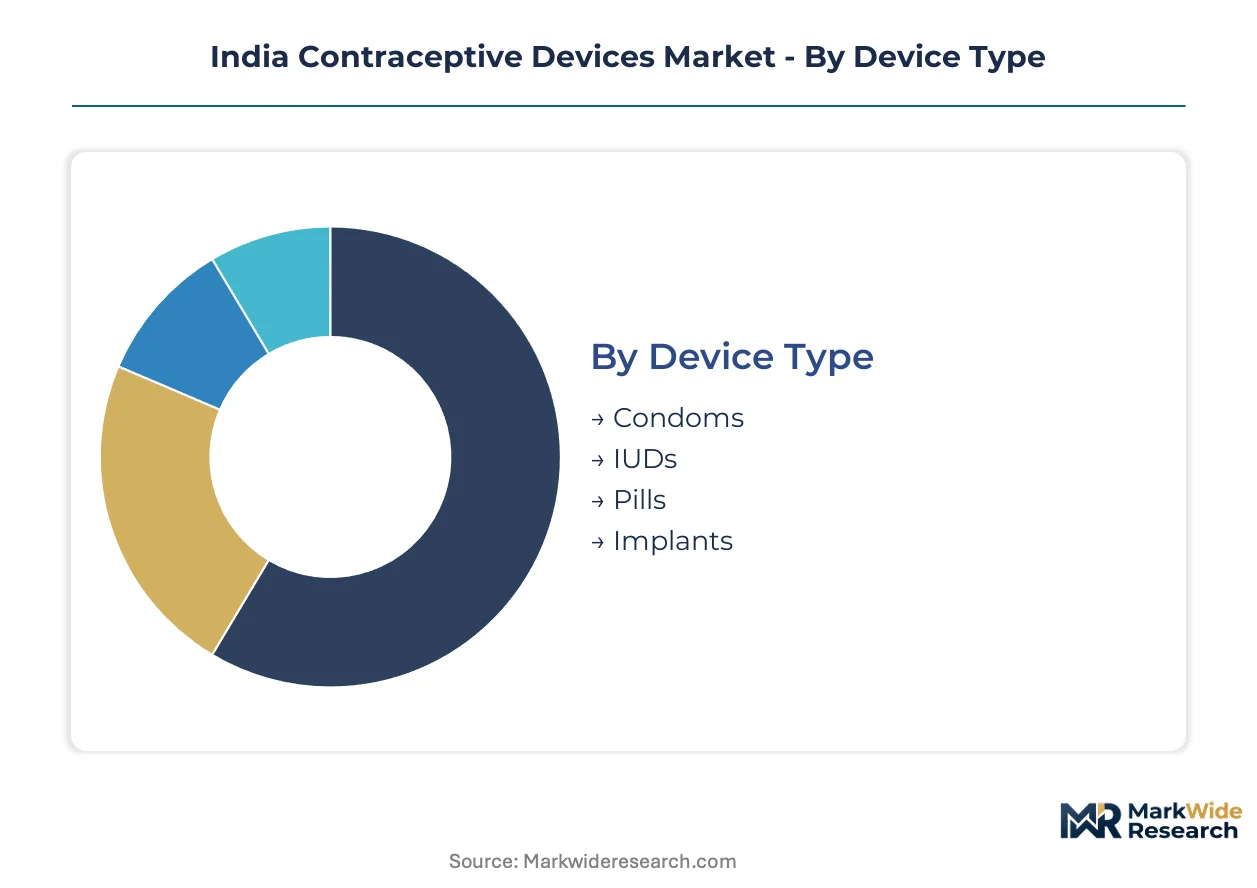
Segmentation in India's contraceptive devices market reveals distinct procurement rhythms and margin structures across product categories. Cycle times range from single-use disposable units to multi-year implant systems, reshaping inventory management and channel economics for manufacturers and distributors alike.
Device Type:
Replacement cycles stretch from hours to years across this category, compressing working capital needs for barrier methods while extending revenue recognition windows for long-acting systems.
- IUDs:Intrauterine devices deploy copper or levonorgestrel-releasing mechanisms with efficacy spanning three to ten years. Tertiary hospitals in Tamil Nadu and Karnataka concentrate demand as insertion procedure fees supplement device margins, though CDSCO's tightened clinical evaluation timelines delay next-generation product launches.
- Condoms:Latex and polyurethane barrier products dominate pharmacy throughput with lowest per-unit cost and zero clinical intervention. Maharashtra's urban clusters drive volume through general trade channels, while Kerala's rubber belt supply exposes manufacturers to raw material price swings.
- Pills:Oral hormonal contraceptives require daily adherence and monthly resupply cycles.
- Implants:Subdermal rods release progestin over three-year periods with highest upfront procurement value.
IUDs dominate installed base through government hospital procurement. Condoms are where expansion concentrates via e-pharmacy channel maturation.
Distribution Channel:
Channel selection determines price realization and regulatory exposure, with institutional buyers extracting volume discounts while direct-to-consumer platforms capture premium margins.
- Online Retail:Telemedicine-integrated e-pharmacies bypass traditional pharmacy networks for condoms and oral contraceptives. Mumbai and Pune metropolitan zones exhibit fastest platform subscription growth, though CDSCO's evolving e-pharmacy regulations create compliance uncertainty for cross-border shipments.
- Hospitals:Government hospitals and primary health centers anchor public sector procurement under the National Family Planning Program. Bihar and Uttar Pradesh districts show persistent supply gaps despite expanding procurement budgets.
- Pharmacies:Brick-and-mortar retail maintains OTC dominance for condoms and emergency contraception.
- Clinics:Private gynecology practices capture insertion fees for IUDs and implants alongside counseling services.
Hospitals dominate installed base through programmatic procurement. Online retail is climbing the fastest as digital health infrastructure matures.
End User:
User type shapes product positioning, with institutional purchasers prioritizing cost minimization and individual buyers responding to convenience and discretion signals.
- Healthcare Providers:Government physicians and private gynecologists function as gatekeepers for IUD and implant adoption. Primary health centers in northern plains states face persistent insertion training gaps that constrain product uptake despite device availability.
- Individuals:Single women and men purchasing condoms and oral contraceptives through retail channels prioritize accessibility and anonymity. Urban Karnataka shows highest direct-to-consumer platform engagement.
- Couples:Joint decision-making units select between coital-dependent and coital-independent methods.
- NGOs:Non-governmental organizations distribute subsidized products through community health worker networks.
Healthcare providers dominate installed base through clinical authority. Individuals are gaining share fastest as telemedicine reduces consultation friction.
Usage Frequency:
Frequency of use correlates with adherence burden and method failure rates, driving preference shifts toward lower-maintenance alternatives in tertiary care settings.
- As Needed:Coitus-dependent barrier methods require no ongoing physiological intervention. Rural Bihar general trade channels sustain volume for mass-market condom brands with minimal clinical counseling.
- Monthly:Injectable and patch-based hormonal systems demand periodic healthcare contact. Urban clinic networks in Maharashtra pilot subscription models combining product delivery with teleconsultation.
- Daily:Oral contraceptive pills impose highest adherence burden with corresponding real-world efficacy gaps.
- On-Demand:Emergency contraception serves backup use cases with limited repeat purchase frequency.
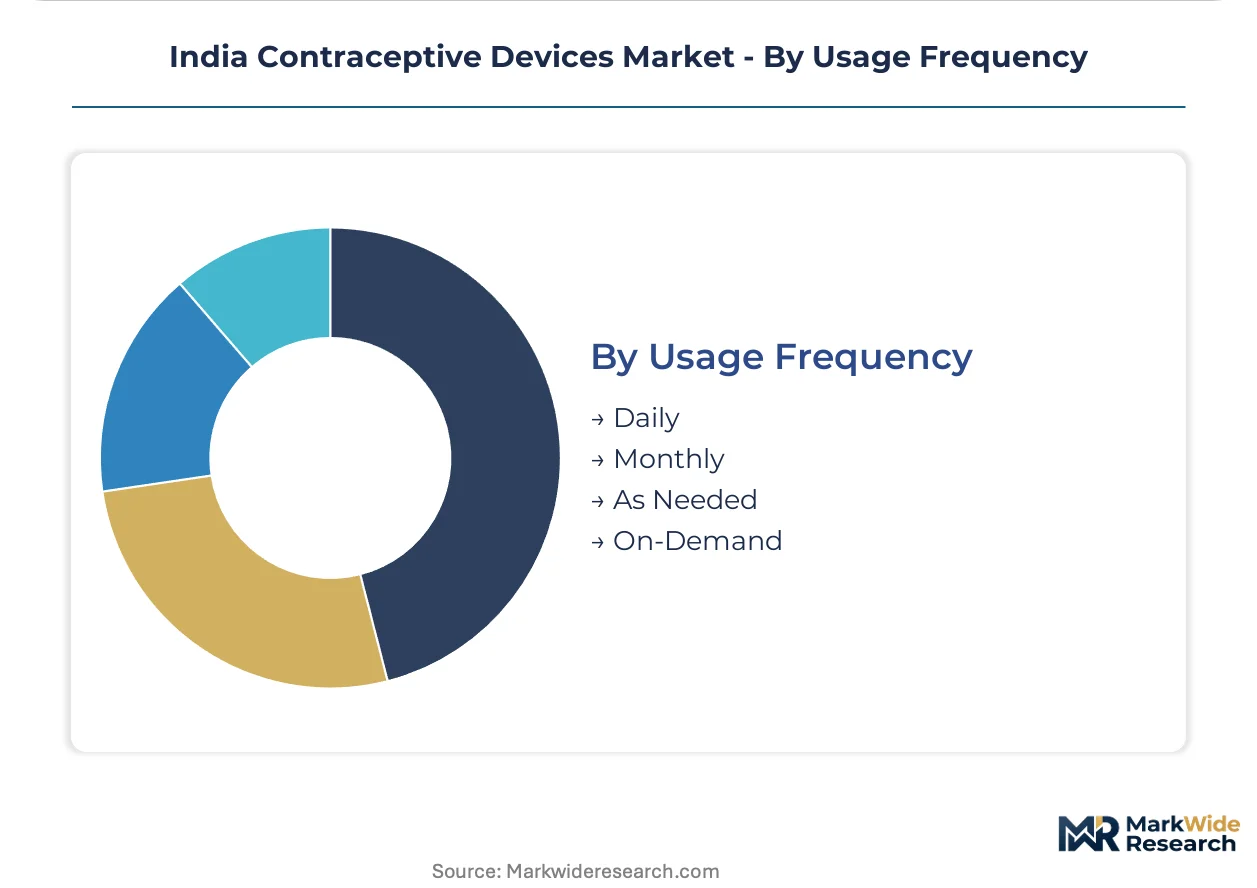
As Needed dominates installed base through condom ubiquity. Monthly is where expansion concentrates as clinic-based subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is redistributing manufacturing capacity toward states with established pharmaceutical infrastructure. State-level procurement under the National Family Planning Program creates divergent demand patterns across northern plains and southern industrial corridors.
Maharashtra
Mumbai and Pune metropolitan zones drive e-pharmacy subscription growth for oral contraceptives and condoms. CDSCO's regional office in Mumbai processes device registration dossiers for hormonal implants and IUDs. Urban clinic networks in these cities unbundle counseling from dispensing, creating separate revenue streams for teleconsultation services.
Karnataka
Bengaluru's tertiary hospital gynecology departments pilot biodegradable polymer subdermal implants ahead of broader CDSCO registration. The state's pharmaceutical distribution hubs concentrate inventory for southern region supply. Direct-to-consumer platform engagement runs highest here among Indian states.
Tamil Nadu
Chennai anchors IUD insertion procedure volume through government hospital procurement under the National Family Planning Program. Contract research organizations in the state capture pharmacovigilance service contracts from multinational sponsors. Kerala's rubber belt supply exposes condom manufacturers to raw material price volatility.
Bihar
Rural general trade channels sustain mass-market condom volume with minimal clinical counseling penetration. Primary health centers face persistent insertion training gaps that constrain IUD uptake despite device availability. Northern plains districts remain below saturation for family planning product distribution.
Uttarakhand
Hilly terrain fragments supply chain reach for long-acting reversible contraceptives requiring clinical administration. Government procurement budgets expand faster than last-mile delivery infrastructure. Dehradun's medical colleges train cadres for implant and IUD insertion procedures.
India Contraceptive Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's contraceptive devices landscape. The market structure fragments between multinational pharmaceutical conglomerates with hormonal technology portfolios and domestic manufacturers leveraging PLI scheme cost advantages. Three archetypes dominate: premium-tier hormonal IUD specialists, mass-market condom distributors with rural reach, and API-integrated oral contraceptive producers. Competitive moves center on backward integration into active pharmaceutical ingredient production and microfinance-linked clinic model expansion.
Within the multinational pharmaceutical tier, Bayer AG and Merck & Co Inc occupy positions anchored by hormonal delivery system expertise. Among domestic manufacturers, Lupin Pharmaceuticals Ltd exemplifies API-integrated competitive positioning. Church & Dwight Co Inc represents the mass-market distribution archetype with general trade channel penetration. Cupid Limited sits within the domestic condom manufacturing segment leveraging proximity to Kerala rubber supply.
| Leading Market Players |
|---|
| AbbVie Inc |
| Church & Dwight Co Inc |
| Bayer AG |
| Lupin Pharmaceuticals Ltd |
| Johnson & Johnson |
| Merck & Co Inc |
| Reckitt Benckiser Group plc |
| Cupid Limited |
| CooperSurgical Inc |
| Others |
Supply & Pricing Matrix
Kerala's rubber belt capacity fluctuations transmit directly into condom manufacturing cost structures, with latex price volatility compressing margin pools for domestic producers while creating procurement leverage for buyers with forward-contract coverage. CDSCO's risk-based device classification tiers segment pricing power across hormonal and barrier categories, concentrating premium realization with dossier-heavy multinationals.
Pricing Analysis
Certification level (CDSCO Class C/D versus Class A/B) creates the primary spread between premium hormonal implants and economy condom tiers. Three-tier pricing structure separates tertiary hospital procurement with procedure bundling from pharmacy OTC transactions and rural general trade penetration. Cost compression in the latex condom segment is intensifying because Kerala rubber supply volatility exposes non-integrated manufacturers to input squeezes. Government hospital procurement committees exhibit highest price sensitivity, while private gynecology clinics demonstrate lowest sensitivity due to patient co-pay structures.
Supply Chain Analysis
Tamil Nadu-based contract research organizations and Karnataka pharmaceutical distribution hubs hold concentrated capacity for clinical trial services and inventory staging. Domestic manufacturing draws from Kerala natural rubber, imported polyurethane feedstocks, and Chinese active pharmaceutical ingredients. Single-source vulnerability runs through levonorgestrel API supply from concentrated offshore producers. Distribution runs through government hospital procurement networks, pharmacy general trade, and emerging telemedicine-integrated e-pharmacy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine platform maturation is shifting India contraceptive devices toward platform-economics dynamics, with e-pharmacy interoperability creating new gatekeeper roles that bypass traditional pharmacy distribution.
For Market Incumbents: Harden quality management systems against CDSCO's compressed clinical evaluation timelines while securing backward integration into API production to defend margin pools from Chinese supply competition. Channel control through microfinance-linked clinic networks represents the critical defensive lever against regional entrants fragmenting capital requirements. For New Entrants and Emerging Players: Pursue rural Bihar and Uttar Pradesh general trade white space where condom penetration remains below saturation and clinical counseling infrastructure is sparse. Asset-light pay-per-use clinic models enable rapid geographic expansion without fixed capital deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-integrated domestic pharmaceutical manufacturers with captive hormone synthesis capability and CDSCO registration expertise. Long-term viability hinges on regulatory navigation capacity rather than pure manufacturing scale. Monitor CDSCO's evolving risk classification for biodegradable polymer implants as the inflection signal for next-generation product substitution.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway Acceleration | Compressed timelines favor sponsors with India-specific clinical data and Tamil Nadu CRO relationships. |
| Microfinance-Linked Clinic Expansion | Asset-light distribution fragments capital barriers and enables regional challenger entry against established supply chains. |
| Backward Integration into API Production | Captive levonorgestrel synthesis captures margin pools previously ceded to Chinese and European suppliers. |
| Telemedicine Platform Partnership | E-pharmacy integration bypasses traditional pharmacy networks in Maharashtra and Karnataka urban clusters. |
| Biodegradable Polymer Implant Development | Three-year efficacy cycles with simplified removal procedures collapse replacement frequency expectations in tertiary hospitals. |
Research Methodology
A spread of perspectives from CDSCO regulatory affairs officers, government hospital procurement managers, private gynecology practitioners, and pharmaceutical distribution channel heads converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from CDSCO Medical Device Rules filings, National Family Planning Program procurement databases, BIS standards documentation, and PLI scheme administrative records. Bottom-up demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance dynamics across device type, distribution channel, and end user segments structured the analytical framework over the projection horizon. Modeled dimensions encompassed IUD versus condom versus implant versus oral contraceptive categories, hospital versus pharmacy versus online retail versus clinic channels, and healthcare provider versus individual versus couple versus NGO end users. CAGRs derived from segment-level growth rate synthesis with India-specific regulatory event probability weighting. Forecast inputs incorporated CDSCO approval timeline distributions and National Family Planning Program budget allocation trajectories.
Macroeconomic conditions sit as an overlay; deviation in rubber commodity prices, rupee exchange rates, or central government health expenditure priorities would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and procurement continuity. Quarterly review of CDSCO risk classification amendments and National Family Planning Program state-level disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Posture Correction Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Global Venous Stents Market
Medical Devices
Needle-Free IV Connectors Market