
 Syringe Scale Magnifiers Market | 2026-2036
Syringe Scale Magnifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Syringe Scale Magnifiers Market Analytics
Polycarbonate is restructuring cost-performance trade-offs in syringe scale magnifier housings as manufacturers shift away from conventional acrylic formulations. Becton, Dickinson and Company leverages its integrated plastics molding network to control component costs across North American production lines. Terumo Corporation anchors its competitive stance through precision optics sourcing from captive Japanese suppliers. B. Braun Medical Inc differentiates via sterilization-compatible polymer formulations that withstand repeated autoclave cycles.
Syringe scale magnifiers are optical magnification devices affixed to syringe barrels, typically providing 2x to 5x enlargement of graduated markings to reduce parallax error during volumetric measurement; most units employ acrylic or polycarbonate lenses bonded to polymer clamps with silicone gasket seals. The plastic product category dominates unit volume due to disposability requirements in pharmaceutical manufacturing cleanrooms, while glass lens variants command premium positioning in analytical laboratories where optical clarity standards are stringent. Application demand from pharmaceutical quality control labs is expanding fastest as USP Chapter 797 revisions mandate enhanced visual verification of compounded sterile preparations.
The FDA's device classification rules and USP compounding standards jointly determine design specifications for magnification-assisted dosing equipment marketed to institutional buyers. The EPA's medical waste stream regulations indirectly shape material selection, as recyclability pressures push manufacturers toward single-polymer constructions that simplify end-of-life processing. Stakeholders must monitor evolving pharmacopeial standards for visual inspection thresholds, as these will dictate minimum magnification power requirements and filter market participants by technical compliance capability.
Market Dynamics
The Syringe Scale Magnifiers Market pivots on compounding pharmacy safety mandates that now require optical verification of injectable doses, forcing institutional buyers to replace unassisted syringe reading with magnification-assisted protocols across acute care and pharmaceutical manufacturing settings.
Growth Catalysts
- USP Chapter 797 revisions:The updated sterile compounding standards in the United States mandate enhanced visual verification, directly expanding procurement of magnification devices by hospital pharmacies and outsourcing facilities.
- Polycarbonate lens adoption:Manufacturers are displacing acrylic with polycarbonate housings to achieve superior impact resistance and autoclave compatibility, opening new segments in reusable surgical environments.
- Pharmaceutical quality control expansion:Injectable biologics manufacturing in Germany and Switzerland is scaling visual inspection stations, driving demand for high-clarity glass-lens magnifiers in analytical laboratory settings.
Market Restraints
- Optical-grade polymer supply concentration:Japan and Germany host the dominant precision optics suppliers, creating vulnerability for manufacturers dependent on imported lens substrates.
- Autoclave degradation limits:Repeated steam sterilization cycles degrade polycarbonate clarity over 50-100 uses, constraining reusability economics in high-throughput hospital environments.
- Single-use plastic restrictions:The EU's medical waste directives and EPA landfill regulations are pressuring disposable acrylic designs toward costlier recyclable single-polymer constructions.
Strategic Opportunities
- Home infusion therapy expansion:CMS reimbursement expansion for outpatient parenteral antimicrobial therapy in the United States creates demand for patient-friendly magnifier designs with simplified clamp mechanisms.
- LED-integrated magnification:Converging optical magnification with battery-powered illumination addresses shadowed marking visibility in low-light compounding hoods, particularly in 503B outsourcing facilities.
- Indian pharmaceutical manufacturing:CDSCO's tightening injectable drug GMP inspections is accelerating quality control equipment upgrades among export-oriented formulation units in Hyderabad and Ahmedabad clusters.
Industry Challenges
- Optical metrology technician scarcity:Precision lens calibration and quality assurance requires specialized skills concentrated in Japanese and German optics clusters, limiting production scaling for new market entrants.
- Multi-standard certification complexity:Simultaneous FDA 510(k), CE-MDR, and ISO 13485 compliance extends product launch timelines by 14-18 months for magnification device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringe Scale Magnifiers Market |
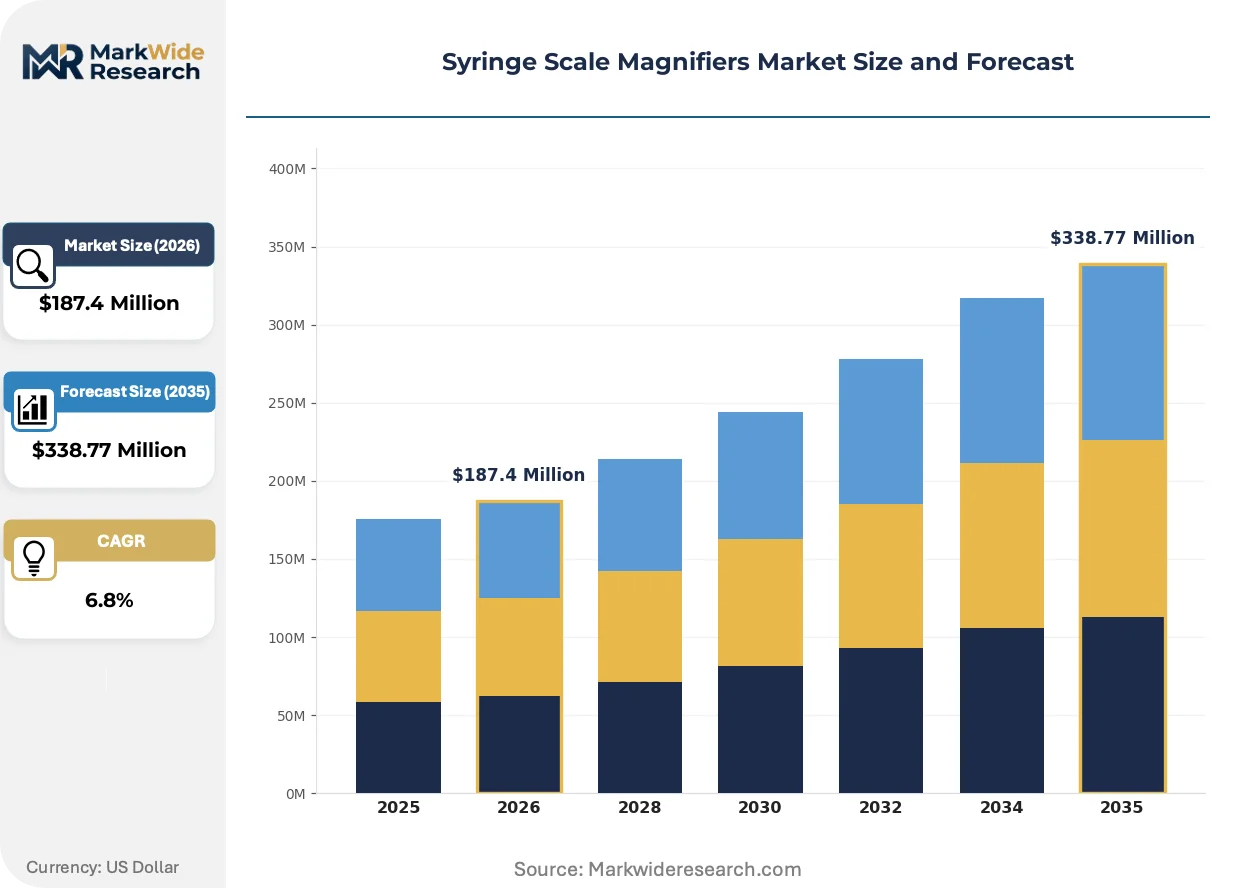
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Silicone Application: Laboratories, Pharmaceuticals, Education, Research End User: Healthcare Professionals, Researchers, Students, Technicians Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, B. Braun Medical Inc, Fresenius Kabi AG, Baxter International Inc, Vita Needle Company, Gerresheimer AG, West Pharmaceutical Services, Inc., Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringe Scale Magnifiers Market Evolving Landscape
Digital overlay technologies and connected device architectures are penetrating syringe scale magnifier design, shifting competitive differentiation from pure optical performance toward integrated verification workflows that reduce human transcription error in high-stakes dosing environments.
Anti-reflective coated polycarbonate is converging with silicone gasket sealing systems to create sterilization-durable magnification clamps that withstand 200+ autoclave cycles. Hospital sterilization departments in the United States are piloting these hybrid constructions to reduce per-procedure equipment costs. The technology is converging with RFID-enabled asset tracking, enabling real-time location monitoring of magnification devices across sprawling medical center campuses.
The FDA's updated guidance on injectable drug preparation accuracy is compelling equipment upgrades across acute care settings, with specific emphasis on parallax-error reduction in volumetric measurement. Hospital pharmacy directors are restructuring capital budgets to prioritize magnification-assisted dosing tools that demonstrate measurable error-rate reduction. This regulatory pressure is concentrating demand in the United States, where CMS reimbursement policies increasingly tie patient safety metrics to capital equipment investments.
Group purchasing organizations are consolidating syringe scale magnifier procurement under single-source contracts that bundle magnification devices with syringe and needle portfolios. This channel compression disadvantages standalone optical specialists while favoring integrated infusion therapy suppliers with full-line contracts. The behavioral shift is most pronounced in the United States, where Vizient and Premier GPOs now specify magnification compatibility in their standardized syringe formularies.
Syringe Scale Magnifiers Market Segmentation
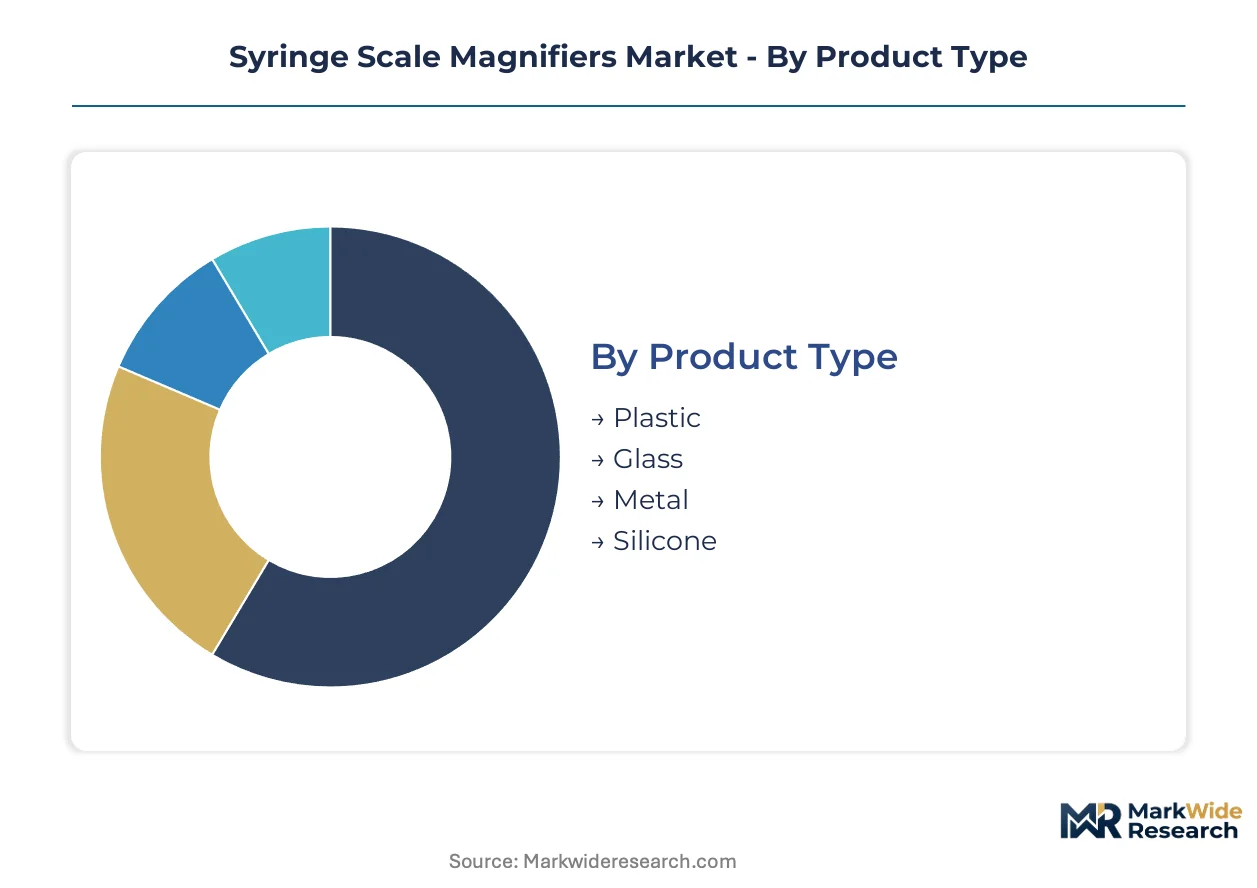
Syringe scale magnifier procurement varies sharply by technical specification and end-use environment, with material selection and optical clarity standards determining price positioning and regulatory compliance pathways across institutional buyer categories.
Product Type:
Polycarbonate and acrylic formulations dominate unit economics, while glass substrates anchor premium laboratory applications where optical precision is non-negotiable.
- Plastic:Polycarbonate and acrylic housings provide 2x to 5x magnification with impact resistance suited for high-throughput hospital pharmacies. Demand concentrates in United States acute care settings where USP Chapter 797 mandates disposable protocols for sterile compounding; single-use plastic restrictions in California and New York are forcing manufacturers toward recyclable single-polymer constructions.
- Glass:Borosilicate and optical-grade glass lenses deliver superior clarity for analytical laboratories measuring sub-milliliter doses of high-value biologics. Swiss and German pharmaceutical quality control labs in Basel and Munich clusters are scaling visual inspection stations, driving procurement of autoclave-compatible glass-lens units that withstand 200+ sterilization cycles.
- Metal:Stainless steel clamp mechanisms serve reusable surgical environments requiring repeated steam sterilization without polymer degradation.
- Silicone:Flexible gasket seals and soft-grip housings address ergonomic requirements in home infusion therapy settings.
Plastic leads on scale; glass leads on momentum.
Application:
Compounding pharmacy safety mandates are restructuring procurement volumes across institutional settings, with pharmaceutical manufacturing quality control expanding fastest.
- Laboratories:Analytical labs in Swissmedic-regulated Swiss facilities and FDA-inspected United States sites require glass-lens magnifiers for USP-compliant visual verification of compounded sterile preparations.
- Pharmaceuticals:Injectable biologics manufacturing in Germany's Rhine-Main cluster and India's Hyderabad-Ahmedabad export zones is scaling magnification-assisted dosing stations as CDSCO and EMA GMP inspections tighten.
- Education:Medical and pharmacy schools in the United States are integrating magnification protocols into injectable technique curricula.
- Research:Preclinical and clinical research organizations employ high-clarity units for dose verification in investigational drug trials.
Pharmaceuticals commands volume concentration; laboratories posts the steepest expansion trajectory.
End User:
Professional credential requirements and liability exposure create sharp segmentation in purchasing authority and specification sophistication.
- Healthcare Professionals:Hospital pharmacists and infusion nurses in CMS-regulated United States facilities drive procurement of LED-integrated magnifiers for low-light compounding hoods. Group purchasing organizations bundle these devices with standardized syringe formularies, concentrating demand through Vizient and Premier contracts.
- Researchers:Principal investigators in NIH-funded United States institutions and Max Planck Society German labs specify optical-grade glass for publication-grade measurement accuracy.
- Students:Medical and pharmacy trainees represent a price-sensitive segment with institutional purchasing through university procurement systems.
- Technicians:Quality control technicians in pharmaceutical manufacturing require calibration-certifiable units with documented optical metrology.
Healthcare professionals dominate absolute demand; researchers gain share fastest.
Distribution Channel:
Channel strategy reflects buyer scale and specification complexity, with integrated suppliers capturing institutional volume through bundled contracts.
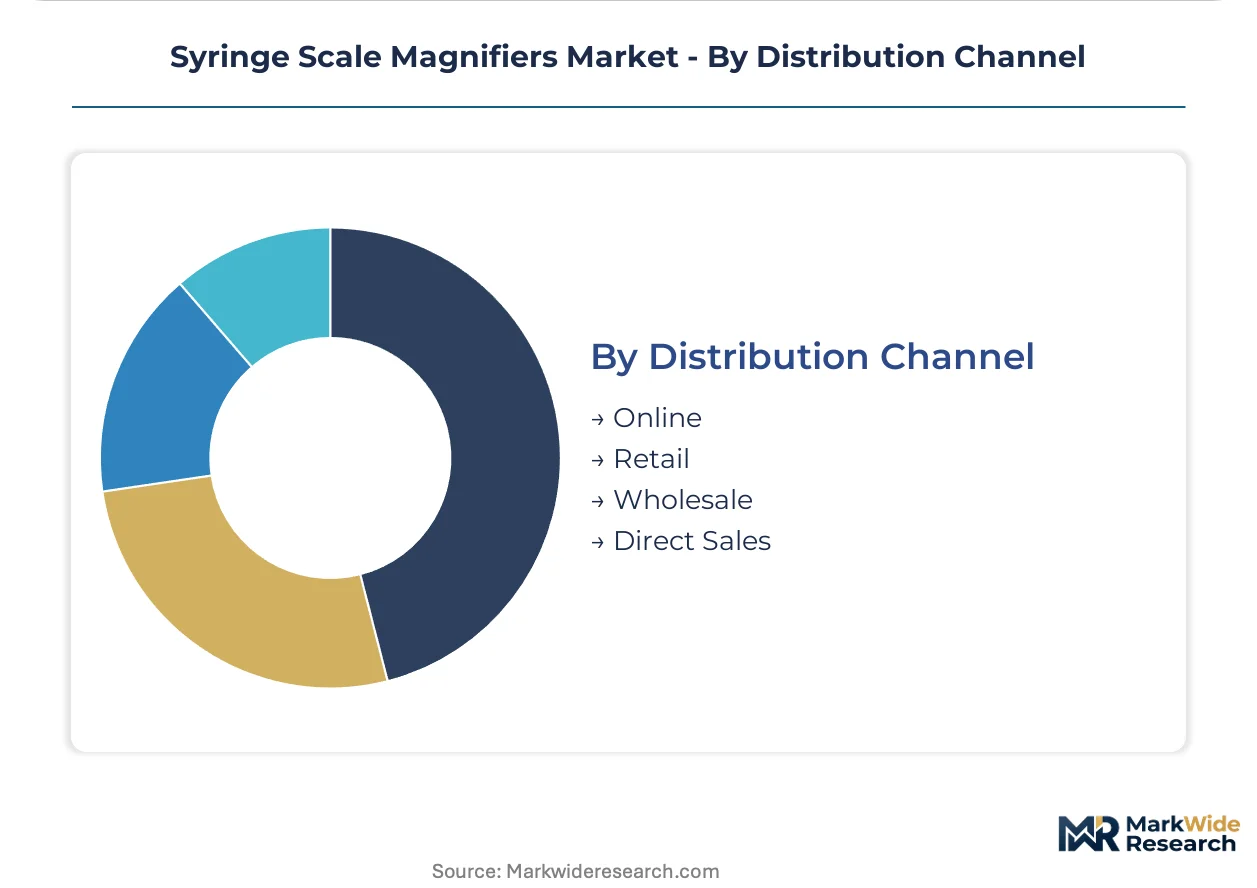
- Online:E-commerce platforms serve small-laboratory and educational buyers with standardized plastic-lens units, though optical-grade glass purchases require technical consultation that digital channels struggle to provide.
- Retail:Medical supply distributors stock mid-tier polycarbonate models for walk-in pharmacy and clinic procurement in the United States.
- Wholesale:Regional distributors aggregate demand from independent compounding pharmacies and outpatient infusion centers.
- Direct Sales:Integrated infusion therapy suppliers leverage full-line contracts with IDNs and GPOs, bundling magnifiers with syringe-needle portfolios to displace standalone optical specialists.
Direct sales leads on scale; online climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main pharmaceutical cluster anchors procurement volume for syringe scale magnifiers, with injectable biologics manufacturing scaling visual inspection stations across multiple regulatory jurisdictions.
United States
Hospital pharmacies and 503B outsourcing facilities drive demand for LED-integrated magnifiers as USP Chapter 797 mandates enhanced visual verification of compounded sterile preparations. The FDA's updated guidance on injectable drug preparation accuracy compels equipment upgrades across acute care settings. CMS reimbursement policies tie patient safety metrics to capital equipment investments, concentrating procurement through Vizient and Premier group purchasing organizations in the Midwest and Northeast corridor.
Germany
Injectable biologics manufacturing in the Rhine-Main cluster scales magnification-assisted dosing stations as EMA GMP inspections tighten quality control protocols. The country's medical device regulation under CE-MDR extends product launch timelines for magnification device manufacturers. Precision optics sourcing from captive suppliers in the Munich-Stuttgart corridor supports autoclave-compatible glass-lens production for analytical laboratories.
Switzerland
Swissmedic-regulated facilities in Basel require glass-lens magnifiers for USP-compliant visual verification of high-value biologics. The country's pharmaceutical quality control labs command premium positioning for optical-grade units with documented calibration certification. Visual inspection stations expand across the Basel-Lucerne pharmaceutical manufacturing belt as export-oriented formulation units upgrade equipment.
India
CDSCO's tightening injectable drug GMP inspections accelerates quality control equipment upgrades among export-oriented formulation units. The country's national pharmaceutical regulator mandates enhanced visual verification protocols for sterile compounding. Hyderabad and Ahmedabad clusters scale magnification-assisted dosing stations to meet EMA and FDA inspection standards for active pharmaceutical ingredient exports.
Japan
PMDA oversight of medical device quality systems shapes procurement specifications for magnification-assisted dosing tools in domestic pharmaceutical manufacturing. Precision optics sourcing from domestic suppliers concentrates production capabilities in the Tokyo-Osaka industrial corridor. Terumo Corporation leverages captive Japanese optics networks to supply regional pharmaceutical quality control labs with calibration-certifiable units.
Syringe Scale Magnifiers Market Competitive Landscape
Global majors compete with regional champions across integrated infusion therapy portfolios, with market structure consolidating around full-line suppliers capable of bundling magnifiers with syringe-needle contracts. Three archetypes dominate: integrated medical device conglomerates with captive plastics molding networks, precision optics specialists with sterilization-compatible polymer formulations, and standalone optical component suppliers serving analytical laboratory niches. Strategic moves center on group purchasing organization contract consolidation and backward integration into lens substrate production to reduce import dependency.
Within the integrated conglomerate tier, Becton, Dickinson and Company and B. Braun Medical Inc exemplify full-line positioning through bundled procurement contracts with institutional buyers. Terumo Corporation occupies a distinct geography-specialist position, leveraging domestic Japanese optics sourcing to serve precision-demanding segments. These three anchors represent divergent pathways for market participation: North American contract consolidation, European sterilization durability engineering, and East Asian precision optics integration.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| B. Braun Medical Inc |
| Fresenius Kabi AG |
| Baxter International Inc |
| Vita Needle Company |
| Gerresheimer AG |
| West Pharmaceutical Services, Inc. |
| Nipro Corporation |
| Others |
Value Network & Pricing Analysis
Group purchasing organization procurement concentration in United States hospital systems anchors a contract-based pricing model that bundles magnification devices with syringe-needle portfolios. This buyer consolidation compresses margin capture for standalone optical specialists while rewarding integrated suppliers with volume commitments and multi-year offtake security.
Pricing Analysis
Optical-grade polymer resin costs pass through directly to polycarbonate-lens magnifier pricing, with Japanese and German substrate suppliers commanding premium positioning. Three-tier pricing structure across premium glass-lens, standard polycarbonate, and economy acrylic levels segments buyers by certification requirement and sterilization durability. Cost compression in the economy tier intensifies as California and New York single-use plastic restrictions force recyclable single-polymer redesigns. Pharmaceutical quality control labs show least price sensitivity due to USP Chapter 797 compliance mandates, while educational institutions represent the most price-constrained segment.
Supply Chain Analysis
ISO 13485 and FDA 510(k) certification gating restricts viable suppliers to established medical device manufacturers with documented quality management systems. Precision optics production concentrates in Japan, Germany, and Switzerland, with Tokyo-Osaka and Munich-Stuttgart corridors hosting dominant lens substrate fabrication. Raw material flows draw from polycarbonate resin producers in the United States and Germany, silicone gasket specialists in Japan, and stainless steel clamp forgers in China. Single-source vulnerability runs through Japanese optical-grade polymer supply, where captive supplier relationships limit alternative sourcing. Distribution runs through direct sales contracts with integrated delivery networks and group purchasing organizations, bypassing traditional distributor markups for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syringe scale magnifier market has entered a late-cycle quality phase where USP Chapter 797 revisions and FDA guidance on injectable preparation accuracy are shifting procurement toward premium glass-lens and LED-integrated specifications.
For Market Incumbents: Lock in GPO contract consolidation through bundled syringe-magnifier-needle portfolios that displace standalone optical competitors. Secure backward integration into polycarbonate lens substrate production to reduce dependency on Japanese and German precision optics suppliers. Prioritize autoclave-durable hybrid constructions that withstand 200+ sterilization cycles, addressing the degradation limit that constrains reusability economics in high-throughput hospital environments. For New Entrants and Emerging Players: The mid-tier price gap between premium glass-lens laboratory units and disposable acrylic pharmacy models offers white-space positioning for polycarbonate-based designs with simplified clamp mechanisms. Target home infusion therapy expansion under CMS outpatient parenteral antimicrobial therapy reimbursement, where patient-friendly ergonomics and LED illumination address unmet visibility needs. Pursue CDSCO-registered manufacturing partnerships in India's Hyderabad-Ahmedabad clusters to serve export-oriented formulation units upgrading for EMA and FDA inspections. For Investors and Strategic Acquirers: Integrated infusion therapy conglomerates represent the most active acquirer category in this space, seeking optical capabilities to complete full-line hospital contracts. The five-to-ten year viability window favors targets with captive lens substrate supply or established sterilization-durable polymer formulations. Acquisition focus should center on mid-cap specialists with ISO 13485 certification and existing GPO relationships. Monitor USP Chapter 797 revision implementation timelines as the primary inflection signal for magnification device procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Substrate Production | Reduces import dependency on Japanese and German precision optics suppliers for polycarbonate and glass lens housings. |
| LED-Integrated Magnification Development | Addresses shadowed marking visibility in low-light compounding hoods across 503B outsourcing facilities and hospital pharmacies. |
| GPO Contract Consolidation | Vizient and Premier bundled procurement specifications now require magnification compatibility in standardized syringe formularies. |
| Autoclave-Durable Hybrid Construction | Anti-reflective coated polycarbonate with silicone gasket sealing withstands 200+ sterilization cycles, reducing per-procedure equipment costs. |
| RFID-Enabled Asset Tracking Integration | Enables real-time location monitoring of magnification devices across sprawling medical center campuses and multi-site health systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and precision optics manufacturing executives with secondary validation. Secondary sources included FDA 510(k) device filings, USP Chapter 797 revision documentation, CMS reimbursement policy updates, and hospital procurement database extracts. Bottom-up demand modeling across product type, application, and end-user segments was triangulated against top-down market sizing from integrated infusion therapy supplier disclosures.
Segment-weighting approaches applied differential growth assumptions across plastic, glass, metal, and silicone product categories, with laboratory, pharmaceutical, education, and research applications modeled separately. End-user segmentation distinguished healthcare professionals, researchers, students, and technicians by procurement authority and specification sophistication. CAGRs were derived from regression analysis of historical procurement patterns against regulatory implementation timelines and reimbursement policy shifts. Forecast inputs incorporated USP Chapter 797 adoption curves, CDSCO inspection intensity in Indian pharmaceutical clusters, and EMA GMP enforcement trajectories across the Rhine-Main and Basel manufacturing belts.
The model assumes a particular technology adoption path for LED-integrated and RFID-enabled magnification devices; alternative pathways for digital overlay and connected device architectures would alter the outlook for optical-only specialists. Forecasts reflect assumptions about regulatory implementation pace, GPO contract consolidation velocity, and precision optics supply chain stability. A model refresh is warranted upon material change in FDA guidance on injectable drug preparation accuracy or USP compounding standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Implants Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Corneal Implants Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Adjustable Speed Vortex Mixer Market