
 On-Body Drug Delivery Devices Market | 2026-2036
On-Body Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
On-Body Drug Delivery Devices Market Analytics
Aftermarket service revenue is tilting from disposable component replenishment toward connected device platform licensing and remote patient monitoring subscriptions. Insulet Corporation leverages its closed-loop ecosystem to sustain recurring revenue through pod replacement cycles and software-enabled dosing optimization. Medtronic anchors its position through deep integration with continuous glucose monitoring streams, while YPSOMED competes via modular wearable injector architectures that accommodate multiple biologic drug viscosities.
On-body drug delivery devices are adhesive or strap-secured systems that administer therapeutic agents through subcutaneous, intradermal, or transdermal routes over extended durations, typically incorporating elastomeric pumping mechanisms, microneedle arrays, or electroosmotic drivers operating at flow rates between 0.1 and 20 mL per hour. These systems eliminate the need for healthcare professional administration during multi-hour infusion cycles, enabling outpatient management of biologics and continuous hormone replacement. Wearable injectors currently occupy the largest value share within product type segmentation due to their compatibility with high-volume monoclonal antibody formulations, while smart delivery systems embedded with Bluetooth connectivity and dose-feedback algorithms represent the fastest-expanding technology tier as pharmaceutical sponsors seek differentiation in competitive biosimilar markets. Home care settings are pulling ahead of hospitals within end user segmentation, driven by payer cost-containment mandates and patient preference for reduced clinic exposure.
The FDA regulates these products as combination devices under 21 CFR Part 820 quality system requirements, while the EMA's Medical Device Regulation imposes additional clinical evidence standards for drug-device integral systems seeking European market access. ISO 11608 needle-based injection systems standards govern mechanical performance testing, with recent amendments addressing connectivity and cybersecurity validation for wireless-enabled platforms. Stakeholders must monitor evolving reimbursement coding for remote therapeutic monitoring as payers recalibrate coverage policies for digitally supported self-administration.
Market Dynamics
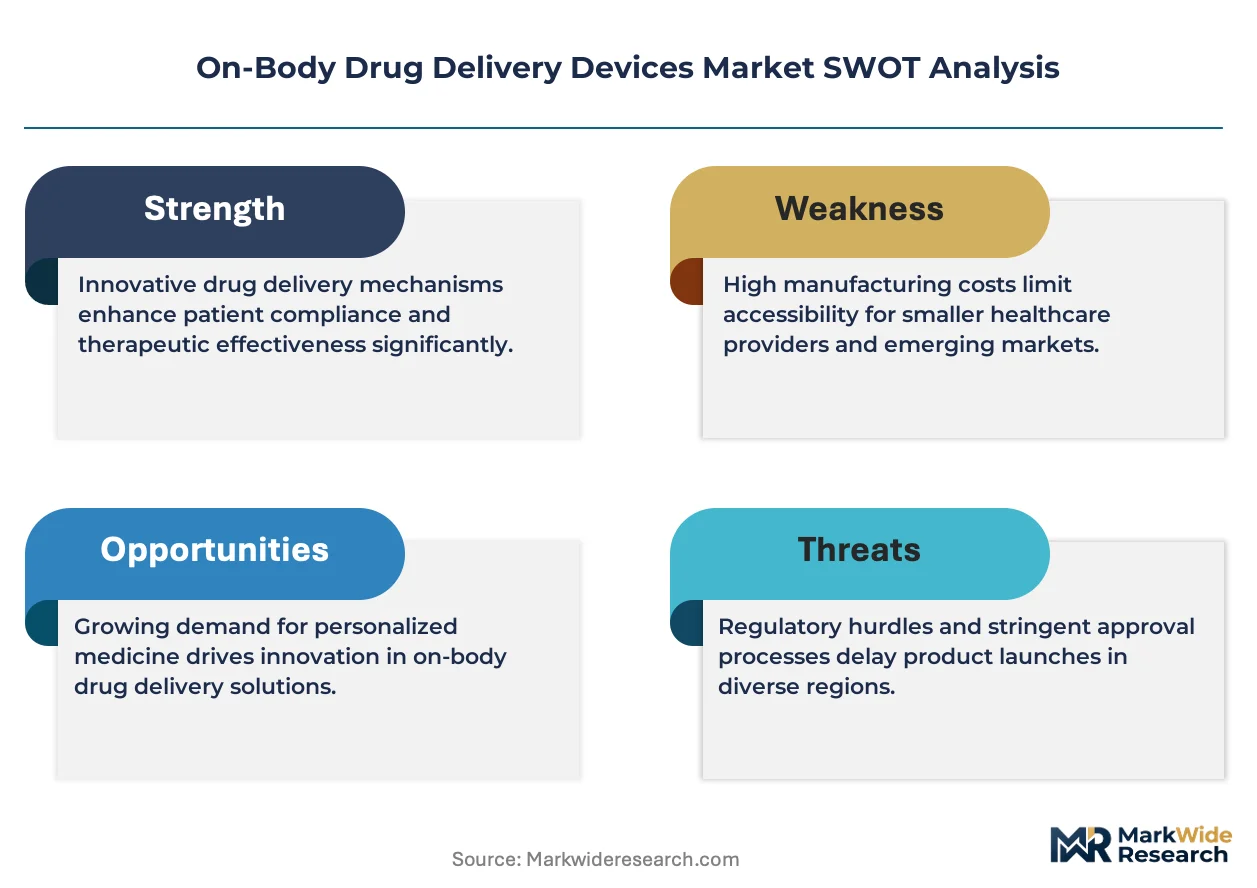
Biopharmaceutical sponsors are consolidating device development partnerships to compress combination product approval timelines and secure manufacturing capacity for high-viscosity monoclonal antibody formulations.
Growth Catalysts
- Specialty pharmacy networks:United States reimbursement frameworks favor ambulatory delivery formats, accelerating patient transitions from infusion centers to home administration.
- 21 CFR Part 820:FDA quality system requirements for combination devices clarify validation pathways, reducing regulatory uncertainty for sponsors integrating drug-device systems.
- Elastomeric pumping mechanisms:Advances in precision flow control enable extended-duration subcutaneous delivery of biologics previously requiring intravenous administration.
Market Restraints
- Medical-grade silicone supply:Concentration of elastomer component manufacturing in select Asian suppliers creates input cost volatility and qualification bottlenecks.
- EMA MDR clinical evidence standards:European Medical Device Regulation imposes additional validation requirements for drug-device integral systems, extending commercialization timelines.
- Intravenous infusion:Established clinical workflows and reimbursement codes for hospital-based administration create substitution resistance among conservative prescriber segments.
Strategic Opportunities
- Remote therapeutic monitoring:Evolving CPT coding for digitally supported self-administration creates reimbursement tailwinds for Bluetooth-enabled delivery platforms.
- Japan's aging demographic:METI healthcare innovation priorities favor wearable injector adoption for chronic disease management in home care settings.
- Microneedle-transdermal convergence:Integration of dissolvable microarray technology with connected dosing algorithms opens intradermal routes for vaccine and hormone therapies.
Industry Challenges
- ISO 11608-6 cybersecurity validation:Recent amendments addressing connectivity testing require specialized firmware engineering talent scarce among traditional mechanical device manufacturers.
- Legacy EHR integration:Dose-feedback algorithms must interface with fragmented hospital information systems, complicating deployment across integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Body Drug Delivery Devices Market |
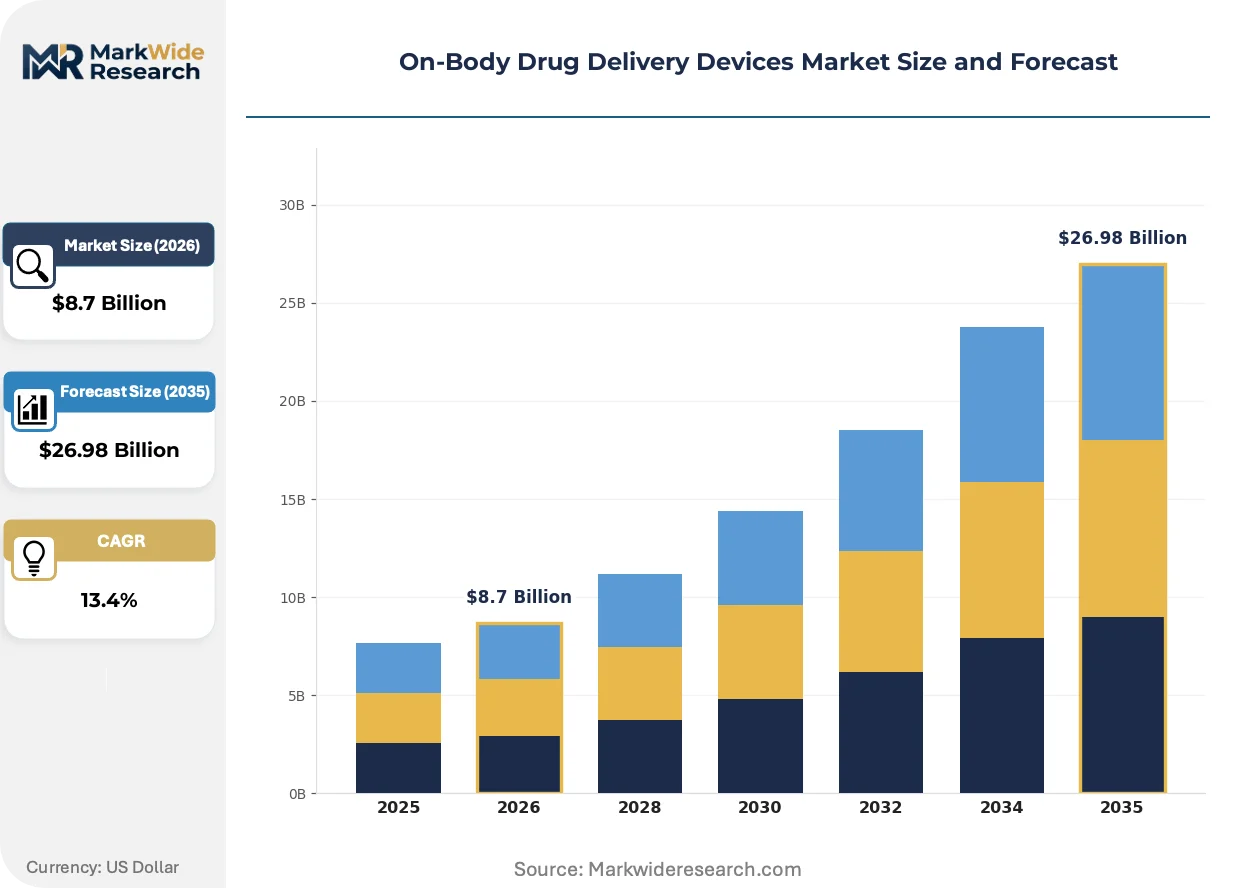
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Injectors, Micro-Needle Patches, Transdermal Patches, Implantable Devices Technology: Active Delivery Systems, Passive Delivery Systems, Smart Delivery Systems, Biodegradable Devices End User: Hospitals, Home Care Settings, Clinics, Research Labs Application: Chronic Diseases, Oncology, Pain Management, Vaccination |
| Companies Covered | Insulet Corporation, Medtronic, Gerresheimer AG, E3D Elcam Drug Delivery Devices, West Pharmaceutical Services, Inc., Enable Injections, YPSOMED, BD, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Body Drug Delivery Devices Market Evolving Landscape
Device architectures are converging around closed-loop ecosystems that synchronize delivery mechanics with continuous physiologic monitoring, compressing the gap between sensing and therapeutic response.
Bluetooth Low Energy connectivity is digitizing dose-event logging and adherence tracking for wearable injectors. Rheumatology and endocrinology practices are piloting these platforms for biologic therapy management. The technology is digitizing pharmaceutical sponsor competitive strategies by enabling real-world evidence generation that differentiates originator products from biosimilars.
EU Medical Device Regulation Annex XVI expansion reclassifies certain drug-device borderline products, tightening clinical evaluation requirements. Manufacturers must now generate additional performance data for systems with ancillary diagnostic functions. Wearable injector platforms with integrated glucose sensing face the steepest compliance burden, prompting restructuring of European market entry sequences.
Hospital procurement committees are unbundling device selection from drug purchasing agreements, enabling pharmacy directors to negotiate wearable platform contracts independently. This fragmentation displaces traditional bundled tender structures that favored incumbent suppliers. The shift is most visible in United States academic medical centers consolidating specialty pharmacy operations under centralized formulary control.
On-Body Drug Delivery Devices Market Segmentation
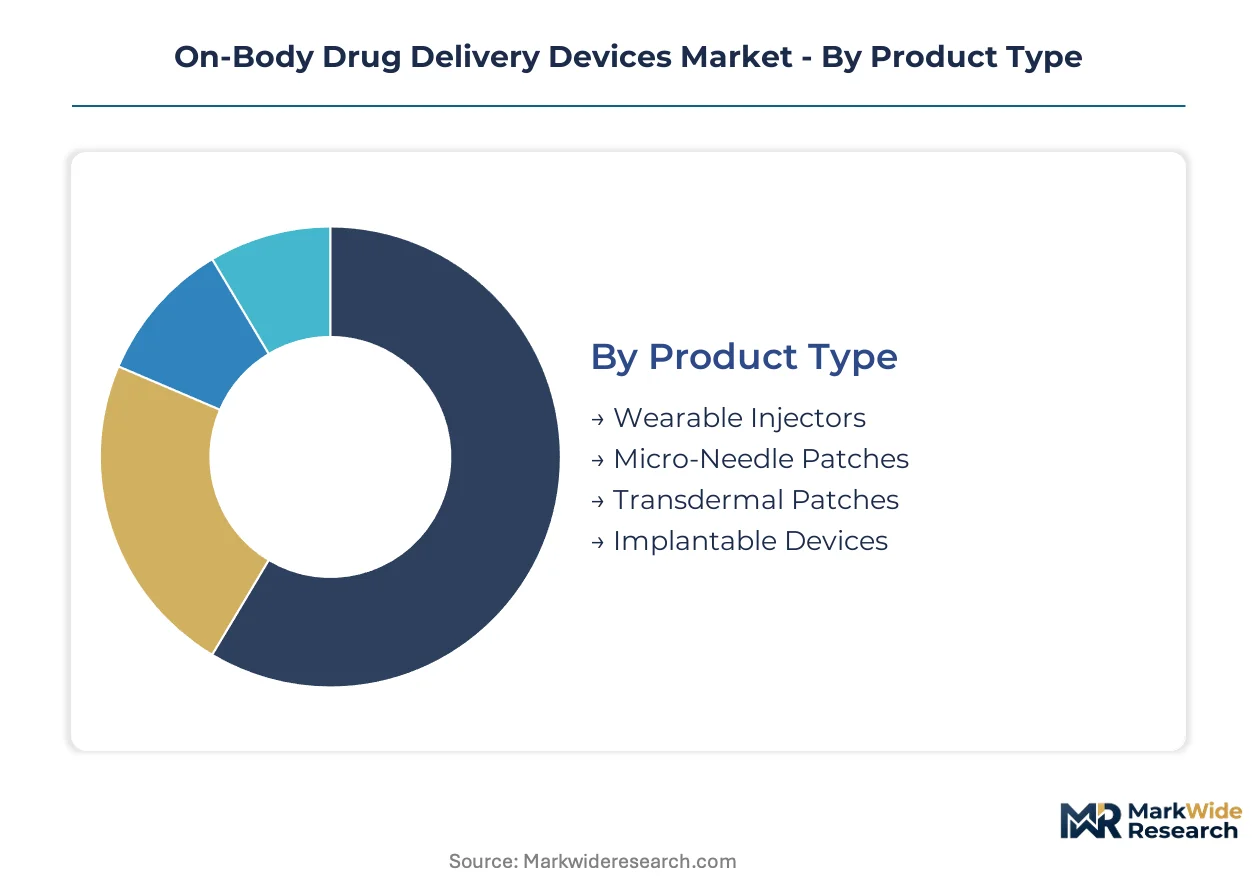
Segmentation reveals how device architectures align with therapeutic requirements and care settings. Manufacturers calibrate platform investments across these dimensions to match reimbursement pathways and patient self-administration readiness.
Product Type:
Volume concentration across these formats tracks biologic drug viscosity and infusion duration requirements.
- Wearable Injectors:Elastomeric pumping mechanisms deliver high-volume monoclonal antibody formulations subcutaneously over extended durations. Demand concentrates in United States specialty pharmacy networks where payer mandates favor home administration of biologics for rheumatology and endocrinology indications.
- Micro-Needle Patches:Dissolvable microarray technology enables intradermal vaccine and hormone delivery without healthcare professional involvement. Japan's METI healthcare innovation priorities accelerate adoption for chronic disease management in aging populations.
- Transdermal Patches:Passive diffusion systems suit small-molecule hormone replacement and pain therapies with steady-state pharmacokinetic requirements.
- Implantable Devices:Long-acting depot formulations integrate with osmotic drivers for multi-month contraceptive or hormonal therapy delivery.
Wearable injectors command the established base. The steepest expansion runs through micro-needle patches.
Technology:
Technology selection determines regulatory pathway complexity and software-enabled differentiation potential.
- Active Delivery Systems:Electroosmotic and mechanical pumping mechanisms achieve precision flow control for high-viscosity biologics. United States FDA 21 CFR Part 820 quality system requirements govern validation pathways for these electromechanical platforms.
- Smart Delivery Systems:Bluetooth Low Energy connectivity and dose-feedback algorithms synchronize delivery with continuous physiologic monitoring. European EMA MDR clinical evidence standards impose additional cybersecurity validation requirements for wireless-enabled platforms.
- Passive Delivery Systems:Osmotic and diffusion-driven mechanisms operate without power sources for cost-sensitive therapeutic categories.
- Biodegradable Devices:Materials science advances enable complete device absorption eliminating retrieval procedures for short-course therapies.
Active delivery systems anchor current revenue. Smart delivery systems are climbing the fastest as pharmaceutical sponsors seek biosimilar differentiation through real-world evidence generation.
End User:
Care setting migration reshapes procurement authority and device feature prioritization.
- Home Care Settings:Patient-administered platforms require intuitive interfaces and remote monitoring capabilities. United States reimbursement frameworks for remote therapeutic monitoring create tailwinds for Bluetooth-enabled systems prescribed through centralized specialty pharmacy operations.
- Hospitals:Acute care deployment emphasizes integration with electronic health record systems and nurse workflow efficiency. Procurement committees increasingly unbundle device selection from drug purchasing agreements.
- Clinics:Ambulatory infusion centers transition medium-duration therapies to on-body formats to reduce chair time and facility overhead.
- Research Labs:Early-phase clinical trials utilize programmable platforms for pharmacokinetic sampling and bioavailability studies.
Home care settings dominate volume growth trajectory. Hospitals retain influence over technology standardization through formulary control.
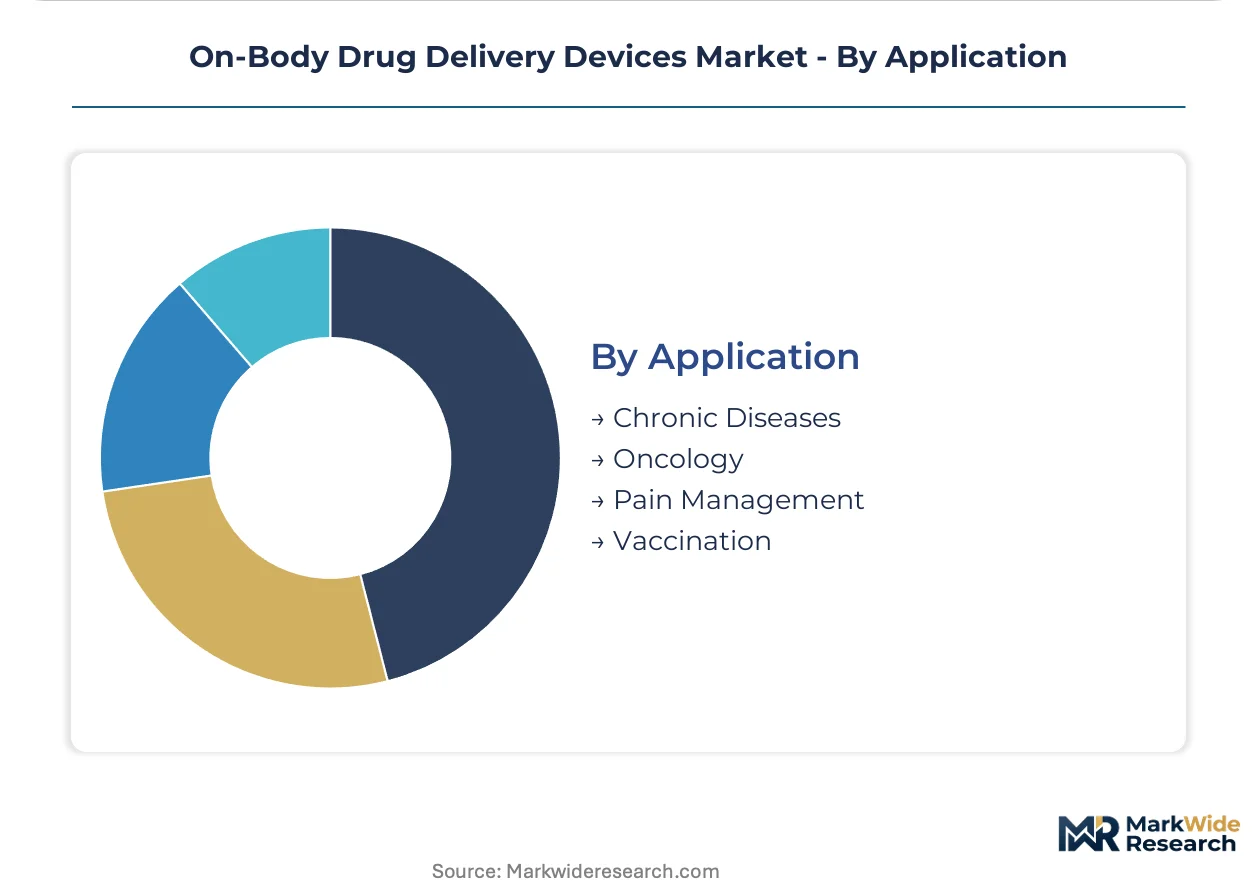
Application:
Therapeutic area specialization dictates device performance specifications and partnership strategies with pharmaceutical sponsors.
- Chronic Diseases:Diabetes and autoimmune conditions require multi-year therapy adherence support through connected dosing reminders and glycemic correlation. United States payers prioritize these platforms for total cost of care reduction.
- Oncology:Subcutaneous monoclonal antibody delivery replaces intravenous infusion for maintenance regimens. EMA MDR Annex XVI reclassification tightens clinical evaluation for systems with integrated diagnostic functions.
- Pain Management:Patient-controlled on-body analgesia reduces opioid exposure and hospital readmission risk.
- Vaccination:Microneedle arrays enable thermostable intradermal delivery for outbreak response and routine immunization programs.
Chronic disease applications hold the largest installed base. Oncology represents the fastest-expanding opportunity as biologic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients administer biologics through wearable injectors at substantially higher per-capita rates than German or Japanese counterparts, reflecting divergent reimbursement incentives and specialty pharmacy infrastructure maturity across markets.
United States
Specialty pharmacy networks and remote therapeutic monitoring reimbursement codes accelerate transitions from infusion centers to home administration. FDA 21 CFR Part 820 quality system requirements clarify combination product validation pathways for sponsors integrating drug-device systems. Greater Boston and San Diego biotechnology clusters concentrate pharmaceutical sponsor headquarters where device partnership negotiations occur.
Germany
Academic medical centers unbundle device selection from drug purchasing agreements, enabling independent pharmacy director negotiations. EMA Medical Device Regulation Annex XVI expansion tightens clinical evaluation requirements for systems with ancillary diagnostic functions. Baden-Württemberg precision engineering clusters supply elastomeric pumping mechanism components to European device manufacturers.
Japan
METI healthcare innovation priorities favor wearable injector adoption for chronic disease management in aging populations seeking home-based alternatives to clinic visits. PMDA consultation procedures address drug-device integral system approval timelines for combination products. Kanto region medical device manufacturing corridors around Tokyo host final assembly operations for Asia-Pacific distribution.
Switzerland
Pharmaceutical sponsor co-development partnerships concentrate among Basel-area biologics manufacturers seeking integrated delivery platforms for high-viscosity monoclonal antibodies. Swissmedic guidance aligns with EMA MDR standards while offering streamlined review pathways for innovative drug-device combinations. Zurich precision component suppliers provide medical-grade silicone molding for wearable injector architectures.
United Kingdom
NHS long-term plan cost-containment mandates push medium-duration therapies from hospital settings to ambulatory on-body formats. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR while introducing national divergence risk for market entry timing. London-Southeast specialty pharmacy consolidation under centralized formulary control reshapes procurement authority for connected delivery platforms.
On-Body Drug Delivery Devices Market Competitive Landscape
Capability concentration sits with specialized device engineering firms possessing elastomeric pumping and microneedle fabrication expertise; scale advantage sits with diversified medical technology conglomerates leveraging global manufacturing footprints and established hospital procurement relationships. The competitive terrain stratifies into three archetypes: closed-loop ecosystem orchestrators, modular platform specialists, and component-integrated contract manufacturers. Dominant competitive moves include pharmaceutical sponsor partnership consolidation to secure combination product co-development pipelines, and backward integration into medical-grade silicone supply chains to mitigate input cost volatility.
Within the ecosystem orchestrator tier, Insulet Corporation and Medtronic exemplify players anchoring recurring revenue through pod replacement cycles and continuous glucose monitoring integration. YPSOMED occupies a position among modular architecture specialists competing via wearable injector platforms accommodating multiple biologic drug viscosities. These three entities represent contrasting strategic postures: closed-loop vertical integration versus open-platform flexibility versus precision component supply.
| Leading Market Players |
|---|
| Insulet Corporation |
| Medtronic |
| Gerresheimer AG |
| E3D Elcam Drug Delivery Devices |
| West Pharmaceutical Services, Inc. |
| Enable Injections |
| YPSOMED |
| BD |
| Stevanato Group |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone molding operations in Southeast Asia concentrate upstream supply for elastomeric pumping mechanisms, anchoring margin capture downstream with closed-loop ecosystem orchestrators who bundle pod replacement cycles into recurring revenue streams.
Pricing Analysis
Long-term offtake agreements dominate procurement between pharmaceutical sponsors and device manufacturers, with pricing stratifying across premium, standard, and economy tiers based on connectivity certification levels and volume scale commitments. Price differentiation rests on FDA 21 CFR Part 820 quality system validation tiers and Bluetooth Low Energy cybersecurity compliance grades. Pricing pressure stems from hospital procurement committees unbundling device selection from drug purchasing agreements, fragmenting traditional bundled tender structures. Specialty pharmacy networks exhibit lowest price sensitivity due to reimbursement tailwinds for remote therapeutic monitoring, while research labs purchasing programmable platforms for pharmacokinetic studies face acute cost compression.
Supply Chain Analysis
Upward feedstock flows of medical-grade silicone, precision-machined elastomeric components, and lithium-polymer power cells draw from manufacturing corridors in Malaysia, Thailand, and South Korea. Raw material dependencies center on pharmaceutical-grade thermoplastics, microneedle-grade silicon wafers, and biocompatible adhesives. Single-source vulnerability concentrates in select Asian suppliers qualified under ISO 11608 needle-based injection systems standards, creating qualification bottlenecks for Western device manufacturers. Distribution runs through centralized specialty pharmacy networks in the United States and academic medical center procurement committees in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-body drug delivery devices market constitutes a defensive moat anchored in regulatory entrenchment, where FDA combination product approval timelines and EMA MDR clinical evidence standards erect formidable barriers against unqualified entrants.
For Market Incumbents: Insulate recurring revenue streams through captive supply of medical-grade silicone components and exclusive co-development partnerships with pharmaceutical sponsors seeking biosimilar differentiation. Threats from modular platform specialists offering open-architecture flexibility necessitate backward integration into elastomeric pumping mechanism manufacturing. Certification investment in ISO 11608-6 cybersecurity validation represents the critical lever for defending position against emerging connected device entrants. For New Entrants and Emerging Players: Microneedle-transdermal convergence for vaccine and hormone therapies in Japan's aging demographic represents the most penetrable entry point, with METI healthcare innovation priorities accelerating reimbursement pathways for home-based administration. White-space exists in biodegradable device architectures for short-course therapies eliminating retrieval procedures. Go-to-market execution should target rheumatology and endocrinology practices piloting Bluetooth-enabled adherence platforms through specialty pharmacy channel partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward modular platform specialists possessing elastomeric pumping expertise across multiple biologic drug viscosities, with long-term viability hinging on pharmaceutical sponsor partnership consolidation trends. Acquisition targets should demonstrate existing FDA 510(k) clearance pathways and European MDR technical documentation readiness. The signal to watch is evolving CPT coding for remote therapeutic monitoring as payers recalibrate coverage policies for digitally supported self-administration.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Sponsor Partnership Consolidation | Insulet Corporation's closed-loop ecosystem secures recurring pod replacement revenue through exclusive biologic co-development agreements. |
| FDA Combination Product Submission | EMA MDR Annex XVI reclassification tightens clinical evaluation requirements for wearable injectors with integrated glucose sensing functions. |
| Backward Integration into Silicone Supply | Medical-grade silicone concentration in Southeast Asian suppliers creates input cost volatility mitigated through captive molding operations. |
| Remote Therapeutic Monitoring Platform Launch | Bluetooth-enabled dose-feedback algorithms synchronize with continuous glucose monitoring streams for real-world evidence generation. |
| Hospital System Partnership Development | Academic medical center procurement committees unbundling device selection from drug purchasing agreements enable independent formulary negotiations. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions driving this analysis. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA submission databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down pharmaceutical sponsor partnership tracking triangulated market sizing across the projection horizon.
Demand-supply-balance framing anchored the analytical framework throughout the modeling period, with segmentation dimensions spanning product type, technology tier, end user setting, and therapeutic application area. CAGRs derived from pharmaceutical pipeline maturation timelines and payer cost-containment mandate trajectories. Industry-specific forecast inputs incorporated specialty pharmacy network expansion rates and remote therapeutic monitoring reimbursement code adoption curves.
Practitioners should monitor FDA guidance evolution on combination products and EMA MDR Annex XVI implementation delays for early signals requiring forecast revision. Cross-checking against hospital procurement database trends and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gynecology Devices Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Rectal Catheters Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Endodontic Devices Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
General Surgery Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Buccal Cavity Devices Market