
 Mobile Gamma Cameras Market | 2026-2036
Mobile Gamma Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Gamma Cameras Market Intelligence
Demand from specialized diagnostic centers and mobile imaging services is collapsing the traditional hospital-centric procurement model for nuclear imaging. Spectrum Dynamics Medical leverages its focus on digital SPECT systems to capture this shift toward more flexible, lower-cost settings. Dilon Technologies specializes in high-resolution, small field-of-view systems suited for outpatient oncology and surgical applications. Mediso Ltd. competes with a broad portfolio that covers both preclinical research and clinical diagnostics, positioning it across multiple end-user types.
A mobile gamma camera is a portable nuclear medicine imaging system for bedside or intraoperative use, utilizing detectors to capture gamma rays from radiotracers and reveal organ function. Its purpose is to provide diagnostic flexibility outside dedicated departments. Hand-held units are seeing rapid uptake due to their versatility, while cardiology applications for myocardial perfusion imaging constitute a mature and significant demand base for these systems.
Market access is governed by stringent regulatory frameworks, including premarket approval from the US FDA, CE marking under the EU's Medical Device Regulation (MDR), and approval from China's NMPA. These regulations mandate rigorous testing for device safety and diagnostic efficacy, influencing product development cycles and timelines. Stakeholders must monitor the integration of artificial intelligence for image reconstruction and analysis, which will define future system capabilities.
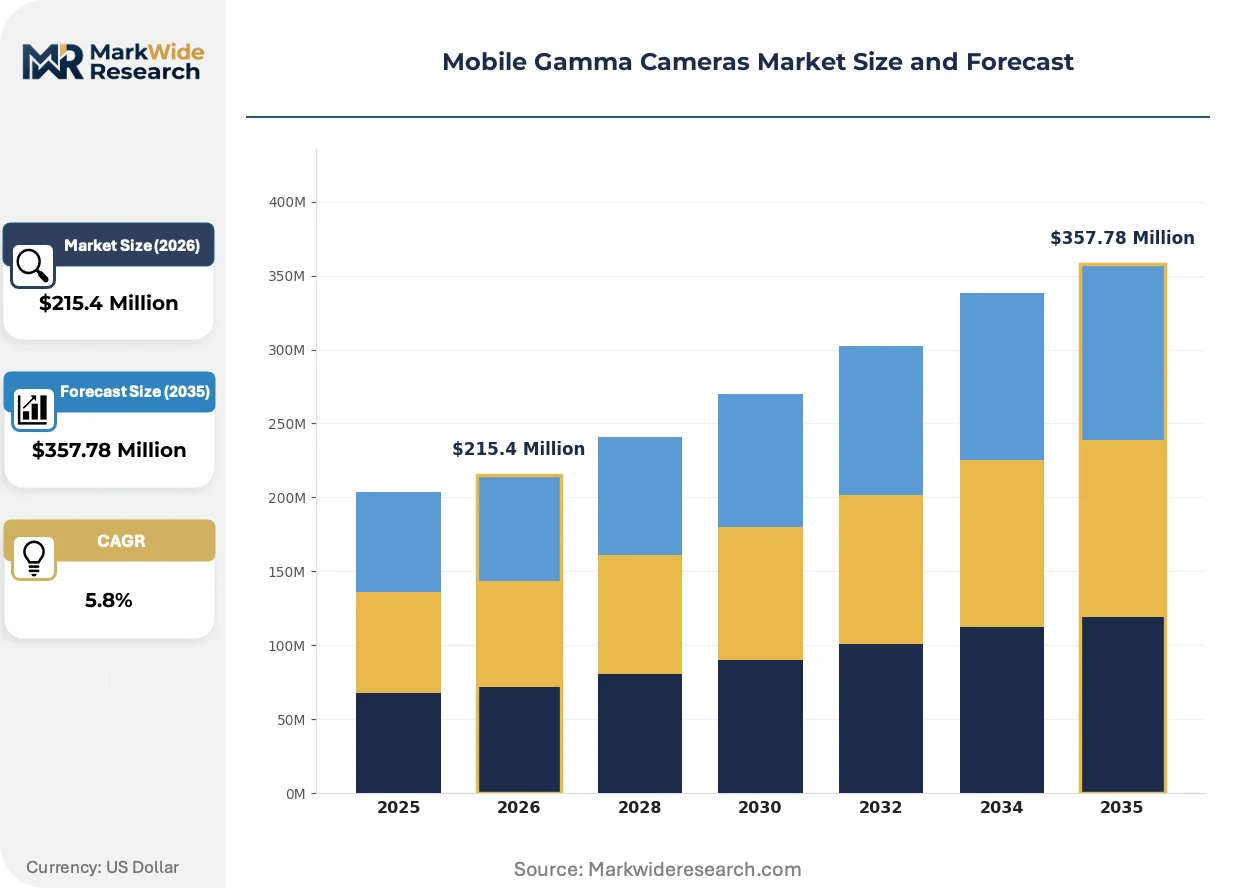
Market Dynamics
The central force shaping the market is the decentralization of nuclear imaging services. This shift moves diagnostic procedures from large, dedicated hospital departments to more flexible settings like operating rooms, bedsides, and specialized outpatient centers, driven by portable system designs.
Growth Catalysts
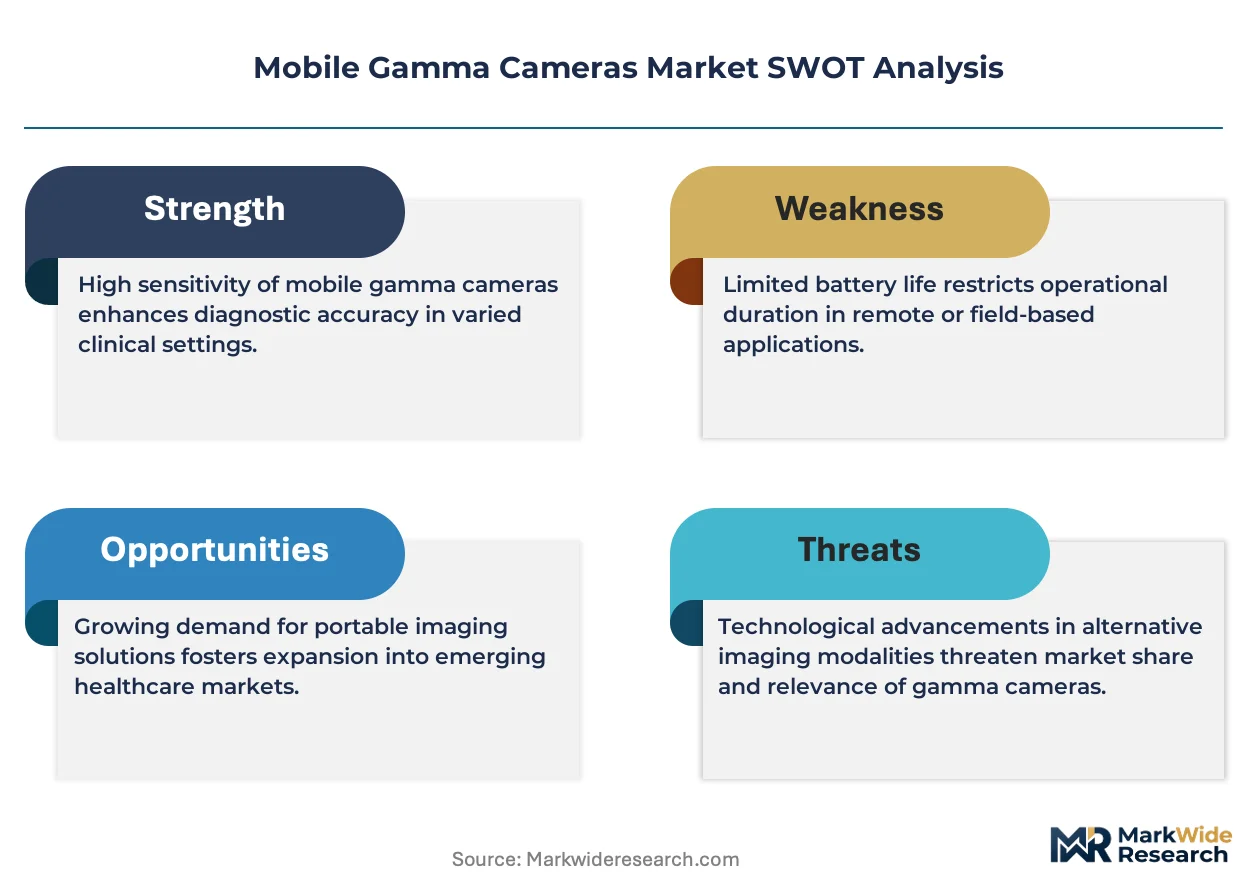
- Oncology Applications:Expanded use in oncology for precise tumor localization and real-time intraoperative margin assessment during surgical procedures provides a significant clinical pull for mobile systems.
- Detector Technology:Advancements in solid-state Cadmium Zinc Telluride (CZT) detectors are improving image resolution and diagnostic accuracy, making mobile units more clinically viable compared to older technologies.
- Geographic Demand Concentration:Uptake within developed healthcare networks, such as in Germany, is establishing a clear precedent for integrating mobile gamma cameras into hospital and specialized diagnostic center workflows.
Market Restraints
- High Capital Cost:The initial acquisition cost for advanced mobile systems, particularly those using premium CZT detectors, remains a significant barrier for smaller clinics and hospitals with constrained capital budgets.
- Regulatory Scrutiny:Rigorous and lengthy premarket approval processes from bodies like the US FDA and notified bodies under the EU's MDR create high entry barriers and extend product development timelines.
- Radiotracer Logistics:The efficacy of mobile gamma cameras depends on the availability of radiotracers, which have short half-lives and complex supply chains, creating logistical hurdles for on-demand imaging.
Strategic Opportunities
- Underpenetrated Geographies:There is significant potential for expansion in countries like Japan, where an aging population and a focus on advanced healthcare create a receptive environment for portable diagnostic imaging solutions.
- Artificial Intelligence Integration:Incorporating AI and machine learning algorithms for automated image reconstruction, noise reduction, and diagnostic analysis presents a major opportunity to enhance system capabilities and clinical utility.
- New Clinical Applications:Exploring use cases beyond cardiology and oncology, such as in neurology for bedside stroke assessment or in rheumatology for inflammation imaging, can open new revenue streams.
Industry Challenges
- Specialized Skills Gap:A shortage of nuclear medicine technologists and physicians trained specifically on the operation and interpretation of images from portable, hand-held gamma camera systems limits wider adoption.
- Data Integration Complexity:Ensuring seamless connectivity and data transfer between mobile gamma cameras and existing hospital Picture Archiving and Communication Systems (PACS) or Radiology Information Systems (RIS) is a persistent technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Gamma Cameras Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Portable, Hand-held, Miniature End User: Hospitals, Diagnostic Centers, Research Institutions, Mobile Imaging Services Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Time-of-Flight, Image Reconstruction Application: Oncology, Cardiology, Neurology, Bone Scanning |
| Companies Covered | CMR Naviscan Corporation, Spectrum Dynamics Medical, Mediso Ltd., MiE GmbH, Oncovision, Crystal Photonics GmbH, DDD-Diagnostic A/S, Dilon Technologies, Digirad Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Gamma Cameras Market Strategic Shifts & Innovations
Miniaturization and enhanced detector sensitivity are enabling a new class of portable and hand-held systems. These innovations are moving gamma camera imaging beyond the confines of the traditional nuclear medicine department and directly to the point of care.
Cadmium Zinc Telluride (CZT) detector technology directly converts gamma radiation into a digital signal, eliminating the need for bulky photomultiplier tubes. Outpatient oncology clinics and specialized cardiology centers are adopting these systems for their superior spatial and energy resolution. This technology is fragmenting the conventional, centralized hospital imaging model by enabling high-fidelity diagnostics in smaller, distributed clinical environments.
The EU's Medical Device Regulation (MDR) is forcing a higher standard of clinical evidence for medical devices seeking CE marking. This increases the time and cost associated with demonstrating device safety and diagnostic efficacy through rigorous trials. Manufacturers of hand-held systems for surgical guidance are most affected, as they must now generate more robust clinical data to substantiate performance claims.
A notable behavioral change is the rise of fee-for-service contracts with third-party mobile imaging providers. This model allows healthcare facilities to access advanced diagnostic capabilities without the large upfront capital investment, displacing traditional direct equipment sales. This procurement pattern is particularly visible in the United States, where outpatient surgery centers and community hospitals use it to manage costs and operational flexibility.
Mobile Gamma Cameras Market Segmentation
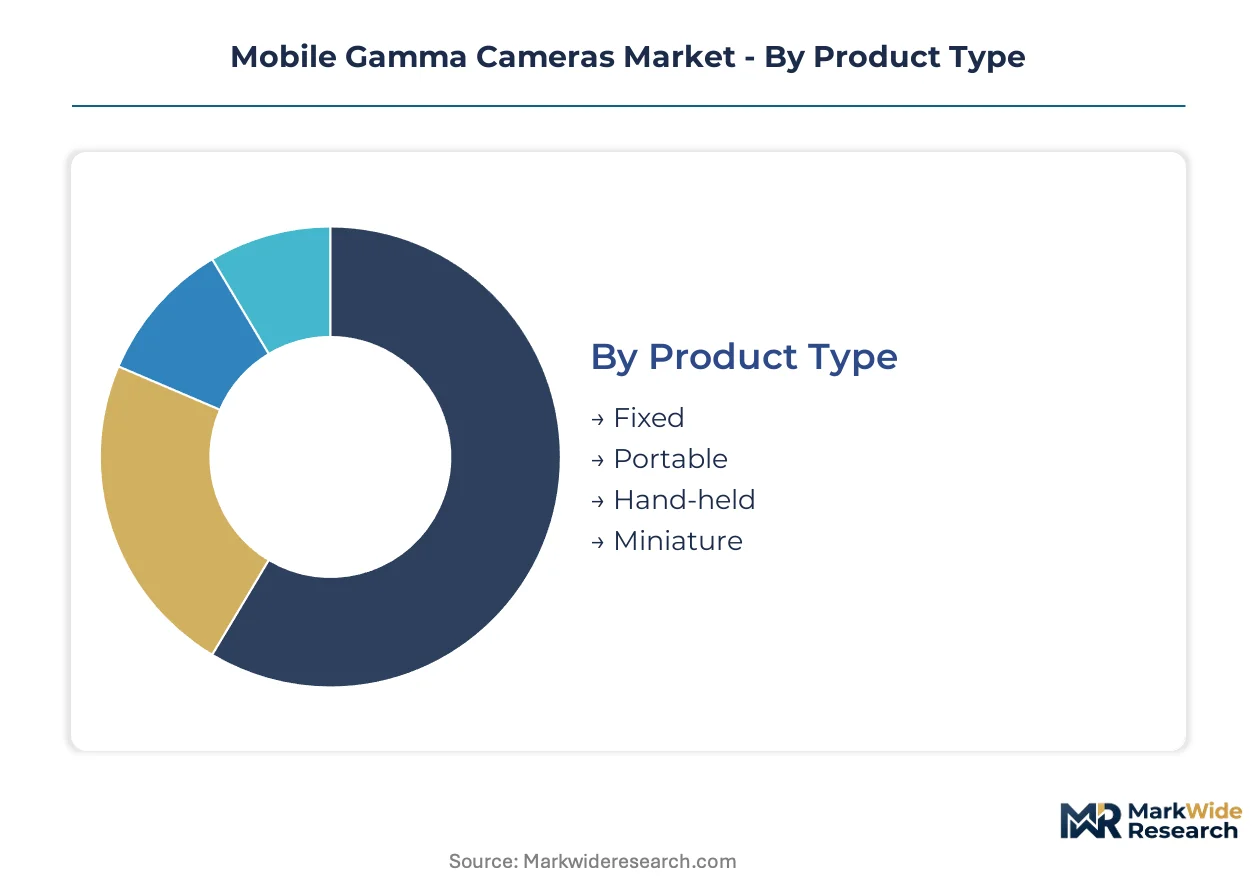
The Mobile Gamma Cameras Market segments across several critical dimensions, reflecting diverse product functionalities and end-user needs. Understanding these distinctions reveals where technological innovation and service delivery models concentrate. This segmentation highlights the evolving landscape of nuclear imaging beyond traditional hospital settings.
Product Type:
Margin pools within product types reflect the complexity and specialized utility of each system. Advanced portable and hand-held units often command higher margins due to their integrated technologies and point-of-care flexibility.
- Portable:Portable systems are designed for easy movement within a healthcare facility, often featuring integrated carts or lighter builds. Demand for these systems is concentrating in specialized diagnostic centers in countries like Germany, driven by the need for flexible deployment and reduced patient transport.
- Hand-held:Hand-held units offer maximum maneuverability, enabling bedside or intraoperative imaging with direct point-of-care application. Uptake is significant in outpatient oncology clinics in the United States, where surgical guidance and margin assessment require immediate feedback.
- Fixed:Fixed gamma cameras are stationary units typically found in dedicated nuclear medicine departments, providing high throughput for routine diagnostics.
- Miniature:Miniature systems represent an emerging class, offering ultra-compact designs for highly specific, localized imaging tasks.
The dominant share belongs to Portable systems, while Hand-held units are closing the gap fastest.
End User:
End-user segmentation reveals the primary channels for mobile gamma camera deployment and service consumption. Each segment possesses distinct procurement patterns and operational requirements influencing system design.
- Hospitals:Hospitals represent a foundational end-user segment, integrating mobile gamma cameras into various departments for diverse diagnostic needs. Demand is strong in large hospital networks across Japan, driven by an aging population requiring accessible diagnostic services.
- Mobile Imaging Services:Mobile imaging services deliver diagnostic capabilities directly to patient locations, often contracting with smaller clinics or remote facilities. This model is gaining traction in the United States, addressing capital cost barriers for healthcare providers.
- Diagnostic Centers:Specialized diagnostic centers focus on outpatient imaging, leveraging mobile units for efficiency and patient convenience.
- Research Institutions:Research institutions utilize mobile gamma cameras for preclinical studies and clinical trials, exploring new radiotracer applications.
Hospitals maintain the largest volume of procedures, with Mobile Imaging Services expanding most quickly.
Technology:
Technological differentiation dictates image quality, diagnostic accuracy, and system complexity within mobile gamma cameras. Detector advancements and processing capabilities define system performance.
- Single Photon Emission Computed Tomography:SPECT technology uses gamma rays to create 3D images of organ function, relying on radiotracers that emit single photons. Digital SPECT systems are seeing increased adoption in Germany, offering improved image resolution for oncology applications.
- Image Reconstruction:Image reconstruction algorithms process raw detector data to form diagnostic images, often employing iterative methods to enhance clarity. Integration of artificial intelligence for this process is a key area of development, improving diagnostic confidence.
- Positron Emission Tomography:PET technology detects positrons from radiotracers, providing high-resolution functional images, often for oncology and neurology.
- Time-of-Flight:Time-of-Flight technology enhances PET imaging by measuring the arrival time difference of annihilation photons, improving image contrast and signal-to-noise ratio.
Single Photon Emission Computed Tomography forms the technology bedrock, while Image Reconstruction advancements show the steepest expansion trajectory.
Application:
Application segments highlight the specific clinical areas where mobile gamma cameras provide critical diagnostic value. Each application presents unique requirements for image resolution and functional assessment.
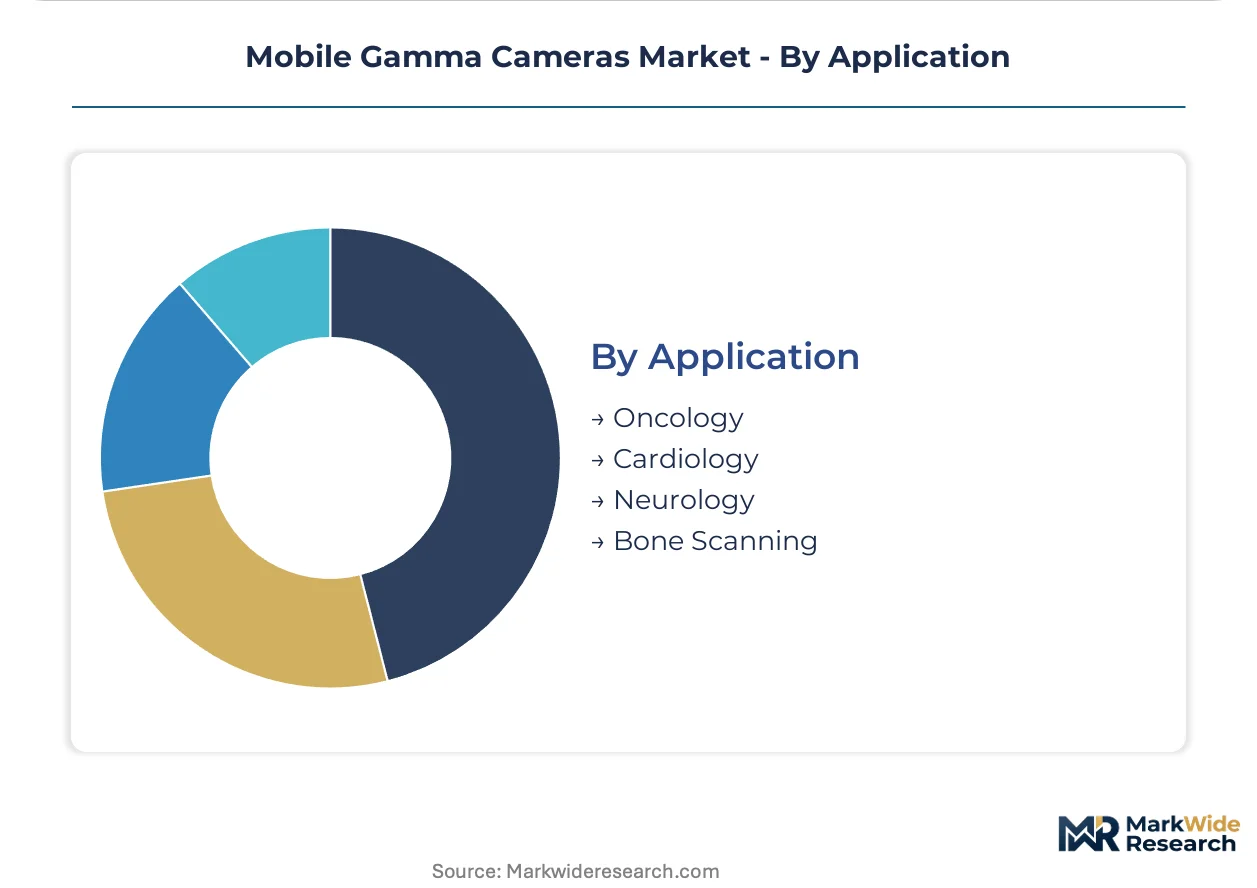
- Oncology:Oncology applications utilize mobile gamma cameras for precise tumor localization, sentinel lymph node mapping, and intraoperative margin assessment. Demand is substantial in developed healthcare systems, supporting surgical decision-making in countries like the United States.
- Cardiology:Cardiology applications primarily involve myocardial perfusion imaging to assess heart muscle blood flow and function, particularly for diagnosing coronary artery disease. These systems are well-established in outpatient cardiology centers, providing routine diagnostic support.
- Neurology:Neurology leverages mobile gamma cameras for assessing brain function, blood flow, and receptor activity, aiding in conditions like stroke and dementia.
- Bone Scanning:Bone scanning applications detect bone abnormalities, infections, or metastases, using radiotracers that accumulate in areas of increased bone turnover.
Oncology and Cardiology represent the largest application areas, with Neurology gaining share fastest among emerging uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust healthcare infrastructure, including advanced hospital networks and specialized diagnostic centers, underpins regional variations in mobile gamma camera adoption. This distributed network facilitates the integration of portable imaging solutions directly into patient care pathways. Demand patterns reflect both established clinical practices and emerging technological advancements across key geographies.
United States
The United States market sees significant demand from outpatient oncology clinics and for surgical guidance applications. US FDA premarket approval processes rigorously govern device introduction, ensuring safety and efficacy. Outpatient surgery centers in major metropolitan areas like New York City and Los Angeles increasingly utilize hand-held units for intraoperative margin assessment.
Germany
Germany's market benefits from strong uptake in specialized diagnostic centers and established hospital networks. CE marking under the EU's Medical Device Regulation (MDR) sets stringent compliance standards for devices. Hospital networks in regions such as Bavaria and North Rhine-Westphalia are integrating portable systems for flexible deployment, particularly digital SPECT units.
Japan
Japan's market is driven by an aging population and a strong focus on accessible diagnostic services within large hospital networks. Approval from the Pharmaceuticals and Medical Devices Agency (PMDA) ensures devices meet national health standards. Major hospital systems in Tokyo and Osaka are driving the adoption of mobile units to enhance diagnostic capabilities at the point of care.
China
Expanding healthcare infrastructure and an increasing oncology burden fuel demand for diagnostic flexibility in China. Approval from China's National Medical Products Administration (NMPA) is critical for market entry and product commercialization. Rapid expansion in urban centers like Shanghai and Beijing is fostering demand for portable systems in specialized diagnostic clinics.
France
France's advanced healthcare system and focus on oncology applications create demand for bedside imaging solutions. CE marking under the EU's Medical Device Regulation (MDR) applies to all medical devices sold within the country. Public and private hospitals in regions such as Île-de-France are adopting mobile gamma cameras for enhanced intraoperative imaging and patient convenience.
Mobile Gamma Cameras Market Key Industry Players
Listed leaders compete with private specialists across detector technology and system form factors within the mobile gamma cameras market. The market exhibits a tiered structure, with established medical imaging conglomerates alongside nimble, technology-focused startups. Strategic archetypes include diversified medical device manufacturers, specialized nuclear medicine imaging providers, and innovators focusing on portable and hand-held units. Geographic expansion into underpenetrated markets and continuous portfolio diversification through new clinical applications represent dominant competitive moves.
Specialists in advanced imaging solutions include Mediso Ltd., an Hungary-based company with a broad portfolio spanning preclinical research and clinical diagnostics. This company occupies a position across multiple end-user types, from research institutions to hospitals. Spectrum Dynamics Medical, an Israel-based company, exemplifies a focused approach on digital SPECT systems, capturing the shift towards flexible, lower-cost settings in specialized diagnostic centers. Dilon Technologies, a US-based company, anchors a segment focused on high-resolution, small field-of-view systems, particularly suited for outpatient oncology and surgical applications. These players collectively illustrate the market's drive towards specialized, point-of-care imaging solutions.
| Leading Market Players |
|---|
| CMR Naviscan Corporation |
| Spectrum Dynamics Medical |
| Mediso Ltd. |
| MiE GmbH |
| Oncovision |
| Crystal Photonics GmbH |
| DDD-Diagnostic A/S |
| Dilon Technologies |
| Digirad Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization in specialized manufacturing facilities for advanced medical imaging systems shapes both supply concentration and the underlying price floors for mobile gamma cameras. This dynamic influences market entry costs and the competitive landscape for device manufacturers.
Pricing Analysis
Volume-discount tiering structures characterize mobile gamma camera procurement, with larger hospital networks often securing more favorable terms. The dominant pricing model remains per-unit transactional for direct sales, though fee-for-service contracts with mobile imaging providers are gaining traction. Price differentiation stems from detector technology, specifically Cadmium Zinc Telluride (CZT) integration, and advanced software features like AI for image reconstruction. Pricing pressure stems from constrained capital budgets in smaller clinics and hospitals. Mobile imaging services demonstrate higher price sensitivity due to their operational model, while large hospital systems prioritize advanced diagnostic capabilities.
Supply Chain Analysis
Germany and the United States anchor the manufacturing of high-precision components and final assembly for mobile gamma cameras. The supply chain draws from specialized input providers for Cadmium Zinc Telluride (CZT) crystals and complex digital signal processors. Single-source vulnerability for these highly specialized detector components presents a structural risk. Radiotracer logistics, characterized by short half-lives and complex distribution networks, also impact operational efficiency. Distribution runs through direct sales channels to hospitals and specialized diagnostic centers, alongside partnerships with third-party mobile imaging service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the technological inflection point of advanced solid-state detectors and the integration of artificial intelligence for enhanced diagnostic capabilities.
For Market Incumbents: Compound investment in digital SPECT systems and CZT detector technology to maintain a competitive edge against agile startups. Diversify the clinical application portfolio beyond cardiology and oncology into emerging areas like neurology to expand revenue streams. Strategic partnerships with mobile imaging service providers can broaden market reach and mitigate the threat of direct sales displacement.
For New Entrants and Emerging Players: Anchor in specialized niches, such as high-resolution hand-held units for intraoperative margin assessment in outpatient oncology. Focus on underpenetrated geographies like Japan, leveraging the demand from an aging population for accessible diagnostics. A go-to-market angle emphasizing flexible, lower-cost deployment models, such as fee-for-service arrangements, can bypass traditional capital expenditure barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors innovators with proprietary detector technology or advanced AI algorithms. Long-term viability hinges on companies capable of navigating stringent regulatory frameworks and integrating seamlessly into diverse healthcare IT ecosystems. A signal to watch is the expansion of reimbursement codes for new mobile gamma camera applications, indicating broader clinical acceptance and market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI for Image Reconstruction | Enhances diagnostic accuracy and operational efficiency for clinicians in Germany. |
| Expand Hand-held Unit Portfolio | Addresses the growing demand for point-of-care imaging in US outpatient oncology clinics. |
| Form Partnerships with Mobile Imaging Services | Facilitates market access without large capital investments for US healthcare providers. |
| Target Neurology Applications | Opens new revenue streams by exploring use cases beyond traditional cardiology and oncology. |
| Pursue PMDA Approval in Japan | Captures demand from an aging population requiring accessible diagnostic services. |
Research Approach
A standing panel of nuclear medicine physicians, hospital procurement managers, and specialized diagnostic center directors provided ongoing calibration for market trends and technological shifts. This primary research was rigorously validated against secondary sources, including US FDA filings, EU MDR guidance documents, and medical journal publications. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
Consistency checks against external benchmarks informed the analytical framework for market sizing and forecasting. Segmentation dimensions modeled include product type, end-user, technology, and application across the analysis window. Compound annual growth rates were derived from historical data and projected trends in healthcare spending and disease prevalence. Forecast inputs integrated technological development timelines and evolving regulatory landscapes.
Underlying assumptions cover stable healthcare policies and continued investment in diagnostic infrastructure, with deviation risk concentrated in radiotracer supply chain stability and the pace of AI integration. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
United States Mammography Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market