
 Portable OT Light Market | 2026-2036
Portable OT Light Market Size, Share, and Industry Trends Forecast 2026-2036
Portable OT Light Market Analytics
Aluminum heat-dissipation housings are hardening as the preferred chassis material over legacy steel frames in portable OT lights, cutting unit weight by nearly half and improving maneuverability during emergency procedures. Stryker Corporation leverages its surgical systems integration expertise to bundle lighting with operating room infrastructure. Dr. Mach GmbH & Co. KG anchors its position through precision German engineering and specialized color-temperature controls. Koninklijke Philips N.V. competes on LED module longevity and energy efficiency across its healthcare lighting portfolio.
A portable OT light is a mobile surgical illumination device, typically mounted on wheeled stands or ceiling pendants, delivering adjustable color temperatures between 3,500K and 5,000K and light intensities exceeding 100,000 lux for tissue differentiation during operations. LED lights now dominate product type configurations due to thermal efficiency and extended lamp life, while halogen lights retain niche presence in cost-sensitive procurement environments. Battery-operated and hybrid power sources are expanding fastest as surgical centers prioritize uninterrupted illumination during grid failures, whereas grid-powered units remain mature in established hospital infrastructure. Emergency procedures and trauma cases drive application demand where rapid deployment of movable lighting proves critical.
FDA 510(k) clearance requirements shape product entry pathways for manufacturers targeting the United States, while CE marking under the EU MDR governs access to European surgical centers. India's CDSCO enforces import quality standards that filter substandard equipment from reaching hospital procurement channels. Stakeholders must monitor evolving energy-efficiency mandates and battery safety certifications as regulatory scope widens beyond optical performance to encompass power system compliance.
Market Dynamics
India's CDSCO is tightening import quality benchmarks for surgical illumination equipment, forcing manufacturers to redesign power systems and thermal management to meet battery safety certifications alongside optical performance standards.
Growth Catalysts
- Emergency procedure volume:Trauma centers and field surgical units require rapid-deployment lighting systems for unstable environments. Battery-operated LED configurations satisfy this operational need.
- CDSCO import standards:India's national medical device regulator now filters substandard equipment from hospital procurement channels, creating demand for certified hybrid-power units in Maharashtra and Gujarat surgical centers.
- LED thermal efficiency:Solid-state illumination generates minimal heat during extended procedures, reducing tissue desiccation risk and enabling closer positioning to operative fields.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in East Asian manufacturing clusters, exposing OEMs to raw material volatility and logistics bottlenecks.
- Halogen legacy installed base:Cost-sensitive procurement environments in public hospital systems retain functional incandescent units, delaying replacement cycles.
- CE marking complexity under EU MDR:European surgical centers now demand extended clinical evidence for Class IIa device registration, lengthening market entry timelines.
Strategic Opportunities
- Tamil Nadu tertiary expansion:India's southern state is adding hybrid-equipped surgical wings to government medical colleges, creating concentrated demand for maneuverable illumination.
- Color-temperature convergence:Adjustable 3,500K–5,000K systems now integrate with endoscopic camera white-balance protocols, enabling vendor lock-in through surgical ecosystem integration.
- Rural clinic electrification gaps:Off-grid surgical centers in sub-Saharan Africa and South Asia require standalone battery systems with photovoltaic charging compatibility.
Industry Challenges
- FDA 510(k) optical equivalence documentation:Manufacturers must demonstrate substantial equivalence to predicate devices for LED spectral output claims, compressing development timelines.
- Legacy pendant infrastructure retrofit:Ceiling-mounted halogen systems in established hospitals require structural reinforcement for lighter LED replacements, complicating installation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable OT Light Market |
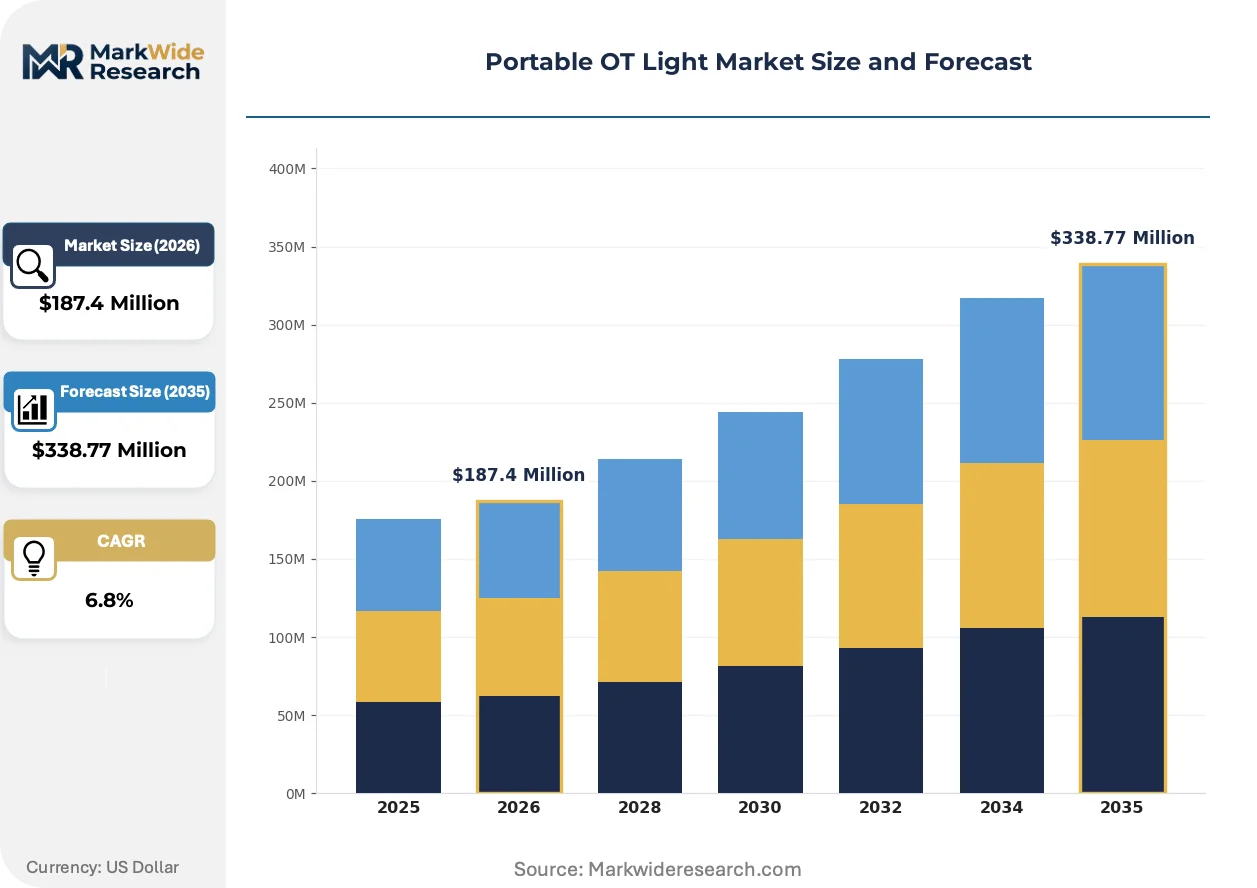
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Halogen Lights, Fluorescent Lights, Xenon Lights Application: Emergency Procedures, Elective Surgeries, Trauma Cases, Minor Operations End User: Hospitals, Surgical Centers, Clinics, Mobile Units Power Source: Battery Operated, Grid Powered, Hybrid, Rechargeable |
| Companies Covered | Stryker Corporation, Dr. Mach GmbH & Co. KG, Koninklijke Philips N.V., STERIS, Getinge AB, Skytron, LLC, Herbert Waldmann GmbH & Co. KG, Maquet, Magnatek Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable OT Light Market Evolving Landscape
Illumination hardware is converging with surgical workflow software, transforming standalone lights into data-capture nodes that integrate with operating room documentation systems and real-time tissue perfusion monitoring.
Aluminum heat-dissipation housings are expanding into emergency and trauma applications where rapid repositioning between bays determines procedural throughput. Aluminum chassis cut unit weight by nearly half versus legacy steel frames, enabling single-operator maneuverability during critical interventions. This material transition is compressing the addressable market for conventional fabricated steel enclosures.
EU MDR compliance timelines are reshaping competitive access patterns for European surgical centers. Extended clinical evaluation requirements for Class IIa surgical devices now demand post-market surveillance data that legacy halogen manufacturers lack. LED specialists with existing CE technical files are capturing shelf space previously held by incumbents unable to justify re-registration costs.
Hospital procurement committees now unbundle after-sales service from capital equipment contracts, forcing lighting OEMs to compete on discrete maintenance pricing. Tertiary centers in Maharashtra and Gujarat negotiate multi-year service agreements separately from initial hardware acquisition. This pattern is most visible in Indian states where public sector tendering mandates transparent lifecycle cost disclosure.
Portable OT Light Market Segmentation
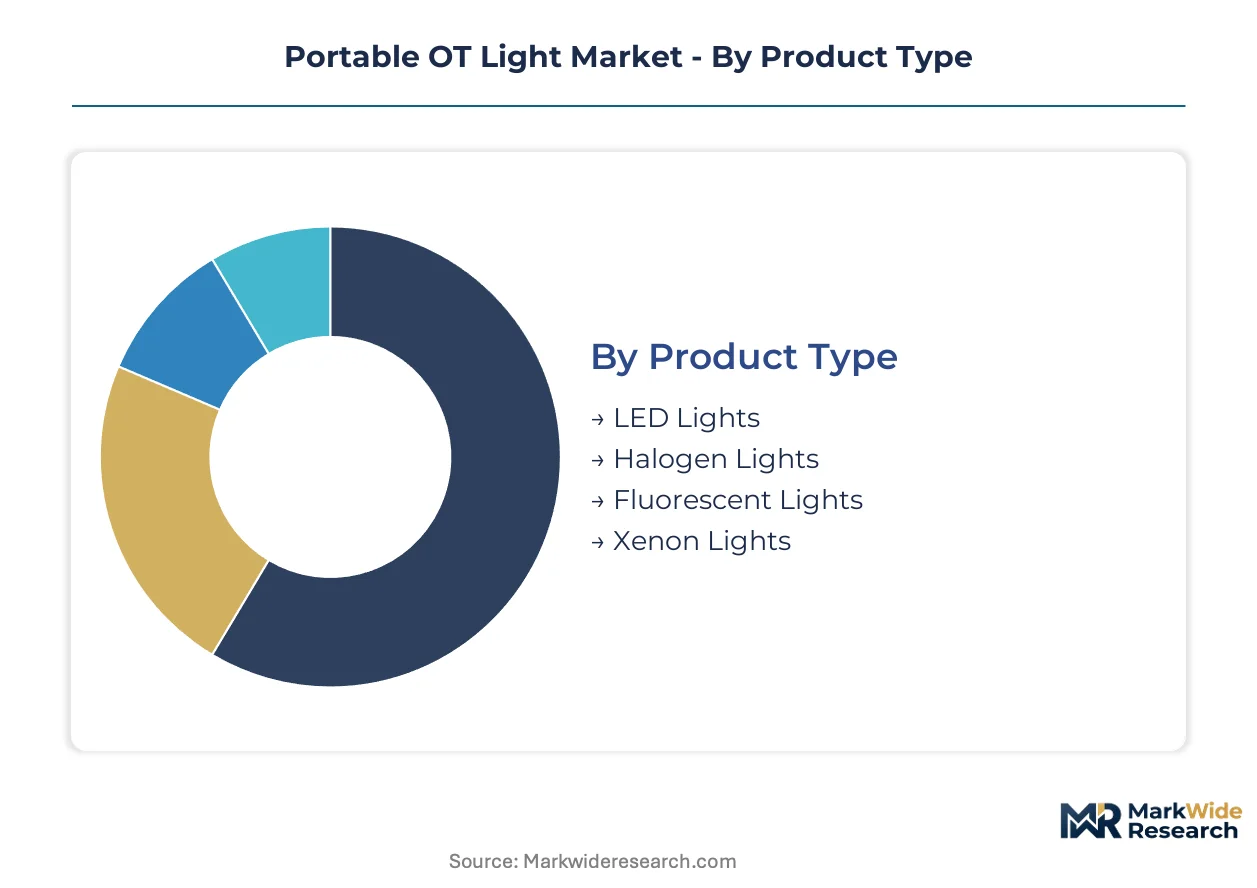
Portable OT light procurement patterns diverge sharply across surgical settings, with power source reliability and illumination precision driving category-specific demand. Understanding these segment boundaries reveals where manufacturers must align thermal engineering, battery chemistry, and optical specifications to capture procurement committee attention.
Product Type:
Supply concentration in LED module manufacturing has compressed pricing for solid-state surgical illumination while leaving legacy technologies dependent on dwindling component sources.
- LED Lights:Solid-state arrays deliver 3,500K–5,000K adjustable color temperatures with thermal efficiency that permits closer positioning to operative fields. Maharashtra and Gujarat tertiary hospitals specify LED units exclusively under CDSCO import quality benchmarks that filter substandard imports from procurement channels.
- Halogen Lights:Tungsten-filament technology retains presence where procurement committees prioritize capital cost minimization over lifecycle efficiency. India's public hospital systems in cost-sensitive environments delay replacement cycles for functional incandescent units despite higher operating expenditures.
- Fluorescent Lights:Gas-discharge tubes with phosphor coatings provide diffuse illumination for minor procedures in budget-constrained clinic settings.
- Xenon Lights:High-intensity arc lamps generate concentrated beams for specialized surgical applications requiring exceptional color rendering indices.
Today's leader: LED Lights. Tomorrow's challenger: Xenon Lights in specialized niches demanding spectral precision beyond LED capabilities.
Application:
Procedure urgency determines mobility requirements and power redundancy specifications, with emergency settings commanding premium pricing for rapid-deployment configurations.
- Emergency Procedures:Trauma bays require instantaneous illumination deployment where grid reliability cannot be assumed. Battery-operated LED configurations satisfy operational needs in unstable environments across Tamil Nadu government medical college expansions.
- Trauma Cases:Field surgical units and mass casualty scenarios demand hybrid-power systems with photovoltaic charging compatibility for off-grid deployment.
- Elective Surgeries:Scheduled procedures in established hospital infrastructure utilize grid-powered pendant systems with predictable demand profiles.
- Minor Operations:Outpatient clinics and ambulatory surgical centers prioritize maneuverable stand-mounted units for dermatological and ophthalmological interventions.
Emergency Procedures command procurement premium. Trauma Cases gain share fastest as disaster preparedness budgets expand.
End User:
Capital allocation authority varies dramatically across facility types, with surgical centers unbundling service contracts from hardware acquisition while hospitals negotiate bundled enterprise agreements.
- Surgical Centers:Specialized facilities in Maharashtra and Gujarat negotiate multi-year maintenance agreements separately from initial hardware procurement under transparent lifecycle cost disclosure mandates. These centers specify hybrid-power configurations as standard equipment.
- Hospitals:Tertiary institutions with established ceiling pendant infrastructure face structural reinforcement requirements when retrofitting lighter LED replacements into legacy mounting systems.
- Clinics:Primary care settings prioritize compact stand-mounted units for minor procedures with limited capital budgets.
- Mobile Units:Field hospitals and disaster response teams require ruggedized battery systems with rapid deployment capabilities for unstable grid environments.
Surgical Centers drive specification innovation. Mobile Units represent the steepest expansion trajectory as disaster medicine investment accelerates.
Power Source:
Battery cell production concentration in East Asian manufacturing clusters exposes OEMs to raw material volatility that shapes sourcing strategies for portable illumination systems.
- Hybrid:Dual grid-battery configurations with automatic failover dominate procurement specifications in Tamil Nadu tertiary expansions and Gujarat surgical center upgrades. CDSCO battery safety certifications filter substandard power systems from import channels.
- Battery Operated:Standalone lithium-ion systems with extended runtime satisfy off-grid surgical centers in sub-Saharan Africa and rural South Asia where photovoltaic charging compatibility addresses electrification gaps.
- Grid Powered:Mature infrastructure in established hospital systems retains dominance where electrical reliability permits capital cost minimization.
- Rechargeable:Removable battery packs with hot-swap capability enable continuous operation during extended procedures without ceiling-mounted infrastructure.
Hybrid configurations capture specification leadership. Battery Operated systems gain fastest as rural electrification gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's surgical corridor spanning Maharashtra, Gujarat, and Tamil Nadu anchors demand for battery-operated LED configurations as CDSCO import quality benchmarks reshape procurement specifications. Regulatory tightening across multiple geographies is filtering substandard equipment from hospital channels and elevating certified hybrid-power systems.
United States
FDA 510(k) clearance requirements govern market entry pathways for surgical illumination manufacturers targeting American surgical centers. The regulator's substantial equivalence documentation demands compress development timelines for LED spectral output claims. Texas and Florida trauma centers drive procurement of rapid-deployment battery configurations for emergency procedure volume.
Germany
CE marking under EU MDR extends clinical evidence requirements for Class IIa surgical devices, lengthening registration timelines for manufacturers. Bavarian and Baden-Württemberg surgical centers prioritize precision-engineered units with specialized color-temperature controls. The country's national medical device regulator enforces post-market surveillance data collection that legacy halogen manufacturers struggle to satisfy.
India
CDSCO battery safety certifications now filter substandard power systems from import channels, forcing redesign of thermal management alongside optical performance. Maharashtra and Gujarat tertiary hospitals specify hybrid-power configurations as standard equipment under transparent lifecycle cost mandates. Tamil Nadu government medical college expansions are adding surgical wings equipped with maneuverable illumination systems.
China
NMPA medical device registration standards shape domestic manufacturing quality benchmarks for export-oriented surgical lighting producers. Yangtze River Delta and Pearl River Delta industrial clusters concentrate LED module production capacity supplying global OEM assembly lines. The country's dual carbon goals accelerate energy-efficiency mandates affecting power system compliance scope.
Brazil
ANVISA medical device regulations govern market access for imported surgical illumination equipment in Latin America's largest healthcare market. São Paulo and Rio de Janeiro surgical centers balance capital cost constraints against lifecycle efficiency when evaluating LED retrofits. Public hospital procurement systems retain functional halogen units in cost-sensitive environments despite higher operating expenditures.
Portable OT Light Market Competitive Landscape
Strategic partnerships dominate the current landscape as lighting OEMs bundle hardware with surgical workflow software and operating room infrastructure. The vendor base clusters around three tiers: diversified medical technology conglomerates with surgical systems integration expertise, precision engineering specialists with German and European manufacturing heritage, and regional fabricators serving cost-sensitive procurement channels. Two archetypes define competitive positioning: ecosystem integrators pursuing vendor lock-in through surgical workflow convergence, and component specialists deepening control over LED module and battery chemistry supply. M&A activity and technology licensing agreements represent the dominant competitive moves as firms address thermal management and power system compliance requirements.
Among diversified medical technology conglomerates, Stryker Corporation and STERIS exemplify the ecosystem integration archetype through their surgical infrastructure bundling strategies. Dr. Mach GmbH & Co. KG occupies a position within the precision engineering tier, its German corporate structure signaling specialized manufacturing heritage. Koninklijke Philips N.V. anchors the lighting technology specialist vector, leveraging LED module longevity capabilities across healthcare portfolios. These three companies represent distinct competitive positioning vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Stryker Corporation |
| Dr. Mach GmbH & Co. KG |
| Koninklijke Philips N.V. |
| STERIS |
| Getinge AB |
| Skytron, LLC |
| Herbert Waldmann GmbH & Co. KG |
| Maquet |
| Magnatek Enterprises |
| Others |
Value Network & Pricing Analysis
Family-owned German precision engineering specialists anchor premium-tier pricing discipline through captive LED module assembly and in-house thermal management fabrication, insulating their cost structures from East Asian battery cell volatility while forcing price competition onto distributors of commoditized halogen alternatives.
Pricing Analysis
Input-cost pass-through from lithium-ion cell volatility runs unevenly across manufacturer tiers. Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-certified hybrid systems from uncertified grid-powered imports and legacy halogen refurbishments. Price differentiation hinges on battery safety certification grade and after-sales service bundling. Pricing pressure stems from procurement committee unbundling of maintenance contracts in Maharashtra and Gujarat public tenders. Public hospital systems exhibit highest price sensitivity; tertiary surgical centers in Tamil Nadu demonstrate lowest sensitivity due to transparent lifecycle cost mandates.
Supply Chain Analysis
Direct-to-hospital channels handle volume procurement from tertiary surgical centers, while distributor networks serve clinic and mobile unit segments with fragmented demand. Manufacturing concentrates in China, Germany, and India. LED module production draws from Yangtze River Delta industrial clusters; battery cell supply rests on South Korean and Japanese chemistry specialists. Single-source vulnerability in lithium-ion cathode materials exposes OEMs to raw material volatility. Distribution runs through medical device distributors with GPO contracts in established hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid-power configurations where aluminum chassis cost-down curves intersect with CDSCO certification premiums, compressing production costs while elevating average selling prices.
For Market Incumbents: To counter EU MDR compliance cost inflation, deepen backward integration into LED driver electronics and captive battery pack assembly. Prioritize CE technical file migration ahead of legacy halogen manufacturer attrition. Channel control through exclusive distributor agreements in Gujarat and Maharashtra surgical center networks protects pricing power against emerging regional fabricators. For New Entrants and Emerging Players: Enter via rural clinic electrification gaps in sub-Saharan Africa and South Asia where photovoltaic-compatible battery systems face minimal incumbent penetration. Target off-grid surgical centers with standalone lithium-ion configurations. Pursue ANVISA fast-track registration for Brazilian public hospital procurement channels as a beachhead into Latin American cost-sensitive environments. For Investors and Strategic Acquirers: Valuations sit cheapest among precision engineering specialists with dormant CE technical files and underutilized German manufacturing capacity. Five-to-ten year viability favors OEMs with integrated thermal management and battery chemistry capabilities. Watch CDSCO import quality benchmark expansion into additional Indian states as inflection signal for certified hybrid-power demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Certification Investment | Unlocks access to Maharashtra and Gujarat tertiary hospital procurement channels under tightened import quality benchmarks. |
| LED Module Longevity Partnership | Philips and Stryker leverage semiconductor supplier alliances to extend warranty terms beyond halogen replacement cycles. |
| Aluminum Chassis Manufacturing Scale-Up | Dr. Mach and Herbert Waldmann expand German fabrication capacity to capture emergency procedure maneuverability demand. |
| Battery Safety Certification Pathway | Hybrid-power OEMs redesign thermal management to meet India's CDSCO battery safety mandates alongside optical standards. |
| Surgical Workflow Software Integration | Stryker bundles illumination hardware with OR documentation systems to create vendor lock-in through ecosystem convergence. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and CDSCO regulatory affairs specialists grounded qualitative insights in procurement decision-making realities. Secondary validation drew from FDA 510(k) filings, CDSCO import quality notifications, EU MDR technical documentation databases, and hospital procurement tender records. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up modeling aggregated procedure volume forecasts, replacement cycle assumptions, and penetration rates across LED, halogen, and hybrid-power configurations. Top-down analysis calibrated total addressable market against healthcare capital expenditure trends and surgical infrastructure investment patterns. Segmentation dimensions spanned product type, power source architecture, end-user facility tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market estimates, stress-tested against battery cell supply volatility and regulatory timeline slippage.
Inputs from CDSCO notification archives and EU MDR transition databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly demand estimates. Forecasts reflect assumptions regarding CDSCO enforcement consistency, lithium-ion cell pricing stability, and EU MDR Class IIa registration timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Needle Destroyer Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Peripheral Embolization Device Market