
 AI-Powered Mental Health Solutions Market | 2026-2036
AI-Powered Mental Health Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Powered Mental Health Solutions Market Insights
Market Context
The FDA's software-as-a-medical-device framework is realigning the cost-of-entry calculus for AI therapeutic platforms, forcing developers to validate clinical efficacy through controlled trials. Woebot Health leverages its prescription digital therapeutic status to anchor reimbursement conversations with payers. Lyra Health, Inc dominates the employer-sponsored benefit channel through direct contracts with Fortune 500 companies. Headspace Health competes by extending its consumer brand into enterprise and payer segments.
Technical Definition and Segments
AI-powered mental health solutions encompass software systems that deploy natural language processing and machine learning algorithms to assess, monitor, or intervene in psychological conditions, typically operating through mobile or web interfaces with response latencies under 200 milliseconds. These platforms serve commercial and clinical purposes by automating cognitive behavioral therapy delivery, triaging symptom severity, and generating clinician-facing risk alerts. Chatbots capture the largest addressable base among product types due to minimal user friction, while wearable devices represent the fastest-expanding margin pool as biometric validation commands premium pricing. Healthcare providers constitute the most concentrated end-user segment for enterprise contracting, though corporates are scaling fastest as employee assistance programs integrate AI tools into standard benefits.
Regulatory Frame and Outlook
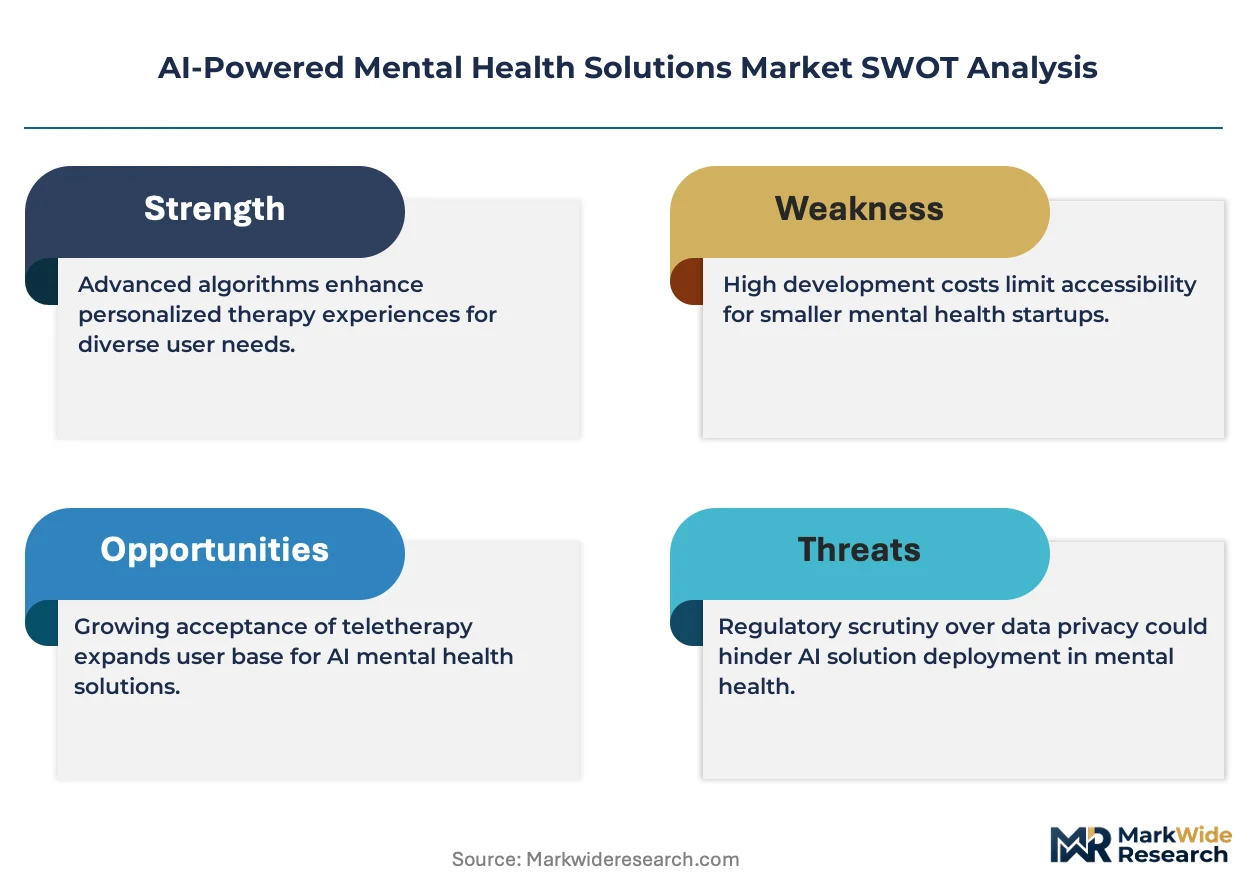
The FDA, HIPAA, and state-level telehealth licensing boards collectively shape product standards, reimbursement pathways, and interstate service delivery for AI mental health platforms in the United States. HIPAA compliance costs function as a de facto barrier to market access, filtering out undercapitalized entrants before they reach scale. Stakeholders must monitor how the FDA's evolving enforcement discretion for AI-based behavioral health software affects predicate device pathways and predicate-less de novo clearances.
Market Dynamics
The FDA's software-as-a-medical-device framework is compressing development timelines for AI therapeutic platforms while elevating clinical validation requirements. Developers now face a bifurcated path: pursue prescription digital therapeutic status with controlled trial evidence, or remain in the wellness category with limited reimbursement access.
Growth Catalysts
- Employer benefit mandates:Fortune 500 companies now contract directly for AI mental health platforms as standard employee assistance program components. This channel bypasses traditional healthcare reimbursement friction.
- HIPAA compliance infrastructure:Cloud providers have pre-built healthcare compliance stacks that reduce startup costs for new entrants. AWS and Azure now offer HIPAA-eligible AI/ML services specifically for behavioral health applications.
- Natural language processing advances:Transformer-based models enable response latencies under 200 milliseconds for therapeutic conversations. This technical threshold unlocks real-time intervention capabilities previously requiring human clinicians.
Market Restraints
- Clinical validation costs:Randomized controlled trials for FDA de novo clearance require capital reserves that filter out pre-revenue developers. The median trial cost for prescription digital therapeutics exceeds typical Series A funding rounds.
- Biometric sensor supply concentration:Wearable device manufacturers depend on a narrow base of optical heart rate and galvanic skin response sensor suppliers. Disruptions at these component vendors cascade through finished goods production.
- Interstate licensing fragmentation:State-level telehealth licensing boards impose patchwork requirements on AI platforms delivering clinician-supervised care. Compliance overhead scales linearly with geographic expansion.
Strategic Opportunities
- Medicaid expansion states:States with expanded Medicaid coverage under the Affordable Care Act show higher reimbursement rates for telehealth mental health services. AI platforms can access this public payer channel with appropriate state-level credentialing.
- Integration with electronic health records:Epic and Cerner interoperability standards create pathways for AI tools to embed directly in clinician workflows. This channel bypasses consumer acquisition costs entirely.
- Biometric-therapy convergence:Wearable devices combining continuous physiological monitoring with just-in-time cognitive behavioral therapy interventions represent an uncaptured premium segment. Hardware-software bundling commands pricing power unavailable to pure software competitors.
Industry Challenges
- Psychiatric oversight shortage:FDA prescription digital therapeutic requirements mandate qualified clinician involvement in algorithm development and risk management. The limited pool of psychiatrists with AI product experience creates hiring bottlenecks.
- Algorithmic bias audit complexity:Platforms must demonstrate equitable performance across demographic subgroups to satisfy FDA expectations and avoid litigation exposure. Validation datasets require deliberate oversampling that extends development timelines.
Report Scope
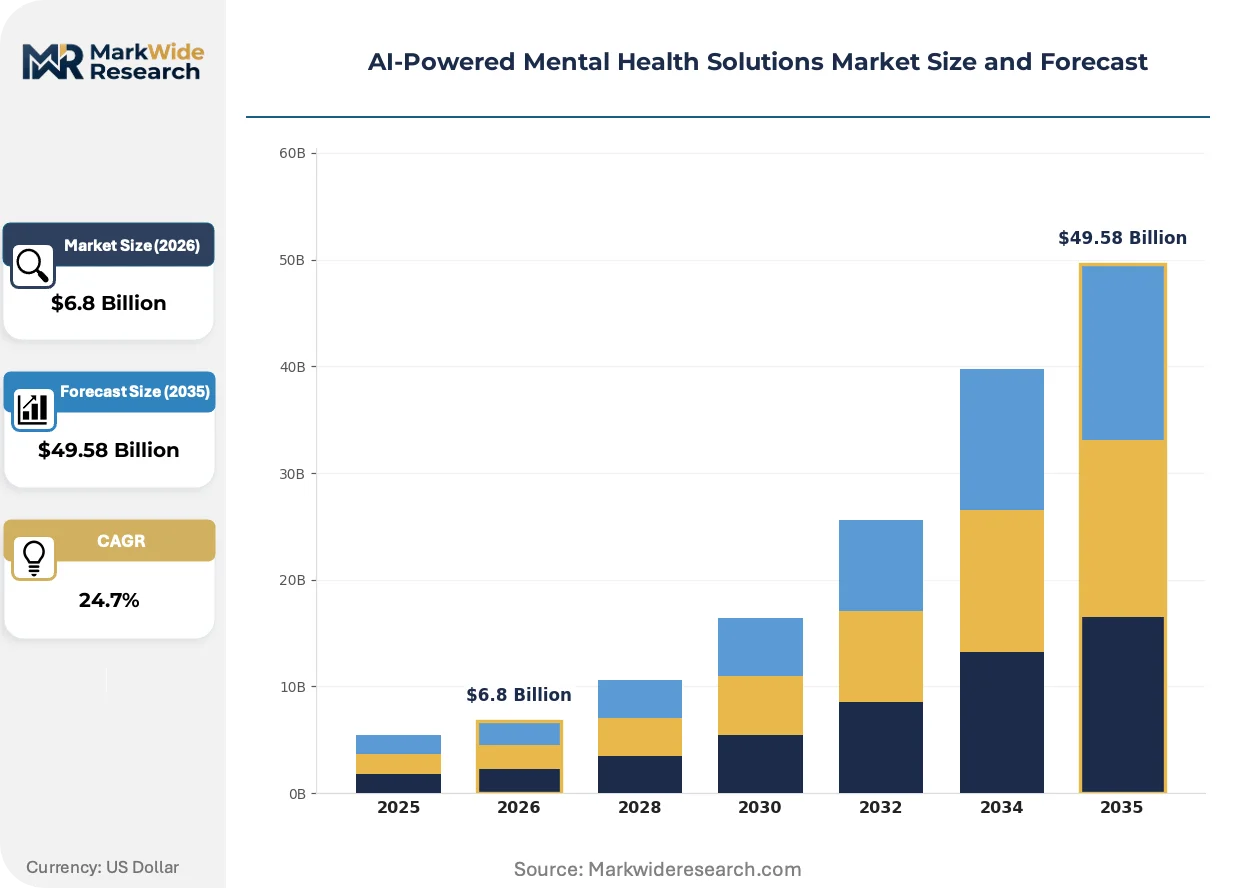
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Powered Mental Health Solutions Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Therapy Apps, Wearable Devices, Virtual Reality End User: Individuals, Healthcare Providers, Corporates, Educational Institutions Delivery Mode: Mobile Platforms, Web Platforms, Telehealth Services, Community Programs Technology: Natural Language Processing, Machine Learning, Cognitive Behavioral Therapy, Data Analytics |
| Companies Covered | Woebot Health, Wysa Ltd, Lyra Health, Inc, Talkspace, Cognoa, Spring Health, Headspace Health, Quartet Health, Koa Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Powered Mental Health Solutions Market Trends and Innovations
Generative AI architectures are restructuring how therapeutic content gets produced and personalized, shifting competitive advantage from static clinical content libraries to dynamic, context-aware response generation. This technical transition favors infrastructure-heavy players with dedicated model training operations.
Large language models fine-tuned on cognitive behavioral therapy protocols are converging with real-time biometric feedback loops from consumer wearables. Healthcare systems including Kaiser Permanente and Mayo Clinic are piloting these integrated stacks for depression and anxiety management. The convergence is compressing the distinction between diagnostic monitoring and therapeutic intervention into single continuous experiences.
The FDA's evolving enforcement discretion for AI-based behavioral health software is creating predicate device uncertainty. Developers pursuing de novo pathways face longer review timelines as the agency builds internal expertise. European developers are responding by sequencing market entry through notified body CE marking under MDR, using European commercial traction to support subsequent FDA submissions.
Buyer concentration in employer-sponsored benefits is shifting procurement authority from HR departments to specialized benefits consultants. Mercer and Willis Towers Watson now maintain dedicated digital health vendor evaluation practices. This channel consolidation is most visible in the United States, where self-insured employers represent the largest addressable commercial pool for AI mental health platforms.
AI-Powered Mental Health Solutions Market Segmentation
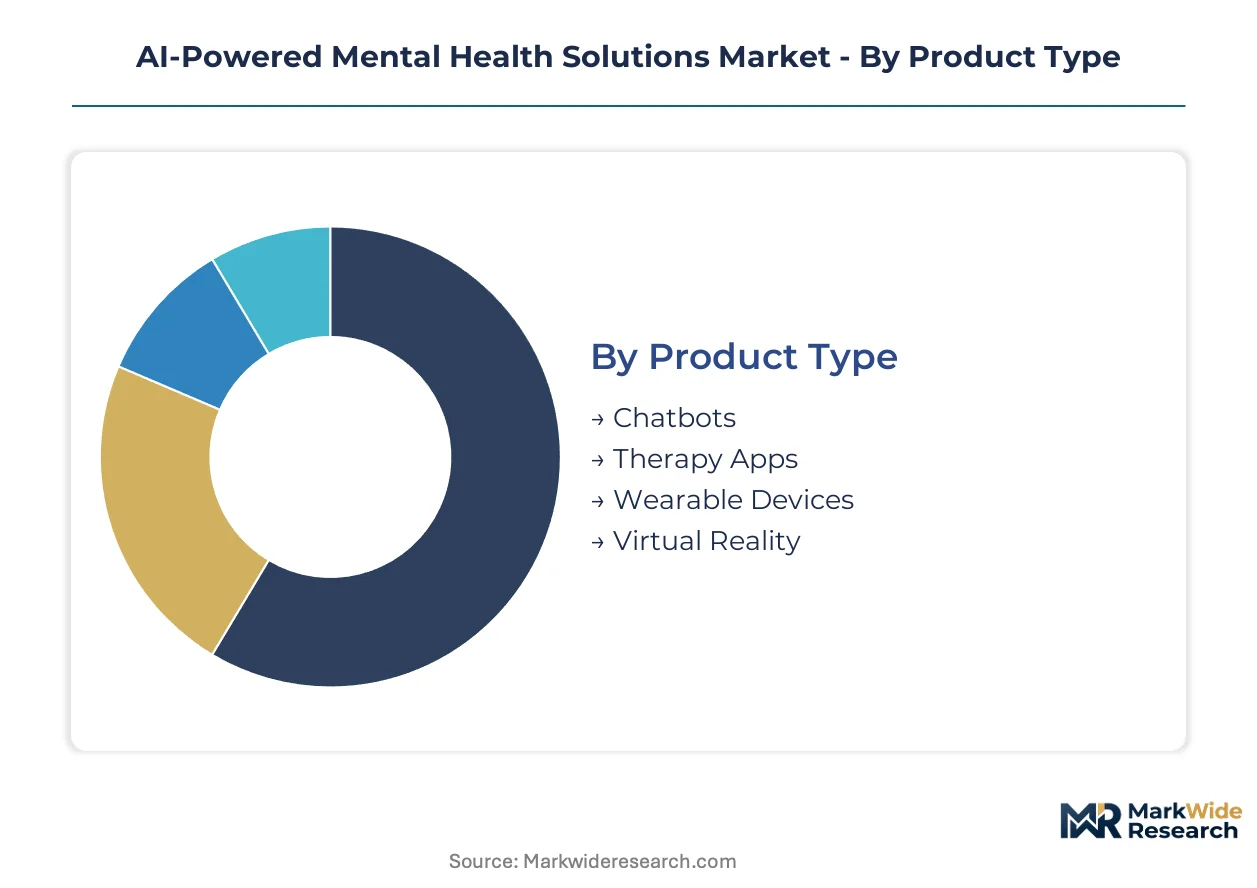
Segmentation in AI-powered mental health solutions reveals how technical architecture, reimbursement pathways, and user context reshape commercial viability. Each category exposes distinct margin structures and regulatory burdens that determine which developers reach sustainable scale.
Product Type:
Product type differentiation tracks user friction thresholds and hardware dependency, separating software-only platforms from biometric-integrated systems.
- Chatbots:Text-based conversational interfaces deploy transformer models for sub-200 millisecond response latency. Demand clusters among self-insured employers seeking zero-friction employee assistance program components, though limited reimbursement access constrains clinical positioning.
- Therapy Apps:Structured digital therapeutic programs delivering cognitive behavioral therapy protocols through guided modules. Healthcare providers in the United States drive enterprise contracting for these platforms as FDA prescription digital therapeutic status unlocks payer reimbursement.
- Wearable Devices:Continuous physiological monitoring hardware paired with algorithmic intervention triggers.
- Virtual Reality:Immersive exposure therapy environments for anxiety and PTSD treatment.
Chatbots lead volumes today; wearable devices are gaining share fastest.
End User:
End user segmentation maps procurement authority from individual consumers to institutional buyers with dedicated mental health budgets.
- Individuals:Direct-to-consumer purchasers accessing subscription-based wellness tools outside reimbursement frameworks. United States consumers dominate this channel, though high churn rates pressure lifetime value calculations for developers.
- Healthcare Providers:Hospital systems and clinical practices integrating AI tools into diagnostic workflows. Epic and Cerner interoperability standards enable embedding directly in electronic health records, bypassing consumer acquisition costs entirely.
- Corporates:Fortune 500 companies contracting for employee assistance program integration.
- Educational Institutions:Universities and K-12 systems licensing campus-wide mental health platforms.
Healthcare providers anchor enterprise value today; corporates are climbing the fastest.
Delivery Mode:
Delivery mode determines regulatory jurisdiction and technical infrastructure requirements, from HIPAA-eligible cloud stacks to state-licensed telehealth compliance.
- Mobile Platforms:Native iOS and Android applications leveraging push notification architecture for just-in-time intervention. United States employer benefit channels concentrate demand here, with AWS and Azure offering pre-built HIPAA-compliant AI/ML services reducing startup barriers.
- Web Platforms:Browser-based access enabling cross-device continuity without app store distribution friction. Medicaid expansion states show elevated reimbursement rates for web-delivered telehealth mental health services, creating public payer access points.
- Telehealth Services:Clinician-supervised synchronous and asynchronous care delivery.
- Community Programs:Nonprofit and government-funded access initiatives.
Mobile platforms dominate user acquisition today; telehealth services show steepest expansion trajectory.
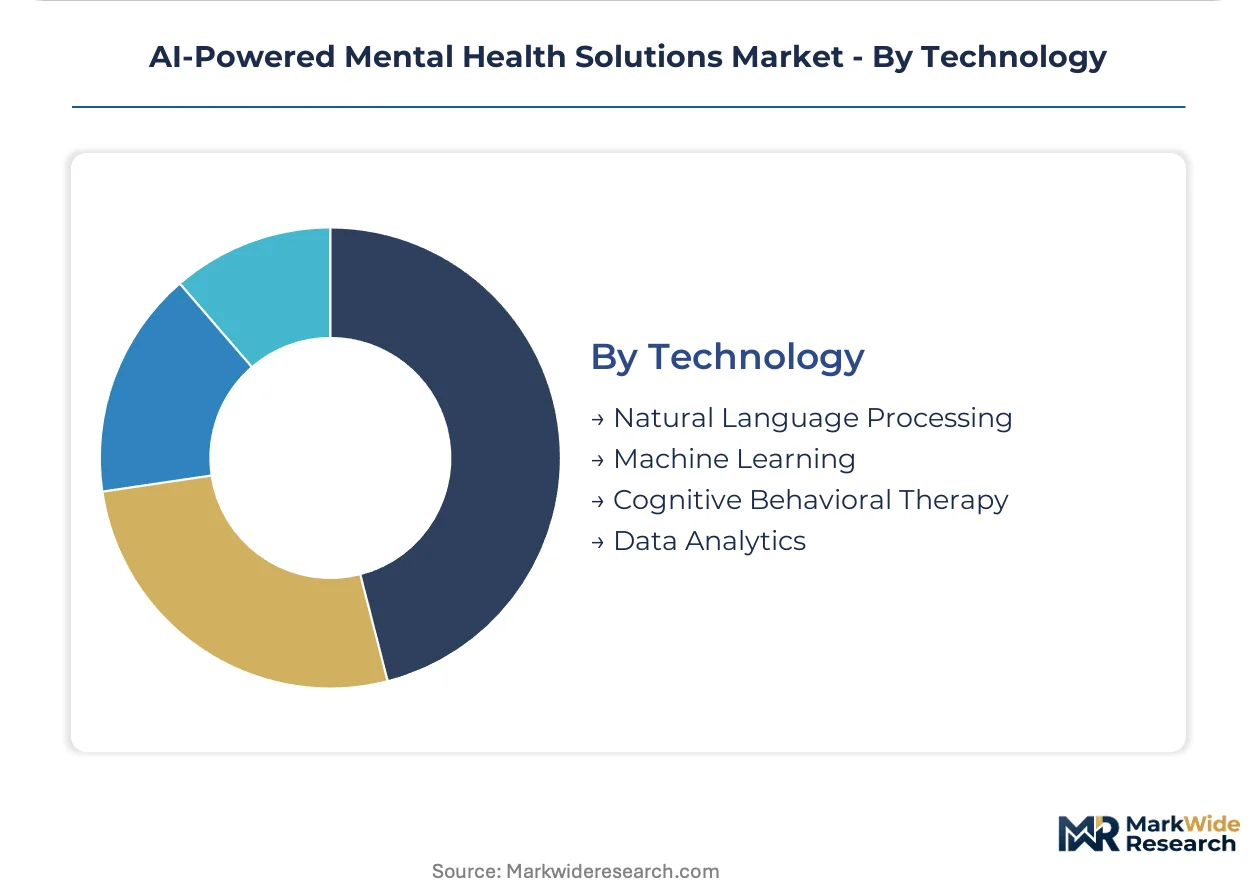
Technology:
Technology segmentation separates infrastructure-heavy model training operations from clinical protocol libraries and analytical capabilities.
- Natural Language Processing:Transformer-based architectures enabling real-time therapeutic dialogue generation. Fine-tuned large language models trained on cognitive behavioral therapy protocols are converging with biometric feedback loops at Kaiser Permanente and Mayo Clinic pilot programs.
- Machine Learning:Predictive algorithms for symptom severity triage and risk stratification. FDA de novo clearance requirements mandate controlled trial validation that filters out undercapitalized developers before scale.
- Cognitive Behavioral Therapy:Structured intervention protocols encoded as algorithmic decision trees.
- Data Analytics:Population-level outcome measurement and algorithmic bias audit capabilities.
Natural language processing commands investment intensity today; machine learning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychiatrists and clinical psychologists cluster in the United States, Germany, the United Kingdom, Japan, and Australia, anchoring regional development capacity for AI therapeutic platforms. These talent concentrations determine where algorithm validation trials and regulatory submissions originate.
United States
Employer-sponsored mental health benefits now routinely include AI-powered platforms as standard employee assistance program components. The FDA's software-as-a-medical-device framework realigns compliance requirements, forcing developers to validate clinical efficacy through controlled trials. Boston and San Francisco host the densest concentrations of digital therapeutic startups pursuing prescription digital therapeutic status.
Germany
Statutory health insurance funds have begun reimbursing digital health applications under the DiGA fast-track pathway, creating accessible public payer channels. The BfArM maintains a dedicated digital health assessment division that evaluates clinical evidence packages. Berlin anchors the startup ecosystem, while Munich concentrates established medical device manufacturers expanding into algorithmic therapies.
United Kingdom
The NHS Digital Technology Assessment Criteria framework streamlines procurement for AI mental health tools within the national health system. MHRA guidance on software as a medical device clarifies regulatory boundaries for cognitive behavioral therapy applications. London's King's College and Oxford University clusters supply psychiatric oversight for product development teams.
Japan
PMDA has established a consultation framework for AI-based medical devices, including mental health monitoring applications. Corporate wellness programs at major manufacturers like Toyota and Sony incorporate digital mental health platforms into occupational health benefits. Tokyo's Shibuya district hosts the domestic startup concentration, with Osaka providing clinical trial infrastructure through university hospital networks.
Australia
The TGA's software-based medical device guidance creates predicate pathways for AI therapeutic platforms entering the market. Medicare reimbursement for telehealth mental health services expanded during recent years, embedding digital delivery into standard care. Melbourne's Parkville biomedical precinct and Sydney's Randwick health and innovation district concentrate development and validation activities.
AI-Powered Mental Health Solutions Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across prescription digital therapeutic, employer benefit, and direct-to-consumer channels. The market structure shows moderate consolidation around platforms with FDA de novo clearance or equivalent regulatory validation, while wellness-category entrants fragment across undifferentiated app stores. Three archetypes dominate: clinical validation-first developers pursuing payer reimbursement, employer-channel specialists scaling through benefits consultants, and consumer-brand extenders leveraging existing user bases. M&A activity concentrates on biometric-therapy convergence capabilities, while strategic partnerships with electronic health record vendors determine enterprise penetration.
Within the clinical validation tier, Woebot Health and Cognoa occupy positions exemplifying the prescription digital therapeutic pathway. Woebot Health leverages its regulatory status to anchor reimbursement conversations with payers, representing the FDA-cleared archetype. Among employer-channel specialists, Lyra Health, Inc sits within the Fortune 500 direct contracting segment, while Headspace Health exemplifies the consumer-brand extension strategy into enterprise benefits. These three companies represent distinct competitive vectors: regulatory-first, channel-first, and brand-first positioning.
| Leading Market Players |
|---|
| Woebot Health |
| Wysa Ltd |
| Lyra Health, Inc |
| Talkspace |
| Cognoa |
| Spring Health |
| Headspace Health |
| Quartet Health |
| Koa Health |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 benefits administrators concentrate procurement authority for AI mental health platforms, driving a subscription-based SaaS pricing model with tiered access levels tied to employee population scale and clinical validation status. This buyer concentration rewards platforms with FDA prescription digital therapeutic clearance through premium positioning, while wellness-category entrants compete on price in undifferentiated app store environments.
Pricing Analysis
Bundled enterprise subscriptions encompassing biometric monitoring, clinician oversight, and EHR integration command substantial premiums over unbundled chatbot-only wellness tools. Three-tier pricing structure across prescription-grade, clinical-adjacent, and wellness tiers separates FDA-cleared platforms from employer-sponsored programs from direct-to-consumer apps. Pricing pressure stems from cloud infrastructure commoditization as AWS and Azure compete for healthcare AI/ML workloads. Self-insured employers show lowest price sensitivity due to claims cost reduction mandates, while individual consumers churn rapidly on subscription costs.
Supply Chain Analysis
Reverse-logistics flows for wearable mental health devices remain underdeveloped, with most manufacturers lacking refurbishment programs for optical heart rate sensors and galvanic skin response components. Component supply concentrates in China, Taiwan, and South Korea for biometric sensors, while cloud infrastructure rests on hyperscaler data centers in the United States, Ireland, and Singapore. Supply chain risk centers on single-source vulnerability for specialized physiological sensors. Distribution runs through employer benefits consultants and EHR vendor marketplaces rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA clearance costs in the United States and DiGA fast-track pathway efficiency in Germany, where statutory health insurance reimbursement accelerates revenue recognition without comparable clinical trial investment.
For Market Incumbents: Anticipate generative AI commoditization of therapeutic dialogue by deepening integration with Epic and Cerner EHR systems. Secure exclusive data-sharing agreements with Kaiser Permanente and Mayo Clinic pilot programs to train proprietary models on clinically validated outcomes. FDA enforcement discretion uncertainty threatens predicate device pathways; maintain dual-track regulatory strategies with CE marking under MDR as fallback. For New Entrants and Emerging Players: Begin with Medicaid expansion states where telehealth reimbursement rates exceed national averages and credentialing requirements remain less fragmented than interstate commercial licensing. Target university and K-12 educational institutions as white-space segments with dedicated mental health budgets and limited incumbent penetration. Pursue go-to-market partnerships with specialized benefits consultants Mercer and Willis Towers Watson rather than direct enterprise sales. For Investors and Strategic Acquirers: Electronic health record vendors are the most active acquirer in this space, seeking AI mental health capabilities to embed in clinician workflows. Five-to-ten-year viability hinges on FDA prescription digital therapeutic status as the dominant competitive moat. Monitor FDA de novo clearance timeline announcements as inflection indicators for platform valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Prescription digital therapeutic status unlocks Medicare and commercial payer reimbursement pathways. |
| CE Marking Pathway | European notified body clearance under MDR enables German DiGA fast-track access to statutory insurance funds. |
| Hospital System Partnership | Epic and Cerner interoperability embeds AI tools directly in clinician diagnostic workflows. |
| Biometric-Therapy Integration | Wearable hardware-software bundling commands premium pricing unavailable to pure software competitors. |
| Reimbursement Strategy | Employer-sponsored benefit channel bypasses traditional healthcare procurement friction entirely. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and benefits consultant contract tracking — were reconciled to construct market estimates. Primary interviews with FDA regulatory affairs leads, digital therapeutic product managers, hospital biomedical engineers, and employer benefits administrators informed validation assumptions. Secondary sources encompassed FDA 510(k) and de novo clearance databases, CMS Medicare telehealth reimbursement data, German BfArM DiGA listings, and NHS Digital procurement records. Bottom-up platform revenue aggregation and top-down employer benefit spend allocation were cross-referenced for triangulation.
Historical revenue trajectories were cross-referenced against panel input from benefits consultants and health system technology officers. Segmentation modeling tracked product type, end user, delivery mode, and technology architecture dimensions across the projection horizon. CAGRs were derived from employer adoption curve analysis and regulatory clearance velocity assumptions. Forecast inputs included FDA review timeline distributions, Medicaid expansion state policy variations, and biometric sensor component cost curves.
Several conditions sit outside the modeled scope, including hypothetical FDA enforcement discretion reversals, state-level telehealth licensing board harmonization, and breakthrough therapeutic modality approvals. Forecasts reflect assumptions about employer benefit mandate continuity and cloud infrastructure cost trajectories. Practitioners should monitor FDA de novo backlog announcements, German DiGA reimbursement rate revisions, and hyperscaler healthcare AI/ML service pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Agoraphobia Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market