
 Waterproof Orthotics Market | 2026-2036
Waterproof Orthotics Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Orthotics Market Analytics
Ethylene vinyl acetate is hardening its position as the dominant midsole material in waterproof orthotics, displacing conventional open-cell foams that degrade under sustained moisture exposure. Aetrex Worldwide leverages its 3D scanning infrastructure to capture custom-fit demand across retail podiatry channels. Superfeet Worldwide anchors its competitive stance with a proprietary closed-cell foam formulation that maintains structural integrity in wet environments. Ottobock competes through its rehabilitation-focused distribution network, sustaining premium positioning in post-surgical applications.
Waterproof orthotics are engineered medical devices constructed from hydrophobic polymers, sealed composites, or laminated barrier materials that prevent moisture ingress while maintaining biomechanical correction and pressure redistribution. These devices typically incorporate closed-cell foam densities between 40-80 Shore A, sealed thermoplastic shells, or vapor-permeable membrane laminates to achieve IPX4-equivalent splash resistance for active-use scenarios. Custom orthotics command the highest margin pools due to clinical consultation requirements and individualized manufacturing workflows, while pre-fabricated orthotics extend volume reach through direct-to-consumer and retail pharmacy channels. Sports rehabilitation applications are experiencing accelerated uptake as athletic trainers integrate moisture-managed foot orthoses into injury prevention protocols.
The FDA regulates waterproof orthotics under Class I or II medical device classifications depending on therapeutic claims, while ISO 13485 quality management standards govern manufacturing consistency for international distribution. The EU Medical Device Regulation requires notified body involvement for orthotics incorporating antimicrobial or pressure-offloading claims, extending certification timelines for European market access. Stakeholders must monitor evolving reimbursement codes for preventive diabetic foot care, as payor coverage decisions will determine whether waterproof orthotics remain cash-pay devices or transition into reimbursable durable medical equipment categories.
Market Dynamics
Podiatry clinics are consolidating orthotic dispensing authority, shifting volume from independent retailers toward clinically integrated supply chains that prioritize moisture-resistant biomechanical correction over commodity insoles.
Growth Catalysts
- FDA Class I Exemptions:Streamlined 510(k) clearance pathways for basic waterproof orthotic insoles accelerate manufacturer entry into direct-to-consumer channels.
- Active-Aging Demographics:United States consumers aged 55-75 seek moisture-managed foot support for sustained athletic participation, expanding addressable demand beyond diabetic populations.
- Closed-Cell Foam Chemistry:Hydrophobic polymer formulations achieving IPX4 splash resistance enable orthotic use in swimming, sailing, and outdoor labor environments previously excluded from the category.
Market Restraints
- Ethylene Vinyl Acetate Price Volatility:Petrochemical feedstock fluctuations compress margins for midsole manufacturers locked into long-term distributor contracts.
- EU MDR Certification Timelines:Notified body involvement for antimicrobial or pressure-offloading claims extends European market access by 12-18 months versus legacy Medical Device Directive pathways.
- Prefabricated Insole Substitution:Mass-market moisture-wicking insoles at retail pharmacy price points capture price-sensitive consumers before clinical consultation.
Strategic Opportunities
- Diabetic Foot Care Reimbursement:Shifting payor coverage decisions in the United States may reclassify waterproof orthotics from cash-pay devices to reimbursable durable medical equipment.
- 3D Scanning Integration:Retail podiatry channels adopting digital foot capture technology collapse custom orthotic production cycles from weeks to days.
- Sports Rehabilitation Protocols:Athletic trainers in collegiate and professional settings integrate moisture-managed foot orthoses into injury prevention programming.
Industry Challenges
- ISO 13485 Compliance Burden:Small manufacturers face capital intensity upgrading quality management systems for international distribution.
- Clinical-Prescription Workflow Integration:Electronic health record compatibility gaps delay orthotic ordering within podiatry practice management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Orthotics Market |
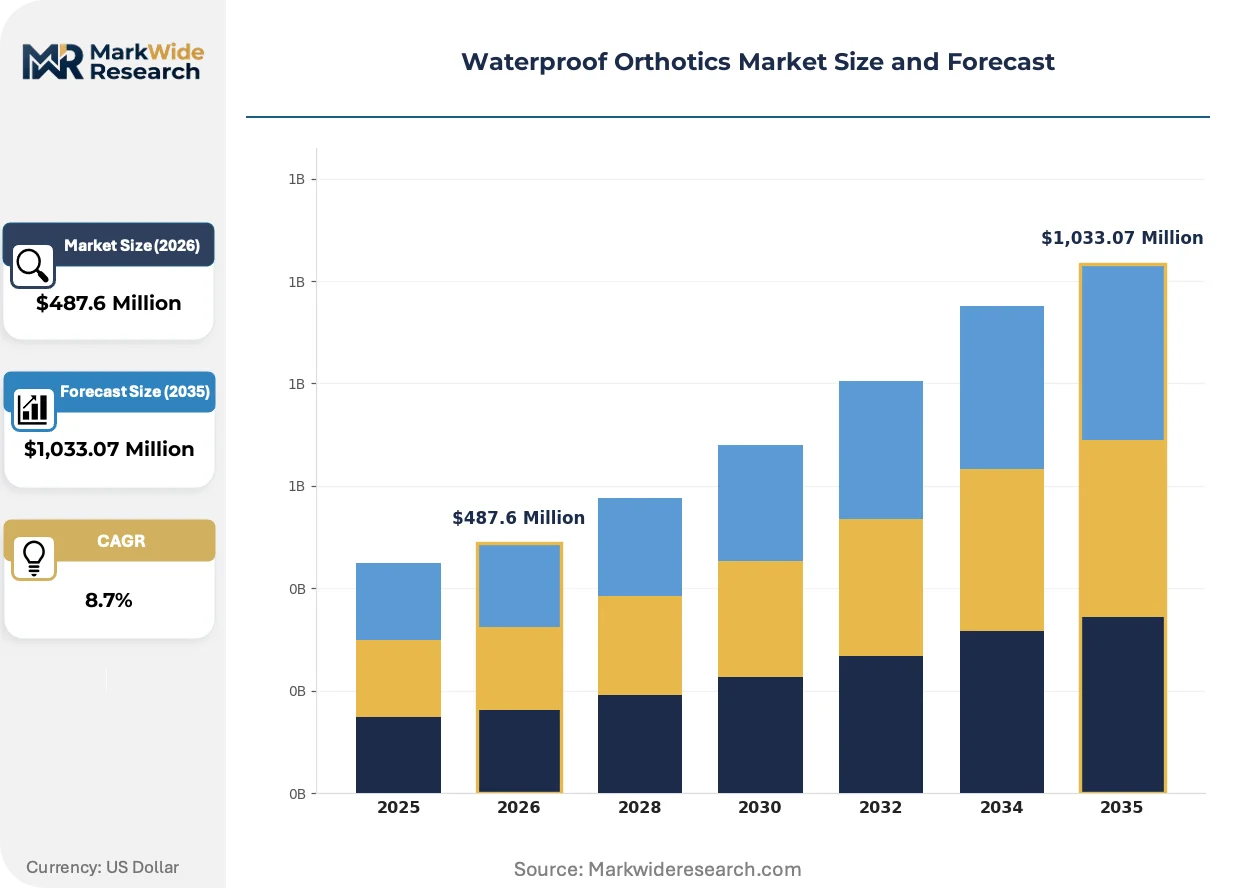
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Orthotics, Pre-fabricated Orthotics, Insoles, Shoe Inserts Material: Thermoplastic, Ethylene Vinyl Acetate, Composite Materials, Rubber End User: Athletes, Seniors, Patients with Diabetes, General Population Application: Sports Rehabilitation, Post-Surgery Recovery, Pain Management, Daily Support |
| Companies Covered | Aetrex Worldwide, Foot Levelers, Ottobock, Hanger Clinic, Superfeet Worldwide, Dr. Scholl's Wellness Company, Spenco Medical Corporation, Turbomed Orthotics, Foot Science International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Orthotics Market Evolving Landscape
Digital manufacturing workflows and regulatory harmonization efforts are compressing product development cycles while expanding the clinical settings where waterproof orthotics are prescribed and dispensed.
Closed-cell thermoplastic polyurethane shells are decentralizing production geography by enabling distributed 3D printing networks to manufacture prescription-grade orthotics at point-of-care locations. Podiatry clinics in the United States and Germany deploy in-house printing capacity to fulfill custom orders within 48 hours. This manufacturing dispersion reduces shipping costs and appointment scheduling friction for follow-up fittings.
REACH restrictions on persistent organic pollutants in polymer formulations are forcing reformulation of legacy adhesive bonding agents used in laminated waterproof barriers. Manufacturers serving European markets accelerate validation of bio-based epoxy alternatives. The transition extends certification timelines for suppliers with limited analytical chemistry capabilities.
Direct-to-consumer channels capture growing share of prefabricated waterproof orthotic volume as telehealth podiatry consultations legitimize remote fitting assessments. Subscription-based replacement programs for athletic users displace single-transaction retail purchases. This behavioral shift concentrates most visibly among marathon runners and triathletes in coastal United States metropolitan areas.
Waterproof Orthotics Market Segmentation
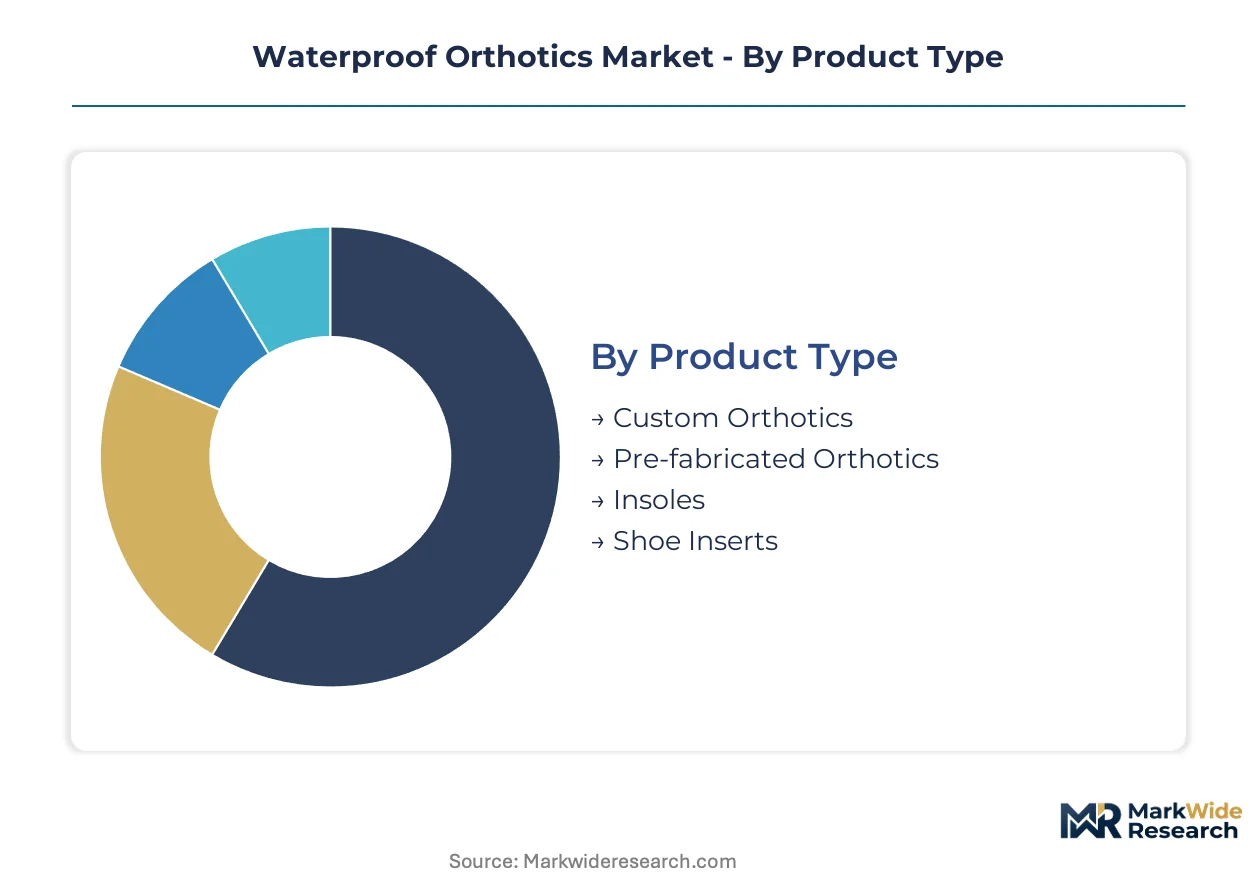
Waterproof orthotics segmentation reflects divergent manufacturing economics between clinical prescription workflows and retail self-selection channels. Material chemistry and end-user biomechanical requirements determine margin architecture across each product tier.
Product Type:
Thermoplastic shell molding and closed-cell foam density specifications differentiate clinical-grade devices from commodity alternatives.
- Custom Orthotics:Individualized devices manufactured from patient-specific foot scans using medical-grade thermoplastic shells with 40-80 Shore A closed-cell foam overlays. Demand concentrates in United States podiatry clinics serving diabetic populations seeking reimbursable durable medical equipment coverage under evolving Medicare guidelines.
- Pre-fabricated Orthotics:Standardized arch supports with hydrophobic polymer construction achieving IPX4 splash resistance without individualized fitting. Volume is accelerating in direct-to-consumer channels as telehealth podiatry consultations legitimize remote sizing assessments for athletic users in coastal metropolitan markets.
- Insoles:Thin-profile moisture-barrier inserts designed for retrofit into existing footwear. Retail pharmacy distribution dominates.
- Shoe Inserts:Basic cushioning layers with limited biomechanical correction capability. Price-sensitive substitution pressure from mass-market moisture-wicking alternatives constrains premium positioning.
Mature deployment sits with Custom Orthotics in clinical settings. Newer deployment is concentrated in Pre-fabricated Orthotics through digital commerce channels.
Material:
Cost tier alignment separates medical-device-grade specifications from consumer-accessible formulations.
- Thermoplastic:Rigid shell materials including polypropylene and carbon fiber composites providing structural correction with sealed vapor-barrier lamination. United States and German podiatry clinics deploying in-house 3D printing networks favor thermoplastic for 48-hour custom production cycles.
- Ethylene Vinyl Acetate:Closed-cell foam formulations displacing conventional open-cell alternatives through superior moisture resistance. Petrochemical feedstock volatility compresses manufacturer margins locked into long-term distributor contracts.
- Composite Materials:Multi-layer laminates combining structural polymers with hydrophobic membranes. REACH restrictions on persistent organic pollutants force adhesive reformulation for European market access.
- Rubber:Natural and synthetic elastomers for outsole traction and impact absorption. Limited clinical adoption due to biomechanical rigidity constraints.
Thermoplastic and Ethylene Vinyl Acetate capture equivalent revenue concentration. Composite Materials are climbing the fastest as antimicrobial and pressure-offloading claims trigger EU MDR notified body involvement.
End User:
Application intensity and reimbursement eligibility structure addressable margin pools.
- Patients with Diabetes:High-risk foot ulcer prevention drives prescription volume through Medicare and private payor channels. Clinical consultation requirements sustain premium pricing.
- Athletes:Marathon runners and triathletes in United States coastal cities adopt subscription-based replacement programs for moisture-managed injury prevention.
- Seniors:Active-aging consumers aged 55-75 seek sustained athletic participation support. Retail self-selection dominates over clinical pathways.
- General Population:Occupational and daily-use moisture protection. Price compression from prefabricated substitutes limits expansion.
Patients with Diabetes anchor reimbursement-dependent revenue. Athletes represent the steepest expansion trajectory through direct-to-consumer subscription models.
Application:
Clinical setting determines regulatory classification and distribution channel economics.
- Sports Rehabilitation:Athletic trainers in collegiate and professional settings integrate moisture-managed foot orthoses into injury prevention protocols. Ottobock and Superfeet compete through specialized distribution networks.
- Post-Surgery Recovery:Post-operative immobilization and gradual weight-bearing transition. Rehabilitation-focused suppliers sustain premium positioning through hospital and clinic relationships.
- Pain Management:Chronic biomechanical correction for plantar fasciitis and metatarsalgia. Podiatry clinic dispensing authority is consolidating volume from independent retailers.
- Daily Support:Routine moisture-resistant comfort for occupational and recreational use. Retail pharmacy and e-commerce channels capture volume.
Post-Surgery Recovery commands the highest per-unit margins through clinical integration. Sports Rehabilitation is gaining share fastest as athletic training protocols formalize moisture management requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers aged 55-75 generate the strongest demand concentration for moisture-managed foot support, with Medicare reimbursement debates determining whether waterproof orthotics transition from cash-pay devices into durable medical equipment categories.
United States
Active-aging demographics in coastal metropolitan areas drive subscription-based replacement programs for athletic users. FDA Class I exemptions streamline 510(k) clearance pathways for basic waterproof orthotic insoles. Boston and San Diego clusters concentrate digital manufacturing workflows that collapse custom orthotic production cycles from weeks to days.
Germany
Podiatry clinics deploy in-house 3D printing networks to fulfill custom orders within 48 hours, reducing shipping costs and appointment friction. EU MDR notified body involvement extends certification timelines for antimicrobial or pressure-offloading claims by 12-18 months. Bavaria and North Rhine-Westphalia host distributed manufacturing nodes serving prescription-grade orthotic demand.
United Kingdom
NHS procurement frameworks evaluate waterproof orthotics for diabetic foot ulcer prevention programs, with coverage decisions pending clinical evidence reviews. MHRA alignment with EU MDR requirements governs market access post-Brexit. London and Southeast England concentrate telehealth podiatry consultations legitimizing remote fitting assessments.
Japan
Aging population demographics expand addressable demand beyond diabetic populations into sustained athletic participation support. PMDA medical device classifications determine reimbursement eligibility for moisture-managed foot orthoses. Tokyo and Osaka metropolitan areas integrate closed-cell thermoplastic polyurethane shells into sports rehabilitation protocols.
Australia
Private health insurance coverage for custom orthotics sustains premium pricing in clinical channels. TGA medical device regulations require conformity assessment procedures for waterproof barrier claims. Melbourne and Sydney clusters concentrate athletic trainer adoption of moisture-managed foot orthoses into injury prevention programming.
Waterproof Orthotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with clinical prescription workflows favoring vertically integrated suppliers while direct-to-consumer channels elevate marketing-intensive brands. The vendor base organizes into three tiers: rehabilitation-focused distributors sustaining premium hospital relationships, retail podiatry channels capturing custom-fit demand through digital infrastructure, and mass-market insole producers competing on pharmacy shelf presence. Dominant competitive moves include 3D scanning integration collapsing production cycles and REACH-driven adhesive reformulation for European market retention.
Among United States-based specialists, Aetrex Worldwide and Superfeet Worldwide exemplify divergent archetypes within the moisture-resistant segment. Aetrex occupies a position anchored in 3D scanning infrastructure deployed across retail podiatry channels. Superfeet represents the proprietary materials tier through closed-cell foam formulations maintaining structural integrity in wet environments. Ottobock, a German GmbH, anchors the rehabilitation-focused distribution network archetype serving post-surgical applications.
| Leading Market Players |
|---|
| Aetrex Worldwide |
| Foot Levelers |
| Ottobock |
| Hanger Clinic |
| Superfeet Worldwide |
| Dr. Scholl's Wellness Company |
| Spenco Medical Corporation |
| Turbomed Orthotics |
| Foot Science International |
| Others |
Value Network & Pricing Analysis
Polymer chemist concentrations in Germany's Rhine-Ruhr industrial corridor and Michigan's automotive belt anchor waterproof orthotics manufacturing, with labor-cost differentials between these clusters driving pricing-tier spreads across custom prescription and retail prefabricated segments.
Pricing Analysis
Volume-mass prefabricated insoles trade at thin margins through retail pharmacy channels, while custom prescription devices capture premium spreads through clinical consultation bundling. Price differentiation hinges on FDA classification tier and ISO 13485 certification status, with Class II antimicrobial claims commanding structural premiums. Cost compression in ethylene vinyl acetate feedstocks is intensifying because petrochemical volatility squeezes midsole manufacturers locked into distributor contracts. Cash-pay seniors in United States coastal markets show highest price sensitivity, whereas diabetic patients seeking Medicare reimbursement demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with closed-cell foam suppliers concentrated in Germany, China, and the United States, where hydrophobic polymer formulations require specialized extrusion capabilities. Raw material dependencies include ethylene vinyl acetate resins, thermoplastic polyurethane pellets, and REACH-compliant epoxy adhesives. Supply chain risk centers on ECHA regulatory restrictions forcing adhesive reformulation for European market access. Distribution runs through podiatry clinic networks for prescription-grade devices and direct-to-consumer platforms for athletic subscription programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof orthotics function as a cost-of-compliance market where EU MDR notified body requirements and FDA Class I exemption pathways create regulatory moats favoring incumbent manufacturers with established quality management infrastructure.
For Market Incumbents: Deploy 3D scanning infrastructure to collapse custom orthotic production cycles from weeks to days, defending against telehealth-enabled remote fitting platforms. Consolidate distributor relationships in United States podiatry channels to preempt volume capture by direct-to-consumer entrants. Backward integration into closed-cell foam formulation secures supply continuity amid petrochemical volatility.
For New Entrants and Emerging Players: Athletic trainers in collegiate sports programs represent an underserved buyer archetype with formalizing moisture-management procurement protocols. Subscription-based replacement programs for marathon runners and triathletes offer the most penetrable entry vector. Partner with telehealth podiatry platforms to legitimize remote sizing assessments without clinical infrastructure investment.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers possessing in-house 3D printing networks given Medicare reimbursement expansion catalysts. Long-term viability favors targets with ISO 13485 certification and established notified body relationships across multiple geographies. Watch for diabetic foot care coverage decisions in United States payor frameworks as inflection indicators for durable medical equipment reclassification.
| Strategic Initiative | Industry Significance |
|---|---|
| 3D Printing Network Deployment | Point-of-care manufacturing collapses custom orthotic fulfillment timelines from weeks to 48 hours. |
| EU MDR Certification Pathway | Notified body involvement for antimicrobial claims extends market access timelines by 12-18 months. |
| Telehealth Podiatry Partnership | Remote fitting assessments legitimize direct-to-consumer volume capture in athletic segments. |
| REACH-Compliant Adhesive Reformulation | Bio-based epoxy alternatives preserve European market access amid persistent organic pollutant restrictions. |
| Subscription Replacement Program | Recurring revenue models displace single-transaction retail purchases among coastal United States athletes. |
Research Methodology
FDA 510(k) filings, ISO 13485 registration databases, and CMS Medicare reimbursement codes formed the secondary backbone, cross-referenced with primary interviews involving podiatrists, biomedical engineers, GPO contracts managers, and athletic training directors. Bottom-up and top-down triangulation validated patient volume estimates against manufacturer shipment data and clinical dispensing records.
Bottom-up modeling anchored volume projections in procedure rates and prescription patterns across diabetic, athletic, and active-aging populations, while top-down analysis tested aggregate market sizing against ethylene vinyl acetate consumption trends and thermoplastic shell production capacity. CAGRs were derived from segmented growth rate blending across custom prescription, prefabricated retail, and direct-to-consumer channels, with inputs including Medicare coverage expansion scenarios and REACH regulatory compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement policy shifts and petrochemical feedstock volatility. Forecasts reflect documented assumptions regarding regulatory timelines and payor behavior, with EU MDR certification delays and FDA classification updates representing primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Light Therapy Market
Medical Devices
Lactation Massager Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Global Medical Footwear Market