
 GCC Telemedicine Market | 2026-2036
GCC Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Telemedicine Market Intelligence
Platform licensing revenue is fragmenting across specialized service modules as vendors compete for recurring revenue streams. Teladoc Health sustains broad geographic coverage through its multi-country deployment model. Siemens Healthineers anchors high-acuity telemedicine workflows with integrated diagnostic imaging capabilities. Philips differentiates through remote patient monitoring hardware paired with clinical decision support software.
Telemedicine encompasses real-time audio-visual consultation, asynchronous store-and-forward diagnostics, and remote physiological monitoring delivered through encrypted digital infrastructure with latency thresholds below 150 milliseconds for synchronous encounters. Software solutions capture the dominant margin pool as health systems prioritize interoperability with existing electronic health records. Virtual consultations lead service type adoption while remote patient monitoring grows fastest among post-acute care providers managing diabetes and cardiovascular conditions. Mobile applications dominate delivery mode preference among younger patient demographics, though integrated systems retain higher per-deployment value.
The Saudi Food and Drug Authority regulates telehealth platform safety classifications while the UAE's Ministry of Health and Prevention governs practitioner licensing for cross-border consultations. Both frameworks mandate data residency requirements that shape cloud architecture decisions for platform operators. Stakeholders must monitor evolving reimbursement codes from national health insurance schemes as these determine provider willingness to scale virtual care beyond pilot programs.
Market Dynamics
Platform licensing revenue is fragmenting across specialized service modules as vendors compete for recurring revenue streams. Government hospitals across Saudi Arabia and the UAE are expanding virtual consultation programs for chronic disease management, while data residency requirements from SFDA and MOHAP reshape cloud architecture decisions.
Growth Catalysts
- MOHAP Telehealth Licensing Framework:The UAE's streamlined approval process accelerates platform market entry and reduces time-to-revenue for virtual care providers.
- Chronic Disease Management Demand:Government hospitals in Riyadh and Jeddah corridors prioritize diabetes and cardiovascular remote monitoring programs.
- Health System Digitization:Saudi Arabia's hospital networks invest in interoperability with existing electronic health records to support virtual consultation scale.
Market Restraints
- Data Residency Compliance Costs:SFDA and MOHAP mandates require localized cloud infrastructure, increasing capital expenditure for platform operators.
- Cross-Border Licensing Friction:Practitioner credentialing restrictions limit specialist access for patients in secondary GCC cities.
- Reimbursement Code Uncertainty:National health insurance schemes maintain limited procedure codes for asynchronous diagnostics, constraining provider willingness to scale beyond pilots.
Strategic Opportunities
- Post-Acute Care Monitoring:Remote physiological monitoring for diabetes and cardiovascular conditions represents underpenetrated white space among UAE home health agencies.
- Mobile-First Delivery Models:Younger patient demographics in Jeddah and Dubai favor smartphone-based consultation interfaces over desktop systems.
- Integrated Diagnostic Imaging:Convergence of telemedicine platforms with radiology workflows creates high-acuity service tier differentiation.
Industry Challenges
- Latency Infrastructure Requirements:Synchronous encounters demand encrypted digital infrastructure below 150 milliseconds, requiring edge computing investments in secondary GCC markets.
- Interoperability Integration Complexity:Health systems struggle to align virtual consultation data flows with legacy electronic health record architectures.
- Specialist Practitioner Recruitment:Virtual care platforms face scarcity of licensed clinicians willing to practice across state and emirate jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Telemedicine Market |
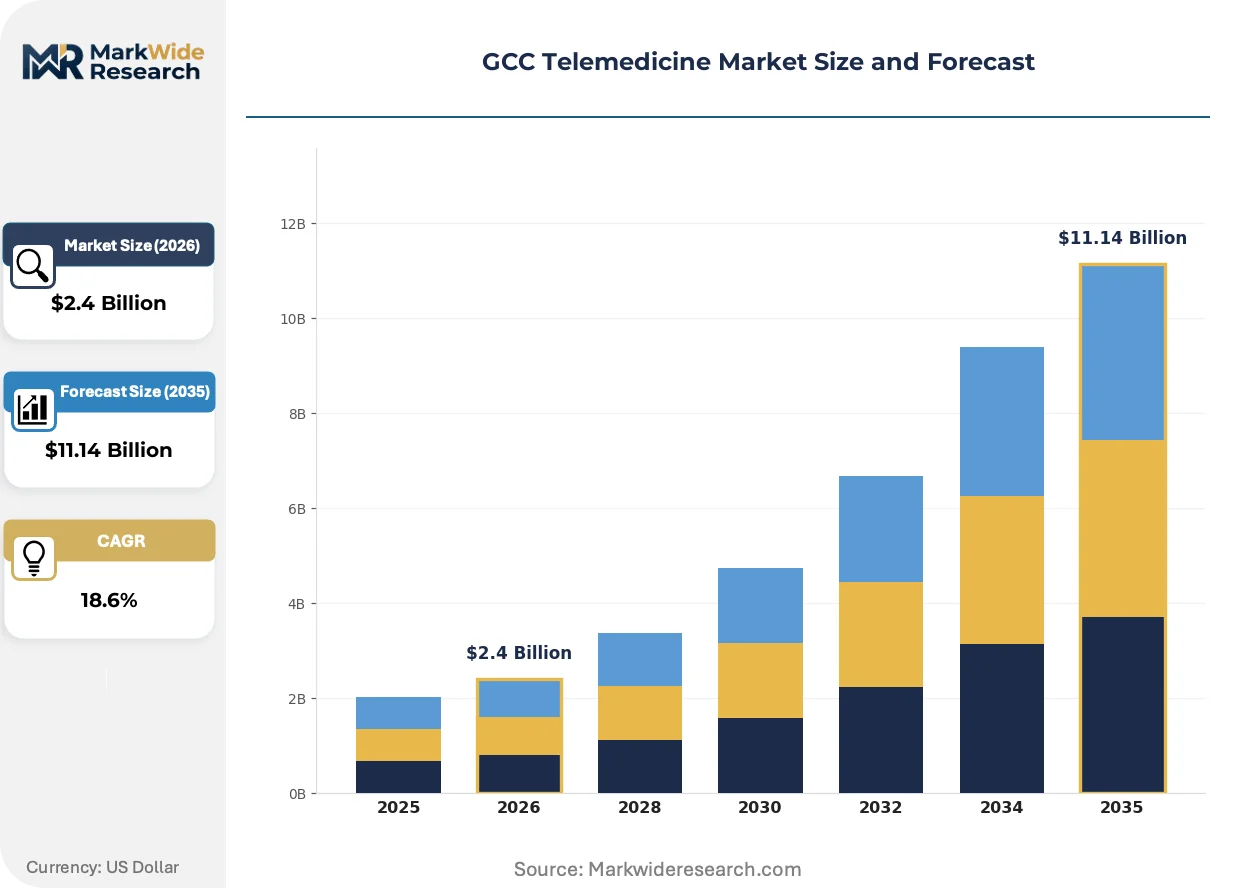
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.14 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Telehealth Platforms, Remote Monitoring Devices Service Type: Virtual Consultations, Remote Patient Monitoring, Disease Management, Mobile Health Services End User: Hospitals, Clinics, Home Care Providers, Insurers Delivery Mode: Web-based, Mobile Applications, Integrated Systems, Cloud Services |
| Companies Covered | Siemens Healthineers AG, Teladoc Health, Inc., Koninklijke Philips N.V., Cisco Systems Inc., American Well, Medtronic, Epic Systems Corporation, Oracle, GE Healthcare, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Telemedicine Market Strategic Shifts & Innovations
Telemedicine delivery models are compressing toward modular, API-first architectures that decouple consultation interfaces from backend clinical systems. Three forces are reshaping competitive positioning: artificial intelligence integration, regulatory harmonization efforts, and shifting patient channel preferences.
Artificial intelligence diagnostic triage is collapsing the traditional primary care referral pathway. Machine learning algorithms now route patient symptoms to appropriate specialty consultations without human intake screening. Saudi government hospitals deploy these systems for initial chronic disease assessments. The technology compresses time-to-specialist-access from days to minutes while reducing clinical staff overhead.
SFDA and MOHAP are converging on mutual recognition frameworks for telehealth platform safety classifications. This regulatory alignment reduces duplicate compliance burdens for vendors operating across Saudi Arabia and the UAE. Cross-border practitioner licensing reciprocity agreements are following platform harmonization. The standardization enables regional scale without jurisdiction-specific infrastructure replication.
Patient channel preferences are rotating sharply toward mobile applications over integrated health system portals. Younger demographics in Riyadh and Dubai bypass hospital-branded interfaces for standalone telemedicine apps with consumer-grade user experience. Health systems respond by white-labeling third-party platforms rather than building proprietary solutions. This channel disintermediation fragments patient data ownership and complicates longitudinal care coordination.
GCC Telemedicine Market Segmentation
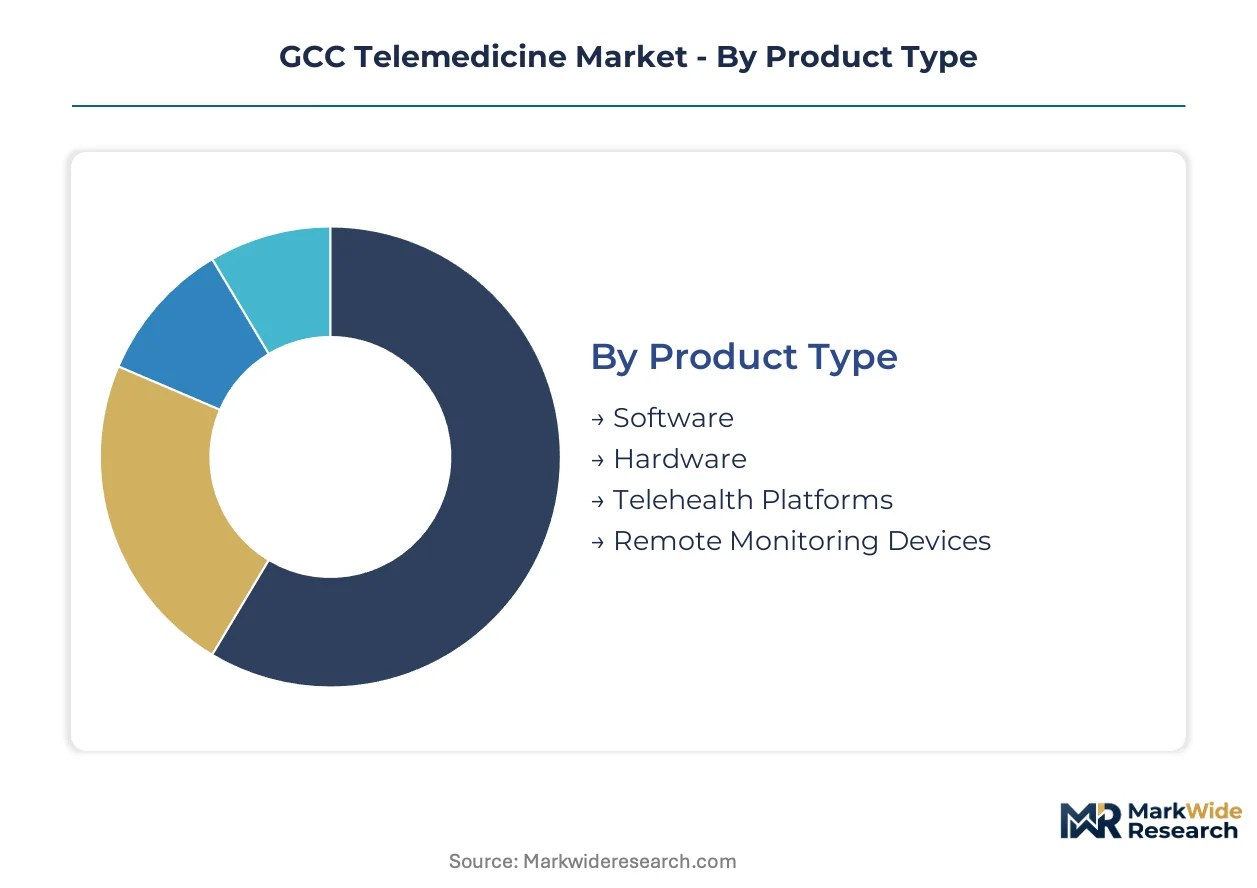
Telemedicine market segmentation reveals distinct margin profiles and service intensity requirements across product architectures. Vendor strategies diverge sharply between high-touch hardware deployments and scalable software licensing models.
Product Type:
After-sales service intensity varies dramatically across physical and digital product categories, with hardware requiring field maintenance while software demands continuous platform updates.
- Software:Cloud-native consultation interfaces and clinical workflow engines generate recurring license revenue through subscription tiers. Saudi government hospitals prioritize interoperability modules that integrate with existing electronic health records in Riyadh and Jeddah corridors, where health system digitization has advanced furthest.
- Hardware:Encrypted video endpoints, diagnostic peripherals, and edge computing nodes for latency-sensitive synchronous encounters carry higher upfront capital expenditure. UAE Ministry of Health and Prevention procurement favors hardware bundles with localized data residency compliance, reflecting MOHAP's cloud architecture mandates.
- Telehealth Platforms:Integrated consultation and billing systems with API-first architectures.
- Remote Monitoring Devices:Wearable physiological sensors and home-based diagnostic equipment for chronic disease tracking.
Software holds the largest share; momentum sits with remote monitoring devices as post-acute care providers expand diabetes and cardiovascular programs.
Service Type:
Cost tier differentiation separates high-volume virtual consultations from premium-priced continuous monitoring contracts with outcome-linked pricing structures.
- Virtual Consultations:Real-time audio-visual encounters between patients and licensed practitioners delivered through encrypted infrastructure. Government hospitals across Saudi Arabia and the UAE scale these programs for chronic disease management, though reimbursement code uncertainty from national health insurance schemes constrains provider willingness beyond pilot phases.
- Remote Patient Monitoring:Asynchronous physiological data collection with automated alert thresholds for clinical intervention. UAE home health agencies represent underpenetrated demand for diabetes and cardiovascular monitoring, with younger patient demographics in Dubai favoring smartphone-integrated sensor systems.
- Disease Management:Structured care protocols for specific chronic conditions with care coordinator oversight.
- Mobile Health Services:Consumer-facing wellness applications and symptom triage tools operating outside formal clinical workflows.
Virtual consultations dominate current deployment value; remote patient monitoring is expanding most quickly among post-acute care networks.
End User:
Customer type determines procurement sophistication, with hospitals demanding enterprise-grade integration while home care providers prioritize standalone usability.
- Hospitals:Multi-department health systems requiring EHR interoperability and specialist network access. Saudi Arabia's hospital networks in Riyadh and Jeddah corridors drive demand for high-acuity telemedicine workflows with integrated diagnostic imaging capabilities.
- Clinics:Smaller outpatient facilities seeking cost-effective virtual consultation platforms without extensive IT infrastructure.
- Home Care Providers:Post-acute and long-term care agencies deploying remote physiological monitoring for patient cohorts outside institutional settings.
- Insurers:Payers developing virtual-first benefit designs and reimbursement frameworks for asynchronous diagnostics.
Hospitals command the greatest per-deployment value; home care providers are gaining share fastest as chronic disease management shifts beyond institutional walls.
Delivery Mode:
Volume concentration tilts toward mobile channels among younger demographics, while integrated systems retain higher per-deployment value through health system contracts.
- Mobile Applications:Smartphone-native consultation interfaces with consumer-grade user experience. Younger patient demographics in Jeddah and Dubai bypass hospital-branded portals for standalone telemedicine apps, forcing health systems toward white-label third-party platforms.
- Web-based:Browser-accessible consultation portals requiring no local software installation.
- Integrated Systems:Embedded modules within existing hospital information systems with single-sign-on authentication. These deployments capture higher per-contract value through enterprise licensing, though implementation cycles stretch longer due to interoperability integration complexity with legacy electronic health record architectures.
- Cloud Services:Infrastructure-as-a-service models for platform operators navigating SFDA and MOHAP data residency requirements.
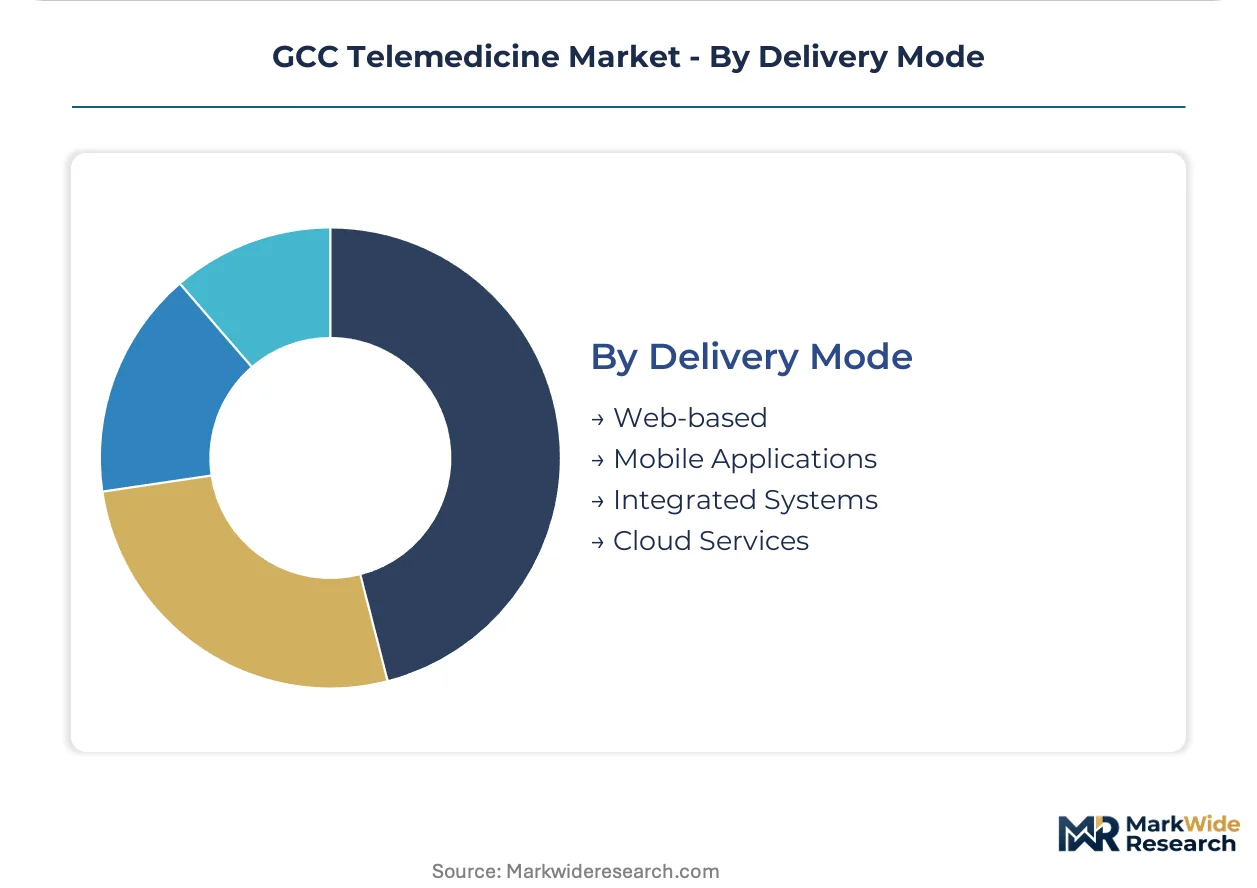
Integrated systems hold the largest share; mobile applications are climbing the fastest as patient channel preferences rotate toward smartphone-first encounters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across GCC member states, with government hospital procurement in Saudi Arabia and the UAE demanding enterprise-grade interoperability while smaller Gulf markets prioritize cost-effective standalone platforms. Buyers in secondary cities face steeper total cost of ownership due to localized cloud infrastructure requirements from national regulators.
Saudi Arabia
Government hospital networks in Riyadh and Jeddah corridors drive the region's most sophisticated telemedicine deployments, with chronic disease management programs for diabetes and cardiovascular conditions expanding fastest. The Saudi Food and Drug Authority mandates data residency requirements that reshape cloud architecture decisions for platform operators. Eastern Province health clusters are digitizing specialist referral pathways through integrated diagnostic imaging workflows.
United Arab Emirates
MOHAP's streamlined telehealth licensing framework accelerates platform market entry and reduces vendor time-to-revenue compared to neighboring jurisdictions. Dubai's younger patient demographics favor smartphone-native consultation interfaces over hospital-branded portals, forcing health systems toward white-label third-party solutions. Abu Dhabi's health authorities are procuring remote patient monitoring bundles for post-acute diabetes management.
Kuwait
Public sector health digitization lags Saudi Arabia and the UAE by approximately three to four years, creating demand for proven platform configurations already deployed elsewhere in the Gulf. The country's national health insurance scheme maintains limited reimbursement codes for asynchronous diagnostics, constraining provider willingness to scale beyond pilot programs. Kuwait City medical centers are testing virtual consultation modules for specialist access in secondary cities.
Qatar
Hamad Medical Corporation's centralized procurement structure favors integrated health system deployments over fragmented point solutions. The Supreme Council of Health governs practitioner licensing for cross-border consultations, with reciprocity agreements following Saudi-UAE regulatory harmonization efforts. Doha's medical city cluster is deploying high-acuity telemedicine workflows with sub-150 millisecond latency requirements for synchronous surgical consultations.
Bahrain
Smaller market scale limits dedicated platform infrastructure investment, with health systems relying on Saudi and UAE-based cloud services subject to data residency compliance. The National Health Regulatory Authority is adapting licensing frameworks from larger GCC neighbors to accelerate virtual care adoption. Manama's private hospital groups are piloting remote monitoring programs for cardiovascular patients discharged to home care settings.
GCC Telemedicine Market Key Industry Players
Capability concentration sits with integrated diagnostic imaging specialists; scale advantage sits with multi-country platform deployers. The vendor base organizes into three tiers: global health technology conglomerates with hardware-software bundles, pure-play telemedicine platforms with API-first architectures, and regional system integrators with localized compliance expertise. Dominant competitive moves include strategic partnerships with government hospital networks and portfolio diversification into remote patient monitoring hardware.
Among the integrated diagnostic imaging tier, Siemens Healthineers AG exemplifies high-acuity workflow specialization, while Teladoc Health, Inc. occupies a position as the archetypal multi-country deployment platform. Koninklijke Philips N.V. represents the converged hardware-software model pairing remote monitoring devices with clinical decision support systems. These three anchors illustrate the strategic divergence between imaging-centric, platform-centric, and monitoring-centric competitive positions.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Teladoc Health, Inc. |
| Koninklijke Philips N.V. |
| Cisco Systems Inc. |
| American Well |
| Medtronic |
| Epic Systems Corporation |
| Oracle |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Jebel Ali port-to-Riyadh freight corridors carry encrypted video endpoints and edge computing nodes through bonded logistics zones, with transport cost differentials between integrated health system contracts and standalone platform deployments shaping margin structures across Saudi Arabia and the UAE. These logistics economics concentrate pricing power with vendors who bundle hardware-software solutions under multi-year enterprise agreements, while unbundled software licensing faces downward pressure from API-first competitors.
Pricing Analysis
Long-term enterprise offtake agreements dominate procurement for Saudi government hospital networks, with subscription tiers scaling by user seat volume and interoperability module depth. Price differentiation separates premium deployments with sub-150 millisecond latency guarantees and localized data residency compliance from standard cloud-native offerings. Cost compression in the hardware tier is intensifying because UAE Ministry of Health and Prevention procurement favors bundled diagnostic imaging peripherals. Government hospitals demonstrate lowest price sensitivity; private clinics in secondary GCC cities exhibit highest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for encrypted video endpoints and wearable physiological sensors. Manufacturing concentrates in China for consumer-grade sensors, Taiwan for semiconductor components, and Germany for diagnostic imaging hardware. Raw material dependencies include lithium-ion cells for portable devices, medical-grade optical sensors, and edge computing processors. Distribution runs through regional system integrators with SFDA and MOHAP compliance certification, bypassing direct vendor-to-hospital relationships in most deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription renewals and remote patient monitoring service contracts are expanding faster than hardware deployment value, creating attractive service-attach economics for vendors who shift from capital sale models to recurring revenue architectures.
For Market Incumbents: Entrench platform positions through exclusive interoperability certifications with Saudi government hospital networks in Riyadh and Jeddah corridors. Deepen backward integration into edge computing infrastructure to capture margin pools currently flowing to third-party cloud operators. API-first competitors threaten incumbents who fail to modularize legacy architectures. For New Entrants and Emerging Players: Establish a beachhead in UAE home health agency remote monitoring programs, where post-acute diabetes and cardiovascular management remains underpenetrated. Target younger patient demographics in Dubai and Jeddah with smartphone-native consultation interfaces that bypass hospital-branded portals. Pursue white-label partnerships with health systems seeking consumer-grade user experience without proprietary development costs. For Investors and Strategic Acquirers: SFDA-MOHAP mutual recognition frameworks for telehealth platform safety classifications reshape the acquisition landscape by reducing duplicate compliance burdens for regional scale. Five-to-ten year viability favors vendors with demonstrated interoperability integration and localized data residency infrastructure. Acquisition target archetype: regional system integrators with MOHAP certification and existing government hospital relationships. Signal to watch: reimbursement code expansion from national health insurance schemes.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | SFDA and MOHAP mandates require EHR integration modules that lock out uncertified competitors from Saudi government hospital procurement. |
| Remote Patient Monitoring Hardware Development | Post-acute diabetes and cardiovascular programs in UAE home health agencies drive demand for wearable sensor systems with clinical decision support. |
| Mobile-First Platform Architecture | Younger demographics in Dubai and Jeddah bypass desktop portals, forcing health systems toward smartphone-native white-label solutions. |
| Localized Cloud Infrastructure Deployment | Data residency requirements from Saudi and UAE regulators necessitate edge computing investments in secondary GCC markets. |
| AI Diagnostic Triage Integration | Machine learning algorithms routing patient symptoms to specialty consultations compress time-to-access from days to minutes in Saudi government hospitals. |
Research Approach
Initial hypotheses were tested against primary input from hospital CIOs, telemedicine platform product managers, biomedical engineers, and GPO contracts managers, and refined through secondary validation against SFDA regulatory filings, MOHAP licensing databases, hospital procurement records, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated with top-down health system digitization budget analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across software-hardware-platform product types, virtual consultation-remote monitoring service tiers, hospital-clinic-home care end users, and mobile-web-integrated delivery modes. CAGRs derived from installed base growth rates and per-deployment value trajectories. Forecast inputs included health system EHR interoperability maturity indices and national health insurance reimbursement code expansion timelines.
Sensitivities concentrate around MOHAP reimbursement policy shifts and SFDA data residency enforcement intensity. Forecasts reflect assumptions about chronic disease management program scale and cross-border practitioner licensing reciprocity progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telepathology Service Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Tele-Care Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Europe Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Telemedicine Cart Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
India Telehealth Services Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Telemedicine Diagnostic Services Market