
 Dynamic Spinal Tethering Systems Market | 2026-2036
Dynamic Spinal Tethering Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Spinal Tethering Systems Market Foresight
Polyetheretherketone is repositioning titanium alloy in tether anchor and rod construction, reducing implant stiffness and improving load-sharing with the growing spine. Medtronic leverages decades of deformity correction heritage to sustain clinical trial infrastructure for pediatric indications. NuVasive anchors its tether portfolio within a broader minimally invasive spine platform. Zimmer Biomet Holdings competes through orthopedic scale and hospital contracting breadth.
Dynamic spinal tethering systems are semi-rigid implants that apply corrective tension across vertebral segments while permitting controlled growth and motion, typically constructed from braided polymer cords, titanium or PEEK anchors, and adjustable fixation mechanisms manufactured via precision machining and laser welding. The devices serve primarily to modulate spinal curvature progression in skeletally immature patients without the rigidity of fusion constructs. Innovative tethers and adjustable rods capture disproportionate engineering investment as manufacturers pursue incremental tension adjustability and biocompatibility improvements. Pediatric surgery applications lead procedure volume, though adult deformity correction represents a faster-growing addressable population as longevity of native motion segments gains clinical priority. Hospitals dominate purchasing volume, while orthopedic clinics and surgery centers expand site-of-care options for qualifying outpatient procedures.
FDA 510(k) clearance requirements and EU MDR technical documentation standards shape product development timelines and evidence generation burdens for tether system manufacturers. ISO 14155 clinical investigation standards and ASTM F2077 mechanical testing protocols further define acceptable performance thresholds for implant durability and biocompatibility. Stakeholders must monitor evolving reimbursement determinations from CMS and Germany's G-BA regarding motion-preserving versus fusion-based interventions, as coverage decisions will determine accessible patient volumes and commercialization feasibility across key markets.
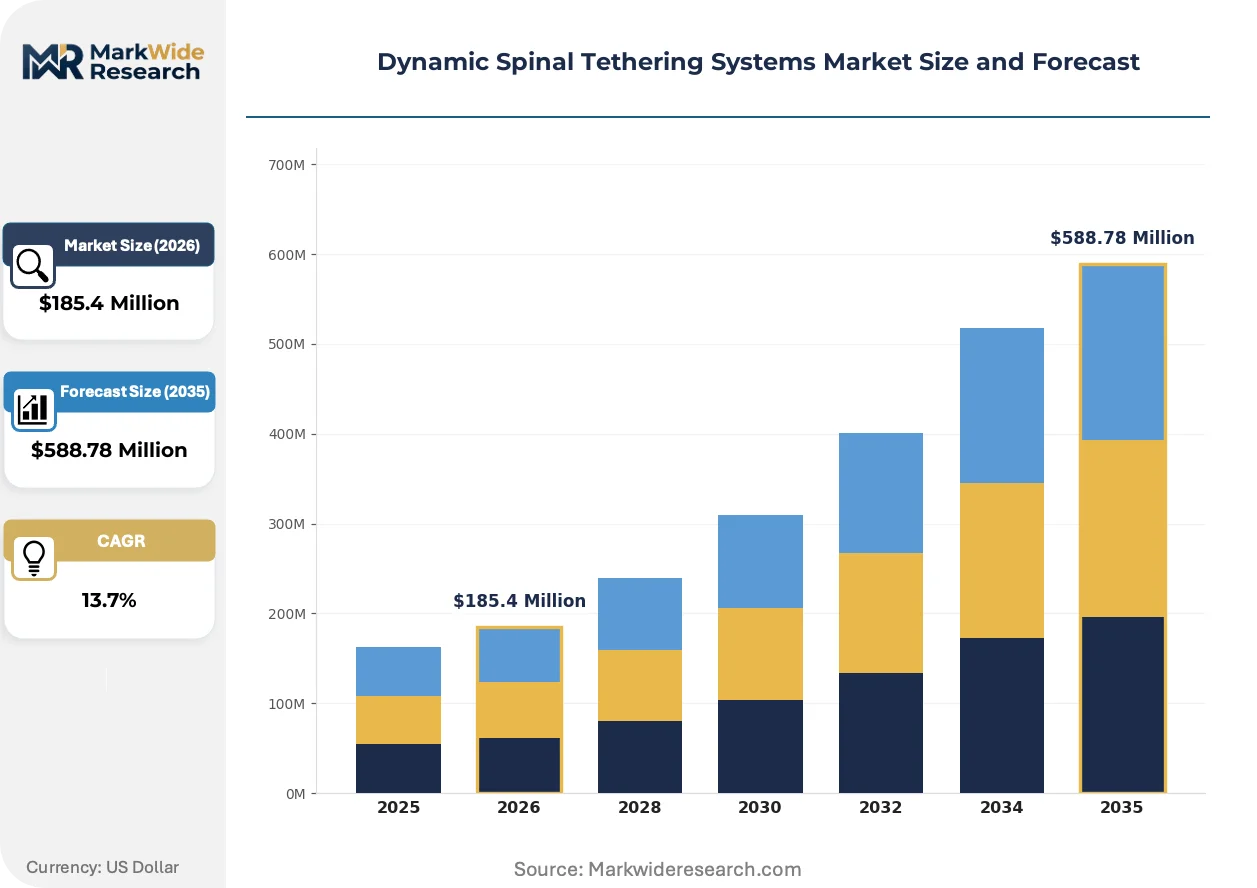
Market Dynamics
FDA premarket notification pathways and EU MDR conformity assessments are tightening evidence requirements for motion-preserving implants, forcing manufacturers to front-load clinical trial investment before commercial traction. This regulatory compression is reshaping capital allocation across pediatric orthopedic device portfolios.
Growth Catalysts
- PEEK Material Transition:Polyetheretherketone is repositioning titanium alloy in tether anchor construction, reducing implant stiffness and improving load-sharing with growing pediatric spines.
- Pediatric Program Expansion:Major hospital systems in the United States, Germany, and Japan are expanding dedicated tethering programs for early-onset scoliosis, creating institutional demand anchors.
- CMS Reimbursement Stabilization:Coverage determinations from the Centers for Medicare and Medicaid Services for non-fusion deformity correction have stabilized, reducing payer uncertainty for qualifying procedures.
Market Restraints
- Clinical Evidence Burden:FDA 510(k) clearance requirements and EU MDR technical documentation standards are extending product development timelines by 18-36 months for novel tether constructs.
- Specialized Surgical Skill Scarcity:Motion-preserving deformity correction demands fellowship-trained pediatric orthopedic surgeons, creating a bottleneck in qualified procedure volume.
- Fusion Procedure Substitution:Traditional spinal fusion remains the clinical default for severe curvature cases, limiting tethering penetration in high-acuity patient segments.
Strategic Opportunities
- Adult Deformity Expansion:Longevity of native motion segments is gaining priority among aging populations, expanding addressable volume beyond pediatric indications.
- Outpatient Site Migration:Ambulatory surgery centers are capturing qualifying tethering procedures, creating channel diversification beyond hospital purchasing dominance.
- Adjustable Tension Mechanisms:Incremental engineering investment in tension adjustability is converging with braided polymer cord advances, enabling post-implantation curvature modulation.
Industry Challenges
- ISO 14155 Compliance Complexity:Clinical investigation standards for implant durability and biocompatibility require specialized CRO partnerships, inflating trial management overhead.
- ASTM F2077 Testing Capacity:Mechanical testing protocol compliance demands specialized equipment and extended validation cycles, compressing R&D throughput.
- Reimbursement Geography Fragmentation:Germany's G-BA coverage determinations for motion-preserving versus fusion-based interventions remain unsettled, creating commercial feasibility uncertainty across European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Spinal Tethering Systems Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $588.78 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innovative Tethers, Adjustable Rods, Surgical Tools, Monitoring Devices Application: Pediatric Surgery, Adult Surgery, Rehabilitation, Pain Management End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Surgery Centers Delivery Mode: Invasive Procedures, Outpatient Procedures, Telehealth Services, Remote Monitoring |
| Companies Covered | Medtronic, NuVasive, Zimmer Biomet Holdings, Globus Medical, Stryker Corporation, Alphatec Spine, Johnson & Johnson, Orthofix Medical, INTUITIVEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Spinal Tethering Systems Market Shifts & Advancements
Engineering investment is concentrating on incremental tension adjustability and biocompatibility improvements, while regulatory evidence generation is becoming the primary competitive differentiator. These forces are compressing development timelines and elevating clinical trial infrastructure as a strategic asset.
Braided polymer cord systems are converging with precision-machined titanium anchors to create semi-rigid constructs that permit controlled vertebral growth. Pediatric surgery departments in major academic medical centers are adopting these hybrid configurations at accelerating pace. This convergence is enabling motion preservation while maintaining corrective tension across multiple growth cycles.
EU MDR conformity assessment procedures are extending technical documentation requirements for implantable devices, forcing manufacturers to expand post-market surveillance infrastructure. The industrial consequence is elevated compliance cost structures that favor established players with legacy quality management systems. Pediatric indication tether systems face the steepest documentation burden due to long-term growth-tracking requirements.
Hospital value analysis committees are consolidating vendor selection authority, compressing the number of approved tether suppliers per system. Orthopedic clinics and surgery centers are capturing qualifying outpatient procedures, fragmenting the traditional hospital purchasing monopoly. This channel rotation is most visible in United States markets where site-of-care flexibility has expanded under revised CMS reimbursement frameworks.
Dynamic Spinal Tethering Systems Market Segmentation
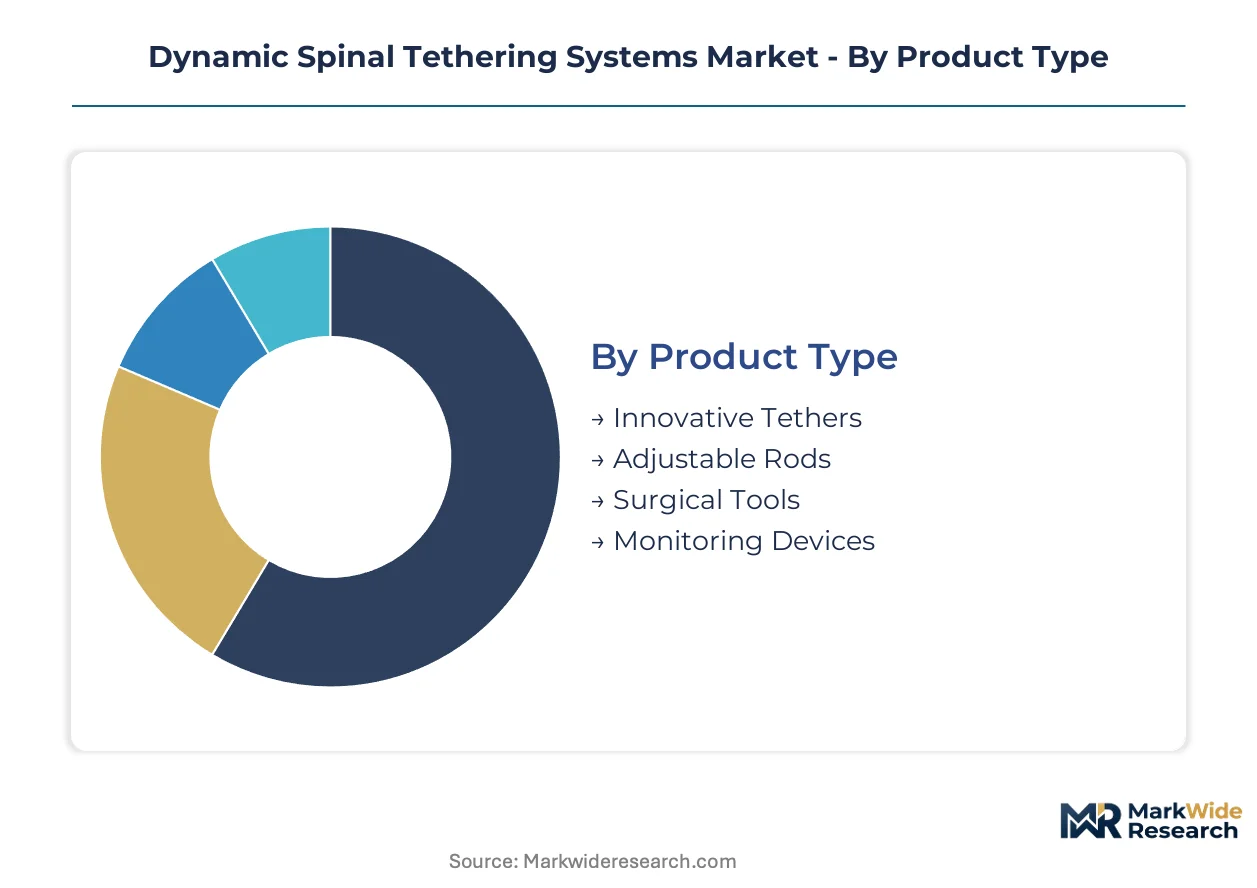
Segmentation in dynamic spinal tethering systems reveals distinct procurement patterns across surgical settings and patient populations. Material selection, reimbursement pathways, and site-of-care economics drive divergent commercial strategies for each category.
Product Type:
Procurement committees prioritize implant performance characteristics against total episode cost when selecting tether system components.
- Innovative Tethers:Braided polymer cord constructs with PEEK or titanium anchors enable controlled tension modulation across vertebral segments. Demand concentrates in pediatric orthopedic departments at academic medical centers in the United States and Germany, where motion-preserving correction protocols have achieved institutional acceptance.
- Adjustable Rods:Semi-rigid titanium or cobalt-chrome constructs permit post-implantation length modification to accommodate spinal growth. Pediatric surgery applications in Japan's university hospitals are expanding fastest, driven by longitudinal growth-tracking requirements for early-onset scoliosis patients.
- Surgical Tools:Specialized insertion instruments and tensioning devices for tether deployment.
- Monitoring Devices:Post-operative curvature tracking and tension assessment systems.
Volume sits with Innovative Tethers; growth tilts toward Adjustable Rods.
Application:
Clinical indication determines regulatory pathway complexity and evidence generation burden for tether system manufacturers.
- Pediatric Surgery:Early-onset scoliosis correction in skeletally immature patients represents the established clinical foundation for tethering technology. United States children's hospitals and German pediatric orthopedic centers account for dominant procedure volumes, supported by stabilized CMS and G-BA reimbursement frameworks.
- Adult Surgery:Motion-preserving deformity correction in degenerative scoliosis and adjacent segment disease is gaining priority among aging populations. Japanese spine surgeons are adopting adult indications most aggressively, responding to demographic pressure for longevity of native motion segments.
- Rehabilitation:Post-surgical recovery protocols and bracing adjuncts.
- Pain Management:Conservative tethering applications for mechanical back pain modulation.
Procedure concentration remains in Pediatric Surgery; Adult Surgery is climbing the fastest.
End User:
Site-of-care economics and capital equipment requirements fragment purchasing authority across delivery settings.
- Hospitals:Academic medical centers and children's hospitals dominate tethering procedure volume through dedicated pediatric orthopedic programs. United States hospital systems in Boston, Philadelphia, and Cincinnati anchor institutional demand through fellowship-trained surgeon density and comprehensive growth-tracking infrastructure.
- Orthopedic Clinics:Specialized spine practices are capturing diagnostic and post-operative monitoring phases. German orthopedic clinic networks in Munich and Hamburg are expanding tether patient management capabilities, supported by ambulatory reimbursement parity with hospital settings.
- Rehabilitation Centers:Post-operative physical therapy and curvature monitoring services.
- Surgery Centers:Ambulatory facilities are qualifying select adult tethering procedures for outpatient migration.
Revenue concentrates with Hospitals; channel expansion favors Surgery Centers.
Delivery Mode:
Reimbursement coding and clinical risk stratification determine feasible settings for tether system deployment.
- Invasive Procedures:Open or minimally invasive surgical implantation of tether constructs under general anesthesia. United States hospital inpatient and outpatient surgical departments perform the majority of these procedures, with CMS reimbursement codes distinguishing fusion from non-fusion deformity correction.
- Outpatient Procedures:Same-day surgical discharge for qualifying low-acuity tethering cases. Japanese surgery centers in Tokyo and Osaka are pioneering outpatient adult tether protocols, leveraging refined patient selection criteria and rapid recovery pathways.
- Telehealth Services:Remote consultation and post-operative follow-up for tether patients.
- Remote Monitoring:Digital curvature tracking and patient-reported outcome collection.
Procedure volume rests with Invasive Procedures; site migration is gaining share fastest in Outpatient Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems anchor procedure volume for dynamic spinal tethering systems, with academic medical centers in Boston, Philadelphia, and Cincinnati driving institutional adoption through fellowship-trained surgeon density and comprehensive growth-tracking infrastructure.
United States
FDA 510(k) clearance pathways and stabilized CMS reimbursement for non-fusion deformity correction support commercial feasibility. Major children's hospitals in Cincinnati and Philadelphia maintain dedicated pediatric orthopedic tethering programs. Hospital value analysis committees consolidate vendor selection authority, compressing approved supplier counts per system.
Germany
University hospitals in Munich and Hamburg expand tether patient management capabilities through ambulatory reimbursement parity with hospital settings. EU MDR conformity assessments tighten technical documentation requirements for implantable devices, elevating compliance cost structures. Pediatric orthopedic centers in Heidelberg and Berlin pioneer longitudinal growth-tracking protocols for early-onset scoliosis patients.
Japan
Demographic pressure for longevity of native motion segments accelerates adult deformity correction adoption. PMDA regulatory frameworks govern motion-preserving implant approvals with stringent post-market surveillance requirements. Spine surgeons in Tokyo and Osaka pioneer outpatient adult tether protocols through refined patient selection criteria and rapid recovery pathways.
United Kingdom
NHS specialized commissioning frameworks determine coverage for pediatric versus adult tethering indications, creating regional access variation. MHRA post-Brexit regulatory alignment with EU MDR technical standards extends product registration timelines. Academic medical centers in London and Birmingham anchor clinical trial infrastructure for novel tether constructs.
Switzerland
Swissmedic regulatory oversight maintains high evidence thresholds for pediatric implantable devices, favoring established manufacturers with legacy quality management systems. University hospitals in Zurich and Geneva concentrate motion-preserving deformity correction expertise. Private hospital groups in Basel and Lausanne expand elective adult tethering capacity for cross-border patient flows.
Dynamic Spinal Tethering Systems Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from fusion-based deformity correction into motion-preserving alternatives. The vendor base concentrates around diversified orthopedic conglomerates with established pediatric spine franchises, creating tiered competitive positioning between integrated platform owners and specialized tether innovators. Three strategic archetypes emerge: diversified spine conglomerates with deformity correction heritage, minimally invasive platform specialists, and emerging tether-focused innovators. M&A activity and clinical trial infrastructure expansion represent the dominant competitive moves as regulatory evidence requirements tighten.
Among diversified orthopedic conglomerates, Medtronic, NuVasive, and Zimmer Biomet Holdings occupy positions shaped by decades of deformity correction heritage and hospital contracting breadth. Medtronic exemplifies the clinical trial infrastructure archetype through sustained investment in pediatric indication evidence generation. NuVasive sits within the minimally invasive platform specialist tier, anchoring tether portfolios within broader spine surgery ecosystems. Zimmer Biomet Holdings represents the orthopedic scale archetype, leveraging hospital system contracting relationships across implant categories.
| Leading Market Players |
|---|
| Medtronic |
| NuVasive |
| Zimmer Biomet Holdings |
| Globus Medical |
| Stryker Corporation |
| Alphatec Spine |
| Johnson & Johnson |
| Orthofix Medical |
| INTUITIVEX |
| Others |
Supply & Pricing Matrix
PEEK polymer resin and precision-machined titanium feedstock flow from specialty chemical suppliers and aerospace-grade metal processors through contract manufacturers to hospital value analysis committees, with material certification tiers separating premium tether constructs from standard configurations.
Pricing Analysis
Volume concentrates in standard-tier tether systems while margin capture sits with premium PEEK-anchor constructs bearing FDA pediatric indication clearances. Price differentiation hinges on biocompatibility certification grade and longitudinal growth-tracking data packages bundled with implant systems. Pricing pressure stems from hospital value analysis committee consolidation compressing approved vendor lists per system. Pediatric orthopedic departments at academic medical centers exhibit lowest price sensitivity due to institutional protocol adherence, while ambulatory surgery centers negotiating direct purchase contracts show highest elasticity.
Supply Chain Analysis
Explant retrieval and component refurbishment programs for adjustable rod mechanisms are emerging as reverse-logistics capabilities among established manufacturers. Raw material sourcing draws from Germany and Switzerland for precision-machined titanium anchors, with PEEK polymer resin supply anchored in United States and United Kingdom specialty chemical production. Single-source vulnerability concentrates in laser-welding equipment for braided cord termination, creating chokepoint exposure. Distribution runs through orthopedic implant distributors holding consignment inventory at major hospital systems, with direct-to-hospital contracting gaining share among tier-one manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around clinical trial infrastructure as EU MDR documentation requirements and FDA pediatric evidence standards force capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Acquire specialized CRO partnerships holding ISO 14155 pediatric investigation experience to compress evidence generation timelines. Fortify hospital system contracting breadth through bundled spine platform offerings that tether systems to established fusion hardware relationships, neutralizing emerging entrants lacking GPO access. For New Entrants and Emerging Players: Begin with adult deformity correction indications in Japanese outpatient surgery centers, where PMDA regulatory frameworks and demographic pressure for motion preservation create penetrable white space. Pursue differentiated positioning through tension-adjustability engineering rather than head-to-head pediatric indication competition against entrenched trial infrastructure. For Investors and Strategic Acquirers: CMS coverage determination expansions for non-fusion deformity correction in adult populations is the leading indicator that addressable volume is shifting toward motion-preserving alternatives. Target acquisition candidates with proprietary braided polymer cord intellectual property and existing CE marking under EU MDR, as these assets command premium positioning across the analysis window. Monitor Germany's G-BA reimbursement determinations for motion-preserving versus fusion-based interventions as the signal for European commercial feasibility normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Clinical Trial Expansion | FDA 510(k) clearance for early-onset scoliosis indications secures institutional purchasing preference at children's hospitals. |
| PEEK Material Vertical Integration | In-house polymer compounding capability reduces anchor stiffness variability and insulates against specialty resin supply disruption. |
| EU MDR Technical Documentation Buildout | Post-market surveillance infrastructure investment elevates compliance cost structures that disadvantage emerging competitors. |
| Outpatient Surgery Center Partnership | Site-of-care migration capture in United States markets leverages revised CMS reimbursement frameworks for qualifying procedures. |
| Adjustable Tension Mechanism Patent Filing | Post-implantation curvature modulation capabilities differentiate constructs in Japanese adult deformity correction protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pediatric orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement determinations, and ASTM mechanical testing protocol records provided validation anchors. Bottom-up procedure volume estimates by indication and site-of-care combined with top-down implant manufacturer revenue triangulation.
Product type, application, end user, and delivery mode dimensions were modeled at country-level granularity across the projection horizon. CAGRs derived from segmented volume trajectories weighted by reimbursement pathway maturity and surgeon training pipeline expansion. Forecast inputs incorporated PMDA approval timelines for adult indications, Germany's G-BA coverage determination schedules, and pediatric orthopedic fellowship program graduation rates.
Underlying measurement precision varies by segment; pediatric surgery applications carry tighter precision than adult deformity correction given established procedure coding and reimbursement frameworks. Forecasts reflect assumptions regarding regulatory pathway stability and surgeon training pipeline expansion that could revise if EU MDR documentation requirements extend further or fellowship program capacity contracts. Practitioners should monitor CMS national coverage determination updates and G-BA benefit assessment rulings for early signals of addressable volume shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Phoropters Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
India Diabetes Devices Market