
 Australia Clear Aligner Market | 2026-2036
Australia Clear Aligner Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Clear Aligner Market Intelligence
Medical-grade polycarbonate certification is unwinding price resistance among Australian orthodontic patients seeking premium outcomes. Align Technology leverages its Invisalign scanner network to dominate chair-side digital workflows across Sydney and Melbourne practices. SmilePath Australia competes on direct-to-consumer accessibility, while Institut Straumann AG anchors its position through specialist orthodontist channel partnerships.
Clear aligners are removable orthodontic appliances fabricated from transparent thermoplastic materials, typically medical-grade polyurethane or polycarbonate, via CAD/CAM and 3D printing processes to sequentially reposition teeth through controlled force application. The product type dimension shows invisible aligners commanding the widest patient acceptance, while 3D printed aligners represent the fastest-growing fabrication method as dental laboratories adopt in-house additive manufacturing. Distribution channel dynamics reveal orthodontic practices capturing the highest-margin cases, whereas direct-to-consumer platforms are expanding volume through teledentistry-enabled remote monitoring.
TGA medical device regulations classify clear aligners as Class IIa products, mandating biocompatibility testing and clinical evidence standards that filter out lower-quality imports. Australian Dental Association guidelines on remote orthodontic supervision create compliance complexity for online platform operators. Stakeholders must monitor how TGA enforcement against unregistered direct-to-consumer aligner providers reshapes competitive access rules.
Market Dynamics
TGA enforcement against unregistered direct-to-consumer aligner providers is compressing competitive access rules and forcing channel consolidation toward orthodontic practice networks.
Growth Catalysts
- Medical-grade polycarbonate certification:Premium material validation is unwinding price resistance among Australian orthodontic patients seeking superior aesthetic outcomes and treatment predictability.
- CAD/CAM workflow integration:Sydney and Melbourne orthodontic practices are digitizing chair-side impressions and treatment planning, reducing turnaround times for aligner fabrication.
- Private dental clinic density in New South Wales:Concentrated specialist infrastructure in Sydney supports higher treatment uptake through proximity-driven patient access.
Market Restraints
- Biocompatibility testing mandates:TGA Class IIa medical device classification requires extensive clinical evidence that filters out lower-quality imports and raises compliance costs.
- Thermoplastic resin supply concentration:Medical-grade polyurethane feedstock depends on limited Asia-Pacific chemical suppliers, creating input cost volatility.
- Fixed appliance substitution persistence:Complex malocclusion cases still require traditional braces, capping clear aligner addressable volume in severe correction segments.
Strategic Opportunities
- Teledentistry-enabled remote monitoring:Direct-to-consumer platforms can expand geographic reach beyond metropolitan orthodontic practice clusters into regional Queensland and Western Australia.
- In-house additive manufacturing adoption:Dental laboratories are integrating 3D printing workflows to capture margin from chair-side digital scanning networks.
- Australian Dental Association guideline evolution:Potential relaxation of remote orthodontic supervision rules could unlock platform scalability for asynchronous treatment management.
Industry Challenges
- Orthodontist training bottlenecks:Limited Australian university programs in digital orthodontics constrain workforce expansion for CAD/CAM treatment planning.
- Compliance timeline compression:TGA medical device registration processes create extended market entry delays for novel aligner materials and fabrication methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Clear Aligner Market |
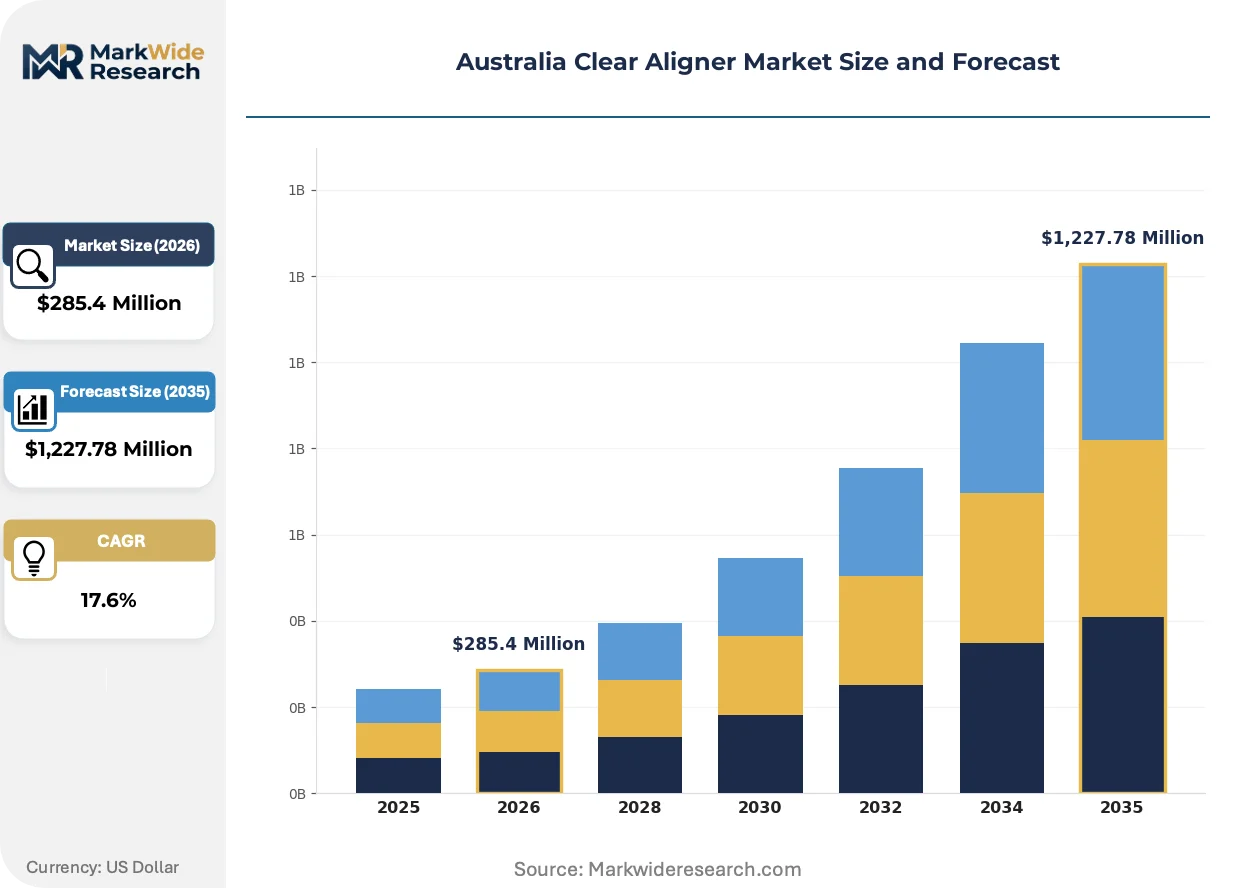
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,227.78 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invisible Aligners, 3D Printed Aligners, Customized Aligners, Standard Aligners Consumer Age Group: Teens, Young Adults, Adults, Seniors Distribution Channel: Direct-to-Consumer, Dental Clinics, Online Platforms, Orthodontic Practices Material Grade: Medical-Grade Polycarbonate, Thermoplastic Elastomer, Polyurethane, Others |
| Companies Covered | Align Technology, SmileDirectClub, Ormco, 3M, Dentsply Sirona, Institut Straumann AG, ClearCorrect, Angelalign Technology, SmilePath Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Clear Aligner Market Strategic Shifts & Innovations
Digital fabrication methods are fragmenting traditional laboratory outsourcing relationships, while regulatory tightening and patient channel preferences reshape how aligners reach end-users across Australian states.
Intraoral scanning hardware paired with cloud-based treatment planning software is fragmenting the conventional alginate impression workflow that dominated Australian orthodontic practices. Melbourne and Sydney clinics are deploying chair-side scanners to bypass external laboratory dependencies. This technology convergence compresses treatment initiation timelines and shifts margin capture toward practice-level digital infrastructure ownership.
TGA medical device regulations governing Class IIa clear aligner classification are tightening biocompatibility documentation requirements for market authorization. The regulator's enforcement posture is elevating quality benchmarks and accelerating exit of unregistered direct-to-consumer providers. Orthodontic practice networks are responding by emphasizing TGA-registered supply chains in patient communications to differentiate against online platform competitors.
Patient acquisition through teledentistry consultations is displacing traditional referral relationships between general dentists and orthodontic specialists. Direct-to-consumer platforms are capturing initial patient touchpoints through remote smile assessments, then routing complex cases to partner orthodontists. This channel disintermediation concentrates most visibly in Victoria and New South Wales, where metropolitan patient density supports platform unit economics.
Australia Clear Aligner Market Segmentation
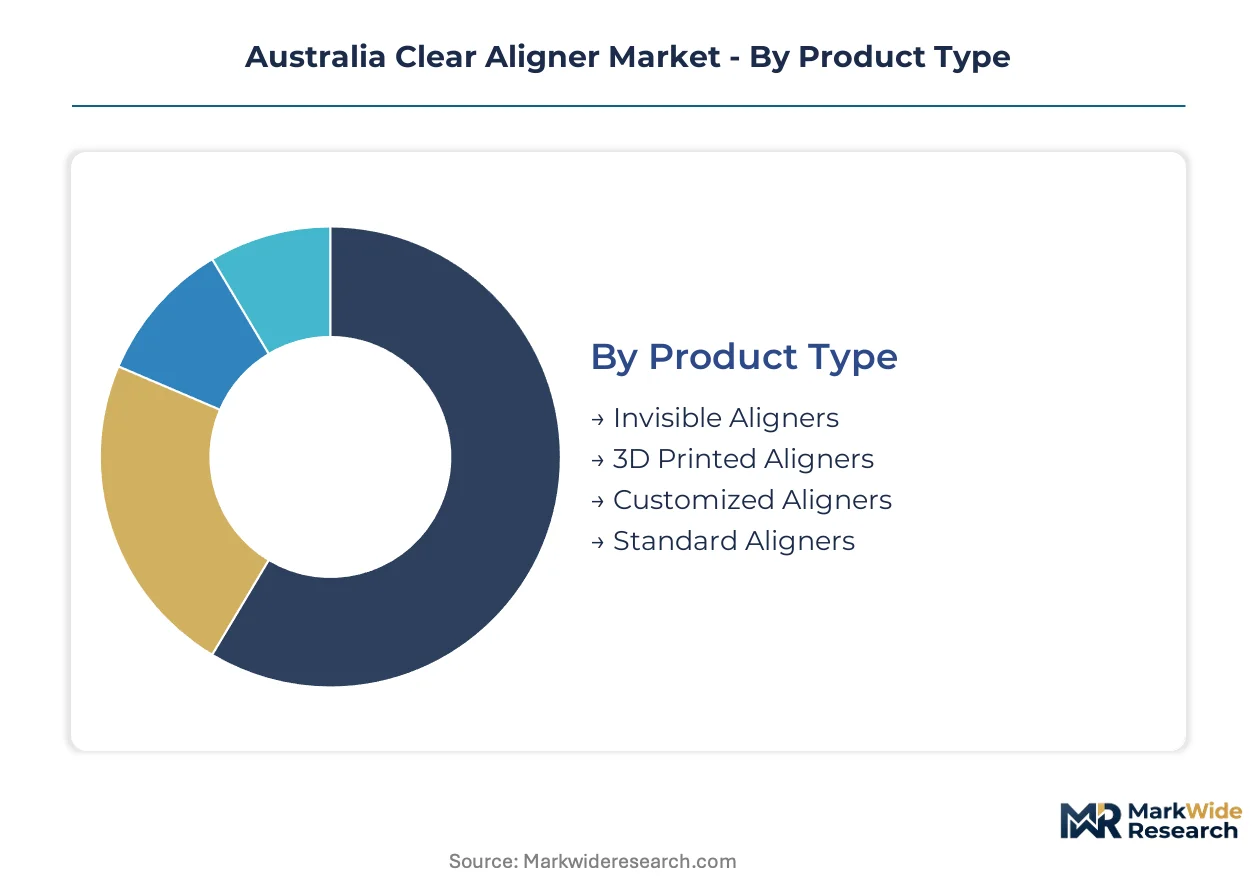
Clear aligner segmentation in Australia reveals how material certification, patient demographics, and channel access reshape competitive positioning. Each dimension carries distinct margin structures and regulatory exposure that determine where value concentrates across the treatment journey.
Product Type:
Margin pools concentrate in fabrication methods that compress laboratory turnaround and shift digital infrastructure ownership toward clinical endpoints.
- Invisible Aligners:Transparent thermoplastic appliances fabricated from medical-grade polyurethane via multi-stage pressure thermoforming. Demand clusters in Sydney and Melbourne private practices where aesthetic-conscious professionals prioritize discretion during treatment. TGA Class IIa registration requirements filter import competition and protect domestic premium positioning.
- 3D Printed Aligners:Additive-manufactured sequential appliances produced through selective laser sintering or digital light processing of photopolymer resins. Adoption accelerates in Queensland dental laboratories investing in chair-side production capacity to capture margin from outsourced fabrication networks.
- Customized Aligners:Patient-specific appliances engineered through AI-assisted treatment planning software with biomechanical optimization algorithms.
- Standard Aligners:Pre-fabricated modular aligner systems targeting mild malocclusion corrections with reduced clinical oversight requirements.
Invisible aligners hold installed capacity. 3D printed aligners are rotating up the share rankings.
Consumer Age Group:
Volume distribution tracks disposable income concentration and orthodontic treatment social normalization across generational cohorts.
- Young Adults:Patients aged 18-35 pursuing aesthetic correction during career establishment phases. Concentrated in New South Wales and Victoria metropolitan corridors where employer-sponsored dental benefits and flexible payment plans reduce upfront cost barriers.
- Adults:Working professionals aged 35-55 seeking retreatment after childhood orthodontic relapse or deferred correction. Higher case complexity drives preference for orthodontic practice channels over direct-to-consumer platforms.
- Teens:Adolescent patients with mixed dentition requiring compliance monitoring and parental consent frameworks.
- Seniors:Mature patients addressing age-related tooth migration and periodontal-compromised alignment needs.
Adults anchor current revenue contribution. Young adults are climbing the fastest in treatment initiation rates.
Distribution Channel:
Channel selection determines regulatory compliance burden and patient acquisition cost structures across Australian states.
- Orthodontic Practices:Specialist-led treatment delivery through fixed-location clinics with comprehensive diagnostic infrastructure. Highest-margin segment concentrated in Sydney, Melbourne, and Brisbane where specialist density supports referral network effects and TGA-registered supply chain differentiation.
- Direct-to-Consumer:Remote treatment platforms utilizing teledentistry consultations and mail-order aligner delivery. Geographic reach extends into regional Western Australia and Tasmania where orthodontic practice scarcity creates access gaps.
- Dental Clinics:General practitioner-mediated aligner provision with orthodontic specialist oversight for complex cases.
- Online Platforms:Digital-native patient acquisition channels aggregating remote smile assessments and treatment planning services.
Orthodontic practices command premium pricing authority. Direct-to-consumer channels are gaining share fastest in underserved regional markets.
Material Grade:
Material certification tier separates premium clinical outcomes from commodity positioning in patient communication and reimbursement negotiations.
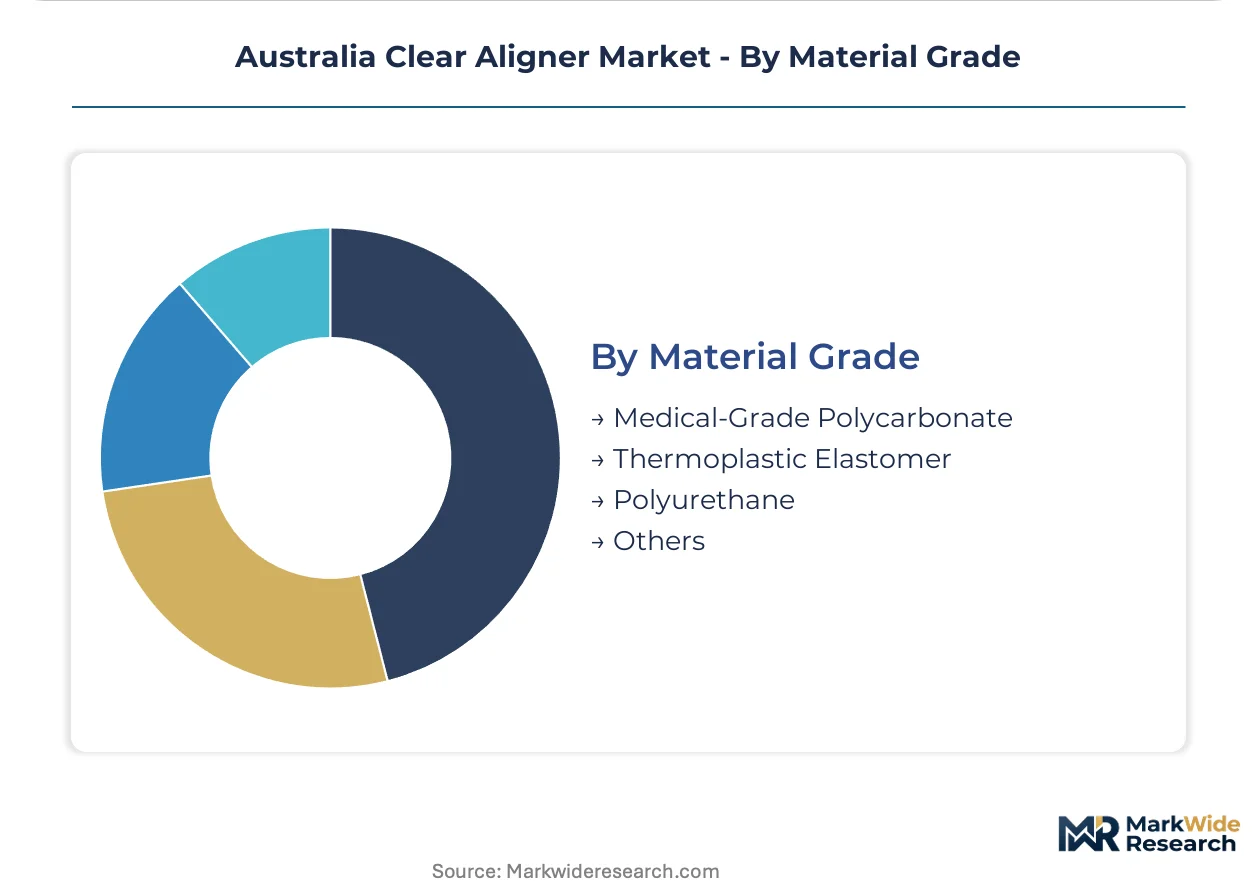
- Medical-Grade Polycarbonate:High-impact thermoplastic with superior optical clarity and fatigue resistance for extended wear cycles. Validation through TGA biocompatibility testing unwinds price resistance among Australian patients seeking treatment predictability and reduced refinement rates.
- Polyurethane:Elastomeric polymer with controlled force-deformation characteristics enabling precise tooth movement sequencing. Dominates invisible aligner fabrication through established Asia-Pacific chemical supplier relationships.
- Thermoplastic Elastomer:Soft-hard block copolymer materials offering alternative biomechanical properties for specific malocclusion types.
- Others:Emerging polymer formulations including bio-based alternatives and recycled content aligner materials.
Polyurethane holds installed capacity. Medical-grade polycarbonate is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import reliance on medical-grade thermoplastic resins from Asia-Pacific chemical suppliers shapes regional distribution patterns, while TGA-registered domestic fabrication capacity concentrates in coastal metropolitan corridors.
New South Wales
Private dental clinic density in Sydney drives the highest per-capita clear aligner treatment initiation nationally. TGA Class IIa medical device registration requirements filter import competition and protect premium positioning for registered providers. Specialist orthodontic networks in North Sydney and Parramatta anchor chair-side digital scanning infrastructure.
Victoria
Melbourne's concentration of employer-sponsored dental benefits reduces upfront cost barriers for young adult patient segments. Australian Dental Association guidelines on remote orthodontic supervision create compliance complexity for platform operators targeting metropolitan corridors. Inner-city practices in Carlton and South Yarra deploy intraoral scanners to compress treatment initiation timelines.
Queensland
Regional access gaps beyond Brisbane create demand concentration for teledentistry-enabled direct-to-consumer platforms. TGA enforcement against unregistered aligner providers compresses competitive access rules and forces channel consolidation. Dental laboratories in Gold Coast and Sunshine Coast invest in additive manufacturing to capture margin from outsourced fabrication networks.
Western Australia
Orthodontic practice scarcity in Perth's outer metropolitan rings and regional centers drives platform-based patient acquisition. The country's national medical device regulator mandates biocompatibility documentation that elevates quality benchmarks for market authorization. Direct-to-consumer operators target Fremantle and Mandurah clusters where specialist infrastructure remains underdeveloped.
Australia Clear Aligner Market Key Industry Players
Listed leaders compete with private specialists across channel access and material certification dimensions, creating a tiered structure where orthodontic practice networks hold premium positioning against platform-based challengers. Market concentration reflects TGA registration barriers that filter lower-quality imports and protect domestic incumbent positions. Two strategic archetypes dominate: integrated scanner-aligner systems and direct-to-consumer remote monitoring platforms. Competitive moves center on specialist channel partnerships and in-house additive manufacturing adoption.
Within the integrated systems tier, Align Technology exemplifies scanner-network dominance through its Invisalign infrastructure across Sydney and Melbourne practices. SmilePath Australia occupies a position representing direct-to-consumer accessibility archetypes, competing on teledentistry-enabled remote monitoring. Institut Straumann AG anchors the specialist partnership vector, emphasizing orthodontic practice channel relationships over platform scalability.
| Leading Market Players |
|---|
| Align Technology |
| SmileDirectClub |
| Ormco |
| 3M |
| Dentsply Sirona |
| Institut Straumann AG |
| ClearCorrect |
| Angelalign Technology |
| SmilePath Australia |
| Others |
Cost & Logistics Intelligence
Medical-grade polycarbonate substitution for conventional polyurethane feedstocks is redrawing procurement geography toward certified Asia-Pacific chemical suppliers while compressing margin pools for laboratories unable to absorb TGA biocompatibility testing costs. This material transition simultaneously elevates quality benchmarks and concentrates pricing power among TGA-registered domestic fabricators.
Pricing Analysis
Orthodontic practice buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on material certification grade and chair-side digital infrastructure ownership. Cost compression in the direct-to-consumer tier is intensifying because TGA enforcement against unregistered providers forces platform compliance investments. Young adult patients in metropolitan corridors show lowest price sensitivity, while regional patients in Western Australia and Tasmania exhibit highest elasticity.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes from Shanghai and Singapore elevates inbound logistics costs for medical-grade thermoplastic resin shipments. Supply concentrates in China, South Korea, and Japan for polyurethane feedstocks, with Germany and Switzerland anchoring polycarbonate specialty grades. Raw material dependencies include photopolymer resins, selective laser sintering powders, and intraoral scanning hardware. Single-source vulnerability from concentrated Asia-Pacific chemical suppliers creates exposure to input cost volatility. Distribution runs through orthodontic practice networks in Sydney and Melbourne, with direct-to-consumer platforms bypassing traditional laboratory intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia clear aligner market is recovering from TGA enforcement cyclicality, with regulatory normalization now enabling volume expansion through registered channels.
For Market Incumbents: Secure TGA-registered supply chain differentiation against direct-to-consumer platform competitors by emphasizing chair-side digital infrastructure ownership. Invest in additive manufacturing capacity within Queensland dental laboratories to capture margin from outsourced fabrication networks. The threat of SmilePath Australia and similar teledentistry platforms demands channel control through specialist orthodontist partnerships. For New Entrants and Emerging Players: Differentiate on regional access penetration in Western Australia and Tasmania where orthodontic practice scarcity creates underserved demand. Target young adult patient segments in Perth outer metropolitan rings through teledentistry-enabled remote monitoring. White-space exists in customized aligner fabrication for complex malocclusion cases requiring AI-assisted treatment planning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental laboratory networks possessing additive manufacturing capabilities. Long-term viability over the next decade hinges on TGA registration compliance and in-house digital workflow adoption. The signal to watch is Australian Dental Association guideline evolution on remote orthodontic supervision rules.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Pathway | Accelerates market authorization for novel aligner materials and fabrication methods. |
| Chair-Side Scanner Network Expansion | Align Technology leverages Invisalign infrastructure across Sydney and Melbourne practices. |
| Additive Manufacturing Integration | Queensland dental laboratories capture margin from outsourced fabrication networks. |
| Specialist Orthodontist Partnership | Institut Straumann AG anchors premium positioning through channel control. |
| Teledentistry Platform Compliance | Direct-to-consumer operators adapt to Australian Dental Association remote supervision guidelines. |
Research Approach
The analysis maps invisible aligner fabrication, 3D printed aligner production, teledentistry platform delivery, and orthodontic practice networks, each validated through orthodontic specialists, dental laboratory operators, TGA regulatory consultants, and direct-to-consumer platform executives. Primary interviews combined with secondary validation from TGA medical device registration databases, Australian Dental Association guideline publications, and Asia-Pacific chemical supplier trade records. Bottom-up and top-down triangulation cross-checked patient volume estimates against fabrication capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, consumer age group, distribution channel, and material grade tier. CAGRs were derived from patient initiation rate trajectories and average selling price evolution. Industry-specific forecast inputs incorporated TGA enforcement intensity scenarios and intraoral scanner adoption curves in metropolitan versus regional practice clusters.
Material uncertainties — TGA regulatory reinterpretation, thermoplastic resin supply disruptions, and Australian Dental Association guideline revisions — sit outside the modeled envelope. Forecasts reflect assumptions about continued patient preference shift from fixed appliances and stable Asia-Pacific chemical supplier relationships. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Neurotech Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Struts Implants Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
North America Ultrasound Probe Disinfection Market