
 Mail Order Pharmacy Market | 2026-2036
Mail Order Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Mail Order Pharmacy Market Analysis
Multi-source pharmaceutical procurement is restructuring supply relationships across the mail order channel. CVS Health Corporation leverages its vertically integrated PBM-pharmacy infrastructure to control formulary access and fulfillment economics. Express Scripts Holding Company anchors its competitive stance through specialty pharmacy capabilities and employer plan carve-out dominance. Amazon Pharmacy competes on logistics velocity, using its distribution footprint to compress delivery windows for maintenance medications.
A mail order pharmacy operates as a remote dispensing facility that receives prescriptions electronically or by mail, validates them through licensed pharmacists, and ships medications directly to patients, typically requiring cold-chain protocols for biologics and temperature-controlled storage for insulin and vaccines. Prescription medications generate the dominant revenue stream, while specialty drugs command the highest margin pools due to limited distribution networks and patient support requirements. Express delivery and same-day delivery segments are expanding fastest as PBMs and retailers respond to patient expectations shaped by consumer e-commerce benchmarks.
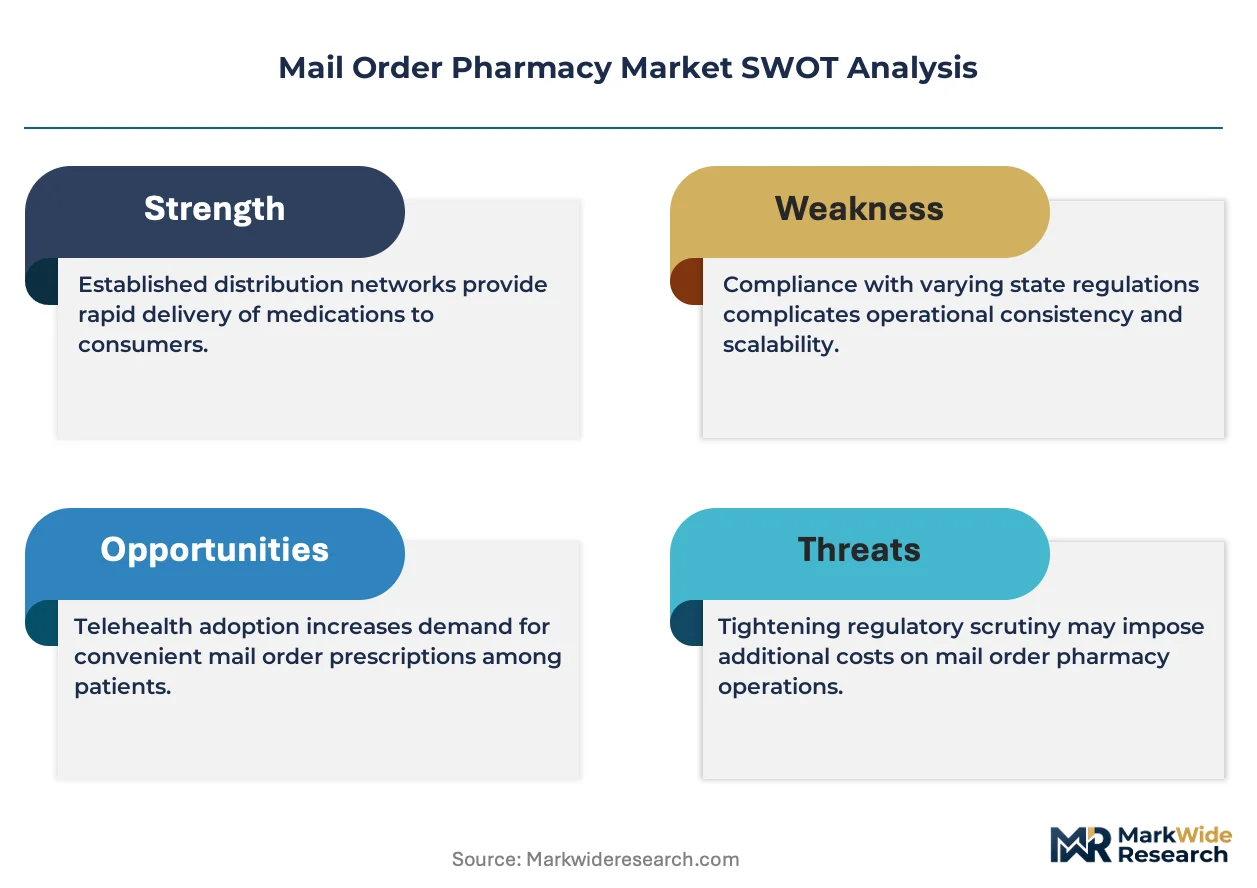
The US FDA enforces track-and-trace requirements under the Drug Supply Chain Security Act, compelling mail order pharmacies to implement serialized packaging and verified shipping partners. HIPAA governs patient data transmission between prescribers, payers, and fulfillment centers, creating compliance costs that favor scaled operators with dedicated security infrastructure. State boards of pharmacy impose varying licensure and staffing rules that fragment operational standardization across jurisdictions. Stakeholders must monitor how CMS reimbursement adjustments for 90-day supplies and specialty tiers reshape patient channel preferences and PBM contract structures.
Market Dynamics
The Drug Supply Chain Security Act's serialization mandate is compressing operating margins for mail order pharmacies while simultaneously erecting compliance barriers that favor scaled operators with integrated track-and-trace infrastructure.
Growth Catalysts
- Chronic Disease Management:Medicare-eligible populations with diabetes, cardiovascular conditions, and respiratory diseases require 90-day maintenance supplies that align with mail order fulfillment economics.
- HIPAA-Certified Data Infrastructure:Secure electronic prescribing networks enable seamless transmission between prescribers, PBMs, and fulfillment centers without paper intermediaries.
- Germany:Dense last-mile networks operated by DocMorris and domestic competitors demonstrate viable cold-chain protocols for temperature-sensitive biologics and insulin.
Market Restraints
- Temperature-Controlled Logistics Costs:Cold-chain packaging for biologics, vaccines, and insulin adds 15-25% to fulfillment expenses versus ambient pharmaceuticals.
- State-by-State Licensure Fragmentation:Varying staffing ratios, pharmacist-in-charge requirements, and facility inspections create operational complexity across US jurisdictions.
- Specialty Drug Limited Distribution Networks:Manufacturer-controlled channels restrict mail order pharmacy access to high-margin oncology and rare disease therapies.
Strategic Opportunities
- Same-Day Delivery Infrastructure:Urban micro-fulfillment centers enable compressed delivery windows for maintenance medications, matching consumer e-commerce expectations.
- Specialty Pharmacy Accreditation:URAC and ACHC certifications open limited distribution networks for complex therapies requiring patient support programs.
- Telehealth Integration:Virtual care platforms are converging with mail order fulfillment to create closed-loop prescription-to-delivery workflows.
Industry Challenges
- Serialized Packaging Implementation:DSCSA compliance requires capital investment in barcode verification systems and verified shipping partner networks.
- Pharmacist Workforce Constraints:Remote verification roles compete with retail and clinical positions for licensed professionals across multiple state jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mail Order Pharmacy Market |
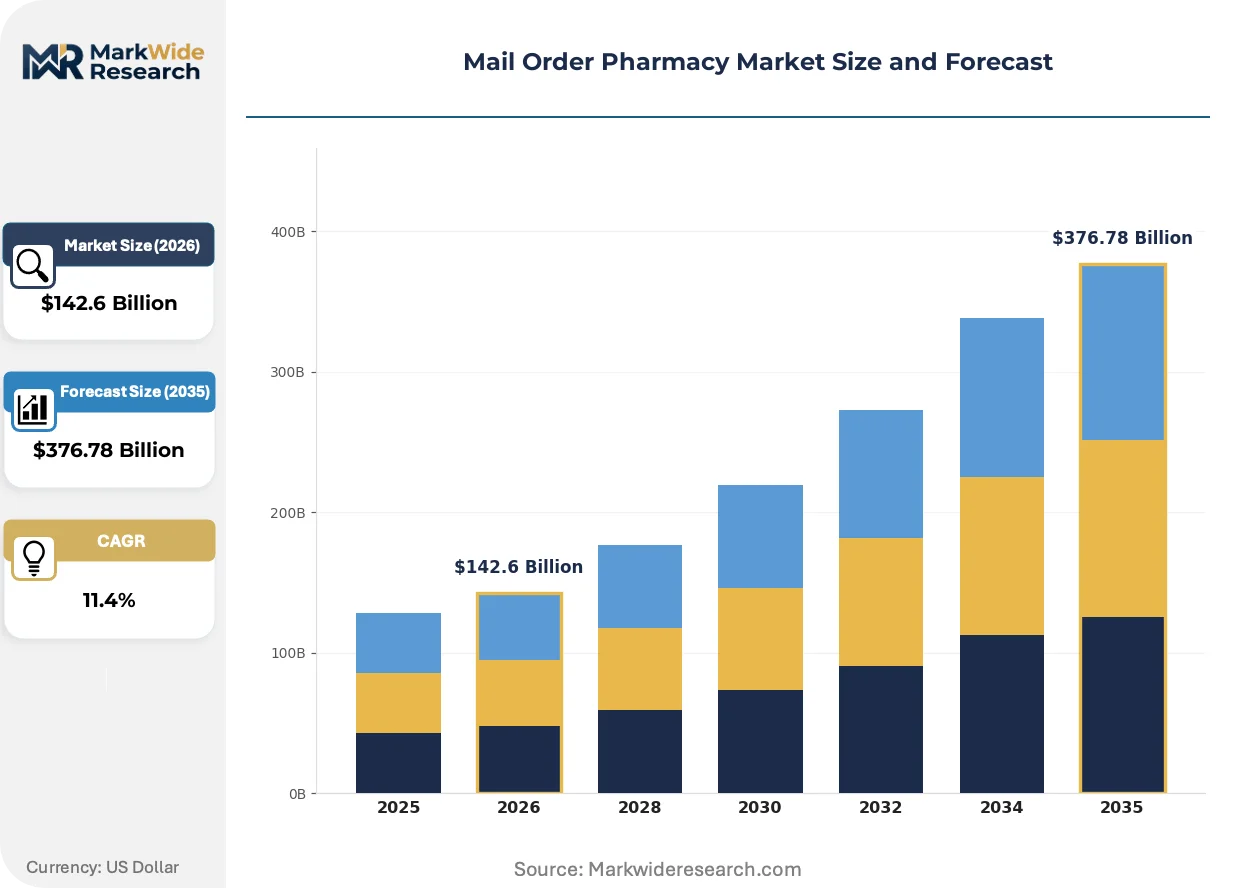
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $376.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prescription Medications, Over-the-Counter Drugs, Nutraceuticals, Specialty Drugs Delivery Method: Standard Shipping, Express Delivery, Local Pickup, Same-Day Delivery End User: Individual Consumers, Healthcare Providers, Insurance Entities, Organizations Payment Model: Subscription-Based, Pay-per-Order, Insurance Coverage, Out-of-Pocket |
| Companies Covered | CVS Health Corporation, Express Scripts Holding Company, Walgreens Boots Alliance Inc., OptumRx Inc., Amazon Pharmacy, Walmart Inc., AllianceRx Walgreens Prime, MedImpact Healthcare Systems Inc., DocMorris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mail Order Pharmacy Market Emerging Trajectories
Automation and regulatory serialization are converging to reshape fulfillment economics, while patient expectations borrowed from consumer retail are compressing delivery timelines and forcing channel integration.
Robotic dispensing systems are automating vial filling, label application, and quality verification in high-volume mail order facilities. CVS Health and Express Scripts have deployed these systems across their centralized fulfillment centers to process 90-day maintenance prescriptions with reduced labor intensity. The technology is automating pharmacist workflow allocation toward clinical consultation and exception handling rather than mechanical dispensing tasks.
The FDA's Drug Supply Chain Security Act mandates unit-level traceability for all prescription drugs by November 2024, with full electronic interoperability required by 2028. Mail order pharmacies must implement serialized packaging, verified shipping partners, and interoperable data systems to maintain dispensing privileges. Specialty drug segments face the steepest compliance costs due to limited batch sizes and complex handling requirements.
Patient channel preferences are rotating toward same-day and next-day delivery options for maintenance medications, displacing traditional 5-7 day standard shipping. Amazon Pharmacy and retail-backed mail order operations are investing in urban micro-fulfillment nodes to match consumer e-commerce benchmarks. This shift is most visible in metropolitan corridors where density supports economically viable rapid delivery networks.
Mail Order Pharmacy Market Segmentation
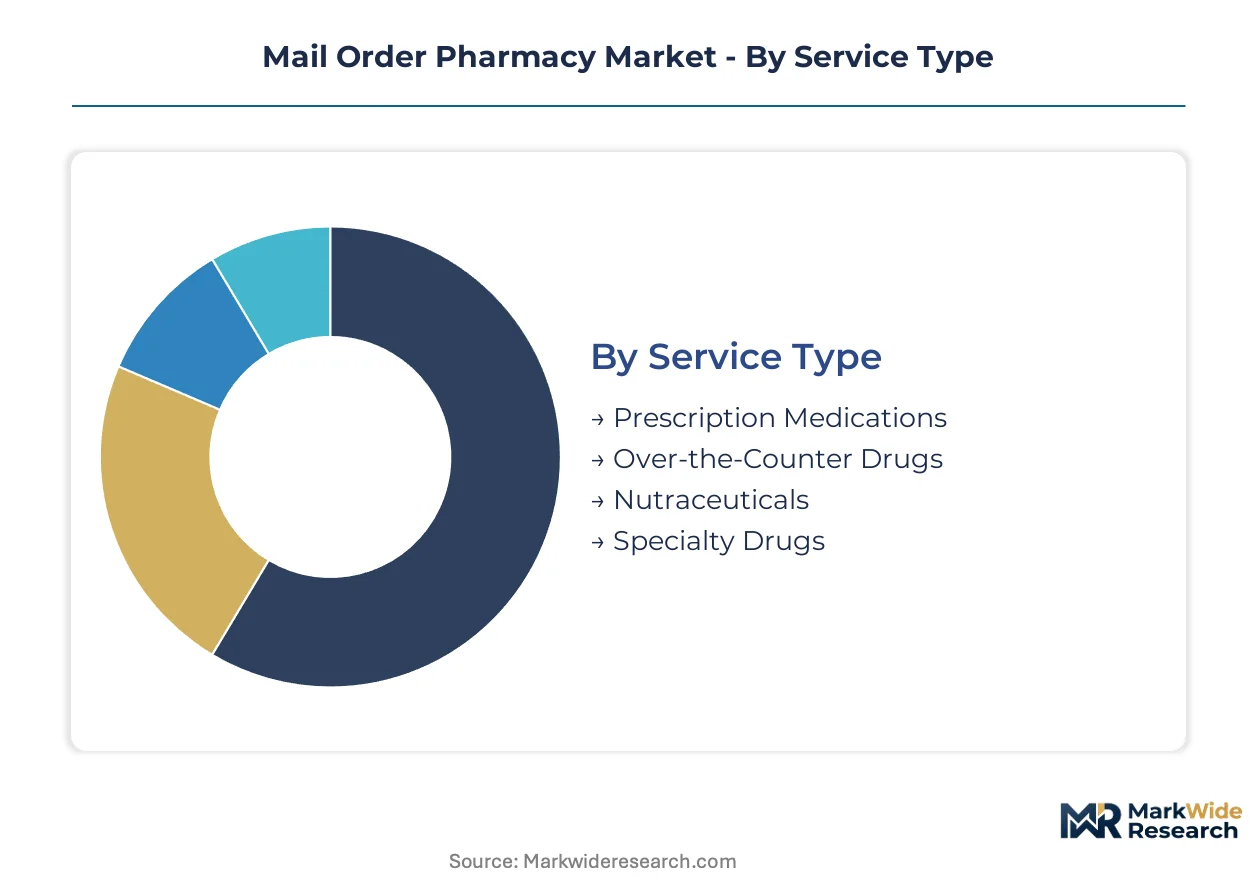
Mail order pharmacy segmentation reveals how fulfillment economics, patient risk profiles, and reimbursement structures allocate revenue across service tiers. Channel preferences diverge sharply between maintenance medications and complex specialty therapies.
Service Type:
Replacement cycles for chronic disease management drive upgrade patterns across service tiers, with patients migrating from acute dispensing to automated 90-day maintenance programs.
- Prescription Medications:Maintenance therapies for diabetes, hypertension, and hyperlipidemia dominate volume through automated refill programs. Medicare Part D beneficiaries in the United States generate concentrated demand for 90-day supplies that reduce copay burdens and improve adherence metrics tracked by CMS.
- Specialty Drugs:Limited distribution biologics for oncology, autoimmune conditions, and rare diseases require cold-chain handling and patient support services. Manufacturers restrict channel access to accredited pharmacies with URAC or ACHC certification, creating margin concentration in qualified fulfillment networks.
- Over-the-Counter Drugs:Bulk purchasing of analgesics, antihistamines, and gastrointestinal remedies supplements prescription revenue with lower per-order value but higher frequency.
- Nutraceuticals:Vitamins, supplements, and wellness products attract cash-pay consumers outside insurance formularies, typically bundled with prescription orders to reach free shipping thresholds.
Volume placements concentrate in Prescription Medications; the faster expansion belongs to Specialty Drugs.
Delivery Method:
Cost tier differentiation separates patients by urgency tolerance and insurance benefit design, with premium delivery options commanding out-of-pocket fees.
- Standard Shipping:Five-to-seven-day ground delivery remains the default for 90-day maintenance prescriptions covered by commercial insurance and Medicare Part D. CVS Health and Express Scripts optimize network density to minimize per-package logistics costs.
- Same-Day Delivery:Urban micro-fulfillment centers enable compressed windows for acute medication needs and insulin refills. Amazon Pharmacy leverages existing distribution infrastructure to match consumer e-commerce expectations in metropolitan corridors.
- Express Delivery:Two-day and overnight options serve patients transitioning from retail pharmacy or requiring antibiotic courses.
- Local Pickup:Hybrid models allow mail order prescriptions to be retrieved at retail partner locations, bridging remote dispensing with immediate access.
Standard Shipping retains the highest prescription volume; Same-Day Delivery is climbing the fastest as urban density supports economically viable rapid networks.
End User:
Application-based segmentation aligns fulfillment protocols with clinical oversight requirements and procurement authority.
- Individual Consumers:Chronic disease patients managing multiple medications represent the core revenue base, with adherence programs targeting Medicare-eligible populations in the United States and statutory insurance beneficiaries in Germany.
- Insurance Entities:PBMs and health plans direct member volume to preferred mail order pharmacies through formulary tiering and cost-sharing incentives.
- Healthcare Providers:Physician practices and health systems prescribe through integrated e-prescribing networks that route directly to mail order fulfillment.
- Organizations:Employer-sponsored health plans and government agencies contract for population-level pharmacy benefits with mandatory mail order requirements for maintenance therapies.
Individual Consumers account for the dominant prescription volume; Insurance Entities are gaining share fastest through PBM vertical integration.
Payment Model:
Customer type segmentation separates cash-pay wellness purchasers from insurance-integrated chronic disease management.
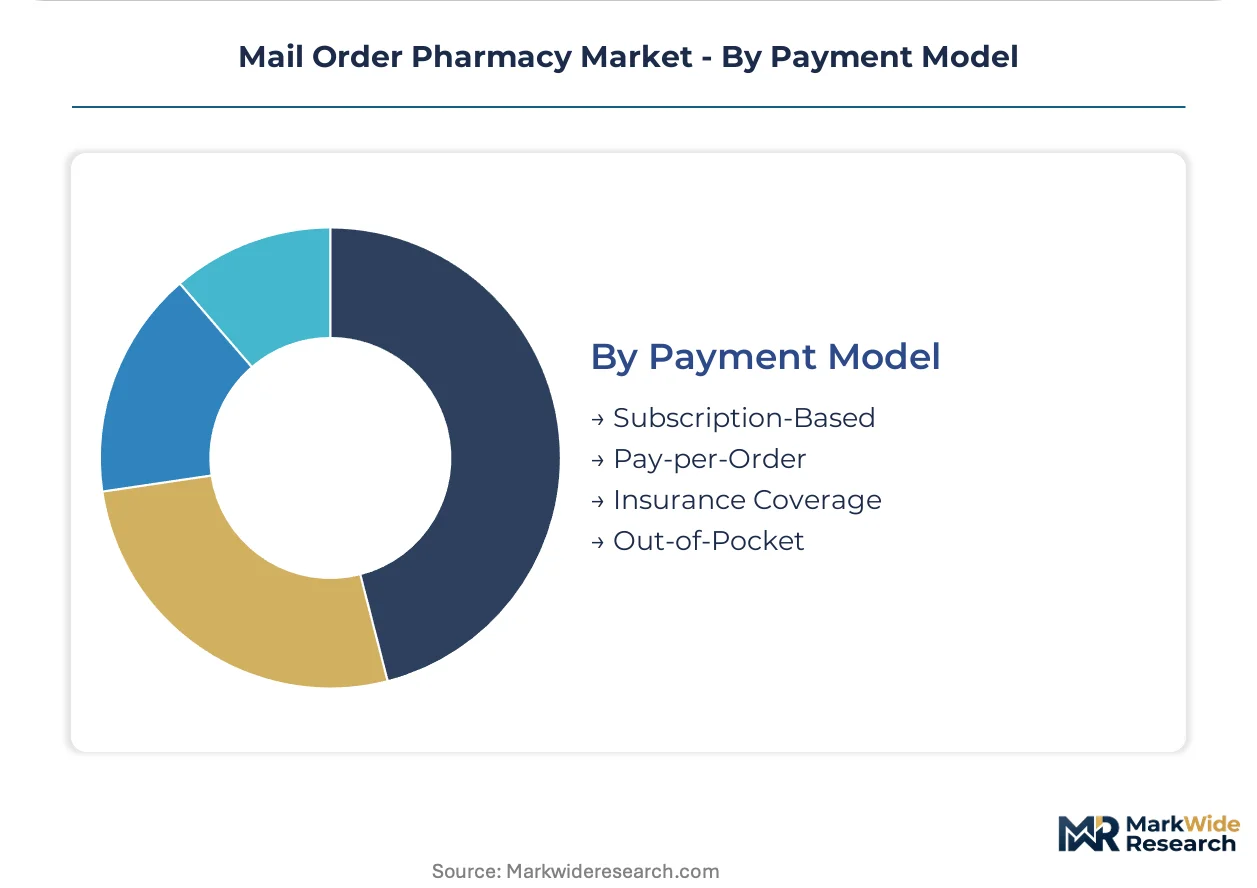
- Insurance Coverage:Commercial and Medicare Part D benefits cover the majority of prescription volume, with mail order pharmacies capturing 90-day supply economics mandated by plan design.
- Subscription-Based:Automated refill programs for chronic conditions reduce administrative burden and secure predictable revenue streams.
- Pay-per-Order:Acute and first-fill prescriptions processed without enrollment in automatic renewal programs.
- Out-of-Pocket:Cash payments for excluded medications, high-deductible plan phases, and international sourcing through cross-border pharmacies.
Insurance Coverage dominates transaction volume; Subscription-Based models are expanding most quickly as PBMs incentivize automated adherence programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mail order pharmacy demand concentrates in Medicare-eligible populations and statutory insurance systems, with regulatory frameworks and last-mile infrastructure determining competitive positioning across major economies.
United States
Medicare Part D beneficiaries drive 90-day maintenance prescription volume through vertically integrated PBM-pharmacy networks. The FDA's Drug Supply Chain Security Act mandates serialized packaging and track-and-trace compliance for all mail-dispensed pharmaceuticals. CVS Health and Express Scripts operate centralized fulfillment centers in Tennessee and Arizona that process millions of automated refills monthly.
Germany
Statutory health insurance beneficiaries generate concentrated demand for chronic disease medications through approved mail order channels. The country's national pharmaceutical regulator enforces strict cold-chain protocols for temperature-sensitive biologics under AMG provisions. DocMorris and domestic competitors maintain dense last-mile networks in North Rhine-Westphalia and Bavaria that demonstrate viable same-day delivery for insulin and vaccines.
United Kingdom
NHS Electronic Prescription Service routing directs chronic medication volume toward centralized dispensing hubs. The Medicines and Healthcare products Regulatory Agency oversees remote pharmacy licensure and patient data protection under GDPR-aligned standards. Pharmacy2U and Boots operate automated fulfillment facilities in the Midlands that serve England's metropolitan corridors with compressed delivery windows.
Japan
Aging demographics and government cost-containment policies accelerate adoption of 90-day supply programs for hypertension and diabetes therapies. PMDA regulations govern pharmaceutical distribution security and patient privacy in electronic prescribing networks. Mitsubishi Tanabe Pharma and domestic pharmacy chains operate temperature-controlled fulfillment centers in the Kanto region serving Tokyo's dense patient populations.
Canada
Provincial drug benefit programs and private insurance carve-outs channel maintenance medication volume toward mail order fulfillment. Health Canada enforces Good Distribution Practices for temperature-sensitive pharmaceuticals and track-and-trace requirements for controlled substances. Shoppers Drug Mart and regional operators operate centralized dispensing facilities in Ontario and British Columbia that serve dispersed rural populations.
Mail Order Pharmacy Market Vendor Landscape
Vertical integration dominates the current landscape as PBMs acquire or build captive mail order fulfillment capacity to control formulary economics and patient data flows. The market structure consolidates around three to five national-scale operators with integrated PBM, pharmacy, and insurance assets, while regional specialists compete on specialty accreditation and local delivery velocity. Two strategic archetypes prevail: vertically integrated healthcare conglomerates leveraging captive patient volume, and logistics-native entrants compressing delivery timelines through distribution infrastructure. Competitive moves center on specialty pharmacy accreditation acquisition and urban micro-fulfillment node deployment.
Among vertically integrated healthcare conglomerates, CVS Health Corporation and Express Scripts Holding Company exemplify the PBM-pharmacy convergence archetype, anchoring competitive positioning through formulary control and centralized fulfillment scale. Amazon Pharmacy represents the logistics-native entrant archetype, occupying a position shaped by consumer e-commerce delivery expectations and metropolitan distribution density. DocMorris sits within the European specialist tier, demonstrating viable cold-chain protocols in Germany's dense last-mile environment.
| Leading Market Players |
|---|
| CVS Health Corporation |
| Express Scripts Holding Company |
| Walgreens Boots Alliance Inc. |
| OptumRx Inc. |
| Amazon Pharmacy |
| Walmart Inc. |
| AllianceRx Walgreens Prime |
| MedImpact Healthcare Systems Inc. |
| DocMorris |
| Others |
Supply Flow & Price Mechanics
DSCSA serialization mandates gate qualified supply access and premium-tier pricing for mail order pharmacies, with compliant operators commanding formulary preference while non-compliant facilities face exclusion from PBM networks and manufacturer limited distribution agreements.
Pricing Analysis
Volume concentrates in 90-day maintenance prescriptions with thin margins, while specialty biologics generate premium returns through limited distribution network exclusivity. Price differentiation hinges on URAC/ACHC accreditation status and cold-chain handling capability, with certified specialty pharmacies capturing 3-5x margin multiples over standard dispensing. Pricing pressure stems from PBM reimbursement compression for generic maintenance therapies, with Medicare Part D DIR fee restructuring accelerating margin erosion. Cash-pay consumers exhibit highest price sensitivity, while employer-sponsored plans prioritize network adequacy over per-prescription cost.
Supply Chain Analysis
Domestic-content rules in pharmaceutical distribution reshape sourcing toward FDA-registered repackagers and verified shipping partners compliant with track-and-trace mandates. API production concentrates in India and China, with finished dose formulation and cold-chain packaging anchored in the United States and Germany. Supply chain risk centers on single-source biologics manufacturers and temperature-excursion liability during last-mile delivery. Distribution runs through centralized fulfillment centers in Tennessee, Arizona, and North Rhine-Westphalia, with urban micro-fulfillment nodes expanding for same-day delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mail order pharmacy has become a vertical-integration race, with formulary control and captive PBM volume serving as the decisive downstream lever for sustainable margin defense.
For Market Incumbents: Cement formulary exclusivity through 90-day supply mandate contracts with employer-sponsored plans and Medicare Advantage organizations. Deepen cold-chain infrastructure in dense metropolitan corridors to match Amazon Pharmacy's delivery velocity. Acquire URAC specialty pharmacy accreditation to unlock oncology and rare disease limited distribution networks before manufacturer channel restrictions tighten further.
For New Entrants and Emerging Players: Telehealth-integrated prescription routing offers a technology-first wedge into the chronic disease management segment, with virtual care platforms creating closed-loop workflows that bypass established PBM gatekeepers. Target cash-pay nutraceutical and wellness bundles as the most penetrable white space, using subscription-based pricing to build recurring revenue before attempting insurance network participation. Partner with regional health systems for e-prescribing integration rather than competing directly for PBM carve-out contracts.
For Investors and Strategic Acquirers: CMS reimbursement adjustments for specialty tier formulary placement are the leading indicator that margin concentration is shifting toward accredited specialty pharmacy operations. Five-to-ten-year viability favors platforms combining PBM assets with captive fulfillment infrastructure and telehealth connectivity. Monitor URAC accreditation application volumes as the signal for competitive intensity in limited distribution network access.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Pharmacy Accreditation | URAC certification unlocks manufacturer limited distribution networks for oncology biologics. |
| Urban Micro-Fulfillment Deployment | Metropolitan nodes enable same-day insulin delivery matching Amazon Pharmacy's velocity benchmarks. |
| PBM Vertical Integration | Captive formulary control secures 90-day maintenance prescription volume from employer plans. |
| Cold-Chain Infrastructure Expansion | Temperature-controlled logistics capabilities support biologics dispensing with 15-25% cost premium capture. |
| Telehealth Platform Integration | Virtual care routing creates closed-loop prescription workflows bypassing traditional retail pharmacy channels. |
Methodological Framework
Multi-period observation of PBM formulary tier adjustments, CMS reimbursement rate publications, and specialty pharmacy accreditation volumes anchored the trend analysis, supplemented by interviews with mail order pharmacy operations directors, PBM contract managers, FDA regulatory affairs specialists, and health system pharmacy procurement leads. Secondary validation drew from FDA DSCSA guidance documents, CMS Medicare Part D payment files, URAC accreditation directories, and state board of pharmacy licensure databases. Bottom-up prescription volume modeling triangulated against top-down PBM market share estimates.
Input-output matrices structured demand across service type, delivery method, end user, and payment model segmentation dimensions, with volume and value outputs reconciled through iterative calibration across the projection horizon. CAGRs were derived from trend extrapolation of 90-day supply adoption rates, specialty drug dispensing growth, and same-day delivery infrastructure expansion. Forecast inputs included Medicare Part D enrollment trajectories, manufacturer limited distribution network restrictions, and cold-chain logistics cost curves.
Several conditions sit outside the modeled scope, including state-by-state licensure rule changes, FDA enforcement discretion on DSCSA compliance timelines, and PBM consolidation outcomes. Forecasts reflect assumptions regarding continued Medicare Advantage growth and employer plan carve-out stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
PDE Inhibitors Market