
 Hormonal Implants Market | 2026-2036
Hormonal Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Hormonal Implants Market Foresight
Hospital outpatient demand for long-acting reversible contraception is shifting toward single-rod etonogestrel systems over multi-capsule legacy formats. Bayer AG leverages polymer science expertise to sustain European manufacturing dominance. Merck & Co anchors North American supply through vertically integrated steroid synthesis. Organon & Co differentiates via clinic-direct distribution networks.
Hormonal implants are subdermal or intrauterine drug delivery systems that release synthetic progestins—typically etonogestrel or levonorgestrel—at controlled rates through biocompatible polymer matrices for contraception or endocrine therapy over multi-year durations. Subdermal implants now lead product type revenue due to insertion simplicity and reversibility, while intrauterine devices capture margin pools from extended replacement cycles. Contraception dominates therapy area volume, though hormone replacement applications are gaining fastest growth as menopausal symptom management expands in clinic settings.
FDA premarket notification requirements and EMA MDR compliance shape polymer biocompatibility standards and clinical trial endpoints for implantable hormonal devices. The EU AI Act and GDPR impose data governance obligations on connected implant monitoring systems under development. Stakeholders must monitor reimbursement negotiations between national health services and manufacturers as cost-effectiveness thresholds tighten for long-acting contraceptive access programs.
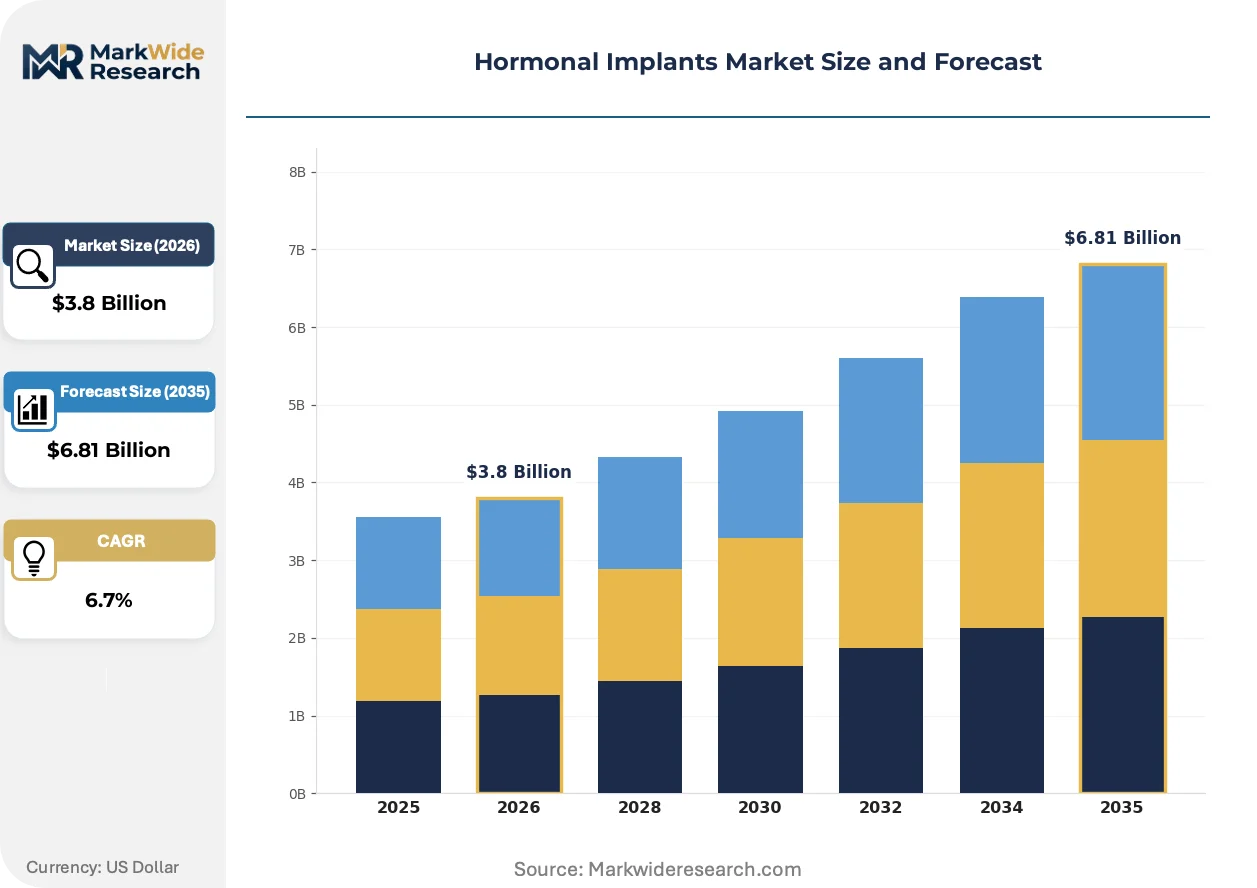
Market Dynamics
Subsidized family planning programs in Brazil, Germany, and the United States are redirecting procurement toward single-rod etonogestrel systems, compressing demand for multi-capsule legacy formats and reshaping manufacturing scale requirements across polymer substrate suppliers.
Growth Catalysts
- EMA MDR Streamlining:The European Medicines Agency's premarket review harmonization for biocompatible polymer substrates accelerates device approval timelines and reduces clinical trial redundancy across member states.
- Brazil's SUS Expansion:The Unified Health System's scaling of long-acting reversible contraceptive services in municipal clinics creates sustained volume commitments for implant manufacturers.
- Polymer Matrix Advances:Next-generation silicone elastomer formulations enable three-year release profiles with improved insertion mechanics, expanding addressable patient populations.
Market Restraints
- Steroid Sourcing Concentration:Etonogestrel API production clusters in Indian and Chinese contract manufacturers, exposing supply chains to export license volatility and geopolitical friction.
- Reimbursement Compression:Germany's Federal Joint Committee applies tightening cost-effectiveness thresholds for contraceptive coverage, pressuring net pricing for premium-tier devices.
- Copper IUD Substitution:Non-hormonal intrauterine devices capture price-sensitive segments in public health systems, particularly where progestin side-effect concerns persist.
Strategic Opportunities
- Menopausal Hormone Therapy:Off-label expansion into endocrine symptom management for perimenopausal patients opens clinic-direct channels beyond traditional family planning settings.
- FDA Breakthrough Device Pathway:Connected implant monitoring systems with real-time release-rate telemetry qualify for expedited review, compressing time-to-market for digital-therapeutic combinations.
- Sub-Saharan Africa Procurement:UNFPA and USAID tender programs for long-acting contraceptives present volume opportunities for manufacturers meeting WHO prequalification standards.
Industry Challenges
- Polymer Biocompatibility Certification:ISO 10993 cytotoxicity and sensitization testing requirements extend preclinical timelines by 12-18 months for novel substrate formulations.
- Insertion Training Infrastructure:Clinic capacity for proper subdermal placement remains uneven across rural health districts, limiting effective demand conversion despite product availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hormonal Implants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subdermal Implants, Intrauterine Devices, Contraceptive Rods, Vaginal Rings Therapy Area: Contraception, Hormone Replacement, Menstrual Regulation, Fertility Treatment Delivery Mode: Injection, Implantation, Oral, Topical End User: Clinics, Hospitals, Pharmacies, Homecare |
| Companies Covered | Merck & Co, Bayer AG, Pfizer, Organon & Co, Shanghai Dahua Pharmaceutical Co., Ltd., Teva Pharmaceutical Industries, Viatris, Gedeon Richter Plc, HRA Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hormonal Implants Market Shifts & Advancements
Digital integration and polymer science advances are converging to transform hormonal implants from passive drug reservoirs into precision delivery platforms with real-time monitoring capabilities.
Biodegradable polymer matrices incorporating polylactic-co-glycolic acid are automating the elimination of removal procedures, enabling complete absorption over the contraceptive duration. Hospital outpatient departments in the United States are piloting these systems for patient populations with limited follow-up access. The technology is automating cost structures by eliminating explantation infrastructure and reducing long-term liability exposure for public health programs.
The EU AI Act's risk-classification framework for software-as-medical-device components imposes conformity assessment obligations on connected implant systems with data transmission capabilities. Manufacturers integrating Bluetooth-enabled release monitoring must demonstrate algorithmic transparency and cybersecurity resilience under notified body supervision. European notified entities are expanding technical documentation requirements specifically for hormonal implant digital companions, affecting product development roadmaps.
Clinic-direct distribution networks are displacing wholesale pharmaceutical channels for long-acting contraceptive procurement. Organon & Co and Bayer AG have established dedicated field teams serving hospital outpatient departments and federally qualified health centers directly. This channel compression is most visible in the United States, where Medicaid managed care organizations increasingly mandate single-source contracting for implantable contraceptives to simplify prior authorization workflows.
Hormonal Implants Market Segmentation
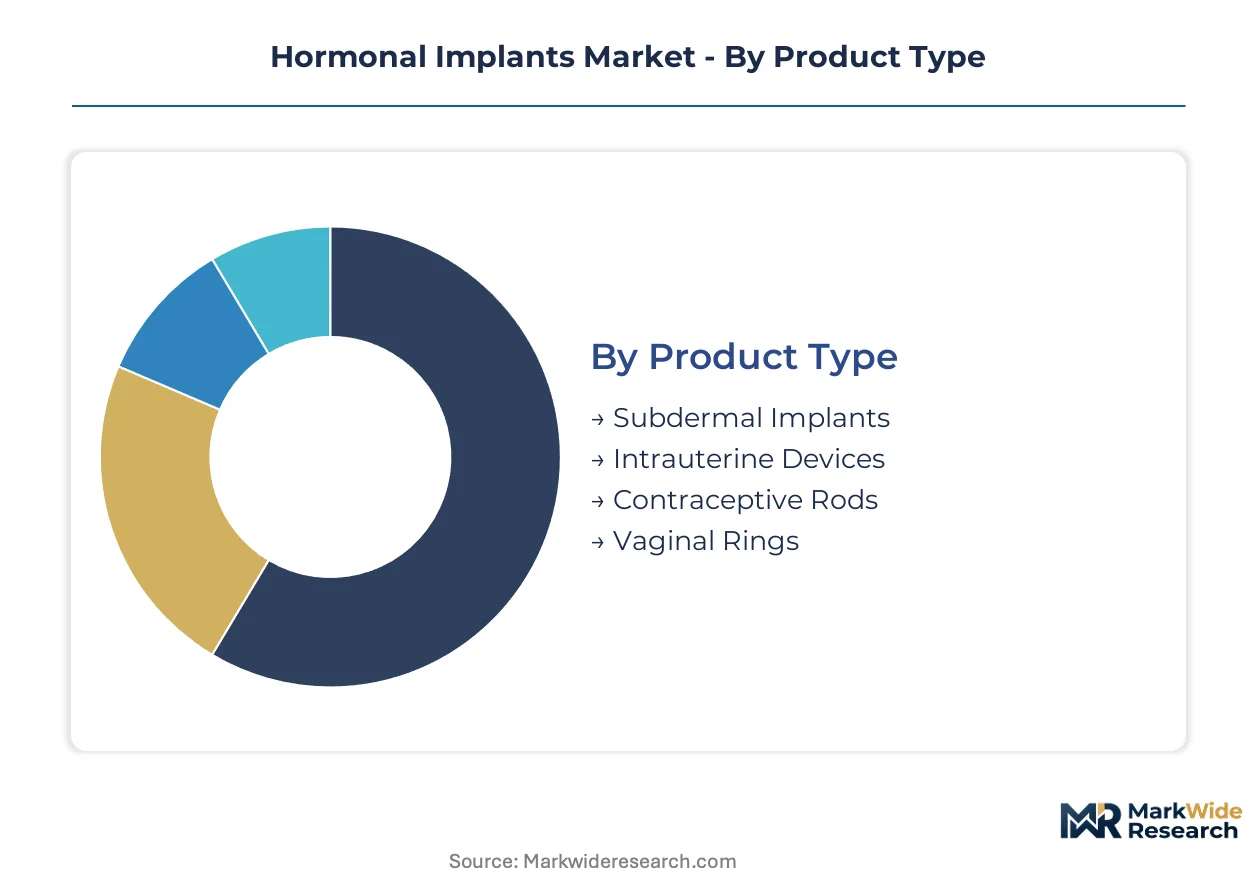
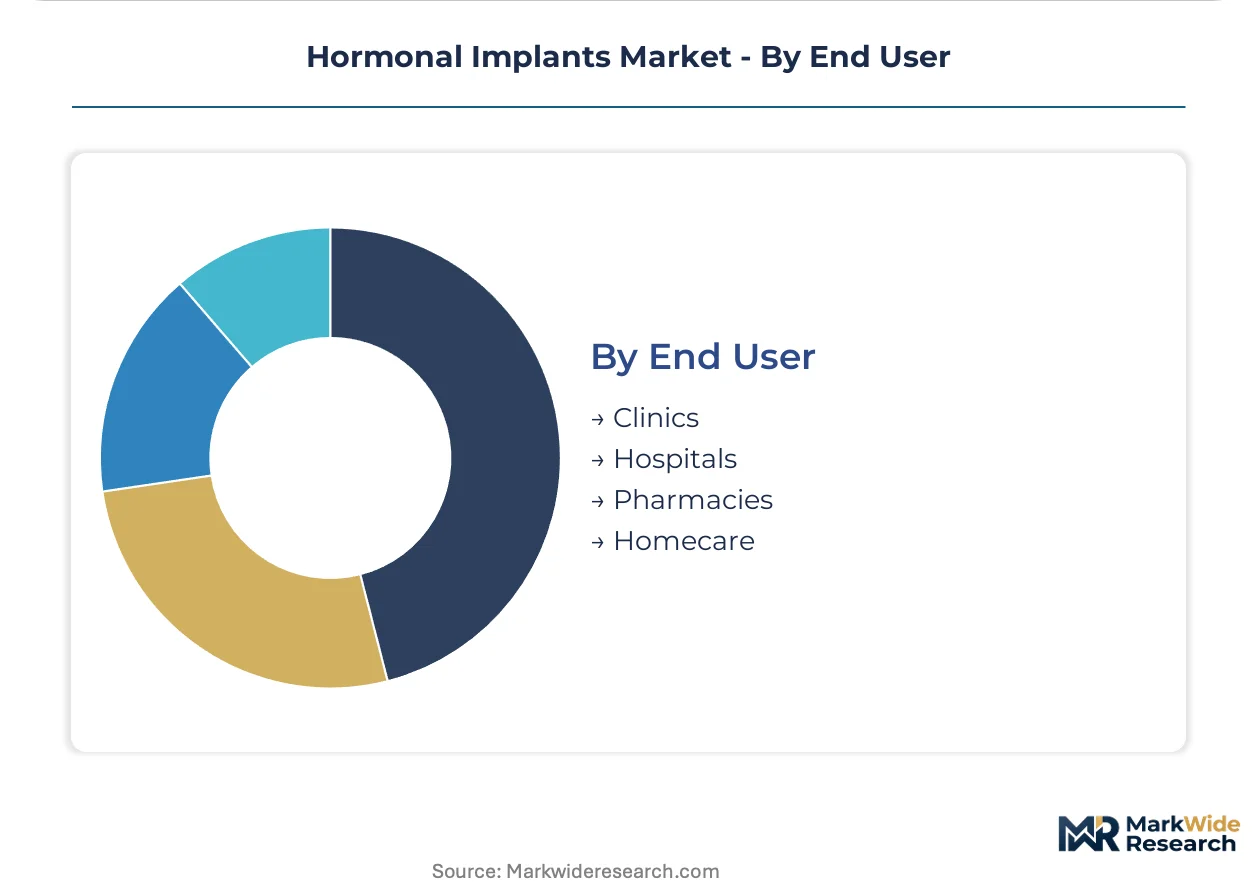
Segmentation in the hormonal implants market reflects divergent clinical workflows and reimbursement pathways. Procurement decisions split between outpatient clinic capacity for insertion procedures and hospital infrastructure for complex cases. Polymer matrix specifications and delivery mechanics further differentiate addressable patient populations across each segment.
Product Type:
Clinicians select implant formats based on insertion complexity, reversibility requirements, and follow-up access for removal procedures.
- Subdermal Implants:Single-rod etonogestrel systems release synthetic progestin through biocompatible silicone elastomer matrices over three-year durations. Demand concentrates in United States hospital outpatient departments scaling long-acting reversible contraceptive services under Medicaid managed care contracts.
- Intrauterine Devices:T-shaped polymer frames with steroid-eluting cores provide five-to-seven year contraception with localized hormone delivery. Germany's Federal Joint Committee reimbursement decisions favor these devices for cost-sensitive public health procurement over premium subdermal alternatives.
- Contraceptive Rods:Multi-capsule legacy formats using levonorgestrel remain in Brazil's SUS formulary for price-constrained municipal clinics.
- Vaginal Rings:Monthly replacement polymer rings offer patient-controlled hormone delivery without procedural insertion requirements.
Subdermal implants lead on scale; intrauterine devices lead on momentum in European cost-effectiveness frameworks.
Therapy Area:
Regulatory approval pathways and clinical trial endpoints vary substantially across reproductive health versus endocrine therapy applications.
- Contraception:Synthetic progestin release for ovulation suppression dominates volume through established FDA and EMA premarket notification frameworks. Brazil's SUS expansion and USAID procurement programs drive concentrated demand in public sector channels.
- Hormone Replacement:Estradiol-progestin combinations for perimenopausal symptom management are expanding fastest into clinic-direct distribution networks beyond traditional family planning settings.
- Menstrual Regulation:Progestin-only systems reduce heavy bleeding in patients with contraindications to estrogen therapy.
- Fertility Treatment:Controlled hormone release supports ovarian suppression protocols in assisted reproduction clinics.
Contraception leads on scale; hormone replacement leads on momentum in aging population demographics.
Delivery Mode:
Patient adherence profiles and healthcare access constraints determine route selection across urban and rural deployment contexts.
- Implantation:Subdermal rod insertion requires trained clinic capacity but eliminates daily compliance requirements. United States federally qualified health centers are scaling insertion training infrastructure to convert demand in underserved counties.
- Injection:Depot formulations offer quarterly administration without procedural infrastructure for device removal.
- Oral:Daily pill regimens remain accessible through pharmacy channels without clinical appointment requirements.
- Topical:Transdermal patches provide alternative for patients with gastrointestinal absorption variability.
Implantation leads on scale; injection leads on momentum in resource-limited settings.
End User:
Procurement authority and reimbursement mechanics fragment across institutional settings with distinct prior authorization workflows.
- Clinics:Hospital outpatient departments and federally qualified health centers anchor United States demand through direct manufacturer contracting. Organon and Bayer field teams serve these channels exclusively, bypassing wholesale pharmaceutical distribution.
- Hospitals:Inpatient departments handle complex cases with comorbidities requiring multidisciplinary management.
- Pharmacies:Retail channels distribute vaginal rings and prescription refills for non-procedural formats.
- Homecare:Self-administered topical and oral options serve patients with transportation barriers to clinical facilities.
Clinics lead on scale; hospitals lead on momentum in integrated health system consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as polymer substrate suppliers migrate toward jurisdictions with streamlined biocompatibility certification pathways. Cost-of-compliance gaps between FDA and EMA premarket frameworks are accelerating facility relocation decisions among contract manufacturers serving implantable device markets.
United States
Medicaid managed care organizations are mandating single-source contracting for long-acting contraceptives to simplify prior authorization workflows. FDA premarket notification requirements for biocompatible polymer substrates shape clinical trial endpoint standards. Hospital outpatient departments in Texas and Florida are scaling insertion training infrastructure to convert demand in underserved counties.
Germany
The Federal Joint Committee applies tightening cost-effectiveness thresholds for contraceptive coverage, pressuring net pricing for premium-tier devices. EMA MDR compliance harmonization accelerates device approval timelines across member states. Manufacturing clusters in North Rhine-Westphalia leverage polymer science expertise to sustain European supply dominance.
Brazil
The Unified Health System's municipal clinic expansion creates sustained volume commitments for implant manufacturers. ANVISA regulatory pathways align with WHO prequalification standards for public procurement eligibility. São Paulo's metropolitan health districts are redirecting procurement toward single-rod etonogestrel systems over legacy multi-capsule formats.
India
CDSCO oversight of etonogestrel API manufacturing concentrates in contract production facilities serving international markets. Export license volatility exposes supply chains to geopolitical friction in steroid sourcing. Gujarat and Maharashtra pharmaceutical clusters anchor active pharmaceutical ingredient production for global implant manufacturers.
China
NMPA biocompatibility standards for implantable polymer matrices extend preclinical timelines for novel substrate formulations. Domestic demand for long-acting contraceptive services expands through hospital outpatient department networks. Yangtze River Delta manufacturing hubs supply silicone elastomer components to multinational device manufacturers.
Hormonal Implants Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale polymer substrate production to meet clinic-direct procurement commitments. The vendor base concentrates around three strategic archetypes: vertically integrated pharmaceutical conglomerates with captive steroid synthesis capabilities, specialized women's health spin-offs with dedicated field sales infrastructure, and regional API suppliers serving contract manufacturing relationships. M&A activity and geographic licensing agreements represent the dominant competitive moves as players secure access to WHO prequalification pathways and national tender programs.
Among vertically integrated pharmaceutical conglomerates, Bayer AG and Merck & Co occupy positions reflecting polymer science expertise and North American supply chain anchoring respectively. Organon & Co exemplifies the women's health specialist archetype through clinic-direct distribution network development. Shanghai Dahua Pharmaceutical Co., Ltd. represents regional API manufacturing concentration serving international contract relationships.
| Leading Market Players |
|---|
| Merck & Co |
| Bayer AG |
| Pfizer |
| Organon & Co |
| Shanghai Dahua Pharmaceutical Co., Ltd. |
| Teva Pharmaceutical Industries |
| Viatris |
| Gedeon Richter Plc |
| HRA Pharma |
| Others |
Supply & Pricing Matrix
Biodegradable polymer matrix development is compressing explantation costs while concentrating manufacturing scale among silicone elastomer specialists with validated ISO 10993 certification pathways. This dual shift simultaneously reduces long-term liability exposure for public health programs and tightens supplier pricing power around biocompatibility-proven substrate formulations.
Pricing Analysis
Clinic-direct distribution margins bypass wholesale pharmaceutical markups entirely, compressing channel economics for manufacturers serving United States federally qualified health centers. Three-tier pricing structure across premium single-rod etonogestrel systems, standard intrauterine devices, and economy multi-capsule legacy formats reflects polymer sophistication and insertion training bundling. Pricing pressure stems from Germany's Federal Joint Committee tightening cost-effectiveness thresholds for contraceptive coverage. Municipal clinics in Brazil's SUS network exhibit highest price sensitivity; United States Medicaid managed care organizations show lowest sensitivity due to single-source contracting mandates.
Supply Chain Analysis
Specialized polymer chemist and biomedical engineer availability concentrates in North Rhine-Westphalia's manufacturing clusters and Yangtze River Delta silicone processing hubs. Etonogestrel API production draws from Gujarat and Maharashtra pharmaceutical corridors in India; silicone elastomer substrates feed from Chinese specialty chemical manufacturers. Single-source vulnerability persists in steroid active pharmaceutical ingredient supply due to export license concentration. Distribution runs through clinic-direct field teams serving hospital outpatient departments, displacing traditional wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hormonal implants market functions as a stable compounder anchored by recurring replacement cycles and expanding public health procurement commitments that sustain predictable volume trajectories.
For Market Incumbents: To counter copper IUD substitution in price-sensitive segments, Bayer AG and Organon should deepen backward integration into biocompatible polymer substrate production and secure EMA MDR certification ahead of notified body capacity constraints. Capacity addition in North Rhine-Westphalia manufacturing clusters reinforces supply security for European clinic-direct contracts. For New Entrants and Emerging Players: Rural health districts with uneven insertion training infrastructure represent the most penetrable buyer archetype for training-integrated product offerings. Menopausal hormone therapy applications beyond traditional family planning settings offer white-space expansion. WHO prequalification pathway investment unlocks UNFPA and USAID tender access in Sub-Saharan Africa procurement programs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional API suppliers with captive etonogestrel synthesis and established CDSCO oversight. Long-term viability framing centers on five-to-ten year replacement cycle visibility and clinic-direct channel control. The signal to watch is Brazil's SUS municipal procurement shifting decisively toward single-rod formats, indicating manufacturing scale requirements that favor consolidated players.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Investment | ISO 10993 cytotoxicity validation accelerates FDA premarket notification timelines for novel polymer substrates. |
| Clinic-Direct Distribution Expansion | Dedicated field teams serving United States federally qualified health centers displace wholesale pharmaceutical intermediaries. |
| Backward Integration into API Synthesis | Captive etonogestrel production insulates against Indian and Chinese export license volatility. |
| Digital Companion Development | Bluetooth-enabled release monitoring qualifies for FDA Breakthrough Device expedited review pathway. |
| WHO Prequalification Pathway | ANVISA-aligned regulatory dossiers unlock UNFPA tender eligibility for Sub-Saharan Africa procurement. |
Research Methodology
Multiple input streams — regulatory filing analysis, procurement database extraction, and clinical workflow observation — were reconciled across primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov endpoints, and CMS Medicare reimbursement schedules. Bottom-up volume modeling and top-down market sizing triangulation anchored value estimates.
Historical shipment data cross-referenced against panel input from polymer substrate suppliers and implant manufacturers shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type, therapy area, delivery mode, and end-user procurement authority. CAGRs derived from polynomial trend fitting applied to replacement cycle frequencies and public health program expansion trajectories. Etonogestrel API pricing indices and silicone elastomer raw material costs fed industry-specific forecast adjustments.
Inputs from FDA premarket notification databases and EMA MDR conformity assessment records were available through the study window; gaps in real-time clinic insertion capacity metrics introduce uncertainty bands around demand conversion assumptions. Forecasts reflect documented assumptions regarding reimbursement stability and polymer biocompatibility certification timelines. Material deviation in Brazil's SUS procurement volumes or Germany's Federal Joint Committee coverage decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Oxygenator Market