
 Digital Kiosk Display Market | 2026-2036
Digital Kiosk Display Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Kiosk Display Market Outlook
Quick-service restaurant operators are gaining share as the kiosk buyer base is bifurcating away from legacy banking deployers. NCR Voyix Corporation leverages its restaurant technology heritage to sustain dominance in food-service automation. Samsung Electronics Co., Ltd. anchors the display panel supply layer with captive OLED and LCD production. Diebold Nixdorf competes through branch transformation solutions that integrate teller-assist functions into interactive terminals.
Digital kiosk displays are integrated screen-and-compute assemblies engineered for unattended public operation, typically rated for continuous duty cycles and equipped with projected capacitive touch layers, optical bonding, and ambient light sensors to maintain readability under direct sunlight or dim interior conditions. Touchscreen kiosks lead unit shipments as retailers replace static menu boards with ordering terminals, while outdoor kiosks command premium pricing due to IP65 ingress protection and thermal management requirements that expand bill-of-materials cost. Cloud-based deployment is expanding fastest among mid-tier buyers seeking centralized content management without on-site server infrastructure.
The FCC's equipment authorization rules govern radio-enabled kiosk modules in the United States, while the EU's CE marking and RoHS restrictions shape material composition and electromagnetic compliance for European deployments. India's BIS certification mandates safety testing for imported electronic displays, creating a compliance checkpoint for foreign manufacturers targeting transit infrastructure tenders. Stakeholders must monitor how energy-efficiency regulations and data-privacy frameworks for biometric-enabled kiosks reshape product roadmaps and geographic prioritization.
Market Dynamics
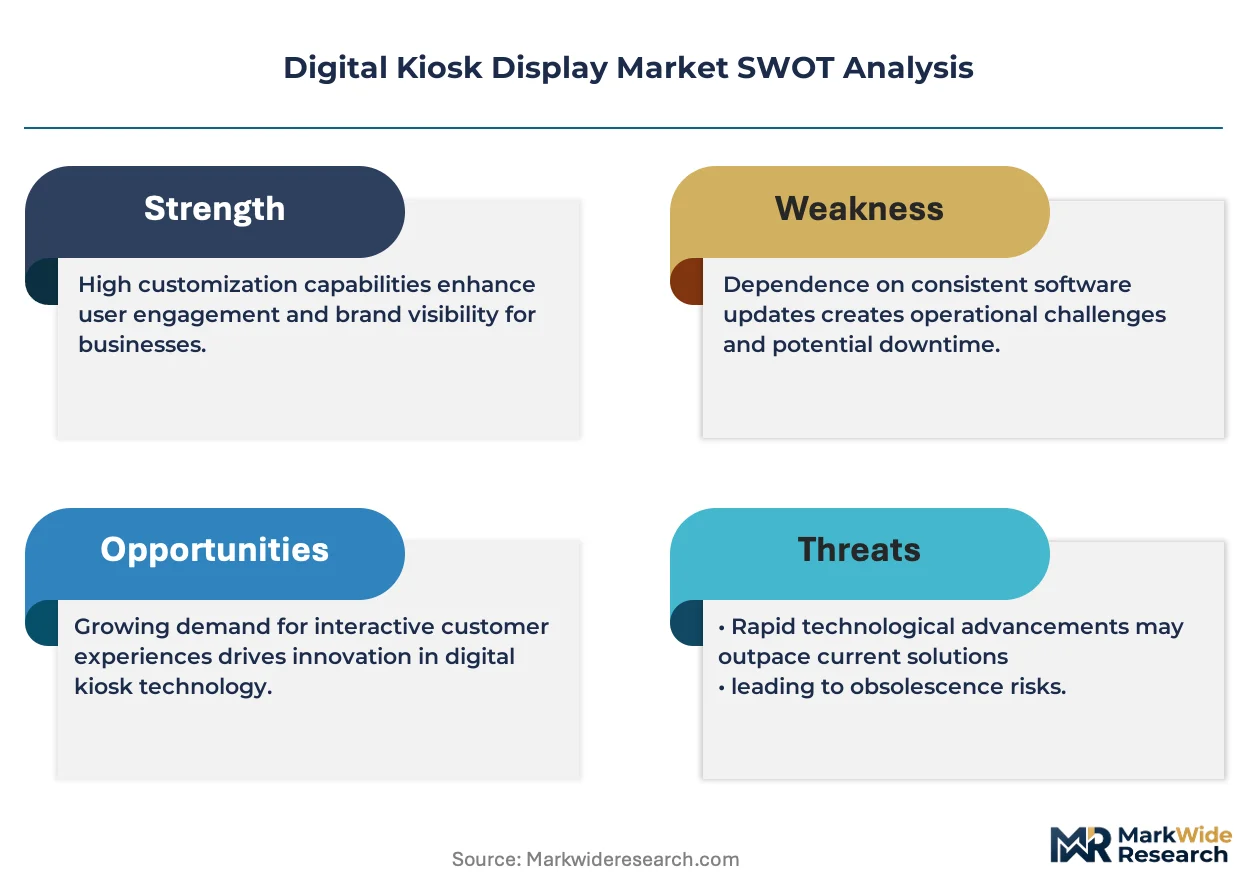
The EU's Ecodesign for Energy-related Products directive is compressing standby power tolerances for public displays, forcing manufacturers to redesign thermal architectures and power management subsystems ahead of compliance deadlines.
Growth Catalysts
- Transit Infrastructure Digitization:India's metro rail modernization and airport digitization projects are generating concentrated tender volumes for interactive wayfinding terminals. BIS certification requirements filter qualified suppliers.
- Quick-Service Restaurant Automation:Food-service operators are replacing static menu boards with self-ordering touchscreen kiosks, expanding deployment velocity across drive-thru and dine-in formats.
- Cloud-Based Content Management:Mid-tier retail buyers are adopting centralized SaaS deployment models, eliminating on-site server infrastructure and reducing total cost of ownership.
Market Restraints
- Display Panel Supply Concentration:Captive OLED and LCD production concentrates at Korean and Taiwanese foundries, creating allocation risk during semiconductor cycle tightness.
- Outdoor Ingress Protection Costs:IP65-rated enclosures and active thermal management expand bill-of-materials cost by 40-60% versus indoor equivalents, compressing margin at volume price points.
- FCC Equipment Authorization Friction:Radio-enabled kiosk modules face extended certification timelines for Wi-Fi and cellular variants, delaying North American deployment schedules.
Strategic Opportunities
- Biometric-Enabled Authentication:Convergence of facial recognition and payment tokenization creates white space in banking and healthcare verticals, pending GDPR and state-level privacy framework resolution.
- EU Green Deal Alignment:Ecodesign-compliant product lines qualify for public procurement preference in European transit and municipal deployments, rewarding early redesign investment.
- Self-Checkout Network Expansion:Grocery and big-box retailers are retrofitting legacy POS lanes with hybrid associate-assisted terminals, opening retrofit revenue streams.
Industry Challenges
- Optical Bonding Skill Scarcity:Projected capacitive touch layer lamination requires cleanroom-grade assembly capability that concentrates among tier-one contract manufacturers, constraining quality output.
- Legacy System Integration Complexity:Branch transformation solutions must interface with core banking platforms through middleware layers, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Kiosk Display Market |
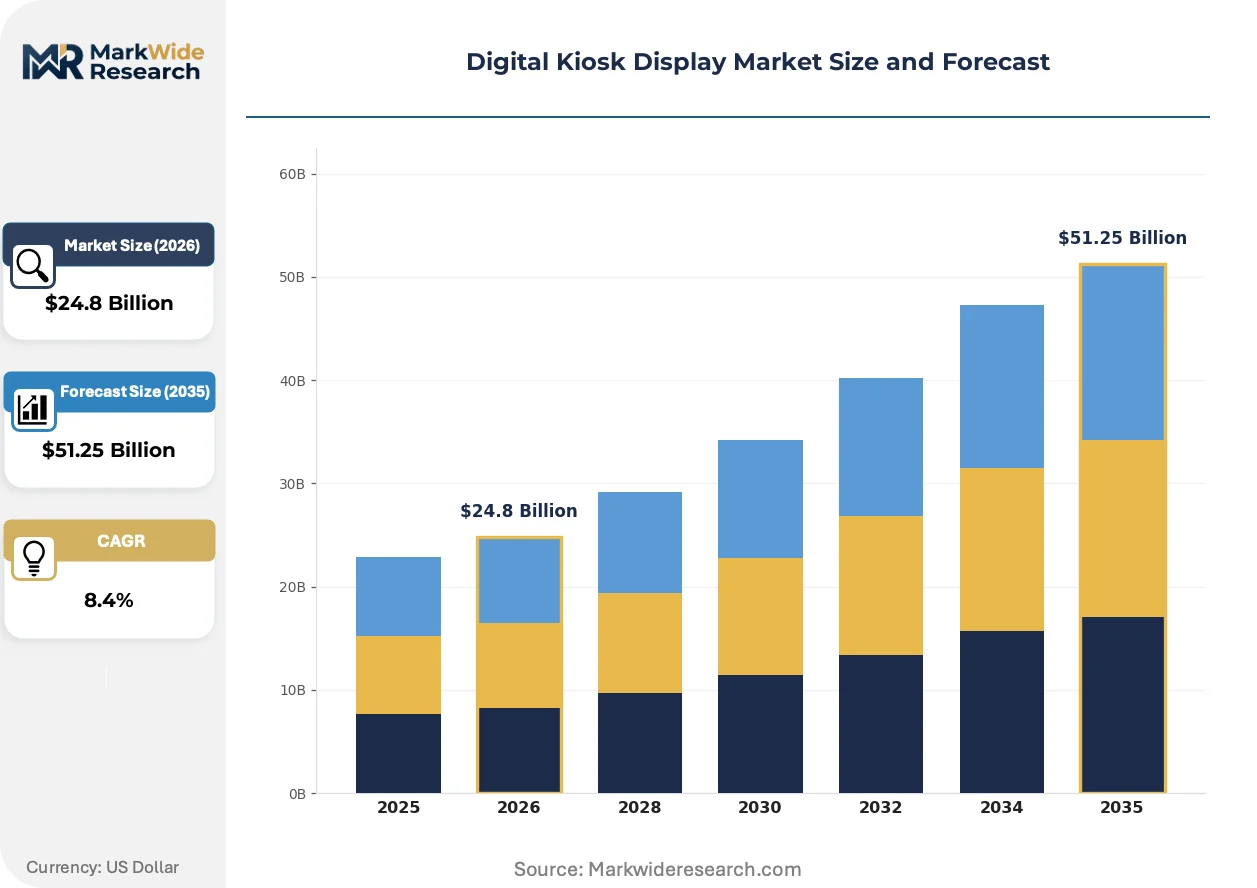
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Kiosks, Touchscreen Kiosks, Digital Signage, Interactive Displays Deployment: On-Premise, Cloud-Based, Hybrid, Self-Service End User: Retail Stores, Educational Institutions, Banks, Transportation Hubs Technology: LED, OLED, LCD, Projection, Plasma |
| Companies Covered | NCR Voyix Corporation, Diebold Nixdorf, KIOSK Information Systems, Advantech Co., Ltd., Samsung Electronics Co., Ltd., Zebra Technologies Corp., Meridian Kiosks, Glory Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Kiosk Display Market Strategic Shifts
Touchscreen kiosk architectures are fragmenting into modular compute-and-display subsystems, enabling faster hardware refresh cycles and software-defined feature activation without full terminal replacement.
Optical bonding is decomposing the traditional display-assembly value chain by eliminating air-gap touch layers and integrating ambient light sensors directly into bonded stacks. Quick-service restaurant chains are adopting these assemblies at 18-month refresh cadences. The technology is compressing field failure rates for sunlight-readable outdoor installations.
REACH substance restrictions are phasing cadmium and certain flame retardants from display component supply chains, forcing material requalification across European-bound product lines. Component suppliers are accelerating halogen-free PCB substrate adoption. Outdoor kiosk categories face the steepest compliance cost escalation due to thermal management material density.
Buyer concentration among multi-national retail chains is consolidating vendor qualification lists to three approved suppliers per region, displacing fragmented procurement through direct OEM relationships. After-sales service unbundling is emerging as a contract negotiation lever. This pattern is most visible in North American grocery self-checkout deployments.
Digital Kiosk Display Market Segmentation
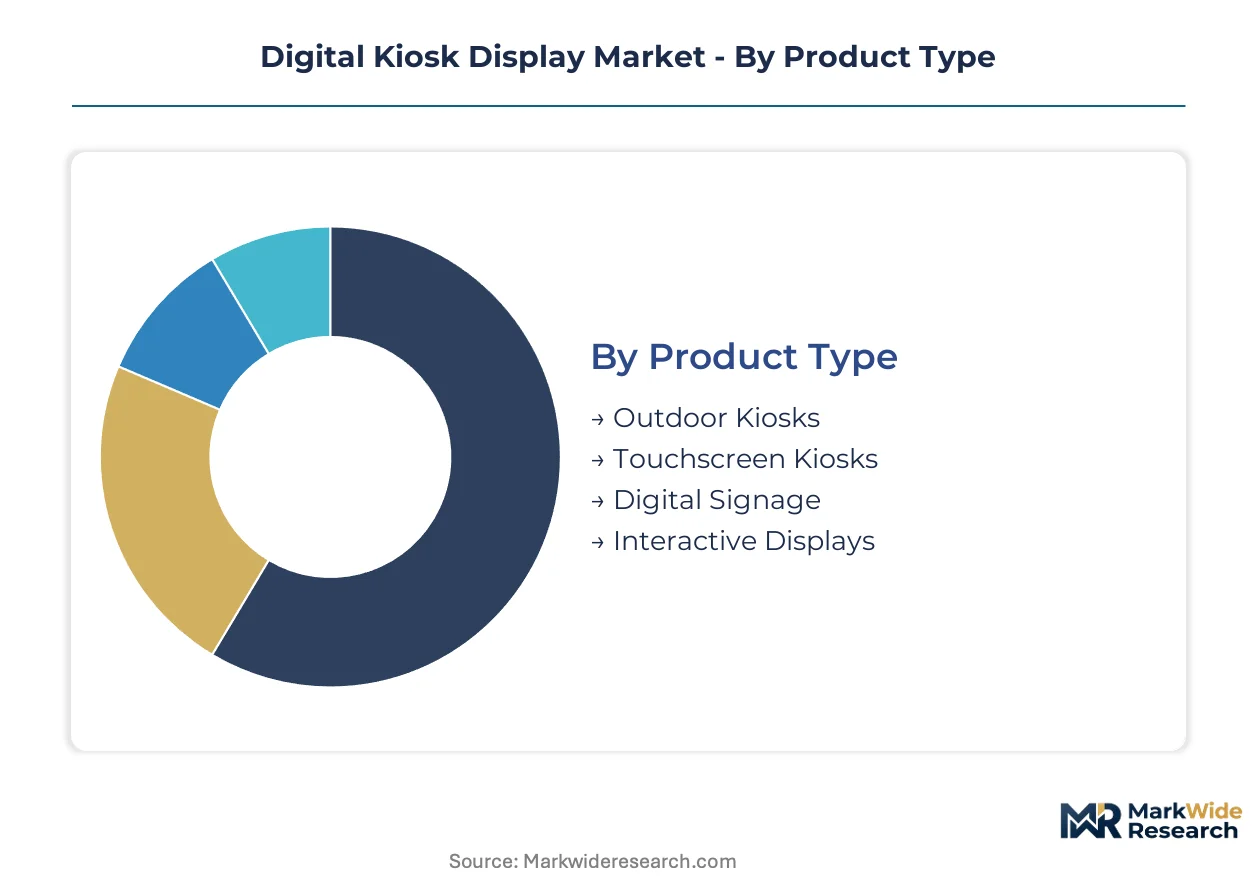
Digital kiosk display procurement patterns diverge sharply across deployment contexts, with regulatory compliance tiers and environmental rating requirements filtering supplier eligibility before price negotiations begin. Segmentation reveals how hardware specifications, connectivity architectures, and end-use durability demands create distinct vendor qualification pools.
Product Type:
IP ratings and thermal management thresholds separate compliant suppliers across outdoor and indoor deployment categories, with Ecodesign standby power limits applying differentially based on enclosure classification.
- Touchscreen Kiosks:Projected capacitive touch layers with optical bonding dominate quick-service restaurant deployments, where 18-month refresh cycles are standardizing. Retail self-checkout networks in North America and India are absorbing volume as static menu boards phase out.
- Outdoor Kiosks:IP65 ingress protection and active thermal management expand bill-of-materials cost substantially versus indoor equivalents. Transit infrastructure tenders in India and EU municipal deployments command premium pricing for sunlight-readable bonded stacks with integrated ambient light sensors.
- Digital Signage:Passive display assemblies without touch layers serve advertising and wayfinding applications in airports and shopping centers.
- Interactive Displays:Hybrid compute-and-screen subsystems support software-defined feature activation without full terminal replacement.
Touchscreen kiosks handle the majority of throughput; outdoor kiosks are climbing the fastest on share.
Deployment:
Total cost of ownership calculations favor cloud architectures for mid-tier buyers lacking on-site IT infrastructure, while regulated sectors mandate data residency through on-premise or hybrid stacks.
- Cloud-Based:Centralized SaaS content management eliminates server infrastructure for retail chains, though GDPR data localization requirements constrain European deployment architectures. Mid-tier grocery and hospitality buyers are adopting this model fastest.
- On-Premise:Air-gapped installations persist in banking branch transformation projects where core platform integration demands middleware layers extending deployment timelines. FCC equipment authorization for radio modules adds friction to North American schedules.
- Hybrid:Edge-compute with cloud synchronization balances latency-sensitive transactions against centralized analytics.
- Self-Service:Unattended operation protocols with remote monitoring capabilities serve transportation hub wayfinding and retail automation.
Cloud-based deployment is expanding most quickly; on-premise retains the largest installed base.
End User:
Procurement consolidation to three approved suppliers per region is most advanced in retail, while transportation infrastructure maintains open tender processes with BIS certification gates in India.
- Retail Stores:Grocery and big-box chains are retrofitting legacy POS lanes with hybrid associate-assisted terminals, opening retrofit revenue streams. Self-checkout network expansion is concentrating vendor relationships.
- Transportation Hubs:India's metro rail modernization and airport digitization projects generate concentrated tender volumes for interactive wayfinding terminals. BIS certification filters qualified suppliers.
- Banks:Branch transformation solutions integrate teller-assist functions into interactive terminals, requiring legacy core banking platform interfaces.
- Educational Institutions:Campus wayfinding and visitor management systems adopt lower-specification indoor kiosks with reduced durability requirements.
Retail stores command the largest procurement volume; transportation hubs show the steepest expansion trajectory.
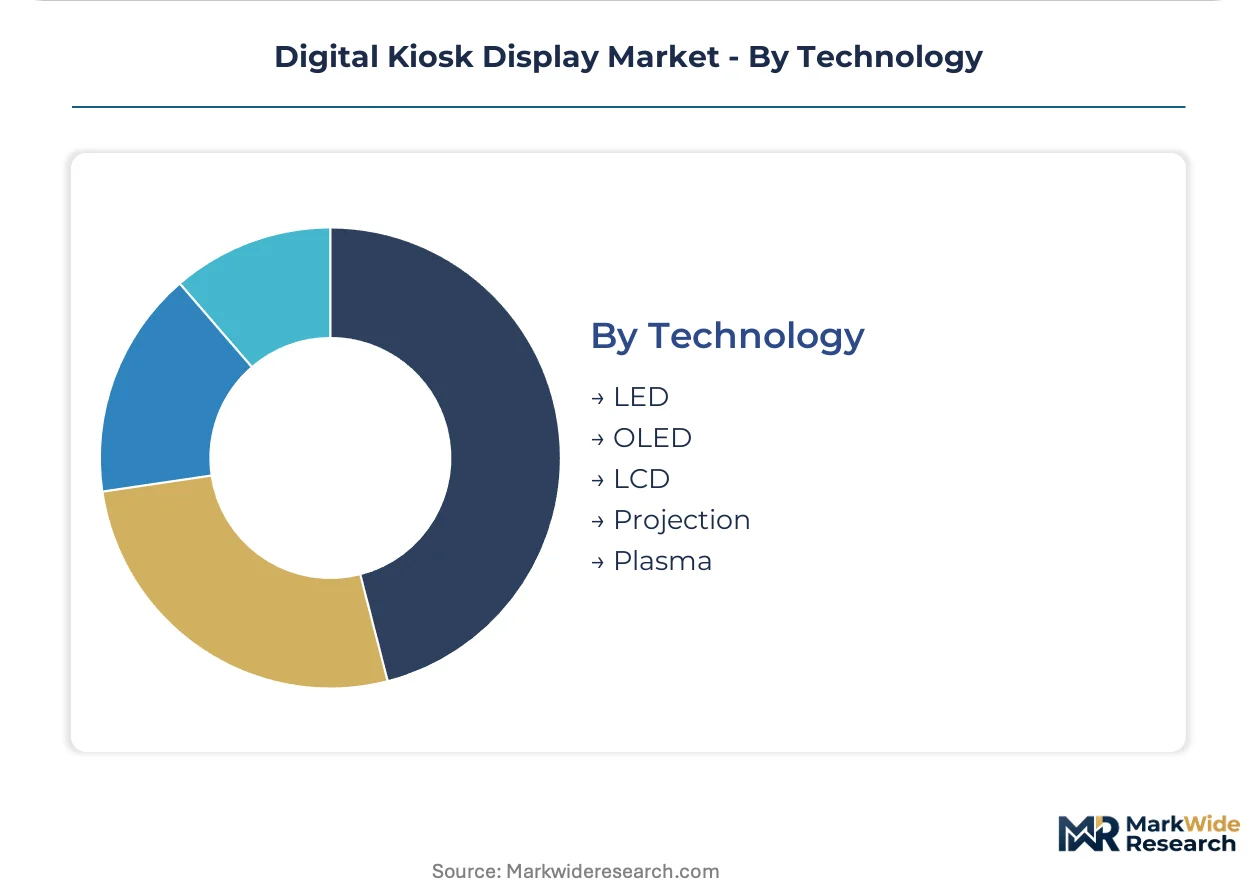
Technology:
Display panel supply concentrates at Korean and Taiwanese foundries, creating allocation risk during semiconductor cycle tightness across all backlight and emissive technologies.
- LCD:Mature TFT-LCD production with LED backlighting dominates cost-sensitive indoor deployments. Supply concentrates among vertically integrated panel manufacturers with captive glass and driver IC production.
- OLED:Self-emissive stacks enable thinner enclosures and superior contrast for premium indoor installations. Samsung Electronics anchors supply through captive production, constraining third-party availability.
- LED:Direct-view LED walls serve large-format outdoor advertising with modular tile architectures.
- Projection:Short-throw laser projection enables temporary or spatially constrained installations without permanent display hardware.
- Plasma:Legacy phosphor technology persists in limited industrial applications with specific burn-in resistance requirements.
LCD retains dominant share; OLED is gaining ground fastest in premium indoor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi Metro's Phase IV expansion and the Mumbai-Ahmedabad high-speed rail corridor anchor South Asia's transit infrastructure digitization, generating concentrated tender volumes for interactive wayfinding terminals. These projects filter qualified suppliers through certification gates and environmental rating requirements.
United States
Quick-service restaurant chains are retrofitting drive-thru and dine-in locations with self-ordering touchscreen terminals at 18-month refresh cycles. The FCC's equipment authorization rules govern radio-enabled kiosk modules, extending certification timelines for Wi-Fi and cellular variants. Deployment concentrates in the Dallas-Fort Worth metroplex and greater Atlanta, where franchise density supports volume procurement.
India
Metro rail modernization in Delhi, Mumbai, and Bangalore generates tender volumes for interactive wayfinding terminals with sunlight-readable bonded stacks. BIS certification mandates safety testing for imported electronic displays, creating a compliance checkpoint for foreign manufacturers. The Delhi-Mumbai Industrial Corridor clusters deployment around airport digitization projects in Hyderabad and Chennai.
Germany
EU Green Deal procurement preferences reward Ecodesign-compliant product lines in municipal transit deployments. The REACH regulation phases cadmium and certain flame retardants from display component supply chains, forcing material requalification. Industrial concentration sits with Bavaria's electronics manufacturing corridor and Berlin-Brandenburg's smart city pilot zones.
Japan
METI standards shape electromagnetic compliance and energy-efficiency benchmarks for public display installations. Railway operators in the Tokyo-Osaka corridor deploy hybrid associate-assisted terminals for station wayfinding and retail automation. The Kansai region's manufacturing base supplies optical bonding and projected capacitive touch layer lamination for premium indoor segments.
South Korea
Captive OLED production anchors display panel supply for thin-enclosure premium installations. The Seoul Capital Area's quick-service restaurant density drives self-checkout network expansion with centralized SaaS content management. Busan-Ulsan's port infrastructure supports component import for re-export to Southeast Asian transit projects.
Digital Kiosk Display Market Competitive Environment
Concentration sits with vertically integrated display panel manufacturers and specialized kiosk system integrators. The vendor base organizes around three strategic archetypes: captive display producers, restaurant technology heritage players, and branch transformation solution providers. Competitive moves center on modular compute-and-display subsystem development and cloud-based deployment architecture licensing.
Within the restaurant technology tier, NCR Voyix Corporation exemplifies food-service automation positioning. Samsung Electronics Co., Ltd. anchors the captive display production archetype through OLED and LCD supply control. Diebold Nixdorf occupies a position within the branch transformation solution segment, representing legacy banking deployer adaptation to interactive terminal integration.
| Leading Market Players |
|---|
| NCR Voyix Corporation |
| Diebold Nixdorf |
| KIOSK Information Systems |
| Advantech Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Zebra Technologies Corp. |
| Meridian Kiosks |
| Glory Ltd. |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
BIS certification for India's metro rail tenders gates both supplier qualification and price differentiation simultaneously, forcing foreign manufacturers to absorb compliance costs that tier pricing across certified and non-certified product lines. The interaction between regulatory gates and supply chain concentration creates premium capture for early certifiers while compressing margins for late entrants facing redundant testing cycles.
Pricing Analysis
Volume-discount tiering structures stratify across premium outdoor kiosks, standard indoor touchscreen terminals, and economy digital signage assemblies. Price differentiation hinges on IP65 ingress certification and optical bonding quality grades, with Ecodesign compliance adding a secondary tier. Cost compression in standard indoor segments is intensifying because of captive LCD oversupply from Korean foundries. Mid-tier retail chains exhibit highest price sensitivity, while transit infrastructure buyers prioritize certification over unit cost.
Supply Chain Analysis
Inventory lead times for projected capacitive touch controllers stretch during semiconductor cycle tightness, constraining output at tier-one contract manufacturers. Panel supply draws from South Korea, Taiwan, and Japan, with driver IC fabrication tethered to Taiwanese foundries. Optical bonding equipment and halogen-free PCB substrates represent critical input dependencies. Single-source vulnerability concentrates in OLED stack production. Distribution runs through direct OEM relationships with multinational retail chains and open tender processes for transit infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile payment-enabled smartphones pose a direct substitution threat to self-service kiosk deployments, forcing incumbents to defend installed base through software-defined feature expansion and biometric authentication integration.
For Market Incumbents: Consolidate vendor qualification relationships with India's metro rail authorities before BIS certification backlogs lengthen. Deepen captive supply of optical bonding capacity to offset cleanroom-grade assembly scarcity. Defend against cloud-based SaaS entrants by embedding edge-compute hardware with subscription-locked feature activation. For New Entrants and Emerging Players: BIS certification fast-tracks for Hyderabad and Chennai airport digitization projects open white-space penetration before incumbent renewal cycles. Target India's transportation hub segment where procurement maintains open tender processes rather than consolidated vendor lists. Pursue modular compute-and-display subsystem licensing to bypass full terminal development costs. For Investors and Strategic Acquirers: EU Ecodesign standby power deadlines reshape the acquisition landscape toward compliant product lines qualifying for Green Deal procurement preference. Five-to-ten year viability favors vertically integrated panel producers with captive OLED and in-house thermal management design. Watch for biometric-enabled authentication regulatory resolution as GDPR and state-level privacy framework clarity signals inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Compute-and-Display Subsystem Development | Enables 18-month hardware refresh cycles without full terminal replacement for quick-service restaurant chains. |
| Cloud-Based Deployment Architecture Licensing | Captures mid-tier retail buyers seeking centralized SaaS content management without on-site infrastructure. |
| Biometric Authentication Integration | Creates banking and healthcare vertical entry pending GDPR and state-level privacy framework resolution. |
| Ecodesign Compliance Product Line Redesign | Qualifies for EU Green Deal procurement preference in municipal transit and European deployments. |
| Optical Bonding Capacity Expansion | Addresses cleanroom-grade assembly scarcity constraining quality output for sunlight-readable outdoor installations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, EU Ecodesign directive compliance registries, and Indian BIS certification records. Primary interviews engaged kiosk system integrators, display panel procurement directors at quick-service restaurant chains, transit authority tender evaluation committees, and optical bonding contract manufacturing managers. Secondary validation drew from SEC filings of publicly traded restaurant technology providers, customs import data for display panel trade flows, and metro rail project tender announcements. Bottom-up unit shipment estimates triangulated against top-down value projections across deployment categories.
Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and display technology across the analysis window. CAGRs derived from regression analysis of historical tender volumes and procurement cycle timing. Industry-specific forecast inputs incorporated refresh cycle compression in food-service automation and BIS certification pipeline velocity for Indian infrastructure.
Underlying assumptions cover regulatory compliance deadline adherence and semiconductor cycle normalization, with deviation risk concentrated in biometric privacy framework delays and display panel allocation shocks. Forecasts reflect these conditions without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Display Panel Market
Display Technologies
Foldable Display Market
Display Technologies
Global OLED Market
Display Technologies
Commercial Display Market
Display Technologies
IGZO Display Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Laptop Panels Market
Display Technologies
Portable Video Wall Market
Display Technologies
Computer Monitor Market
Display Technologies
Interactive Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
QLED Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Quantum Dot Display Market