
 Display Mask Market | 2026-2036
Display Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Display Mask Market Insights
EU REACH is rebalancing the cost-of-entry calculus for European mask suppliers by mandating stricter documentation for chromium-based etching chemistries. Hoya Corporation leverages its captive quartz substrate production to sustain margin control across high-NA photomask tiers. Toppan Photomasks, Inc. anchors its competitive stance through deep EUV blank partnerships with lithography equipment makers in Japan and the Netherlands.
Display masks are high-precision quartz or glass substrates patterned with chrome or molybdenum-silicide absorber layers, serving as master templates for photolithographic transfer of circuit geometries onto display backplanes. These components achieve pattern fidelity below 1.5 micrometer critical dimension across substrates exceeding 1.5 meters for Gen 10.5 panel lines. OLED mask variants command premium positioning due to fine-pixel patterning requirements for mobile and television applications, while LCD mask demand matures amid panel fab consolidation. Active matrix technology segments absorb the bulk of R&D investment as manufacturers chase higher refresh rates and variable refresh implementations.
FDA device-grade standards and EPA hazardous waste rules shape mask requalification protocols for medical display applications in the United States. Japan's METI subsidizes domestic mask blank development through its semiconductor revitalization framework, reinforcing supply security for advanced node production. South Korea's MFDS and K-Battery initiatives indirectly channel mask demand through display-panel-to-EV supply chain integration. Stakeholders must monitor which regulatory jurisdiction first mandates perfluorinated compound disclosure in mask cleaning operations, as this will cascade through supplier qualification timelines.
Market Dynamics
Photomask procurement for Gen 10.5 OLED lines is concentrating demand among three substrate suppliers, compressing lead times and amplifying price volatility for quartz blanks. Taiwan Semiconductor Manufacturing Company and Samsung Display are locking multi-year contracts, freezing out mid-tier panel makers.
Growth Catalysts
- Advanced OLED pixel architectures:Mobile and television manufacturers are driving mask resolution requirements below 1.5 micrometer critical dimension, pulling investment into high-NA patterning infrastructure.
- EU F-Gas Regulation phase-down:The fluorinated gas restrictions are accelerating adoption of dry etching alternatives for chrome absorber processing, opening equipment upgrade cycles.
- Hefei-Chengdu display cluster expansion:China's domestic foundry buildouts are generating captive demand for large-area photomasks, reducing import dependency.
Market Restraints
- Quartz substrate supply concentration:Synthetic fused silica production centers on Japanese and German specialty glassmakers, exposing mask fabricators to single-source risk.
- Chromium compound handling costs:REACH substance restrictions in Europe are mandating closed-loop etching chemistry recovery, adding fixed cost layers to mask requalification.
- EUV blank technical limitation:Defect density at the multilayer mirror interface remains above commercial thresholds for display-scale substrates, delaying next-node adoption.
Strategic Opportunities
- Medical display certification pathways:FDA device-grade standards for diagnostic imaging panels are creating premium mask tiers with extended requalification cycles and higher unit economics.
- Automotive-grade AMOLED integration:South Korea's K-Battery initiative is channeling display-panel-to-EV supply chain linkages, opening dedicated mask qualification tracks for in-cabin screens.
- Molybdenum-silicide absorber convergence:The transition from chrome to MoSi multilayer stacks is enabling thinner absorber profiles and improved line-edge roughness for sub-micron features.
Industry Challenges
- EUV lithography talent scarcity:The specialized skill set for high-NA mask design and defect review is concentrated among retiring cohorts in Japan and the Netherlands.
- Multi-generational fab equipment integration:Gen 8.5 and Gen 10.5 lines require mask qualification across incompatible stepper generations, fragmenting process development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Mask Market |
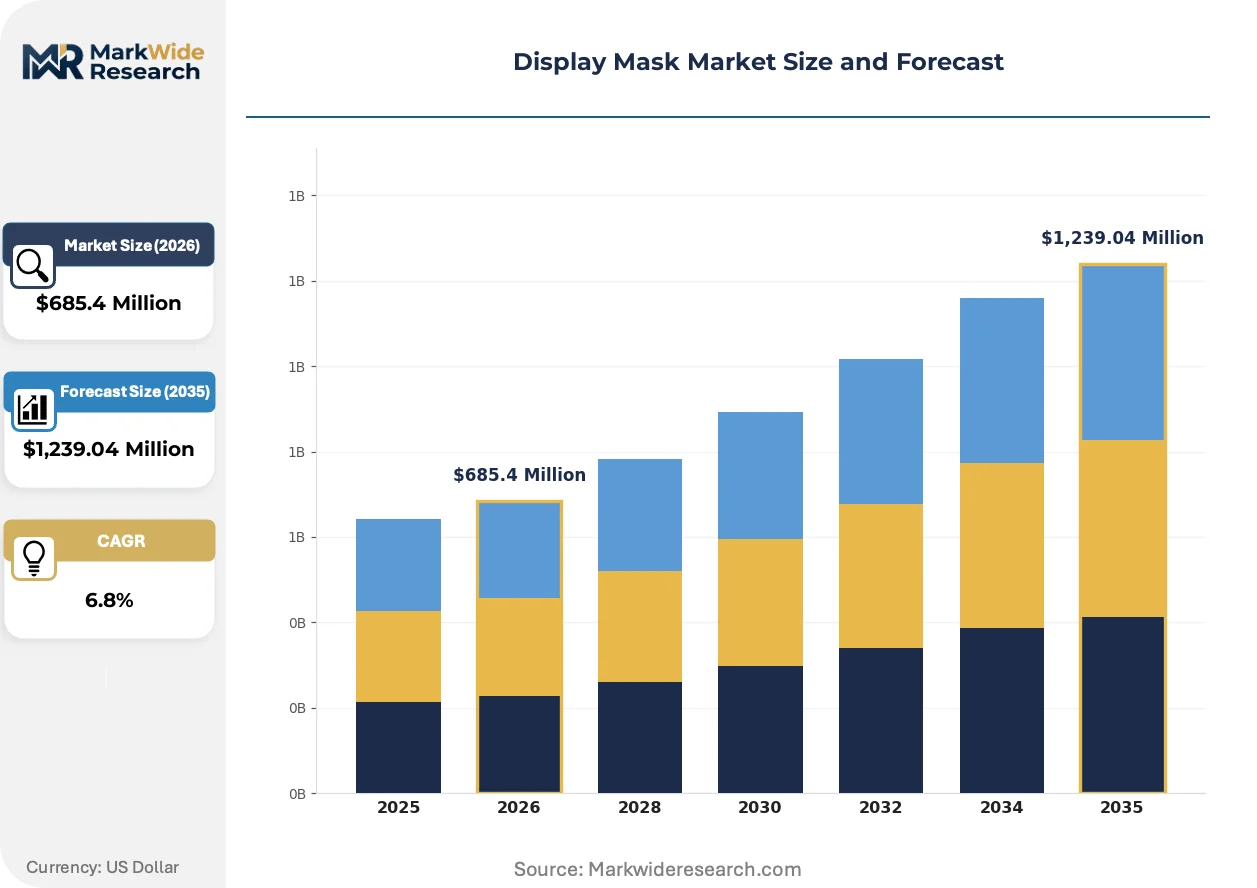
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Masks, OLED Masks, LED Masks, QLED Masks End User: Consumer Electronics, Automotive, Industrial, Medical Size: Small, Medium, Large, Extra Large Technology: Passive Matrix, Active Matrix, Quantum Dot, MicroLED |
| Companies Covered | Dai Nippon Printing Co., Ltd., Hoya Corporation, LG Innotek, SK-Electronics Co., Ltd., Samsung Display Co., Ltd., Darwin Microelectronic Co., Ltd., Photronics Inc., Taiwan Mask Corporation, Toppan Photomasks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Mask Market Trends and Innovations
Pattern fidelity requirements for variable refresh rate implementations are compressing mask design cycles and forcing convergence between semiconductor and display lithography toolchains. Equipment makers are responding with unified metrology platforms.
Computational lithography is converging with machine-learning defect prediction to enable real-time mask error correction during exposure. Panel makers in Taiwan and South Korea are deploying these hybrid systems for Gen 8.6 OLED lines. The structural consequence is collapsing the traditional separation between mask data preparation and final inspection, compressing supplier qualification timelines.
Japan's METI semiconductor revitalization framework is subsidizing domestic mask blank development to reduce import exposure for advanced node production. The industrial consequence is accelerating quartz substrate purification investments in Hokkaido and Kyushu. Display mask segments are capturing spillover technology from logic device photomask programs, shortening development cycles for mobile OLED applications.
Buyer concentration among mega-panel fabs is consolidating procurement authority and unbundling after-sales service from equipment contracts. Taiwanese and Korean display makers are negotiating direct mask blank supply agreements, bypassing traditional photomask house intermediaries. This disintermediation is most visible in the Gen 10.5 segment, where substrate dimensions exceed standard shipping logistics and favor localized fabrication partnerships.
Display Mask Market Segmentation
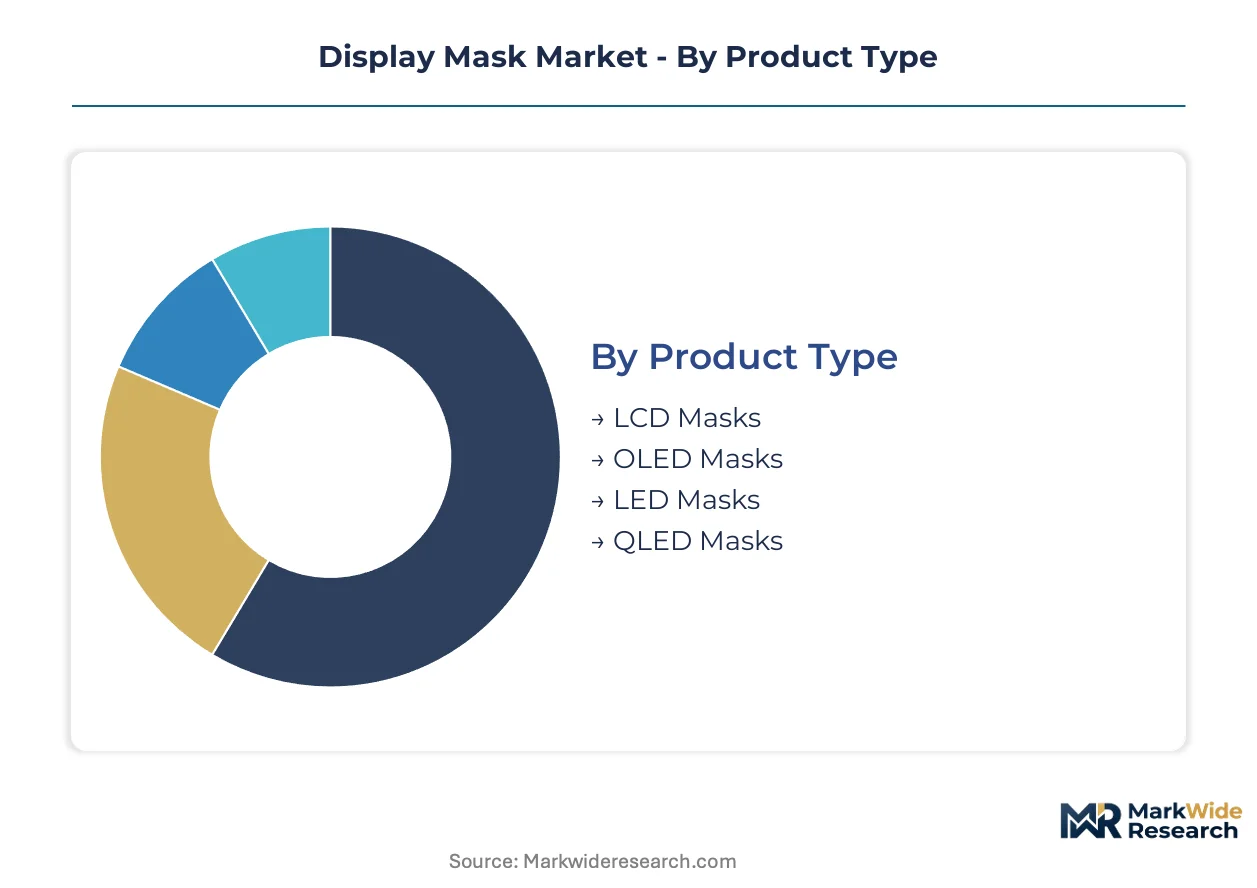
Display mask procurement patterns diverge sharply across panel generation lines and pixel architectures, with substrate dimensions and absorber material specifications dictating supplier qualification tiers. Understanding how demand fragments across these technical boundaries clarifies where fabrication capacity investments concentrate.
Product Type:
Integration depth varies by emissive technology, with standalone mask sets for OLED and QLED lines commanding dedicated process development versus LCD masks embedded in mature supply chains.
- OLED Masks:These multilayer chrome or molybdenum-silicide absorber patterns achieve sub-1.5 micrometer critical dimensions for mobile and television backplanes. Taiwan Semiconductor Manufacturing Company and Samsung Display are locking multi-year procurement contracts for Gen 10.5 lines, freezing out mid-tier panel makers from substrate allocation.
- LCD Masks:Amorphous silicon and IGZO backplane patterns on large-area quartz substrates serve maturing television and monitor production. Demand concentrates in China's Hefei-Chengdu cluster as domestic foundry buildouts reduce import dependency for Gen 8.5 and Gen 10.5 capacity expansions.
- LED Masks:Direct-view LED display backplane patterns for commercial signage and cinema screens.
- QLED Masks:Quantum dot color conversion layer patterns bridging LCD and emissive display architectures.
Volume placements concentrate in LCD Masks; the faster expansion belongs to OLED Masks.
End User:
Cost tier stratification separates medical and automotive qualification tracks from high-volume consumer electronics procurement, with certification overhead determining margin capture.
- Consumer Electronics:Smartphones, tablets, and television panels absorb the majority of mask volume through Gen 6 to Gen 10.5 fabrication lines. South Korea's display-panel-to-EV supply chain integration is indirectly channeling mask demand through Samsung Display's captive requirements.
- Medical:FDA device-grade diagnostic imaging panels impose extended requalification cycles and premium unit economics. EPA hazardous waste rules shape mask requalification protocols, creating dedicated supplier tiers with documented chromium compound handling compliance.
- Automotive:In-cabin AMOLED displays for instrument clusters and infotainment systems.
- Industrial:HMI panels and specialized monitoring equipment with extended temperature range specifications.
Consumer Electronics absorbs dominant volume share; Medical commands the steepest expansion trajectory in value terms.
Size:
Application footprint determines shipping logistics constraints and localized fabrication partnerships, with extra-large substrates exceeding standard freight dimensions.
- Large:Gen 8.5 and Gen 8.6 substrates for television and monitor production, where pattern fidelity requirements for variable refresh rate implementations compress mask design cycles. Taiwan and South Korean panel makers deploy hybrid machine-learning defect prediction systems for these lines.
- Extra Large:Gen 10.5 substrates exceeding 1.5 meters dimensionally, requiring specialized shipping logistics and favoring localized fabrication partnerships. Taiwanese and Korean display makers negotiate direct mask blank supply agreements, bypassing traditional photomask house intermediaries.
- Small:Mobile and wearable device substrates with fine-pixel patterning requirements.
- Medium:Tablet and small-format monitor production.
Large size dominates current procurement volumes; Extra Large is climbing the fastest as Gen 10.5 lines ramp.
Technology:
Supply concentration for high-NA patterning infrastructure separates active matrix investment tiers from passive matrix legacy production.
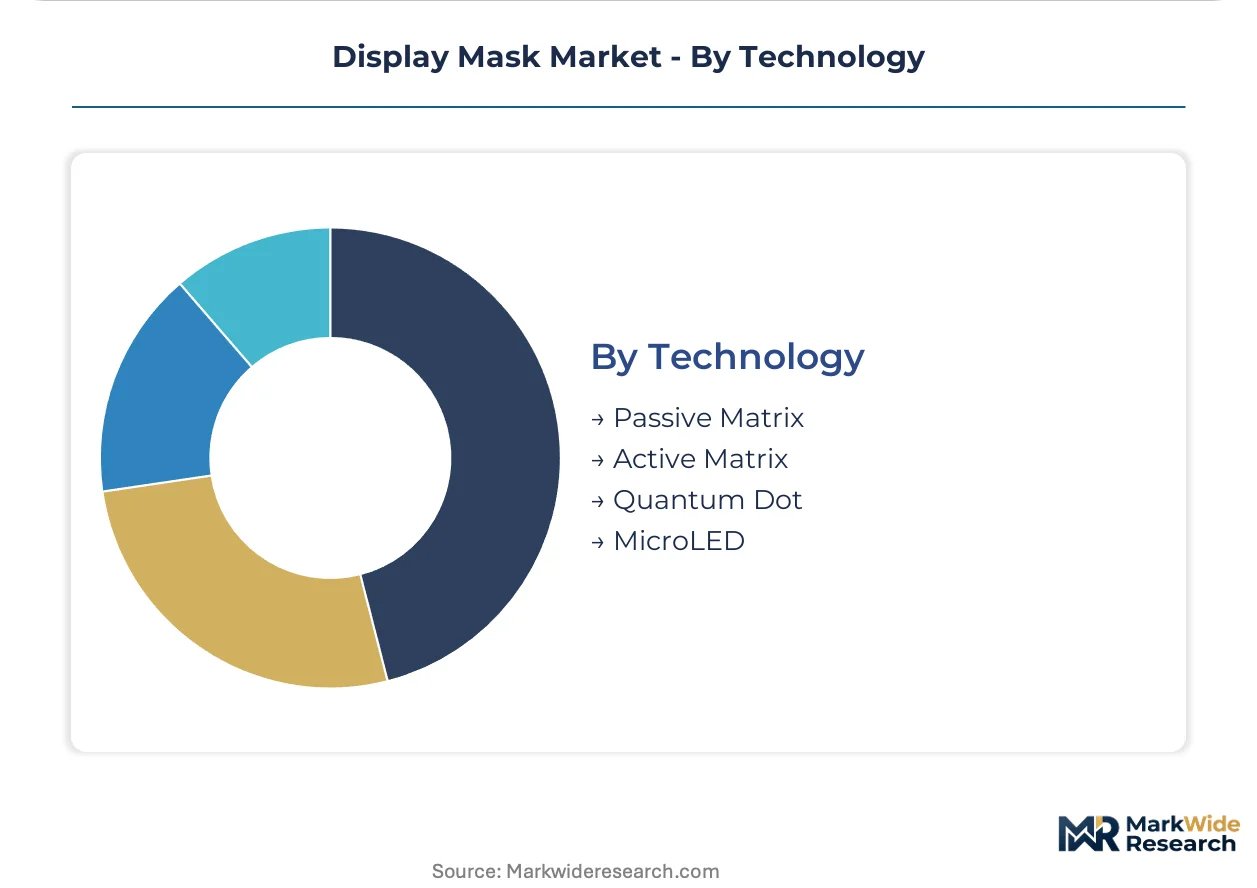
- Active Matrix:TFT backplane architectures for OLED and advanced LCD implementations absorb the bulk of R&D investment as manufacturers chase higher refresh rates. Japan's METI subsidizes domestic mask blank development through its semiconductor revitalization framework, reinforcing supply security for these advanced node requirements.
- MicroLED:Chiplet transfer and mass transfer patterning for next-generation emissive displays, where defect density at the multilayer mirror interface remains above commercial thresholds for display-scale substrates.
- Passive Matrix:Simpler addressing schemes for cost-constrained signage and indicator applications.
- Quantum Dot:Color conversion layer patterning bridging current LCD infrastructure with emissive performance targets.
Active Matrix holds dominant placement volume; MicroLED represents the most speculative upside contingent on EUV blank technical resolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photomask procurement concentrates in East Asian fabrication clusters where Gen 10.5 OLED lines are ramping. Taiwan, South Korea, and China absorb the majority of substrate allocation through multi-year supply contracts.
Taiwan
Semiconductor fabrication facilities are expanding photomask procurement for advanced OLED panel production. The Industrial Development Bureau under the Ministry of Economic Affairs coordinates domestic supply chain reinforcement initiatives. Hsinchu Science Park anchors concentrated mask blank demand from integrated display foundry operations.
South Korea
Samsung Display and captive suppliers are locking multi-year contracts for large-area photomasks, freezing out mid-tier panel makers. The Ministry of Food and Drug Safety and K-Battery initiatives indirectly channel mask demand through display-panel-to-EV supply chain integration. Gyeonggi Province hosts the primary concentration of Gen 8.6 and Gen 10.5 mask qualification activity.
China
Domestic display foundry buildouts in Hefei and Chengdu are generating captive demand for large-area photomasks, reducing import dependency. The Ministry of Industry and Information Technology supervises standards alignment for advanced node mask production under national semiconductor self-sufficiency programs. The Yangtze River Delta and Sichuan-Chongqing economic zones concentrate new substrate purification investments.
Japan
Synthetic fused silica production centers on specialty glassmakers in Hokkaido and Kyushu, exposing mask fabricators to single-source risk. METI subsidizes domestic mask blank development through its semiconductor revitalization framework, reinforcing supply security for advanced node production. The Tohoku region maintains concentrated quartz substrate purification capacity serving both logic and display photomask segments.
Germany
REACH substance restrictions are tightening chromium compound handling requirements for mask etching operations, mandating closed-loop chemistry recovery. The Federal Environment Agency enforces industrial emissions standards affecting mask requalification protocols. Saxony and Bavaria host precision optics clusters where EUV blank development intersects with display-scale substrate research.
Display Mask Market Competitive Landscape
Japanese producers anchor the premium substrate tier; Taiwanese and Korean specialists hold volume fabrication positions. The vendor base separates into three tiers based on captive quartz supply, EUV blank partnerships, and foundry-scale qualification capacity. Strategic archetypes include integrated substrate-to-mask houses, independent photomask service providers, and captive display-maker operations. Capacity expansion and direct blank supply agreements represent the dominant competitive vectors as procurement authority consolidates.
Among Japanese fabricators, Hoya Corporation and Toppan Photomasks, Inc. exemplify the integrated archetype through upstream quartz control and lithography equipment partnerships. Photronics Inc. represents the independent service model with geographic diversification across multiple fabrication nodes. These three anchors illustrate how supply security and technical depth determine positioning as Gen 10.5 procurement concentrates.
| Leading Market Players |
|---|
| Dai Nippon Printing Co., Ltd. |
| Hoya Corporation |
| LG Innotek |
| SK-Electronics Co., Ltd. |
| Samsung Display Co., Ltd. |
| Darwin Microelectronic Co., Ltd. |
| Photronics Inc. |
| Taiwan Mask Corporation |
| Toppan Photomasks, Inc. |
| Others |
Pricing and Supply Chain Analysis
EUV lithography talent concentration in Japan and the Netherlands generates labor-cost differentials that widen pricing-tier spreads between premium mask blanks and standard-grade alternatives. Skilled mask design engineers command compensation premiums that cascade into final substrate quotations, compressing margins for mid-tier fabricators unable to amortize specialist overhead across high-volume contracts.
Pricing Analysis
Volume placements concentrate in LCD masks with compressed unit economics, while OLED mask variants capture margin premiums through fine-pixel certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA device-grade diagnostic imaging tiers from consumer electronics procurement, with chromium compound handling compliance under REACH adding fixed-cost layers to European quotations. Price differentiation hinges on absorber material specification and substrate dimensional class. Mid-tier panel makers exhibit acute price sensitivity as multi-year contracts by Samsung Display and Taiwan Semiconductor Manufacturing Company freeze substrate allocation.
Supply Chain Analysis
Dual-sourcing mandates from Taiwanese and Korean display makers require mask blank qualification across Japanese and German synthetic fused silica suppliers, fragmenting procurement authority. Geographic supply concentration centers on Japan, Germany, and China for quartz substrate purification, with Hokkaido and Kyushu facilities anchoring premium-grade output. Raw material dependencies encompass synthetic fused silica, chrome and molybdenum-silicide absorber metals, and high-purity etching chemistries. Single-source vulnerability persists for Gen 10.5 substrate dimensions exceeding standard freight logistics. Distribution runs through direct blank supply agreements that bypass traditional photomask house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
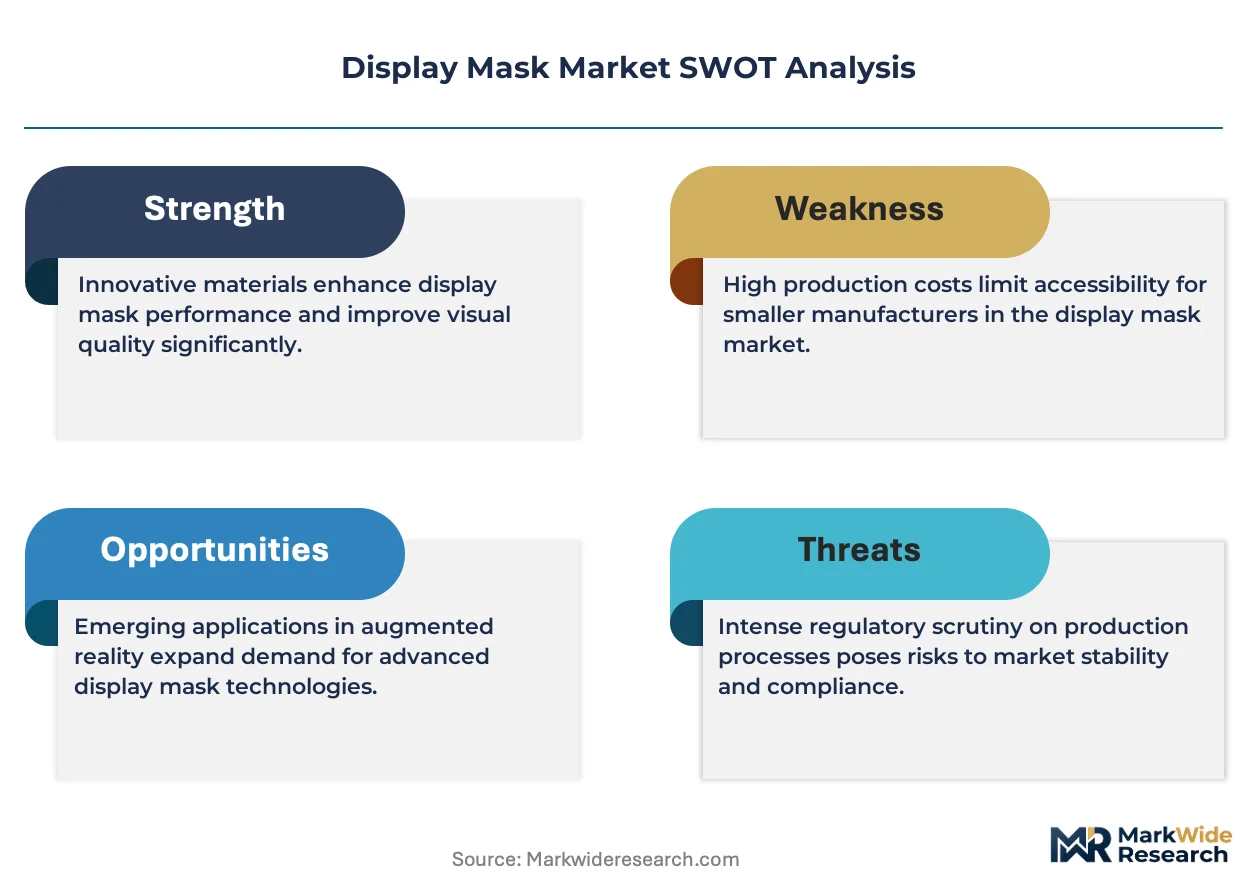
This market operates as a cost-of-compliance story where EU REACH substance restrictions on chromium compound handling create a barrier-to-entry moat for European mask suppliers with documented closed-loop recovery systems.
For Market Incumbents: To counter disintermediation by mega-panel fabs negotiating direct quartz substrate agreements, Hoya Corporation and Toppan Photomasks should deepen captive blank partnerships with lithography equipment makers while expanding EUV blank technical development through METI-subsidized programs. Capacity addition in Hokkaido and Kyushu reinforces supply security against German specialty glassmaker concentration.
For New Entrants and Emerging Players: Launch via medical display certification pathways where FDA device-grade standards impose extended requalification cycles and premium unit economics that deter volume-focused incumbents. White-space targets include diagnostic imaging panel mask tiers and automotive-grade AMOLED integration through South Korea's K-Battery supply chain linkages. Go-to-market angle centers on chromium compound handling compliance documentation for European regulatory alignment.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated substrate-to-mask houses given synthetic fused silica supply concentration and the premium commanded by captive quartz purification capabilities. Long-term viability favors archetypes with demonstrated Gen 10.5 qualification capacity and deep EUV blank partnerships across the analysis window. Signal to watch is first-mover perfluorinated compound disclosure mandates in mask cleaning operations that would cascade through supplier qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Substrate Production | Hoya Corporation's captive fused silica supply insulates margin control against Japanese and German specialty glassmaker concentration. |
| EUV Blank Partnership with Lithography Equipment Makers | Toppan Photomasks deepens technical collaboration with Netherlands and Japan equipment vendors for next-node display-scale substrates. |
| Medical Display Certification Pathway Investment | FDA device-grade qualification creates premium mask tiers with extended requalification cycles and higher unit economics. |
| Molybdenum-Silicide Absorber Transition | MoSi multilayer stacks enable thinner absorber profiles and improved line-edge roughness for sub-micron OLED pixel architectures. |
| Direct Blank Supply Agreement Negotiation | Taiwanese and Korean display makers bypass photomask house intermediaries for Gen 10.5 substrates exceeding standard shipping logistics. |
Research Methodology
Independent corroboration across mask fabrication executives, display panel procurement directors, lithography equipment specialists, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with plant managers at Hefei and Chengdu foundry operations, technical R&D directors at quartz substrate purifiers, and channel partners in semiconductor equipment distribution combined with secondary validation from customs and trade data, SEC filings by listed photomask houses, METI semiconductor revitalization framework disclosures, and ECHA REACH substance restriction updates. Bottom-up and top-down triangulation cross-checked substrate allocation volumes against panel generation line ramp schedules.
Rate-of-change decomposition across the projection horizon modeled display mask demand by emissive technology type, substrate dimensional class, absorber material specification, and end-use certification tier. CAGRs derived from panel maker capital expenditure trajectories, foundry buildout timelines in China's Yangtze River Delta and Sichuan-Chongqing zones, and OLED pixel architecture roadmaps. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down impacts on dry etching equipment upgrade cycles and variable refresh rate implementation patterns compressing mask design cycles.
EUV blank technical limitation resolution, REACH substance restriction enforcement intensity, and perfluorinated compound disclosure mandate timing are the dominant revision risks. Deviation in EUV blank defect density thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Smartwatch Display Panel Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Laptop Panels Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
North America Industrial Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
QLED Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Light Field Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Thin Display Technology Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Projector Screen Market