
 AMOLED Substrate Market | 2026-2036
AMOLED Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
AMOLED Substrate Market Outlook
LTPO backplane integration with variable refresh rates is reconfiguring substrate thermal stability requirements across the AMOLED stack. Corning Incorporated leverages fused silica expertise to anchor high-temperature polysilicon processing lines. AGC Inc. sustains competitive positioning through alkali-free glass formulations optimized for Gen 6 OLED lines. Samsung Corning Precision Materials Co., Ltd. dominates the Korean supply corridor with captive melting capacity.
AMOLED substrates are thin, thermally stable carrier materials—typically alkali-free borosilicate glass or colorless polyimide film—that support semiconductor thin-film transistor deposition during panel fabrication, with coefficient of thermal expansion below 3.8 ppm/°C to prevent pixel misalignment during crystallization annealing. Glass substrates retain volume leadership in rigid smartphone and TV applications where dimensional stability during 500°C+ processing cycles determines yield. Polyimide substrates represent the fastest-expanding segment, driven by foldable smartphone and wearable demand where substrate thickness below 50 micrometers enables bending radii under 3 millimeters. Metal substrates occupy niche industrial and automotive aperture segments requiring thermal dissipation beyond polymer limits.
South Korea's Ministry of Trade, Industry and Energy enforces local content quotas for display material supply chains, while Japan's Ministry of Economy, Trade and Industry (METI) governs export licensing for fluorinated polyimide precursors under foreign exchange controls. REACH registration requirements in Europe constrain perfluorinated compound usage in substrate coating chemistries, redirecting formulation R&D toward silicon-based alternatives. Stakeholders must monitor how substrate suppliers navigate divergent chemical compliance regimes while scaling polyimide capacity for next-generation foldable form factors.
Market Dynamics
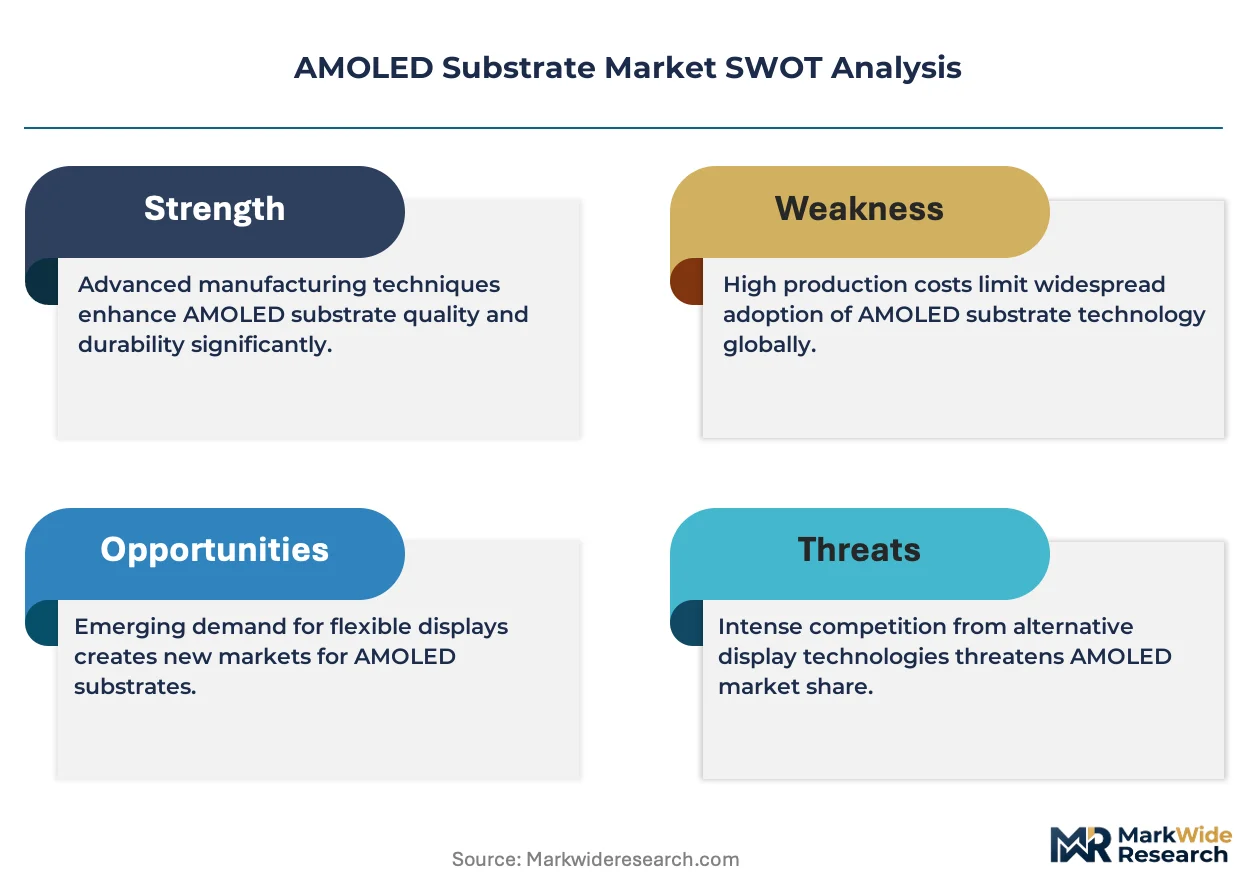
LTPO backplane integration with variable refresh rates is reconfiguring thermal stability requirements across the AMOLED substrate stack, forcing suppliers to engineer coefficient of thermal expansion below 3.8 ppm/°C for pixel alignment precision during crystallization annealing cycles.
Growth Catalysts
- Foldable smartphone procurement expansion:Smartphone manufacturers are scaling flexible display procurement, concentrating polyimide substrate demand near Samsung Display's Asan supply corridor.
- Domestic sourcing mandates:South Korea's Ministry of Trade, Industry and Energy enforces local content quotas for strategic display materials, anchoring captive melting capacity within national borders.
- Wearable form factor proliferation:Substrates below 50 micrometers thickness enable bending radii under 3 millimeters for next-generation wearable devices.
Market Restraints
- Fluorinated precursor supply concentration:Japan's METI governs export licensing for polyimide precursors under foreign exchange controls, creating input volatility for non-Japanese panel fabricators.
- High-temperature processing yield loss:Glass substrates require dimensional stability through 500°C+ annealing cycles, where thermal expansion mismatch destroys pixel alignment.
- Perfluorinated compound regulatory friction:REACH registration requirements in Europe constrain coating chemistries, redirecting formulation R&D toward silicon-based alternatives with unproven scale economics.
Strategic Opportunities
- Automotive aperture thermal dissipation:Metal substrates occupy underdeveloped industrial and automotive segments where polymer thermal limits exclude incumbent materials.
- Alkali-free glass Gen 6 optimization:AGC Inc. formulations demonstrate compatibility with next-generation OLED line widths, creating white space for equipment retrofits.
- Silicon-based coating chemistry transition:Regulatory tailwinds from EU chemical policy are accelerating alternative formulation platforms ahead of competitor repositioning.
Industry Challenges
- Thin-film transistor integration complexity:LTPO variable refresh architectures demand substrate thermal uniformity across expanded active matrix dimensions, compressing process windows.
- Cross-border compliance timeline fragmentation:Divergent chemical control regimes between Japanese precursor licensing, Korean local content rules, and European REACH obligations multiply certification overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AMOLED Substrate Market |
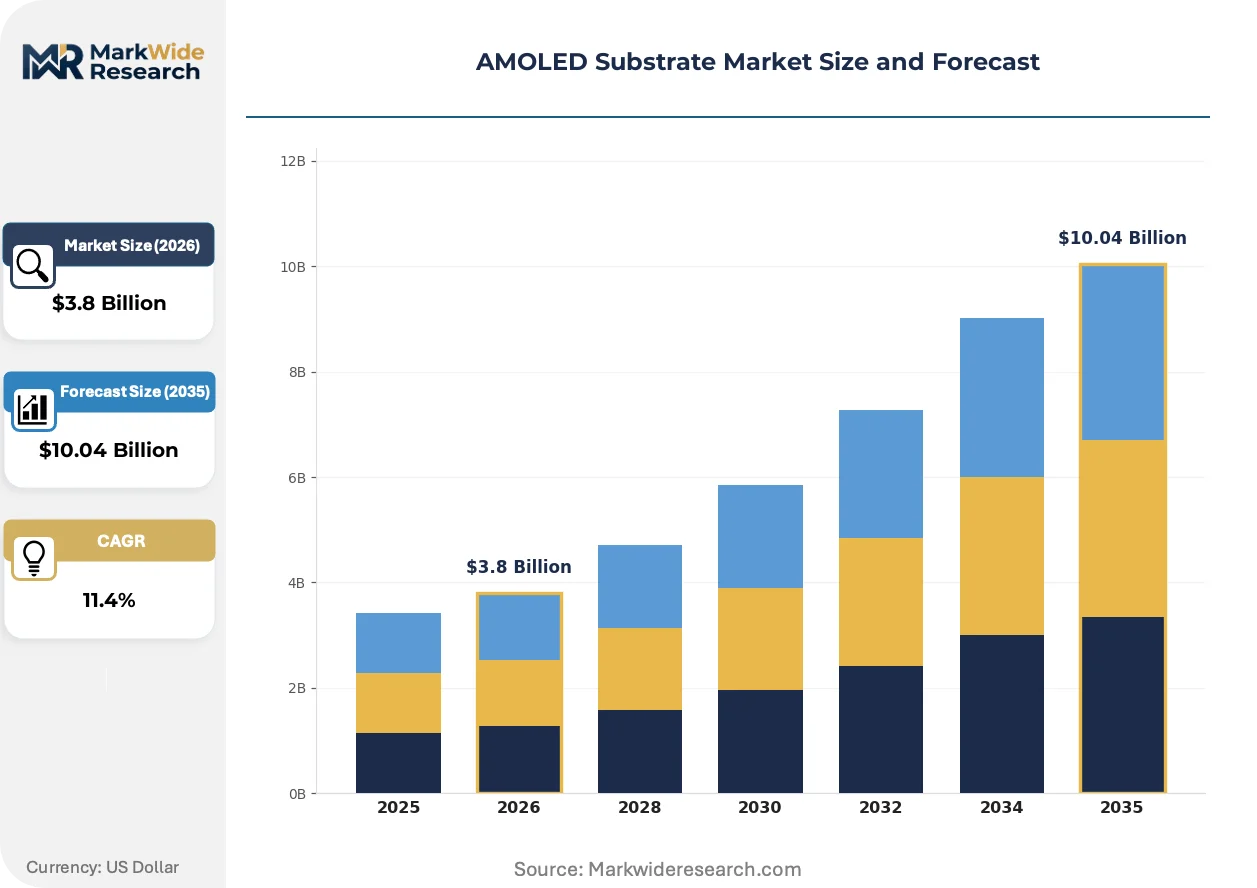
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Polyimide, Metal, Quartz Application: Smartphones, Wearables, TVs, Monitors Technology: Flexible, Rigid, Transparent, OLED End User: Consumer Electronics, Automotive, Aerospace, Industrial |
| Companies Covered | Corning Incorporated, AGC Inc., Nippon Electric Glass Co., Ltd., Samsung Corning Precision Materials Co., Ltd., Schott AG, LG Chem Ltd., Saint-Gobain, AvanStrate Inc., HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AMOLED Substrate Market Strategic Shifts
Substrate technology is bifurcating along rigidity-flexibility lines, with thermal processing requirements and bending radius specifications diverging investment priorities across glass, polyimide, and metal carrier platforms.
Colorless polyimide film is migrating from niche foldable prototyping to mainstream smartphone stack integration. Panel fabricators in Korea's display belt are adopting sub-50 micrometer substrates at accelerating volume. This migration from glass-dominant rigid panels to polymer-flexible architectures is compressing traditional borosilicate capacity expansion timelines.
REACH perfluorinated compound restrictions are tightening formulation constraints across European supply chains. Coating chemistry R&D is pivoting toward silicon-based alternatives with comparable thermal stability profiles. Substrate suppliers with captive European manufacturing are accelerating alternative platform qualification to maintain market access.
Buyer consolidation around Samsung Display's procurement function is compressing supplier negotiation leverage. Tier-2 substrate vendors are retreating from direct panel fabricator relationships toward material precursor supply. Korea's domestic sourcing enforcement is amplifying this concentration effect within the Asan industrial cluster.
AMOLED Substrate Market Segmentation
AMOLED substrate procurement splits along thermal processing requirements and mechanical flexibility needs. Material composition determines compatibility with crystallization annealing cycles above 500°C. Application end-use dictates thickness tolerances and bending radius specifications.
Material Type:
Cost tier stratification separates premium polyimide formulations from commodity glass melting operations.
- Glass:Alkali-free borosilicate compositions deliver dimensional stability through high-temperature polysilicon processing. Volume concentrates in rigid smartphone and TV fabrication where thermal expansion below 3.8 ppm/°C prevents pixel misalignment during annealing.
- Polyimide:Colorless film substrates below 50 micrometers enable bending radii under 3 millimeters for foldable devices. Procurement is accelerating near Samsung Display's Asan supply corridor where Korean domestic sourcing mandates anchor captive capacity.
- Metal:Thermal dissipation properties serve automotive aperture and industrial segments exceeding polymer temperature limits.
- Quartz:Fused silica substrates support specialized high-frequency processing applications with extreme thermal uniformity requirements.
Glass holds installed capacity. Polyimide is rotating up the share rankings.
Application:
Volume concentration tracks display size scaling and procurement batch economics across consumer device categories.
- Smartphones:Flexible substrate penetration is deepest here, with foldable form factors driving sub-50 micrometer polyimide qualification at Korean panel fabricators.
- Wearables:Thickness constraints below 50 micrometers enable tight bending radii for wrist-worn devices, with substrate area per panel minimizing material cost sensitivity.
- TVs:Rigid glass substrates retain dominance due to dimensional stability requirements across large active matrix dimensions during extended annealing cycles.
- Monitors:Intermediate size category splitting procurement between glass-dominant desktop displays and emerging flexible concepts for portable monitors.
Smartphones command procurement volume. Wearables are climbing the fastest expansion trajectory.
Technology:
Maturity gradients separate mass-production rigid architectures from emerging flexible qualification pipelines.
- Flexible:Polyimide carrier platforms enable dynamic bending with substrate thickness reduction below 50 micrometers. LTPO backplane integration is reconfiguring thermal stability requirements across the stack.
- Rigid:Glass-based architectures retain yield advantages in high-temperature processing where dimensional stability determines pixel alignment precision.
- Transparent:Specialized substrate formulations for see-through display applications requiring optical clarity alongside thermal processing compatibility.
- OLED:Standard emissive display architecture spanning both rigid and flexible substrate implementations.
Rigid technology holds installed capacity. Flexible is rotating up the share rankings.
End User:
Customer type differentiation separates high-volume consumer electronics procurement from specialized industrial qualification cycles.
- Consumer Electronics:Smartphone and wearable manufacturers drive substrate volume with flexible display procurement scaling near Samsung Display's Korean supply corridor.
- Automotive:Metal substrates occupy underdeveloped aperture segments where thermal dissipation requirements exceed polymer limits.
- Aerospace:Specialized qualification for extreme environment reliability with substrate thermal cycling performance prioritized over cost optimization.
- Industrial:Niche applications combining thermal management needs with mechanical durability requirements outside consumer device specifications.
Consumer Electronics holds installed capacity. Automotive is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports fluorinated polyimide precursors to Korean panel fabricators under METI foreign exchange licensing, while South Korea enforces domestic sourcing mandates that reshape procurement corridors across East Asia.
South Korea
Flexible display procurement concentrates near Samsung Display's Asan supply corridor where polyimide substrate demand is accelerating. The Ministry of Trade, Industry and Energy enforces local content quotas for strategic display materials, anchoring captive melting capacity within national borders. Seoul Capital Area fabricators are scaling sub-50 micrometer substrate qualification for foldable smartphone stacks.
Japan
Alkali-free glass formulations and colorless polyimide precursors serve Korean and Chinese panel manufacturers under export licensing regimes. METI governs fluorinated compound shipments through foreign exchange controls, creating input volatility for downstream fabricators. Chubu and Kansai industrial belts host specialized substrate material production for high-temperature OLED processing lines.
China
Domestic panel fabricators are expanding substrate procurement for rigid smartphone and TV applications where dimensional stability through 500°C annealing determines yield. MIIT industrial policy supports display material localization through GB standards alignment and domestic capacity subsidies. Yangtze River Delta clusters are scaling Gen 6 OLED line substrate qualification pipelines.
United States
Specialized fused silica substrates support high-frequency processing applications with extreme thermal uniformity requirements. The EPA regulates perfluorinated compound emissions from substrate coating operations, redirecting formulation R&D toward silicon-based alternatives. Arizona and New York State host precision glass melting operations serving aerospace and industrial aperture segments.
Germany
Automotive display substrate qualification is expanding for thermal dissipation applications exceeding polymer temperature limits. ECHA REACH registration requirements constrain perfluorinated coating chemistries, accelerating alternative formulation platform development. Bavaria and Baden-Württemberg host substrate suppliers navigating EU chemical compliance while serving industrial equipment manufacturers.
AMOLED Substrate Market Competitive Environment
On the supply side, the industry is consolidating around material specialists with captive high-temperature processing capabilities and regulatory compliance expertise. Three archetypes dominate: glass melting incumbents with alkali-free borosilicate expertise, polyimide formulators serving flexible display procurement, and precision materials joint ventures anchored to Korean domestic sourcing mandates. Competitive moves center on capacity expansion near Korean industrial clusters and technology licensing for next-generation LTPO backplane compatibility.
Among Japanese material specialists, AGC Inc. and Nippon Electric Glass Co., Ltd. occupy positions within the glass substrate tier, while Samsung Corning Precision Materials Co., Ltd. represents the captive joint venture archetype serving Korean domestic content requirements.
| Leading Market Players |
|---|
| Corning Incorporated |
| AGC Inc. |
| Nippon Electric Glass Co., Ltd. |
| Samsung Corning Precision Materials Co., Ltd. |
| Schott AG |
| LG Chem Ltd. |
| Saint-Gobain |
| AvanStrate Inc. |
| HOYA Corporation |
| Others |
Value Chain & Pricing Dynamics
Japan's fluorinated polyimide precursor manufacturers anchor upstream margin capture, with METI export licensing authority translating directly into Korean panel fabricator cost absorption downstream. This concentration dynamic positions raw material suppliers to extract premium positioning while display OEMs face compressed negotiation leverage on substrate procurement.
Pricing Analysis
Gen 6 alkali-free glass substrates command sustained premiums against Gen 5.5 legacy lines, while sub-50 micrometer polyimide formulations for foldable stacks price at multiples above rigid glass equivalents. Pricing stratifies across premium, standard, and economy tiers based on thermal expansion coefficient certification and volume commitment scale. Cost compression in commodity glass tiers is intensifying because Chinese domestic capacity additions are flooding rigid smartphone substrate procurement. Tier-2 panel fabricators exhibit highest price sensitivity, whereas Samsung Display's consolidated procurement function commands volume-discount positioning.
Supply Chain Analysis
Samsung Corning Precision Materials Co., Ltd. and AGC Inc. hold captive melting and coating capacity across Korea and Japan. Raw material flows draw from fluorinated precursor synthesis in Japan, alkali-free borosilicate melting in Korea, and specialized coating chemistry formulation in Germany. Single-source vulnerability concentrates in Japanese precursor licensing chokepoints where METI foreign exchange controls create input disruption risk. Distribution runs through direct panel fabricator relationships anchored to Samsung Display's Asan supply corridor, with tier-2 vendors retreating toward precursor-only supply positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat structure where Korean domestic content mandates and Japanese export licensing create entrenched supplier switching costs that protect incumbent positioning.
For Market Incumbents: Pre-empt Chinese substrate localization by accelerating Gen 6 OLED line qualification partnerships before MIIT industrial policy achieves GB standards alignment. Secure captive precursor supply through backward integration into fluorinated polyimide synthesis or long-term offtake contracting with Japanese chemical specialists. Defensive priority centers on maintaining thermal expansion coefficient certification leadership as LTPO backplane architectures compress process windows. For New Entrants and Emerging Players: Build out automotive aperture substrate qualification pipelines where metal carrier thermal dissipation properties address unmet industrial demand outside consumer electronics procurement concentration. White-space opportunity concentrates in German automotive OEM display qualification programs where REACH chemical compliance requirements have delayed incumbent repositioning. Go-to-market angle should leverage silicon-based coating chemistry platforms already validated for EU market access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polyimide formulators holding Korean domestic sourcing certifications but lacking scale to serve Samsung Display directly. Long-term viability across the analysis window hinges on regulatory entrenchment durability rather than technology disruption risk. Watch Japanese METI licensing stance relaxation as signal for margin compression inflection in precursor supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Korean Industrial Clusters | Domestic sourcing mandates from the Ministry of Trade, Industry and Energy reward captive melting proximity to Samsung Display's Asan corridor. |
| Backward Integration into Fluorinated Precursor Synthesis | METI export licensing exposure is neutralized through in-house production of colorless polyimide raw materials. |
| Silicon-Based Coating Chemistry Transition | ECHA REACH registration requirements are satisfied ahead of perfluorinated compound restrictions tightening across European supply chains. |
| Automotive Aperture Substrate Qualification | Thermal dissipation requirements from German OEM display programs open industrial segments beyond consumer electronics procurement. |
| LTPO Backplane Compatibility Certification | Variable refresh rate architectures from Korean panel fabricators demand substrate thermal uniformity below 3.8 ppm/°C coefficient expansion. |
Study Parameters
A spread of perspectives from substrate plant managers, display procurement leads at Korean panel fabricators, fluorinated precursor R&D directors, and automotive OEM display engineers converged on the working assumptions. Primary interview intelligence was cross-referenced against customs trade data, METI export licensing disclosures, SEC 10-K filings from listed material specialists, and ECHA REACH registration databases. Bottom-up substrate volume estimates were triangulated with top-down display panel production forecasts across the analysis window.
Demand-supply balance modeling segmented procurement by material type, application end-use, and technology generation, with CAGRs derived from shipment volume trajectory analysis and value-per-unit thermal performance tiering. Forecast inputs incorporated Korean domestic content quota enforcement timelines, Japanese foreign exchange control licensing patterns, and EU chemical policy transition schedules for perfluorinated compound restrictions.
Stress conditions across METI licensing severity, Chinese domestic capacity subsidy scale-up, and foldable smartphone adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory continuity and technology transition pacing. Quarterly review of Japanese precursor export license approval rates and Korean Ministry of Trade, Industry and Energy domestic content enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Portable Projector Market
Display Technologies
Thin Display Technology Market
Display Technologies
Touch Screen Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
3D Display Module Market
Display Technologies
4K VR Displays Market
Display Technologies
Projector Screen Market
Display Technologies
Collaboration Display Market
Display Technologies
United States Microdisplay Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Smart Screen Market