
 Lighting Control Components Market | 2026-2036
Lighting Control Components Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Control Components Market Analytics
Electrical distributor networks across North America and Europe are reshaping how lighting control components reach contractors and specifiers. Signify Holding leverages direct specification relationships with large commercial developers to sustain volume commitments in project lighting. Acuity Brands Lighting anchors its position through deep vertical integration into LED driver and control module manufacturing. Schneider Electric competes by bundling lighting controls with building management software, extending its share of integrated facility contracts.
Lighting control components encompass dimmers, sensors, controllers, and relay modules that modulate artificial illumination based on occupancy, daylight availability, or scheduled commands, typically operating at low-voltage DC or line-voltage AC with communication protocols such as Zigbee or BACnet. These devices reduce energy consumption in commercial and residential buildings by automating on-off cycles and intensity levels. Sensor-based systems currently lead product type revenue due to code-mandated occupancy detection in new construction across multiple jurisdictions. Wireless installations are outpacing wired alternatives in retrofit applications where conduit access is limited or costly. Bluetooth and Zigbee technologies dominate technology selection for residential smart home ecosystems, while Wi-Fi controls occupy premium commercial segments requiring higher bandwidth for centralized monitoring.
The US Department of Energy enforces efficiency standards through ENERGY STAR and federal appliance regulations that directly shape sensor and controller performance thresholds. In Europe, the Ecodesign Directive and CE marking requirements under the EU Green Deal mandate minimum efficacy and interoperability standards for lighting control products sold in member states. China's GB standards and MIIT circular economy policies impose domestic efficiency and materials recovery rules on control component manufacturers. Stakeholders must monitor divergence between regional certification regimes and protocol standards to avoid fragmentation in product portfolios and supply chain compliance costs.
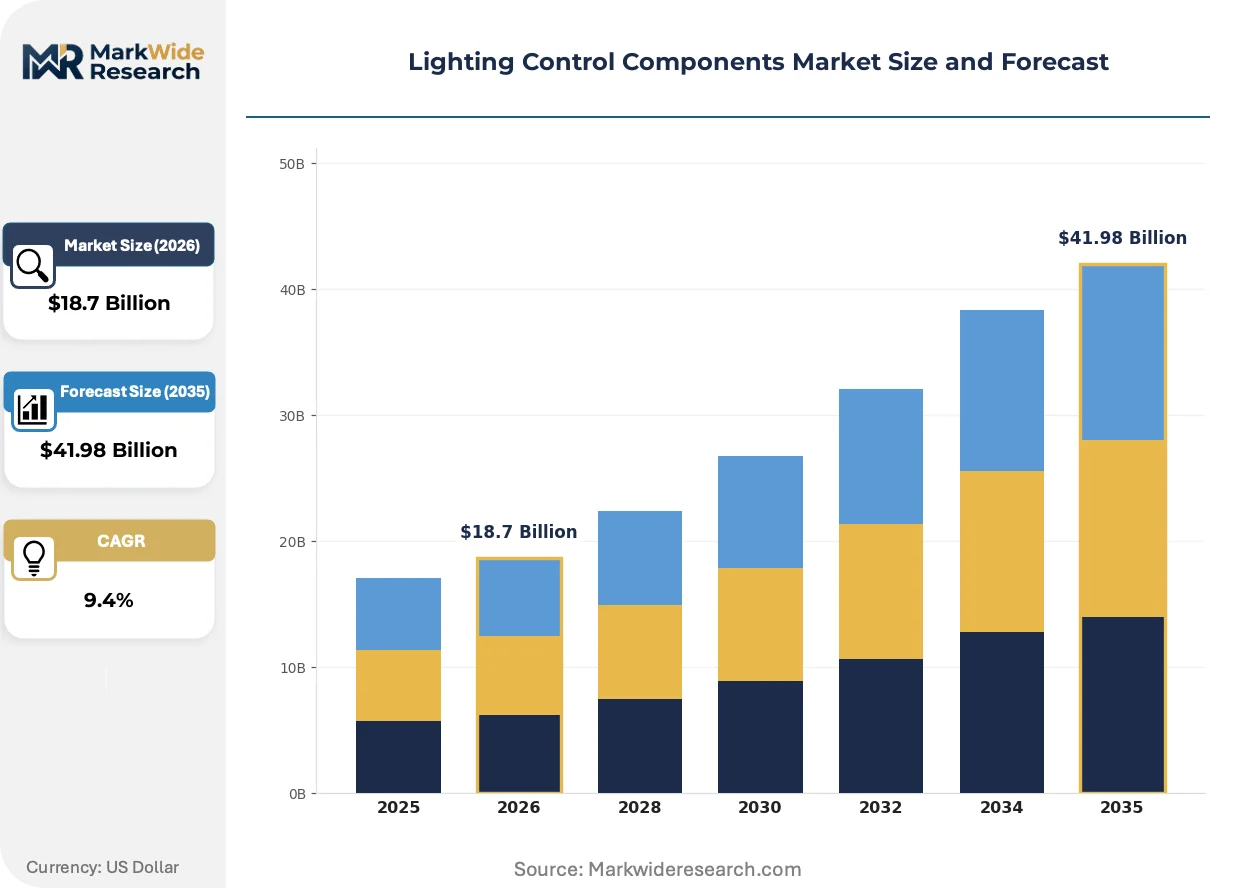
Market Dynamics
The EU Green Deal and parallel efficiency mandates in North America and Asia are compressing procurement cycles as building owners accelerate retrofit timelines to meet tightening performance thresholds before penalty phases activate.
Growth Catalysts
- Commercial real estate smart building adoption:Property developers in the United States and Germany are embedding sensor networks and automated dimming systems into new construction specifications to secure green building certifications and attract ESG-focused tenants.
- ENERGY STAR and federal appliance regulations:The US Department of Energy mandates occupancy detection and daylight harvesting in federal buildings, forcing controller and sensor upgrades across public sector facilities.
- Wireless protocol maturation:Zigbee and Bluetooth mesh deployments are eliminating conduit costs in retrofit projects, unlocking building stock previously uneconomical to upgrade due to hardwired infrastructure requirements.
Market Restraints
- Silicon and rare earth element price volatility:Controller chipsets and sensor magnet assemblies face input cost instability from concentrated mining operations in China and processing bottlenecks in Southeast Asia.
- Protocol fragmentation:Divergent certification regimes across the EU Green Deal, China's GB standards, and US federal requirements force manufacturers to maintain multiple product variants, inflating inventory and testing overhead.
- Competition from standalone smart bulbs:Consumer-grade Wi-Fi enabled luminaires with onboard controls threaten discrete component sales in residential and light commercial segments where installation simplicity trumps system integration.
Strategic Opportunities
- India's building energy code expansion:The Bureau of Energy Efficiency is mandating lighting controls in commercial buildings exceeding specified floor areas, creating first-mover advantage for component suppliers establishing local assembly partnerships.
- Healthcare facility circadian lighting:Hospitals and aged-care operators are specifying tunable white systems with programmable controllers to support patient recovery protocols and staff alertness management.
- Convergence of lighting controls with HVAC and security:BACnet-integrated controllers that share occupancy data across building management systems are capturing premium specification in large commercial developments seeking single-platform facility oversight.
Industry Challenges
- Cybersecurity certification complexity:IoT-enabled controllers must satisfy diverging national standards for network security, with the EU Cybersecurity Act and US NIST frameworks imposing non-harmonized testing timelines that delay product launches.
- Legacy fluorescent infrastructure integration:Contractors face technical friction when retrofitting digital controls onto existing magnetic ballast circuits, requiring specialized adapters and extending project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Control Components Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimmer Switches, Sensors, Controllers, Relay Modules Technology: Zigbee, Z-Wave, Bluetooth, Wi-Fi Application: Residential, Commercial, Industrial, Outdoor Installation: Wired, Wireless, Retrofit, Integrated |
| Companies Covered | Signify Holding, Acuity Brands Lighting, Inc., Schneider Electric, Legrand S.A., Eaton Corporation, Lutron Electronics Co., Inc., ams-OSRAM AG, Hubbell Incorporated, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Control Components Market Evolving Landscape
Digital twin architecture and edge computing are reshaping how lighting control systems generate and act on environmental data, compressing the gap between sensor input and automated response.
Power-over-Ethernet (PoE) lighting control systems are digitizing fixture-level energy management by delivering both electricity and data through standard network cabling. Large commercial developers in the United States are specifying PoE for new headquarters and campus projects to simplify infrastructure and enable granular consumption tracking. This architecture is digitizing the traditional division between electrical contracting and IT networking, forcing contractor specialization and reshaping project bidding structures.
The EU Ecodesign Directive's tightening standby power limits are eliminating inefficient controller designs from the European market. Manufacturers must redesign power supplies and sleep-state logic to meet sub-watt thresholds, accelerating obsolescence of legacy product lines. Sensor modules with integrated microcontrollers are most affected, with suppliers racing to certify next-generation ASICs before enforcement deadlines.
Facility managers are consolidating vendor relationships by specifying integrated lighting and building management platforms from single suppliers. This pattern is displacing the historical practice of procuring controls through electrical distributors independent of HVAC and security system decisions. Germany and the Netherlands show the strongest concentration of this behavior, driven by large property portfolio operators seeking unified service contracts and simplified warranty management.
Lighting Control Components Market Segmentation
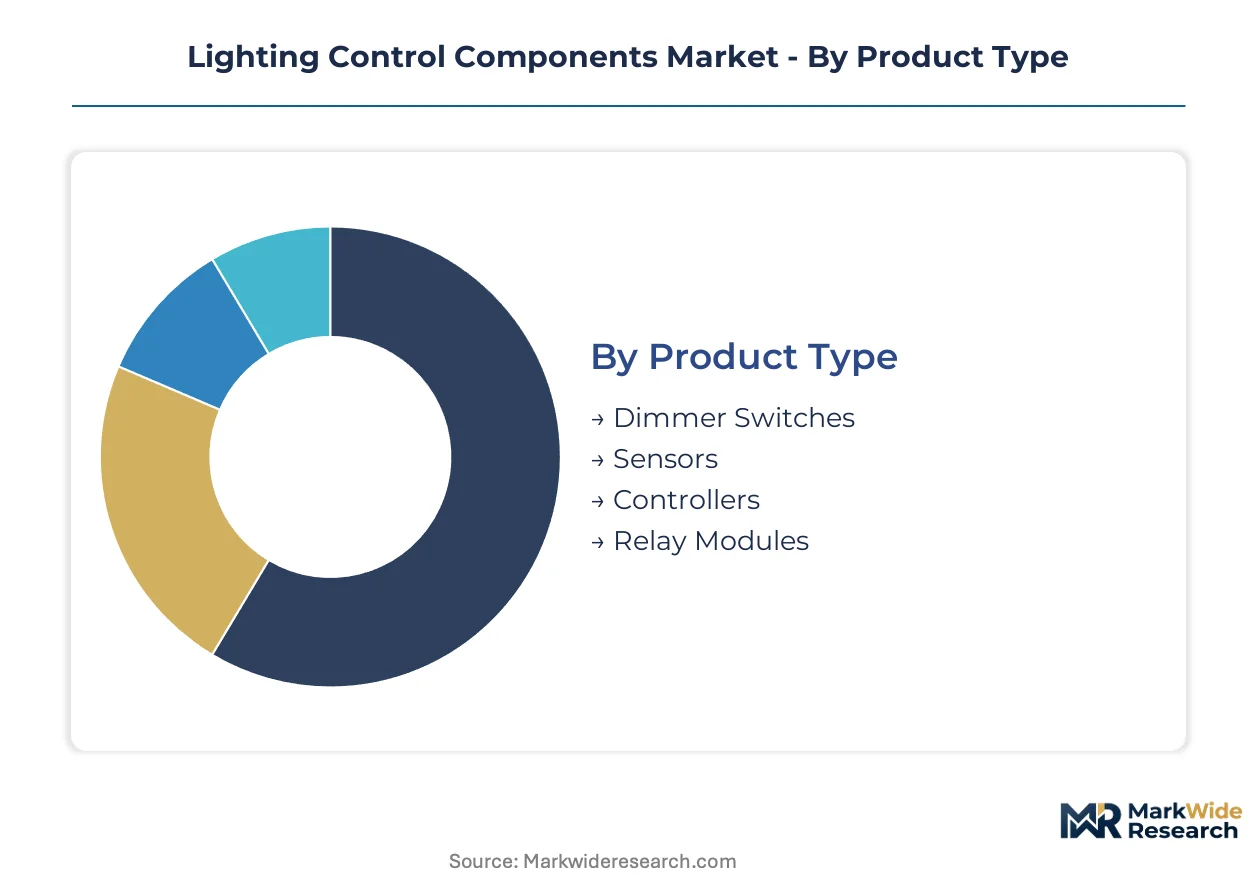
Lighting control components fragment across four dimensions that shape procurement economics and technical specification. Product architecture, communication protocol, end-use environment, and deployment method each impose distinct compliance burdens and margin structures on suppliers.
Product Type:
Cost tier differentiation separates commodity-grade switching hardware from premium sensing and control intelligence.
- Sensors:Photocells, passive infrared, and ultrasonic modules detect occupancy and ambient light levels to trigger automated responses. Demand concentrates in new commercial construction across Germany and the United States where building codes mandate occupancy detection and daylight harvesting. ENERGY STAR certification requirements and EU Ecodesign standby power limits are forcing chipset redesigns and accelerating obsolescence of legacy microcontroller architectures.
- Controllers:Microprocessor-based units execute programmed lighting schedules and process sensor inputs to modulate output intensity. Large commercial developers in China and the Netherlands specify BACnet-integrated controllers that share occupancy data with HVAC and security systems, capturing premium positioning in unified building management contracts.
- Dimmer Switches:Phase-cut and 0-10V analog devices adjust fixture output through wall-mounted or remote interfaces. Residential renovation activity in the United States and United Kingdom sustains volume for basic TRIAC-based units.
- Relay Modules:Electromechanical or solid-state switching devices isolate control circuits from load currents in centralized panel architectures. Industrial facilities in Japan and South Korea specify heavy-duty relay banks for high-bay and hazardous location installations.
Sensors hold installed capacity. Controllers are rotating up the share rankings.
Technology:
Protocol selection determines infrastructure cost, interoperability scope, and cybersecurity exposure across deployment scenarios.
- Zigbee:Mesh networking standard operating at 2.4 GHz with self-healing topology and low power consumption. Residential smart home ecosystems in the United States and Germany favor Zigbee for whole-house automation, while commercial specifiers value its deterministic latency for daylight harvesting coordination. The protocol's certification overhead through the Connectivity Standards Alliance creates barrier-to-entry for new entrants.
- Bluetooth:Point-to-point and mesh configurations leverage ubiquitous smartphone compatibility for commissioning and user control. Retrofit contractors in the United Kingdom and Australia specify Bluetooth mesh where conduit access is restricted, eliminating labor-intensive wiring runs in historic building stock.
- Wi-Fi:High-bandwidth protocol enabling cloud-connected monitoring and over-the-air firmware updates. Premium commercial segments in Singapore and the United Arab Emirates specify Wi-Fi controls for centralized facility oversight across distributed real estate portfolios.
- Z-Wave:Sub-GHz mesh protocol optimized for residential range and penetration through building materials. Security-focused installers in the United States specify Z-Wave for its proprietary stack and reduced interference profile in multi-protocol environments.
Zigbee holds installed capacity. Bluetooth is rotating up the share rankings.
Application:
End-use environment dictates performance specifications, warranty terms, and channel access requirements.
- Commercial:Office, retail, hospitality, and healthcare facilities requiring code-compliant automation and integration with building management systems. Property developers in the United States and Germany embed sensor networks to secure LEED and BREEAM certifications and attract ESG-focused tenants.
- Residential:Single-family and multi-unit dwellings where consumer-grade installation simplicity and aesthetic integration dominate purchasing criteria. Smart home adoption in China and South Korea drives demand for app-configurable wireless controls.
- Industrial:Manufacturing, warehousing, and logistics facilities requiring ruggedized hardware and high-bay coverage. Facilities in Japan and Germany specify heavy-duty relay modules and high-power controllers for 24-hour operational environments.
- Outdoor:Street lighting, parking structures, and landscape illumination exposed to environmental stress and vandalism. Municipal procurement in the Netherlands and Singapore favors networked controls with remote diagnostics to reduce maintenance truck rolls.
Commercial holds installed capacity. Residential is rotating up the share rankings.
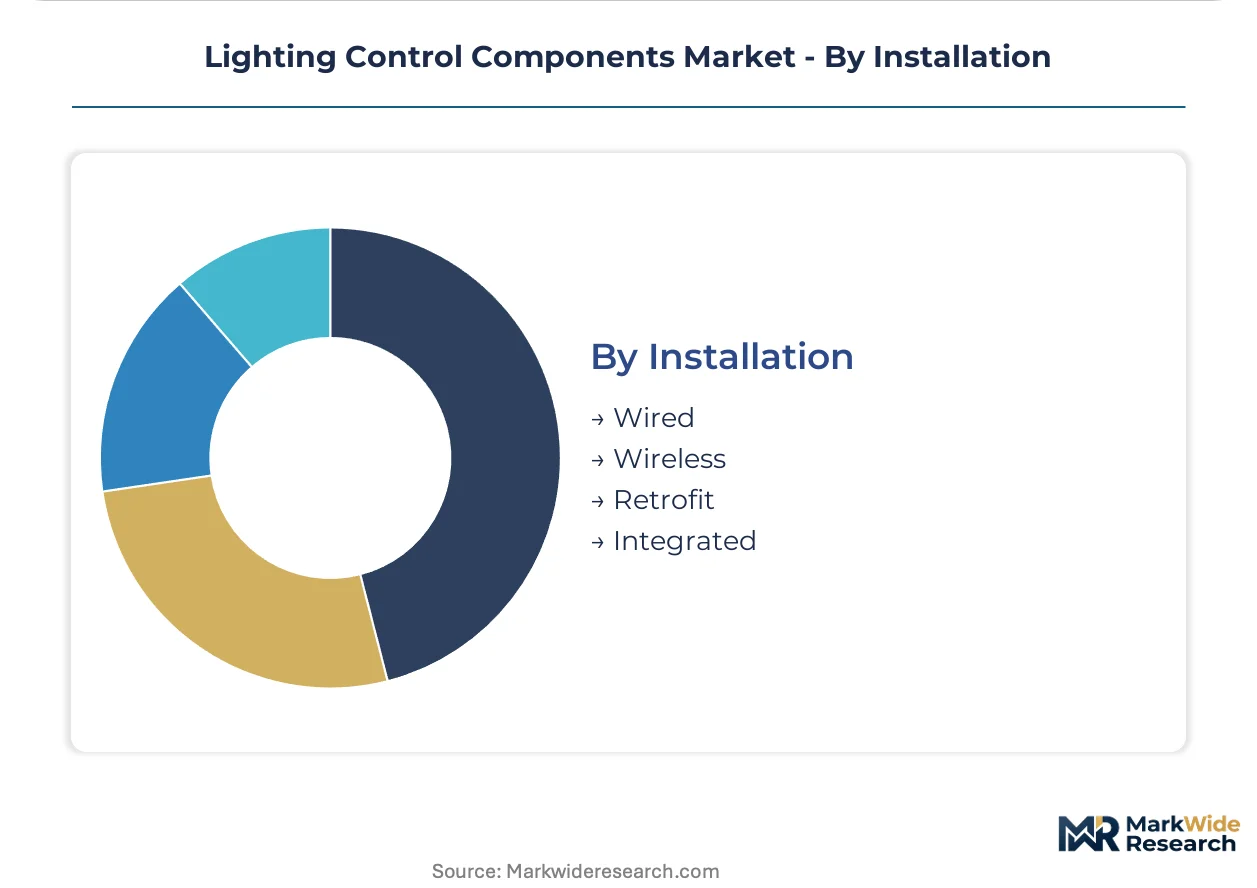
Installation:
Deployment method shapes contractor specialization, project duration, and total installed cost.
- Wireless:Battery-powered or line-powered devices communicating via radio frequency without dedicated control wiring. Retrofit activity in the United Kingdom and United States accelerates as Zigbee and Bluetooth mesh eliminate conduit costs in building stock previously uneconomical to upgrade.
- Integrated:Factory-embedded controls within luminaire housings delivered as complete assemblies. Large commercial developers in the United States and Germany specify integrated systems to consolidate vendor relationships and simplify warranty management.
- Wired:Dedicated low-voltage or line-voltage control circuits installed during new construction or full-gut renovation. New commercial builds in China and Singapore specify wired BACnet or DALI infrastructure for deterministic performance and centralized monitoring.
- Retrofit:Adaptation of existing luminaires with add-on control modules and wireless bridges. Contractors in Japan and France face technical friction when interfacing digital controls with legacy magnetic ballast circuits, requiring specialized adapters.
Wired holds installed capacity. Wireless is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's European distribution hub underwrites the Netherlands' role in trans-shipping control components to German industrial clusters and UK retrofit contractors.
United States
Federal building mandates and commercial real estate ESG financing accelerate sensor procurement across office and healthcare verticals. The US Department of Energy enforces ENERGY STAR and federal appliance regulations that mandate occupancy detection in public facilities. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate specification activity for large commercial developments seeking LEED certification.
Germany
Industrial facility automation and circadian healthcare lighting specifications drive controller demand in manufacturing and hospital segments. The EU Green Deal and Ecodesign Directive impose tightening standby power limits that eliminate inefficient designs from the market. Bavaria's Munich-Stuttgart corridor anchors specification engineering for integrated building management systems.
China
New construction standards and smart city infrastructure deployment expand domestic sensor and relay module manufacturing capacity. MIIT circular economy policies and GB standards impose domestic efficiency and materials recovery rules on control component producers. The Yangtze River Delta cluster around Shanghai concentrates export-oriented production for Southeast Asian and European markets.
United Kingdom
Historic building retrofit limitations and wireless protocol maturation accelerate Bluetooth mesh adoption where conduit access is restricted. CE marking requirements under EU-aligned regulations maintain performance thresholds for products entering Northern Ireland and EU markets. London's commercial property sector leads specification of integrated controls for unified facility management platforms.
India
Bureau of Energy Efficiency building code expansion mandates lighting controls in commercial buildings exceeding specified floor areas. Central Electricity Authority efficiency guidelines and state-level green building incentives compress procurement cycles for retrofit and new construction. Maharashtra's Mumbai-Pune industrial corridor attracts first-mover assembly partnerships for component localization.
Lighting Control Components Market Competitive Landscape
On the supply side, the industry is moderately consolidated with tiered specialization across integrated building management platforms, discrete component manufacturing, and wireless protocol ecosystems. Electrical distributors reshape channel access in North America and Europe while direct specification relationships dominate large commercial projects. Three archetypes anchor competitive positioning: vertically integrated lighting conglomerates, building automation specialists, and wireless technology licensors. M&A activity concentrates on sensor chipset capabilities and software platform integration, while geographic expansion targets India's emerging building code enforcement and Southeast Asian manufacturing cost advantages.
Among diversified electrical equipment conglomerates, Signify Holding and Schneider Electric occupy positions exemplifying the integrated platform archetype, bundling controls with broader facility management offerings. Acuity Brands Lighting, Inc. anchors the vertically integrated specialist tier with captive manufacturing of LED drivers and control modules. These three entities represent the dominant competitive vectors shaping procurement relationships with large commercial developers and facility management operators across Germany, the United States, and China.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands Lighting, Inc. |
| Schneider Electric |
| Legrand S.A. |
| Eaton Corporation |
| Lutron Electronics Co., Inc. |
| ams-OSRAM AG |
| Hubbell Incorporated |
| General Electric Company |
| Others |
Value Network & Pricing Analysis
Rare earth element price volatility from concentrated Chinese mining operations determines both the spread between premium sensor modules and economy-grade relay hardware and the geographic clustering of final assembly capacity. Manufacturers must absorb input cost swings or pass them through to buyers, compressing margins at the mid-market tier while insulated premium suppliers maintain pricing power through certification-locked specifications.
Pricing Analysis
Volume-discount tiering separates project-scale procurement for large commercial developers from transactional spot purchases by residential contractors. Pricing stratifies across premium BACnet-integrated controllers, standard Zigbee sensor networks, and economy-grade TRIAC dimmers based on interoperability certification and after-sales service bundling. Cost compression in the standard tier is intensifying as Chinese manufacturers expand relay module capacity. Residential retrofit contractors exhibit highest price sensitivity, while healthcare facility operators prioritize circadian lighting performance over unit economics.
Supply Chain Analysis
Upstream silicon wafer and magnet assembly feedstock draws from concentrated operations in China, Taiwan, and Malaysia. Controller chipsets rest on 200mm semiconductor foundry capacity and neodymium magnet supply from Bayan Obo mining complexes. Single-source vulnerability in rare earth processing creates exposure to export restriction shocks. Distribution runs through electrical distributor networks in North America and Europe, with direct specification relationships bypassing wholesale channels for large commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified firmware engineering talent for BACnet and cybersecurity compliance is constraining how quickly suppliers can refresh product portfolios to meet tightening EU and US efficiency mandates.
For Market Incumbents: Entrench specification relationships with large commercial developers by embedding controls within integrated building management platforms. Acquire sensor chipset capabilities to reduce dependency on external semiconductor suppliers. Channel control through direct specification engineering teams represents the critical defensive lever against emerging wireless-native competitors. For New Entrants and Emerging Players: Mid-market commercial buildings in India represent the most penetrable entry point as Bureau of Energy Efficiency codes activate first-mover procurement windows. Bluetooth mesh retrofit kits for historic building stock in the United Kingdom offer secondary white-space access. Partner with local electrical contractors for installation certification rather than building captive sales infrastructure. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors platform-integrated suppliers over discrete component manufacturers. Long-term viability hinges on software recurring revenue attachment rates rather than hardware shipment volumes. Acquisition targets should demonstrate BACnet-integrated controller portfolios with healthcare facility reference sites. Monitor EU Cybersecurity Act enforcement timelines as inflection signals for compliance-cost barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Chipset Acquisition | Captive semiconductor supply insulates margins from rare earth price volatility originating in Chinese mining operations. |
| BACnet Platform Integration | Unified building management contracts with HVAC and security vendors capture premium specification in German commercial developments. |
| India Assembly Partnership | Local production satisfies Bureau of Energy Efficiency domestic content expectations for commercial building code compliance. |
| Cybersecurity Certification Investment | EU Cybersecurity Act and US NIST framework compliance accelerates product launch timelines for IoT-enabled controllers. |
| Healthcare Circadian Lighting Development | Tunable white systems with programmable controllers address patient recovery protocols in US hospital capital expenditure cycles. |
Research Methodology
Desk research of regulatory filings from the US Department of Energy and EU Ecodesign Directive databases preceded structured interviews with commercial real estate developers, electrical contractor procurement managers, and building automation system integrators. Secondary validation drew from ENERGY STAR certification records, CE marking registries, and MIIT circular economy policy circulars. Bottom-up segment sizing triangulated against top-down construction spending data across the analysis window.
Assumptions held fixed include EU Green Deal enforcement timelines and US federal building mandate activation schedules, while wireless protocol adoption curves and rare earth supply disruption probabilities were varied across sensitivity scenarios. Segmentation modeling spanned product architecture, communication protocol, end-use environment, and deployment method dimensions plus regional regulatory cluster differentiation. CAGRs derived from installed base replacement cycles and new construction standard adoption rates, with PoE infrastructure penetration and smart city deployment cadence serving as key industry-specific inputs.
Practitioners should monitor EU Cybersecurity Act implementation delays and Chinese rare earth export licensing changes for early signals requiring forecast revision. Cross-checking against US Census Bureau construction spending data and Eurostat building permit statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Work Lights Market
Lighting
Digital Light Processing Technology Market
Lighting
EV Lighting Market
Lighting
Street Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Solid-State Lighting Source Market
Lighting
GCC Smart Lighting Market
Lighting
Directional Luminaire Market
Lighting
LED Solar Lighting Market
Lighting
Solar Column Headlight Market
Lighting
UAE Smart Lighting Market
Lighting
Intelligent Lighting Controls Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
Recessed Lighting Market
Lighting
Ring Lights Market