
 Interactive Display Market | 2026-2036
Interactive Display Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Display Market Analysis
Indium tin oxide is restructuring cost structures across capacitive touch layers as silver nanowire and metal-mesh alternatives gain commercial scale. Samsung Electronics Co Ltd leverages its captive semiconductor and display fabs to control vertical supply chains from driver ICs to finished modules. LG Electronics Inc anchors premium interactive OLED installations in corporate and broadcast environments through differentiated form factors. BOE Technology Group Co Ltd dominates volume manufacturing of LCD interactive panels, sustaining price competitiveness through massive Gen 10.5 fab scale.
An interactive display is a human-machine interface comprising a flat-panel matrix bonded to a position-sensing substrate, typically operating at 4K resolution with touch latency below 10 milliseconds, designed to enable simultaneous multi-user input for information presentation and manipulation. LCD technology occupies the bulk of unit shipments due to mature supply chains and cost efficiency, while LED video walls capture the highest value-per-square-meter in command-center and retail flagship deployments. Interactive kiosks represent the fastest-growing product type as quick-service restaurants and transit authorities replace static terminals with gesture-capable ordering and wayfinding systems.
The U.S. FCC regulates electromagnetic emissions from interactive display wireless connectivity modules, while the EU RoHS Directive and REACH framework restrict hazardous substances in panel substrates and solder materials, compelling Asian contract manufacturers to reformulate assembly chemistries. China's MIIT enforces GB standards for display energy efficiency and network security in connected classroom devices. Stakeholders must monitor divergence between regional e-waste recycling mandates and modular repairability requirements, as these will determine which supply chain configurations retain market access across major economies.
Market Dynamics
Silver nanowire touch layers are compressing bill-of-materials costs for capacitive interactive panels, forcing legacy ITO deposition equipment into obsolescence across Asian contract manufacturers.
Growth Catalysts
- EU Ecodesign Directive:Mandates for lower-power panel architectures are accelerating procurement of energy-efficient interactive screens in German corporate boardrooms and Dutch retail chains.
- Gesture recognition:Quick-service restaurants in Shanghai and Shenzhen are replacing static terminals with motion-capable ordering systems, expanding kiosk deployment.
- China MIIT digitization:Government programs for connected classrooms are driving LCD interactive panel installation across provincial education infrastructure.
Market Restraints
- Indium supply concentration:Over 70% of refined indium originates from Chinese smelters, creating input cost volatility for ITO-dependent touch layer production.
- Gen 10.5 fab lock-in:Massive LCD capacity concentration in Hefei and Wuhan limits supplier diversification for large-format interactive modules.
- Touch latency floors:Capacitive architectures struggle to break sub-5 millisecond response thresholds required for broadcast studio applications.
Strategic Opportunities
- India education infrastructure:Underpenetrated smart classroom deployment in Maharashtra and Karnataka offers white space for interactive whiteboard vendors.
- Metal-mesh convergence:Hybrid silver-copper mesh processes are opening premium OLED touch integration for curved corporate installations.
- EU CSRD reporting:Corporate sustainability disclosure requirements are creating preference for modular, repairable interactive display procurement.
Industry Challenges
- Driver IC firmware integration:Multi-touch protocol standardization gaps between Windows, Android, and proprietary embedded systems extend certification timelines for unified classroom platforms.
- Legacy AV infrastructure:HDMI 2.0 cabling and control room matrix switchers in existing command centers resist seamless 4K 120Hz interactive panel integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Display Market |
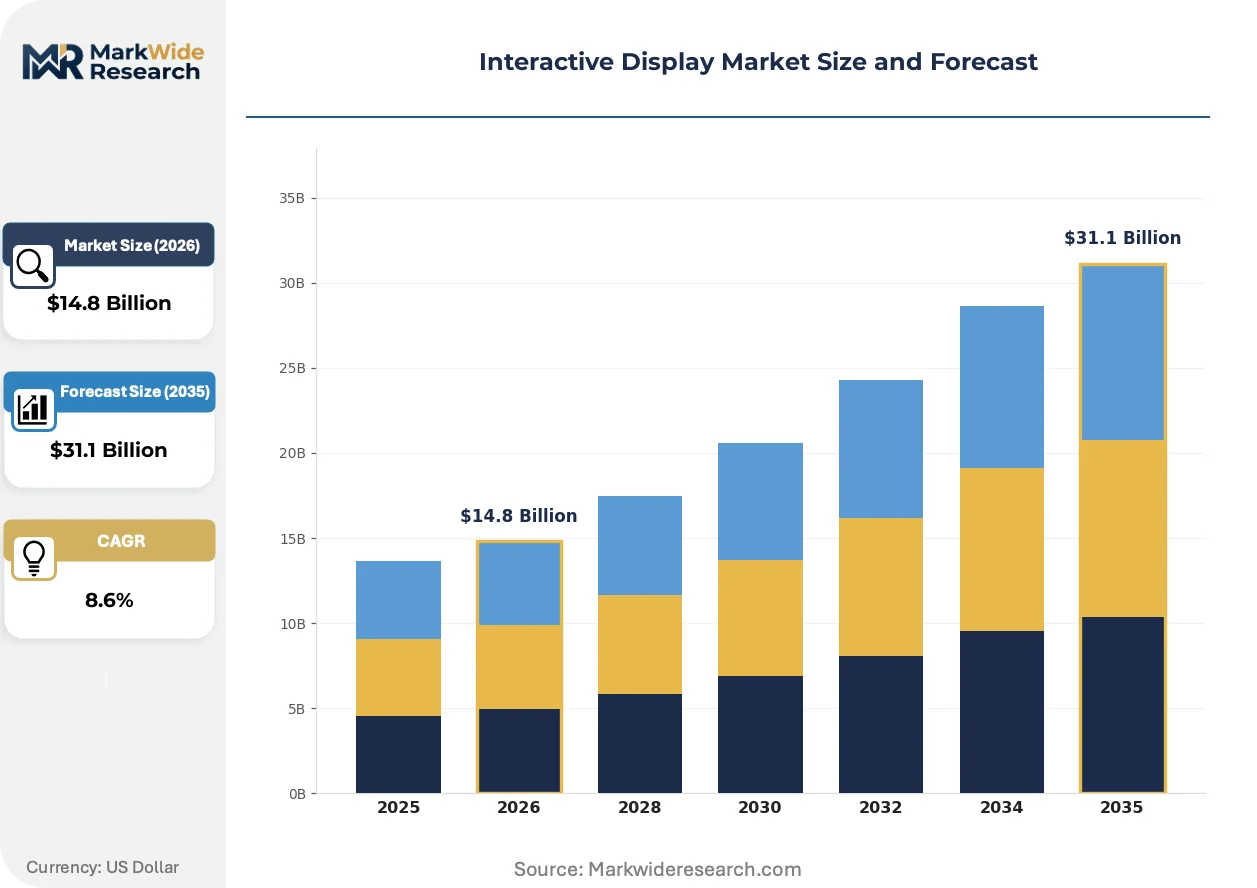
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Monitors, Video Walls, Digital Signage, Interactive Kiosks Technology: LCD, LED, OLED, Projection Mapping End User: Education, Retail, Corporate, Hospitality Installation Type: Wall-mounted, Free-standing, Portable, Embedded |
| Companies Covered | Samsung Electronics Co Ltd, LG Electronics Inc, BOE Technology Group Co Ltd, Panasonic Corporation, Sharp Corporation, ViewSonic Corporation, Promethean Limited, BenQ Corporation, Leyard Optoelectronic Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Display Market Emerging Trajectories
Touch substrate materials and procurement protocols are bifurcating the interactive display landscape into premium gesture-capable installations and cost-optimized education deployments.
Metal-mesh capacitive sensors are overtaking indium tin oxide in large-format interactive panels. Corporate boardrooms above 86 inches are adopting copper-silver hybrid meshes for superior conductivity at reduced material cost. The structural consequence is overtaking ITO sputtering equipment valuations in Korean and Taiwanese fabrication facilities.
REACH substance restrictions are forcing reformulation of solder alloys and panel substrate resins. Asian contract manufacturers serving EU markets must eliminate specified phthalates and heavy metals from assembly chemistries. Interactive kiosk producers are responding by shifting final assembly to European facilities with certified green chemistry lines.
Subscription-based hardware refresh cycles are displacing capital purchase models in North American enterprise accounts. IT departments favor predictable operating expenditures over depreciated asset ownership. This pattern concentrates most visibly in California and Texas technology sector headquarters, where facilities teams bundle interactive displays with managed service agreements.
Interactive Display Market Segmentation
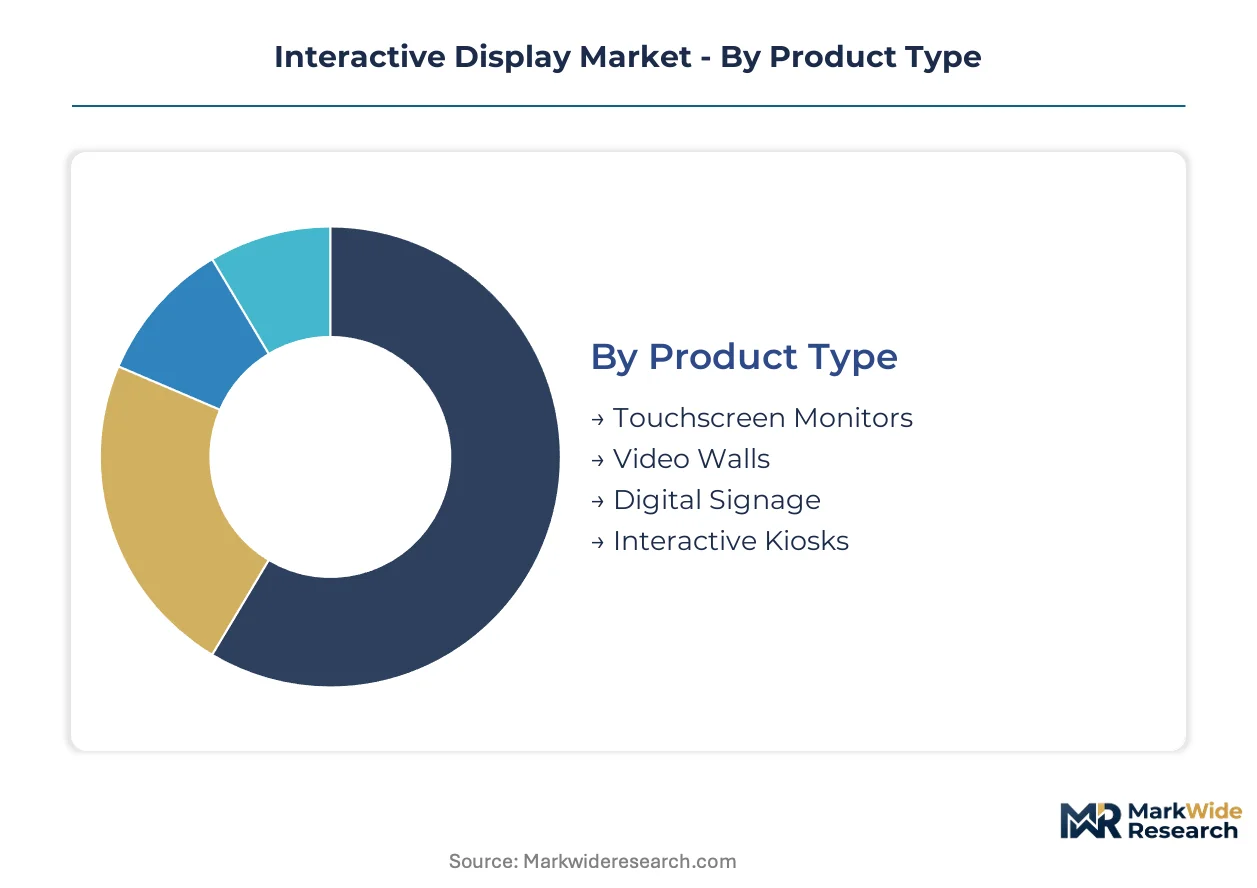
Interactive display procurement patterns diverge sharply across use cases, with education buyers prioritizing cost efficiency while corporate and broadcast clients demand sub-10 millisecond latency and 4K resolution specifications. Understanding segment-specific upgrade cycles and replacement thresholds enables vendors to align product roadmaps with predictable refresh demand.
Product Type:
Replacement cycles vary from 3-4 years in quick-service restaurant kiosks to 7-10 years in installed video wall arrays, creating asynchronous revenue pulses across the product portfolio.
- Touchscreen Monitors:Single-panel capacitive or infrared touch matrices ranging from 24 to 98 inches, bonded to glass substrates with anti-glare coatings. Procurement concentrates in German corporate boardrooms and Dutch municipal offices under EU Ecodesign Directive compliance mandates, with buyers prioritizing energy-efficient driver architectures over legacy fluorescent backlight units.
- Interactive Kiosks:Self-contained units integrating gesture-capable displays with payment terminals and thermal printers, typically deployed at 32 to 55 inches. Quick-service restaurants in Shanghai and Shenzhen are replacing static terminals with motion-sensing ordering systems, accelerating kiosk deployment as labor costs rise and customer throughput demands intensify.
- Video Walls:Tiled LED or LCD arrays with bezel-minimized seams for seamless imagery in command centers and broadcast studios.
- Digital Signage:Network-connected displays for retail wayfinding and promotional content, prioritizing remote management and content scheduling over interactivity depth.
Touchscreen monitors sit at the top of the volume ranking, with interactive kiosks climbing the fastest.
Technology:
Cost tiers stratify sharply across display technologies, with LCD commanding unit volume leadership and OLED extracting premium pricing for curved and transparent form factors.
- LCD:Thin-film transistor backplanes with LED edge-lit or direct-lit backlight units, dominating unit shipments through mature supply chains and Gen 10.5 fab scale in Hefei and Wuhan. Education sector procurement in China and India drives volume, with MIIT-connected classroom programs specifying LCD interactive whiteboards for provincial infrastructure rollout.
- OLED:Organic electroluminescent pixels on flexible polyimide substrates, enabling curved installations and transparent showcase applications. Corporate broadcast environments in London and Los Angeles specify OLED for premium control room and studio installations where black level performance and viewing angle consistency justify 3-4x cost premiums over equivalent LCD formats.
- LED:Direct-view LED modules with pixel pitches from 0.9mm to 4mm, capturing highest value-per-square-meter in flagship retail and command-center deployments.
- Projection Mapping:Ultra-short-throw laser projectors with interactive infrared sensing, serving temporary installations and heritage building retrofits where display weight and heat dissipation constrain fixed-panel options.
LCD dominates absolute shipment volumes, while OLED gains share fastest in premium corporate and broadcast segments.
End User:
Customer type determines specification intensity, with education buyers accepting 20+ millisecond touch latency while broadcast and command-center clients demand sub-5 millisecond performance.
- Education:K-12 and higher education institutions deploying interactive whiteboards and student response systems, typically 65 to 86 inches. China's MIIT digitization programs drive LCD panel installation across provincial infrastructure, with connected classroom mandates specifying multi-touch protocols compatible with Android and Windows embedded systems.
- Corporate:Enterprise boardrooms, training facilities, and huddle spaces requiring wireless presentation integration and unified communications compatibility. Underpenetrated smart classroom deployment in Maharashtra and Karnataka offers expansion space for vendors with localized service networks and regional language software support.
- Retail:Quick-service restaurants, flagship stores, and transit hubs deploying wayfinding and self-service terminals.
- Hospitality:Hotel lobbies, conference centers, and event venues prioritizing aesthetic integration and concierge functionality over technical performance specifications.
Education commands the largest installed base, with corporate applications expanding most quickly as hybrid work models drive huddle space retrofit demand.
Installation Type:
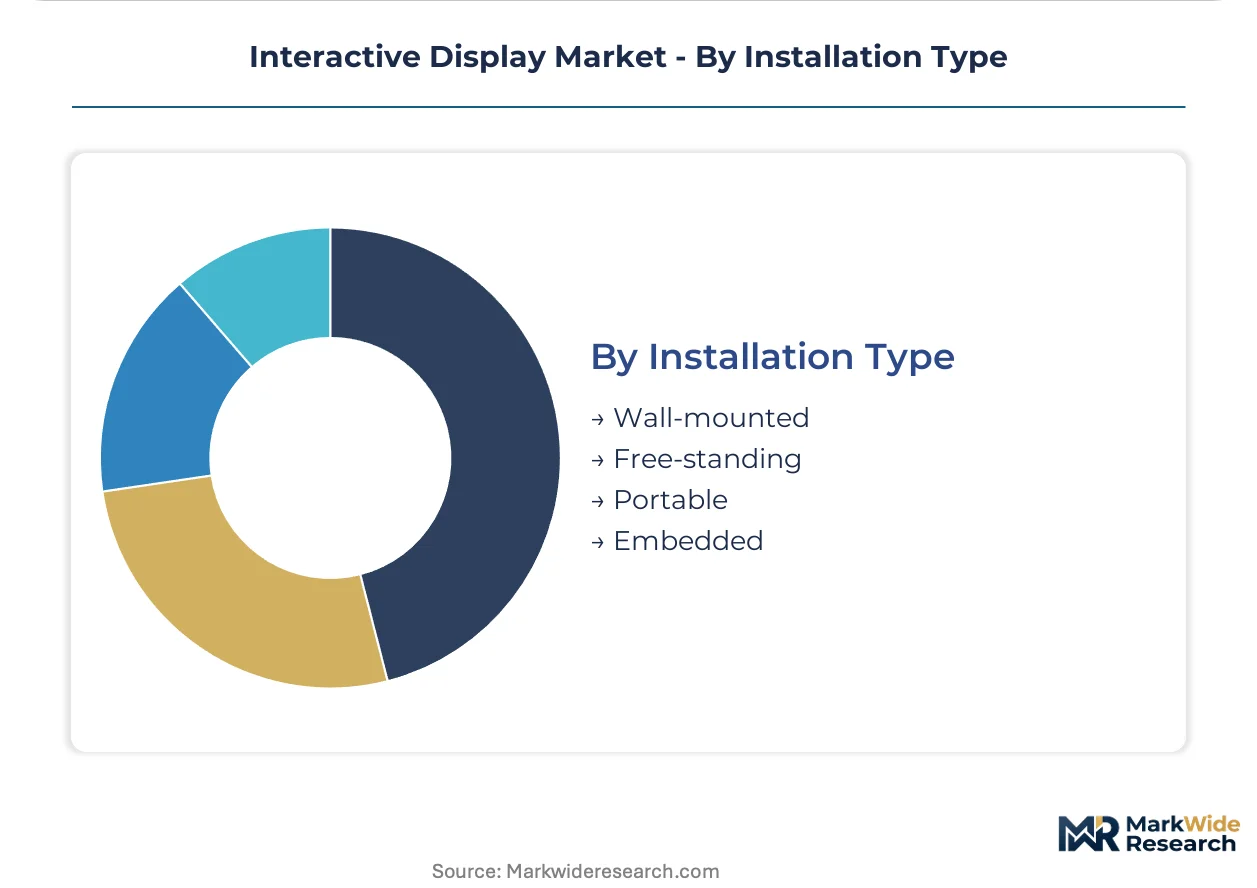
Physical mounting configuration constrains thermal management, cable routing, and service access, with implications for warranty terms and field service cost structures.
- Wall-mounted:Fixed bracket installations for permanent classroom and boardroom deployments, dominating education sector procurement where floor space constraints and vandalism resistance prioritize secure mounting.
- Free-standing:Mobile carts and floor-mounted pedestals enabling reconfiguration in multi-purpose corporate and hospitality spaces.
- Portable:Battery-powered or lightweight units for temporary event and trade show deployment, requiring ruggedized chassis and rapid deployment mechanisms.
- Embedded:Custom-integrated displays within furniture, kiosks, or architectural elements, demanding specialized thermal design and front-service access panels.
Wall-mounted configurations retain the largest installed base, with embedded installations gaining share fastest as retail and hospitality environments prioritize seamless aesthetic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hefei and Wuhan anchor interactive display manufacturing through massive Gen 10.5 fab complexes. Procurement patterns diverge across education digitization programs, corporate retrofit cycles, and retail infrastructure buildouts.
China
MIIT-connected classroom mandates accelerate LCD interactive whiteboard deployment across provincial education infrastructure. GB standards for display energy efficiency and network security shape procurement specifications for connected classroom devices. BOE Technology Group Co Ltd dominates volume manufacturing from Hefei and Wuhan fab clusters, sustaining price competitiveness through captive Gen 10.5 capacity.
United States
Enterprise IT departments favor subscription-based hardware refresh cycles over capital purchase models in California and Texas technology sector headquarters. FCC electromagnetic emission regulations govern wireless connectivity modules in interactive displays. Corporate boardrooms in Seattle and Austin drive demand for large-format screens with unified communications integration.
Germany
EU Ecodesign Directive compliance mandates accelerate procurement of energy-efficient interactive screens in corporate boardrooms and Dutch retail chains. REACH substance restrictions compel reformulation of solder alloys and panel substrate resins. Industrial procurement from Munich and Frankfurt prioritizes modular, repairable display architectures under emerging CSRD reporting frameworks.
India
Underpenetrated smart classroom deployment in Maharashtra and Karnataka offers expansion space for interactive whiteboard vendors with localized service networks. BIS certification requirements and state-level education technology programs shape vendor qualification. Domestic assembly operations in Gujarat and Tamil Nadu are scaling to meet procurement localization preferences.
Japan
Broadcast studio and command-center applications demand sub-5 millisecond touch latency specifications that strain capacitive architecture limits. METI industrial standards and JIS certification frameworks govern display performance claims. Tokyo and Osaka corporate installations anchor premium OLED interactive display demand for curved form factors.
Interactive Display Market Vendor Landscape
Global majors compete with regional champions across technology integration and supply chain control dimensions. The market structure consolidates around three tiers: captive semiconductor-display fabricators, specialized interactive panel assemblers, and regional education-focused distributors. Strategic archetypes include vertically integrated electronics conglomerates, pure-play display technology specialists, and contract manufacturing platforms. Competitive moves concentrate on backward integration into driver IC production and geographic expansion through localized final assembly.
Among Korean-based electronics conglomerates, Samsung Electronics Co Ltd and LG Electronics Inc exemplify the captive supply chain archetype, leveraging in-house semiconductor and display fabrication to control module production from driver ICs to finished panels. Chinese fabricators BOE Technology Group Co Ltd anchors the scale-driven tier through massive Gen 10.5 LCD capacity, occupying a position that sustains price competitiveness in education sector procurement. These three entities represent distinct competitive positioning vectors: technology integration depth, manufacturing scale, and premium form factor differentiation.
| Leading Market Players |
|---|
| Samsung Electronics Co Ltd |
| LG Electronics Inc |
| BOE Technology Group Co Ltd |
| Panasonic Corporation |
| Sharp Corporation |
| ViewSonic Corporation |
| Promethean Limited |
| BenQ Corporation |
| Leyard Optoelectronic Co Ltd |
| Others |
Supply Flow & Price Mechanics
Education procurement programs in China and India anchor volume demand, locking pricing into three-tier structures across premium OLED installations, standard LCD corporate deployments, and economy-grade classroom whiteboards. This buyer concentration transfers pricing power upstream to panel fabricators with captive Gen 10.5 capacity, compressing margins for assembly-only contract manufacturers.
Pricing Analysis
Silver nanowire and metal-mesh material costs pass through directly to touchscreen monitor bill-of-materials, with copper-silver hybrid meshes commanding premium positioning over legacy ITO deposition. Price differentiation hinges on touch latency certification tiers and after-sales service bundling, with sub-10 millisecond corporate specifications extracting 2-3x premiums over education-grade 20+ millisecond panels. Pricing pressure stems from BOE's Hefei and Wuhan fab scale flooding LCD interactive panel supply. Education buyers in provincial China and Maharashtra exhibit highest price sensitivity, while Tokyo and Los Angeles broadcast studios prioritize performance over unit cost.
Supply Chain Analysis
India's PLI scheme and domestic assembly mandates in Gujarat and Tamil Nadu are forcing component localization for education-sector interactive whiteboards. Manufacturing gravity centers on China, South Korea, and Taiwan, with driver IC fabrication drawing from Taiwanese foundries and display backplanes sourcing from Korean semiconductor lines. Indium, silver nanowire, and copper mesh feedstock dependencies create single-source vulnerability through Chinese smelter concentration for refined indium. Distribution runs through regional education-technology distributors in Asia and AV systems integrators in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interactive display procurement offers geographic arbitrage between India's underpenetrated state-level education programs and China's saturated provincial infrastructure, with BIS certification requirements creating margin buffers for localized assemblers against pure import competition.
For Market Incumbents: Hedge indium supply volatility through backward integration into silver nanowire touch layer partnerships or metal-mesh process licensing. Samsung Electronics and LG Electronics should reinforce captive driver IC production against Taiwanese foundry concentration risk. Defend position in German corporate boardrooms by accelerating EU Ecodesign Directive compliance certification ahead of REACH substance restriction enforcement timelines. For New Entrants and Emerging Players: Quick-service restaurant chains in India's tier-2 cities represent an underserved buyer archetype with minimal incumbent kiosk penetration. Maharashtra and Karnataka smart classroom deployment offers white space for vendors with Marathi and Kannada software localization. Target embedded installation partnerships with retail fixture manufacturers rather than direct panel sales to bypass BOE's LCD price dominance. For Investors and Strategic Acquirers: Semiconductor-display conglomerates are the most active acquirer in this space, seeking driver IC specialists and touch-layer process IP to close vertical gaps. Long-term viability hinges on metal-mesh technology migration and India manufacturing localization within a 5-10 year demand window. Acquisition targets should display modular repairable architectures aligned with EU CSRD reporting requirements. Watch for MIIT-connected classroom procurement volume inflection as the signal for China demand saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Production | Samsung's captive semiconductor fabs eliminate Taiwanese foundry dependency for touch controller supply. |
| Silver Nanowire Process Licensing | Metal-mesh technology transfer enables LG's curved OLED installations to bypass ITO indium cost volatility. |
| India Final Assembly Localization | Gujarat and Tamil Nadu facilities satisfy BIS certification and state education procurement preferences. |
| EU Green Chemistry Line Certification | REACH-compliant solder reformulation retains German corporate boardroom market access against Asian competitors. |
| Gesture Recognition Platform Integration | Motion-sensing software bundling differentiates kiosk offerings for Shanghai quick-service restaurant deployments. |
Methodological Framework
Multiple input streams — procurement manager interviews at German corporate headquarters, technical director discussions at Korean display fabricators, and education-technology coordinator surveys across Maharashtra and Karnataka — were reconciled against customs records, MIIT connected-classroom procurement disclosures, and EU Ecodesign Directive compliance filings. Primary fieldwork captured specification requirements from broadcast studio engineers in Tokyo and AV integrators in Texas. Secondary validation drew from SEC filings of listed display manufacturers, BOE Technology Group sustainability reports, and FCC equipment authorization databases. Bottom-up panel shipment tallies and top-down education infrastructure budget allocations were cross-triangulated.
Data-stream reconciliation fed segmentation models across product type, display technology, end-use vertical, and installation configuration dimensions over the projection horizon. CAGRs were derived from installed base replacement cycle analysis and procurement pipeline tracking. Forecast inputs incorporated MIIT digitization program rollout schedules, EU CSRD reporting adoption curves, and silver nanowire material cost trajectories. Volume projections for LCD interactive whiteboards, OLED corporate installations, and LED video wall arrays were sensitivity-tested against indium price volatility scenarios.
Underlying measurement precision varies by segment; education procurement volumes carry tighter precision than hospitality deployment estimates due to government budget transparency. Forecasts reflect documented assumptions around MIIT program continuity and REACH substance restriction enforcement timelines. Supply concentration in Hefei and Wuhan fab clusters, indium smelter geographic concentration, and touch latency protocol standardization gaps constitute specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Mask Market
Display Technologies
Global Projector Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Global Center Stack Display Market
Display Technologies
OLED Microdisplay Market
Display Technologies
LCD Panel Market
Display Technologies
Industrial Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Global Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Touch Screen Film Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Global Display Panel Market
Display Technologies
Flexible Display Market