
 Electronic Paper Display (EPD) Market | 2026-2036
Electronic Paper Display (EPD) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Paper Display (EPD) Market Foresight
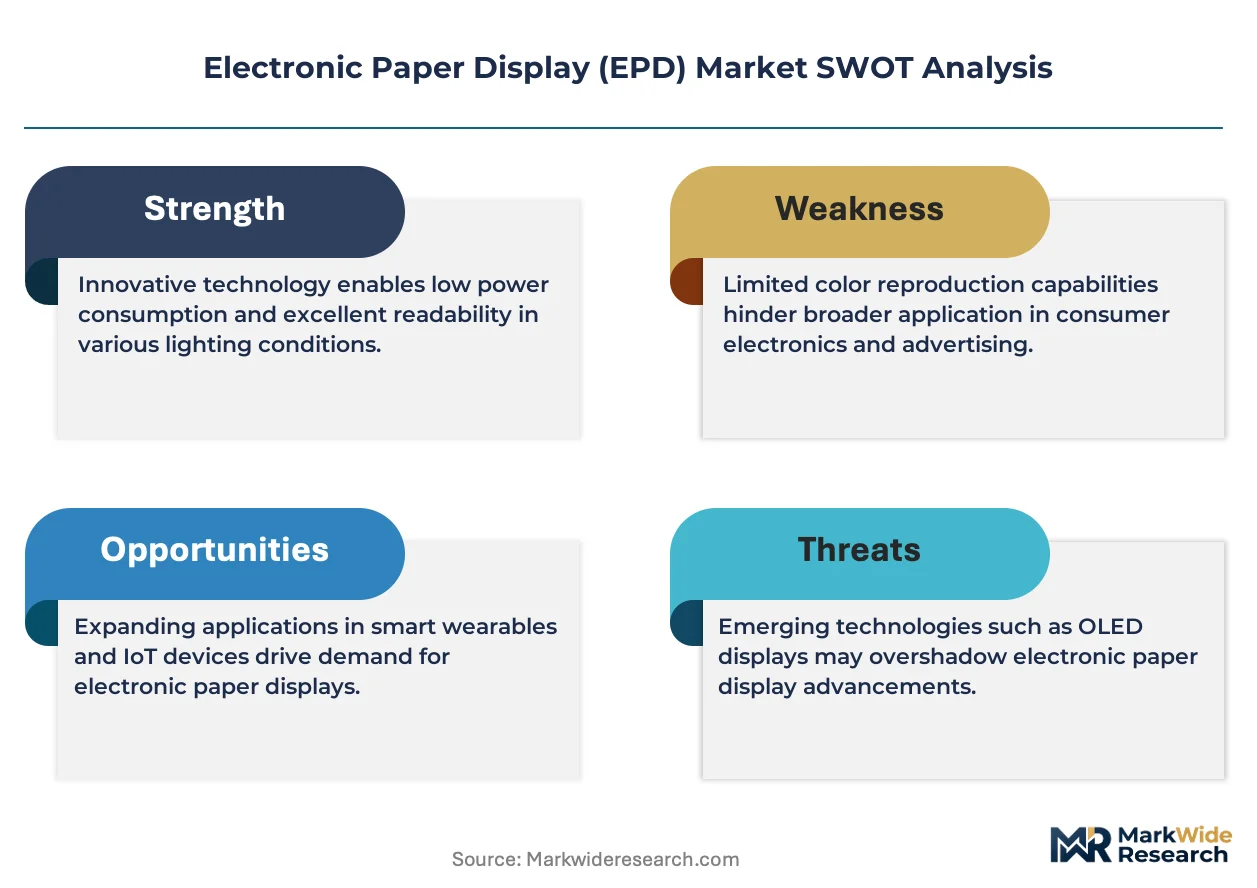
REACH is hardening material compliance costs for EPD manufacturers sourcing microcapsule suspensions and electrode substrates from European suppliers. E Ink Holdings leverages captive production of electrophoretic film to sustain margin control across the value chain. BOE Technology Group anchors high-volume active matrix backplane capacity in Beijing and Chengdu. Samsung Electronics competes through advanced polymer-dispersed liquid crystal R&D for reflective display variants.
Electronic paper display denotes a non-emissive screen technology that relies on ambient light reflection rather than backlighting, typically achieving contrast ratios above 10:1 at sub-1-watt operational draw. Electrophoretic configurations dominate commercial shipments due to mature manufacturing infrastructure and proven bistable image retention, while electrochromic variants are gaining traction in wearable devices requiring sub-millimeter bending radii. Flexible display formats command premium positioning in smart label and retail signage applications where conformal mounting surfaces are essential. Active matrix backplanes support the fastest refresh requirements in transportation displays and interactive wayfinding systems.
FCC certification governs radio-enabled smart labels and signage nodes in the United States, while the EU Ecodesign Directive and CE marking framework enforce energy consumption ceilings that bistable EPD technologies naturally satisfy. China's GB standards for electronic display products, administered by SAMR, establish electromagnetic compatibility and safety baselines for domestic and export-bound panels. Stakeholders must track evolving interoperability mandates for IoT-connected signage networks and assess how polymer substrate recyclability requirements under extended producer responsibility schemes will reshape material selection and end-of-life processing economics.
Market Dynamics
Bistable display architectures are compressing power budgets across retail and transportation signage, forcing incumbent LCD suppliers to reposition around reflective alternatives or exit low-margin fixture categories entirely.
Growth Catalysts
- EU Ecodesign Directive:Standby power thresholds below 0.5 watts favor electrophoretic panels in networked retail displays across Germany, France, and Italy.
- Microcapsule suspension advances:Improved particle mobility in electrophoretic films enables sub-500-millisecond refresh rates for transportation timetable applications.
- Beijing-Chengdu manufacturing corridor:Concentrated active matrix backplane capacity reduces panel cost curves for export-bound smart label production.
Market Restraints
- Electrode substrate concentration:Indium tin oxide supply tightness from Korean and Japanese sputtering targets elevates input cost volatility for flexible display formats.
- Electrochromic refresh latency:Switching speeds above two seconds limit adoption in interactive wayfinding systems requiring real-time updates.
- REACH compliance burden:ECHA registration requirements for microcapsule chemical constituents add 12-18 month qualification timelines for European-sourced suspensions.
Strategic Opportunities
- India BIS certification pathway:Mandatory IS 13252 standards for electronic display products create first-mover positioning for compliant bistable panel suppliers in railway signage.
- Polymer-dispersed liquid crystal convergence:Hybrid reflective-transmissive architectures open wearable device segments requiring ambient and backlight operation modes.
- Extended producer responsibility schemes:France's AGEC law mandates polymer substrate recyclability, rewarding suppliers with closed-loop film recovery capabilities.
Industry Challenges
- Active matrix TFT design talent:Scarcity of engineers experienced in low-temperature polysilicon backplane integration delays product ramps for curved retail fixtures.
- FCC Part 15 certification timelines:Radio-enabled smart labels face 4-6 month approval cycles for IoT signage networks, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Paper Display (EPD) Market |
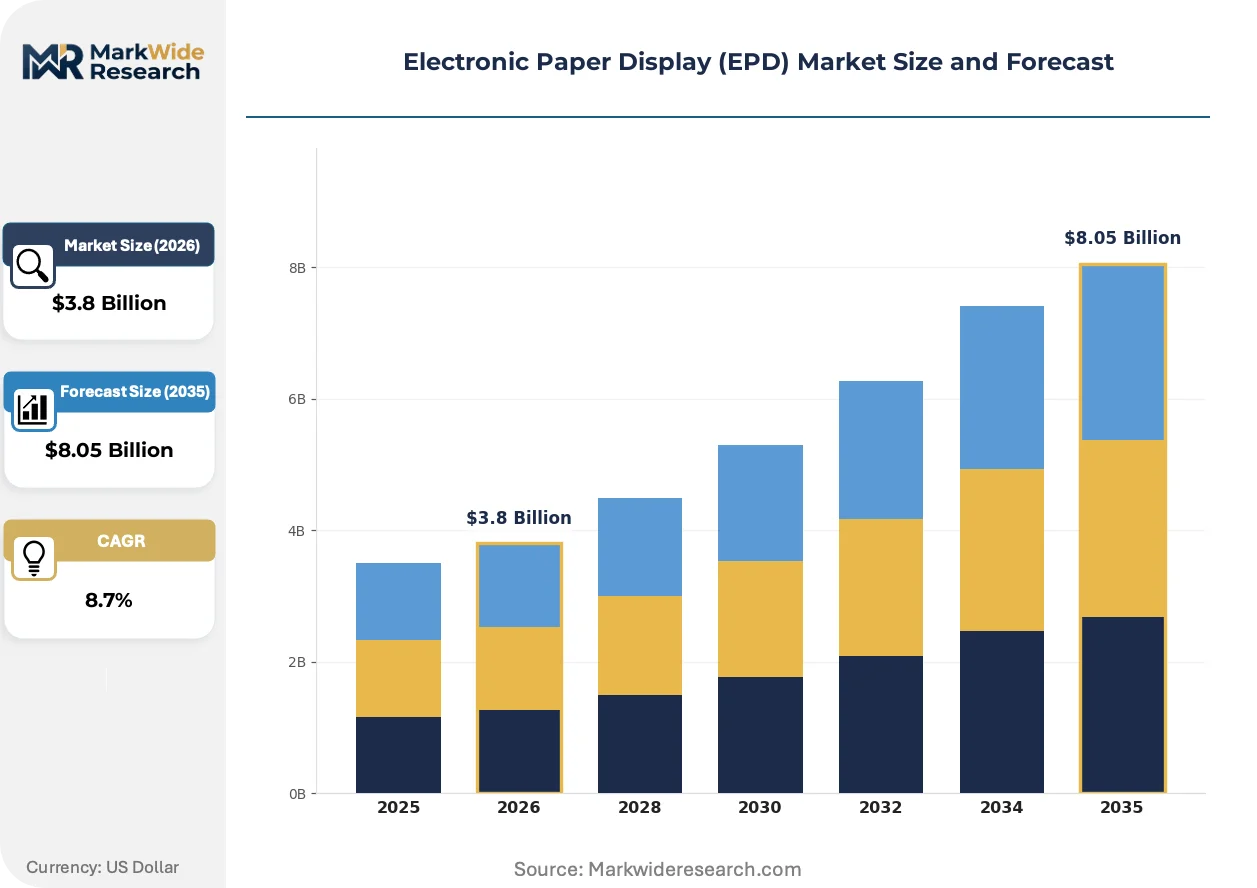
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Display, Bistable Display, Reflective Display, Active Matrix Display Technology: Electrophoretic, Electrochromic, Microencapsulated, Polymer Dispersed End User: Consumer Electronics, E-Readers, Digital Signage, Smart Labels Application: Retail Signage, Wearable Devices, Smart Home, Transportation Displays |
| Companies Covered | DKE (Dongfang Kemo), Guangzhou OED Technologies, E Ink Holdings Inc., SOLUM, Visionect, BOE Technology Group, Pervasive Displays Inc., Sony Corporation, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Paper Display (EPD) Market Shifts & Advancements
Reflective display architectures are fragmenting into substrate-specific variants optimized for conformal mounting, low-power IoT endpoints, and hybrid indoor-outdoor visibility requirements.
Electrophoretic film production is modularizing around roll-to-roll coating lines that separate microcapsule synthesis from electrode lamination. Display integrators in South Korea and Taiwan are adopting this disaggregated supply model to reduce capital intensity. The shift is modularizing entry barriers for mid-volume smart label specialists previously excluded by integrated film manufacturing economics.
REACH authorization requirements for microplastic-containing formulations are tightening material substitution timelines across European supply chains. ECHA's 2024 restriction roadmap targets encapsulated pigment particles below five micrometers. Smart label manufacturers serving German retail chains are accelerating electrochromic and electrowetting alternatives to preempt compliance disruption.
Buyer concentration among omnichannel retailers is compressing display procurement cycles from annual to quarterly rhythms. Fixture suppliers serving Walmart and Carrefour networks are shifting from purchase orders to consignment inventory models with usage-based settlement. This pattern is most visible in North American and Western European grocery chains deploying dynamic price labels at shelf edge.
Electronic Paper Display (EPD) Market Segmentation
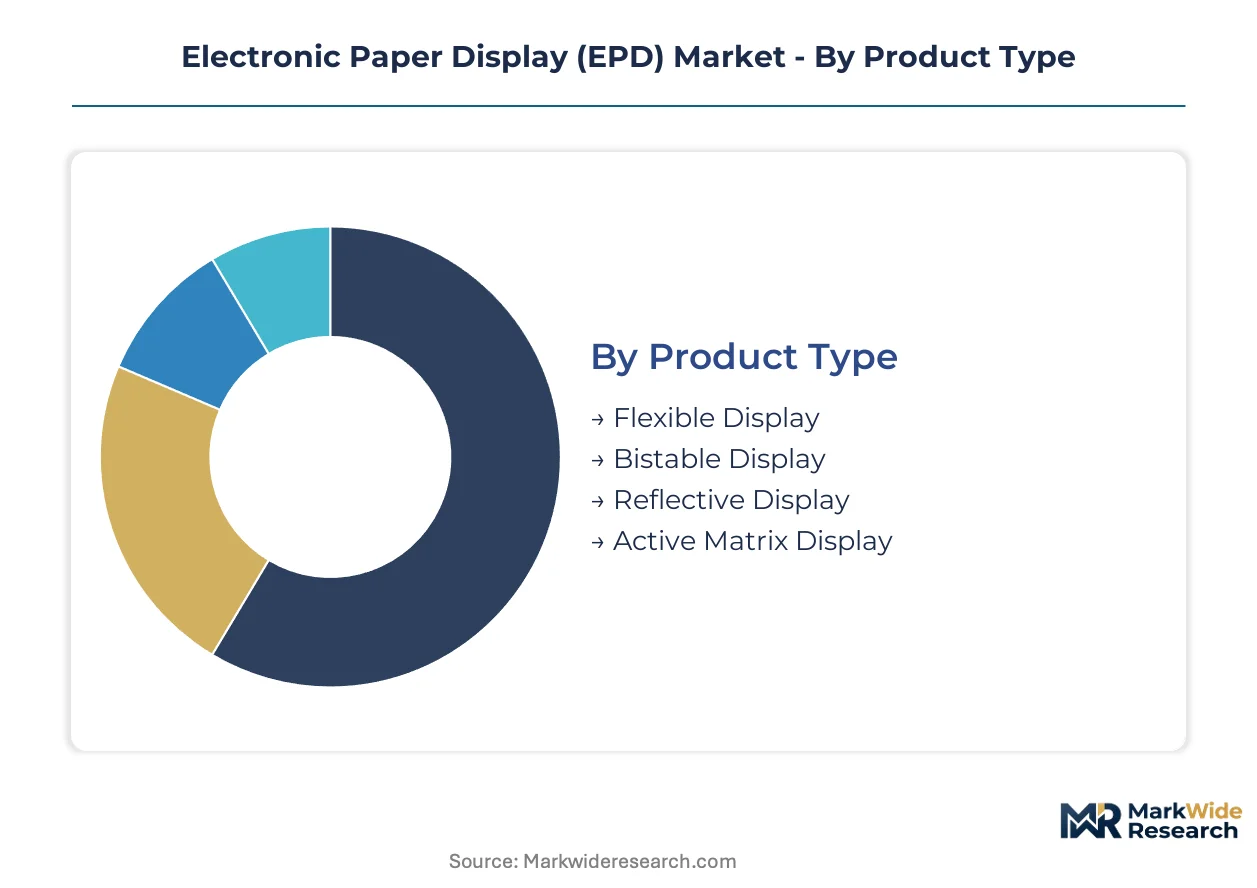
EPD segmentation reveals how display architectures align with power constraints, form factors, and refresh requirements across retail, transportation, and consumer endpoints. Technology choices here determine manufacturing partnerships, certification pathways, and margin structures for panel suppliers.
Product Type:
Standalone panels dominate high-visibility installations, while embedded formats integrate into compact IoT endpoints and conformal product surfaces.
- Flexible Display:Polyimide or metal foil substrates enable sub-millimeter bending radii for curved retail fixtures and wearable form factors. Smart label manufacturers in Germany and France prioritize these for shelf-edge conformal mounting where flat glass fails.
- Bistable Display:Image retention without power draw satisfies EU Ecodesign standby thresholds below 0.5 watts, making these the default for networked retail signage nodes across Italy and Spain. Electrophoretic and electrochromic variants both exploit this zero-static-power characteristic.
- Reflective Display:Ambient light dependence eliminates backlight layers, reducing panel thickness and weight for outdoor transportation timetables.
- Active Matrix Display:Thin-film transistor backplanes drive fastest refresh requirements in interactive wayfinding systems and animated signage.
Volume placements concentrate in Bistable Display configurations; the faster expansion belongs to Flexible Display formats.
Technology:
Cost tiers separate mature electrophoretic infrastructure from emerging alternatives competing on refresh speed and color capability.
- Electrophoretic:Microcapsule-based particle migration achieves bistable image retention with sub-1-watt operational draw. Beijing and Chengdu manufacturing corridors anchor global film supply for e-reader and smart label production.
- Electrochromic:Solid-state redox reactions enable sub-millimeter stacking for wearable devices requiring extreme thinness. Switching latencies above two seconds constrain adoption in real-time signage applications.
- Microencapsulated:Pigment particle containment improves environmental durability for outdoor retail installations facing temperature cycling.
- Polymer Dispersed:Liquid crystal droplets embedded in polymer matrices create hybrid reflective-transmissive modes for ambient and backlight operation.
Electrophoretic technologies retain the highest shipment volumes; Polymer Dispersed variants are climbing the fastest on wearable device demand.
End User:
Customer types range from high-volume consumer electronics OEMs to fragmented industrial signage integrators with distinct procurement rhythms.
- Consumer Electronics:E-reader and wearable device OEMs specify panel performance around sunlight readability and multi-week battery life. Amazon and Rakuten Kobo procurement cycles drive seasonal demand spikes in electrophoretic film production.
- E-Readers:Dedicated reading devices prioritize 300-plus pixel density and front-light uniformity over color or video capability. This segment sustains the highest manufacturing yields for mature electrophoretic processes.
- Digital Signage:Retail and transportation networks require FCC Part 15 certification for radio-enabled nodes, extending product launch timelines. Walmart and Carrefour procurement is shifting from annual purchase orders to quarterly consignment models.
- Smart Labels:Shelf-edge pricing displays demand sub-dollar panel costs at million-unit scales, favoring roll-to-roll manufacturing in South Korea and Taiwan.
E-Readers dominate current volume placements; Digital Signage represents the steepest expansion trajectory on retail network refresh cycles.
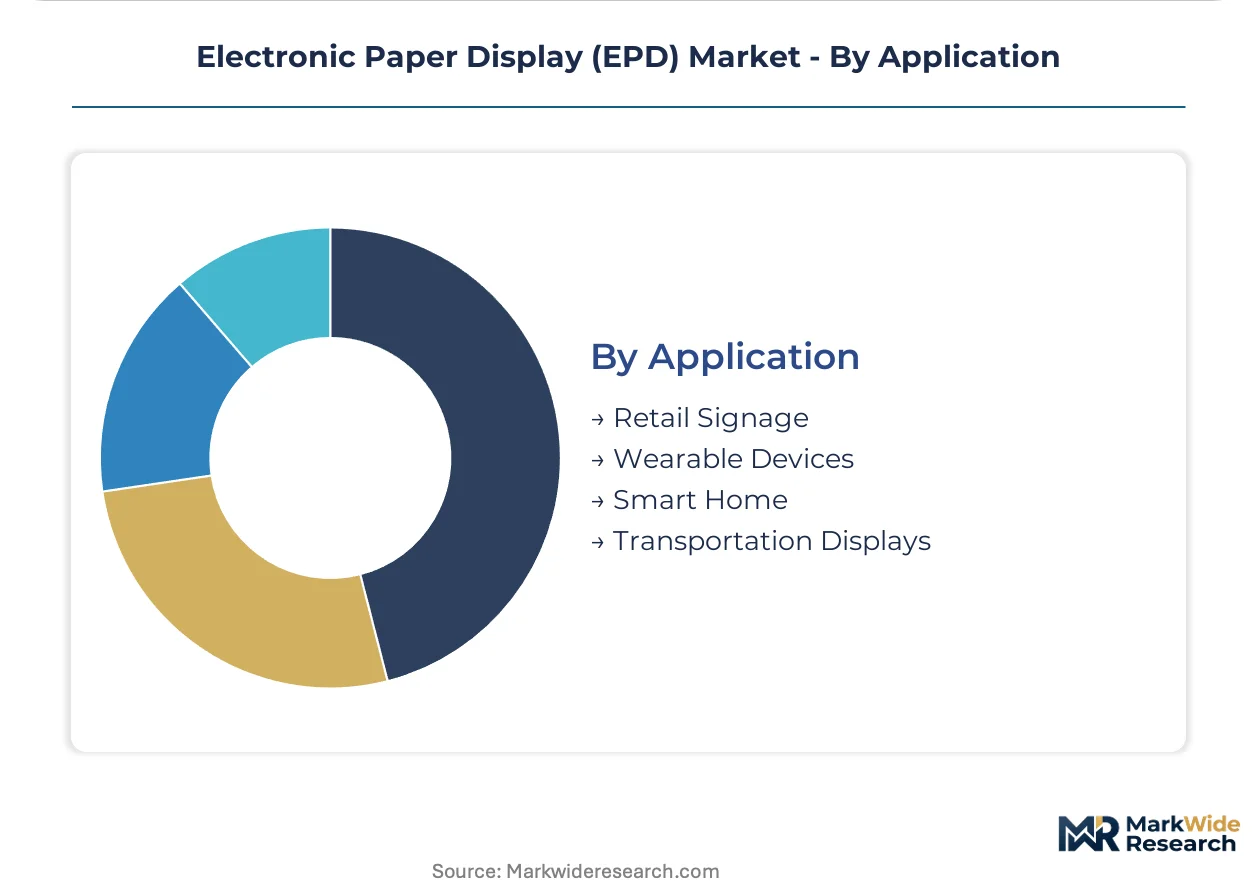
Application:
Geographic deployment patterns concentrate manufacturing investment near end-use clusters to minimize logistics costs for fragile panel shipments.
- Retail Signage:Dynamic price labels and promotional displays exploit bistable power budgets for battery-operated shelf-edge mounting. French AGEC law recyclability mandates are reshaping polymer substrate selection for Carrefour and Auchan networks.
- Wearable Devices:Smartwatches and fitness bands require sub-2-millimeter thickness and sub-10-gram panel weight. BOE Technology Group and E Ink Holdings compete on flexible film integration for Xiaomi and Garmin supply chains.
- Smart Home:Thermostats, calendar displays, and control panels prioritize always-on information visibility without backlight heat generation.
- Transportation Displays:Bus, rail, and airport timetable applications demand wide temperature operation and direct sunlight legibility. India's BIS IS 13252 certification creates first-mover positioning for compliant suppliers in railway signage tenders.
Retail Signage commands the highest current volumes; Wearable Devices are gaining share fastest on consumer electronics refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhongguancun Science Park tax incentives and Beijing-Chengdu special economic corridors concentrate EPD manufacturing investment near active matrix backplane foundries. Panel suppliers co-locate with TFT-LCD ecosystem spillovers to minimize logistics costs for fragile display shipments. This geographic pattern shapes regional competitive positioning across three continents.
China
Domestic e-reader OEM procurement and smart label export demand drive volume requirements for electrophoretic film production. SAMR-administered GB standards for electronic display products establish electromagnetic compatibility baselines for domestic and export-bound panels. Beijing and Chengdu manufacturing corridors anchor global active matrix backplane capacity serving Walmart and Carrefour supply chains.
United States
Retail network refresh cycles at Walmart and omnichannel grocers accelerate dynamic price label deployment across shelf-edge installations. FCC Part 15 certification governs radio-enabled smart label nodes, extending product launch timelines for IoT signage networks. Pacific Northwest technology clusters concentrate software integration capabilities for networked display management platforms.
Germany
Carrefour and Auchan procurement networks demand bistable panels meeting EU Ecodesign standby thresholds below 0.5 watts for battery-operated retail fixtures. ECHA REACH authorization requirements for microcapsule chemical constituents add qualification timelines for European-sourced suspensions. Bavaria-based industrial automation specialists integrate EPD modules into factory-floor information systems.
South Korea
Samsung Electronics and domestic display fabricators advance polymer-dispersed liquid crystal R&D for reflective-transmissive hybrid architectures. MFDS-equivalent display safety standards align with export market requirements for wearable device integration. Seoul Capital Area roll-to-roll coating lines adopt disaggregated supply models separating microcapsule synthesis from electrode lamination.
India
Railway signage tenders and smart city initiatives create first-mover positioning for BIS IS 13252 compliant bistable panel suppliers. BIS mandatory standards for electronic display products establish electromagnetic compatibility and safety baselines for domestic installations. Maharashtra industrial corridors concentrate assembly capacity for transportation timetable applications requiring wide temperature operation.
Electronic Paper Display (EPD) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the EPD market. The vendor base stratifies between integrated film manufacturers controlling microcapsule synthesis and modular assembly specialists sourcing electrophoretic materials externally. Three archetypes dominate: captive film producers with backward integration into particle chemistry, fabless display integrators leveraging roll-to-roll partnerships, and diversified electronics conglomerates cross-leveraging LCD infrastructure. Capacity expansion in Beijing-Chengdu corridors and strategic licensing of electrophoretic patents represent the dominant competitive moves reshaping supply relationships.
Among Greater China-based fabricators, BOE Technology Group and E Ink Holdings occupy positions spanning captive film production and active matrix backplane integration. E Ink Holdings exemplifies the pure-play specialist archetype through concentrated electrophoretic technology depth. Samsung Electronics represents the diversified conglomerate vector, anchoring polymer-dispersed liquid crystal development within broader display R&D portfolios. These three entities collectively illustrate how geographic clustering near TFT-LCD ecosystems and differential integration strategies partition competitive terrain.
| Leading Market Players |
|---|
| DKE (Dongfang Kemo) |
| Guangzhou OED Technologies |
| E Ink Holdings Inc. |
| SOLUM |
| Visionect |
| BOE Technology Group |
| Pervasive Displays Inc. |
| Sony Corporation |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Captive film producers with sovereign-backed manufacturing footprints in Beijing and Chengdu corridors wield asymmetric pricing power over modular assembly specialists. Their backward integration into microcapsule chemistry compresses input cost volatility while forcing fabless integrators to absorb margin compression from indium tin oxide supply tightness.
Pricing Analysis
Premium positioning for sub-500-millisecond refresh electrophoretic panels with 90-day lead times commands 15-25% markups over spot inventory with 180-day availability windows. Three-tier pricing structure across premium, standard, and economy levels separates FCC Part 15 certified nodes from uncertified equivalents and surplus film lots. Cost compression in economy-tier smart label panels is intensifying because South Korean roll-to-roll specialists are disaggregating microcapsule synthesis from electrode lamination. Digital signage integrators serving Walmart and Carrefour networks exhibit highest price sensitivity, while transportation timetable OEMs prioritize refresh performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Rakuten Kobo procurement teams, while distributor-mediated flows serve fragmented smart label specialists in Germany and France. Manufacturing gravity centers on China, South Korea, and Taiwan for electrophoretic film and active matrix backplane production. The supply chain draws from microcapsule suspensions, indium tin oxide sputtering targets, and polyimide substrate films as critical inputs. Single-source vulnerability around Korean and Japanese electrode substrate suppliers elevates disruption risk for flexible display formats. Distribution runs through consignment inventory models with usage-based settlement for omnichannel retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active matrix TFT backplane capacity scarcity in low-temperature polysilicon integration is propping panel pricing above commodity LCD alternatives. This supply-constrained structure rewards early positioning in captive film production and qualified supplier relationships.
For Market Incumbents: Cement control over microcapsule synthesis through captive chemistry operations or exclusive tolling arrangements with Beijing-Chengdu corridor producers. Add low-temperature polysilicon backplane capacity in Sichuan province to capture transportation display demand requiring sub-500-millisecond refresh. Electrophoretic patent licensing revenue streams face displacement from electrochromic alternatives targeting REACH-compliant wearable devices. For New Entrants and Emerging Players: The 40-60% price-point gap between premium FCC-certified digital signage nodes and economy-tier uncertified smart labels creates entry space for hybrid electrochromic-electrophoretic specialists. Target India's BIS IS 13252 certification pathway for railway signage tenders before incumbent qualification cycles complete. Pursue white-label assembly partnerships with South Korean roll-to-roll coating lines to bypass integrated film manufacturing capital barriers. For Investors and Strategic Acquirers: ECHA's 2024 restriction roadmap targeting encapsulated pigment particles below five micrometers is the leading indicator that electrochromic technology inflection is approaching. Frame five-to-ten year viability around patent estate quality in solid-state redox reactions and closed-loop polymer substrate recovery capabilities. Acquire roll-to-roll coating specialists with disaggregated supply model adoption and existing Walmart or Carrefour supplier relationships. Watch for BIS certification completion announcements from Maharashtra-based assembly operations as demand confirmation signals.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Microcapsule Chemistry Investment | E Ink Holdings' backward integration into particle synthesis sustains margin control against modular competitors. |
| Low-Temperature Polysilicon Backplane Expansion | BOE Technology Group's Chengdu capacity additions address TFT design talent scarcity constraining curved retail fixture ramps. |
| FCC Part 15 Certification Pre-Positioning | Early radio-enabled node approval compresses product launch windows for Walmart and Carrefour network deployments. |
| Electrochromic R&D Pivot | Samsung Electronics' polymer-dispersed liquid crystal development captures wearable device demand requiring sub-millimeter bending radii. |
| Closed-Loop Film Recovery Partnership | France's AGEC law recyclability mandates reward suppliers with polymer substrate recovery capabilities in Carrefour supply chains. |
Research Methodology
Independent corroboration across electrophoretic film production executives, active matrix backplane integration specialists, and retail signage procurement managers at omnichannel grocery networks underwrites the qualitative findings. Primary interviews with TFT-LCD ecosystem spillover engineers, SAMR regulatory affairs consultants, and ECHA REACH authorization specialists combined with secondary validation from SEC 10-K filings, customs trade data, and BIS certification registries. Bottom-up panel shipment tallies triangulate against top-down retail network deployment estimates.
Rate-of-change decomposition across technology substitution curves, regulatory compliance timelines, and manufacturing capacity absorption frames the analytical approach throughout the projection horizon. Segmentation dimensions modeled include display architecture, refresh performance tier, substrate flexibility grade, and end-use certification requirements. CAGRs derive from fitted S-curve adoption patterns for bistable signage networks and wearable device refresh cycles. Indium tin oxide price volatility bands and REACH authorization delay distributions inform scenario-weighted outputs.
Inputs from BIS certification databases and ECHA restriction roadmap disclosures were available through the study window; gaps in real-time Walmart and Carrefour procurement contract terms introduce uncertainty bands around consignment inventory model adoption rates. Forecasts reflect base assumptions around EU Ecodesign Directive enforcement continuity and SAMR GB standards alignment with export market requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Interactive Video Wall Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Holographic Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Gaming Monitors Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Field Emission Display Market
Display Technologies
Global Medical Display Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Thin Display Technology Market
Display Technologies
Computer Monitor Market
Display Technologies
Visual Computing Market